
 Asia-Pacific Renewable Energy Market | 2026-2036
Asia-Pacific Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Renewable Energy Market Analysis
Utility-grade project specifications are rotating toward higher capacity factors and longer asset lifespans across the Asia-Pacific renewable energy market. China Three Gorges Corporation leverages its integrated hydropower-to-grid infrastructure to dominate transmission-linked developments. Adani Green Energy Limited anchors its position through backward integration into solar cell manufacturing. Xinjiang Goldwind Science & Technology Co., Ltd. specializes in larger rotor diameters for low-wind regimes across Southeast Asian sites.
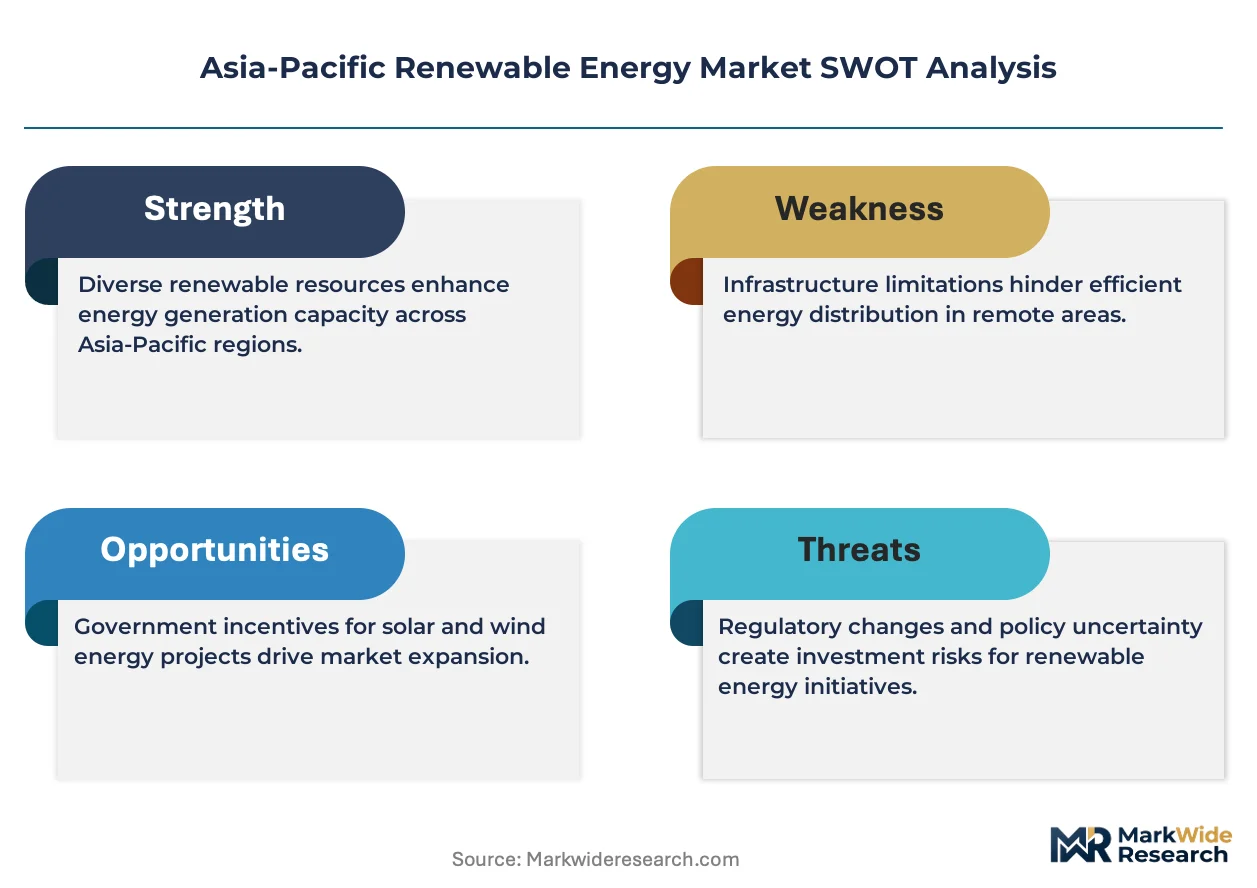
Asia-Pacific renewable energy encompasses solar photovoltaic, onshore and offshore wind, biomass thermal conversion, and run-of-river hydroelectric systems engineered for grid synchronization, frequency regulation, and baseload displacement. Photovoltaic modules in this region typically target degradation rates below 0.5% annually and temperature coefficients optimized for tropical humidity cycles, serving utilities and industrial off-takers seeking to replace coal-fired generation. Solar technology leads installed capacity across the region, though offshore wind segments command premium margin pools due to specialized foundation engineering and limited installation vessel availability. Utility end users represent the dominant demand channel, while residential adoption accelerates fastest in markets with net metering enforcement and distributed generation incentives.
China's MIIT enforces GB standards for inverter grid-code compliance, while India's CEA mandates renewable purchase obligations that utilities must satisfy through certified green power procurement. Japan's METI revises feed-in-tariff schedules to shift subsidy exposure toward merchant-price exposure for newer projects. Stakeholders must monitor regulatory transitions from guaranteed tariffs to competitive auction mechanisms as these frameworks determine project finance structures and equity return thresholds.
Market Dynamics
Grid-scale solar deployment across Southeast Asian utilities is compressing project development timelines while tightening domestic content requirements reshape supplier qualification criteria.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for solar module manufacturing attract capital toward integrated cell-to-module facilities in Gujarat and Rajasthan.
- China's dual carbon goals:National targets for carbon peak and neutrality accelerate utility procurement of renewable capacity through state-owned generation groups.
- Utility-scale offtake concentration:State electricity boards in Vietnam, Thailand, and the Philippines tender multi-gigawatt pipelines under competitive auction frameworks.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based producers control critical raw material flows, exposing module manufacturers to input cost volatility and logistics bottlenecks.
- Land acquisition friction:India's western states face competing claims from agriculture and industry, delaying project commissioning timelines.
- Grid integration capacity:Weak transmission infrastructure in Indonesian archipelago markets limits renewable penetration despite abundant solar and geothermal resources.
Strategic Opportunities
- Offshore wind in Vietnam:Shallow continental shelf geology and accelerating permitting frameworks position the country for foundation engineering specialization.
- Green hydrogen offtake:Japan's METI subsidy programs for ammonia co-firing create demand anchors for Australian and Malaysian renewable-to-hydrogen projects.
- Distributed solar in Australia:Net metering enforcement and battery storage incentives accelerate residential adoption beyond utility-scale dominance.
Industry Challenges
- Installation vessel scarcity:Limited jack-up and heavy-lift vessel availability constrains offshore wind construction windows across Asia-Pacific waters.
- Inverter grid-code compliance:China's MIIT GB standards and India's CEA technical regulations require firmware recertification cycles that delay equipment deployment.
- Skilled technician pipelines:Turbine maintenance and high-voltage substation commissioning face talent shortages in emerging Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Renewable Energy Market |
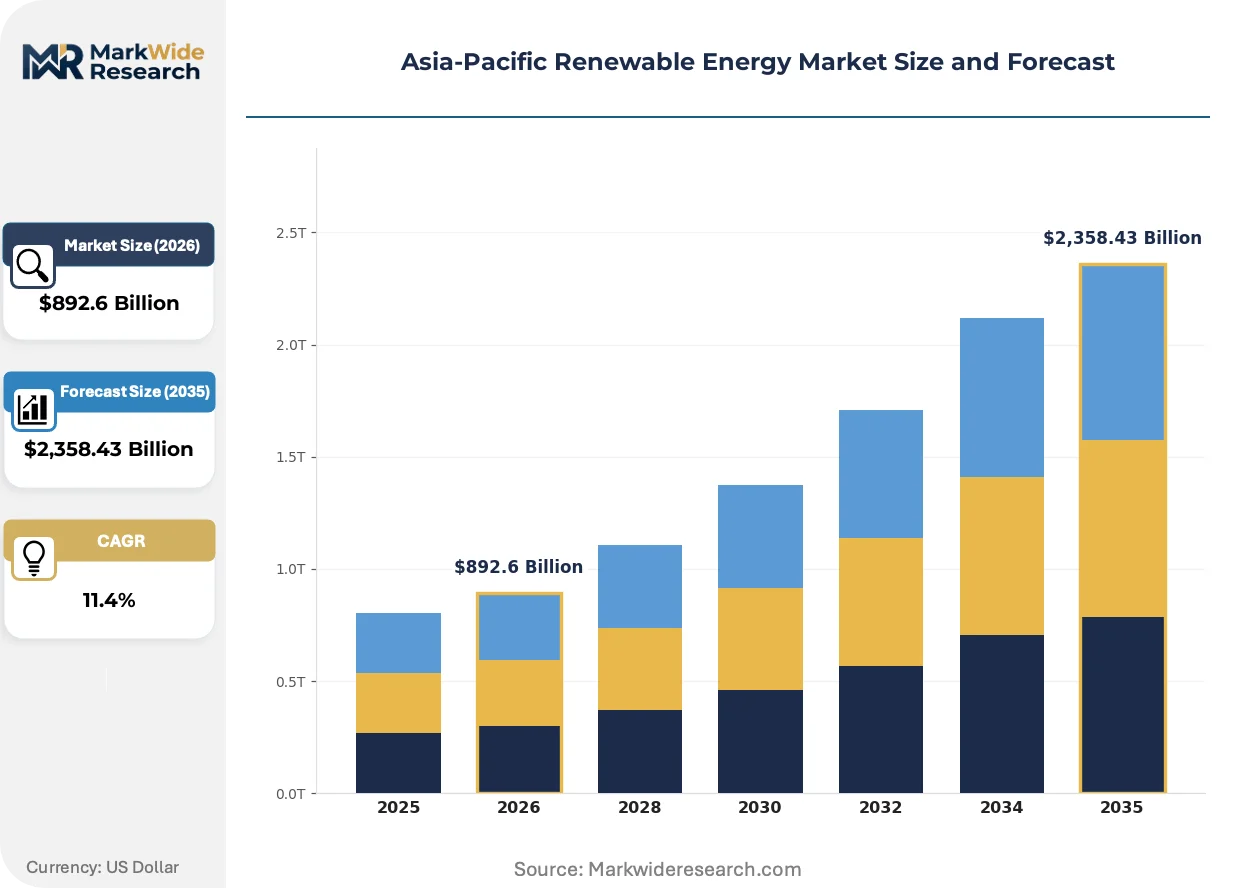
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $2,358.43 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro Application: Power Generation, Heating, Transportation, Industrial End User: Utilities, Commercial, Residential, Governments Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | China Three Gorges Corporation, State Power Investment Corporation, Adani Green Energy Limited, ReNew Power Ventures, Vena Energy, Xinjiang Goldwind Science & Technology Co., Ltd., Trina Solar Ltd., Tata Power Company Limited, Sungrow Power Supply, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Renewable Energy Market Emerging Trajectories
Technology convergence between digital controls and hardware engineering is compressing asset performance gaps while policy instruments pivot from guaranteed tariffs toward merchant price exposure.
Bifacial photovoltaic modules with tracking systems is supplanting fixed-tilt monofacial installations across utility portfolios. Indian and Australian developers adopt dual-sided generation configurations to capture reflected irradiance from arid ground surfaces. This technology is supplanting conventional engineering-procurement-construction contracts with performance-guaranteed full-wrap agreements that transfer operational risk to EPC consortia.
India's CEA mandates renewable purchase obligations that utilities satisfy through certified green power procurement certificates. The framework shifts compliance verification from annual audits to quarterly digital tracking through centralized registry platforms. Grid-connected solar and wind projects in Maharashtra, Karnataka, and Tamil Nadu adjust offtake strategies toward hybrid storage configurations to meet dispatchable obligation requirements.
Corporate power purchase agreements now dominate procurement channels for data center and semiconductor manufacturing loads. Technology firms in Singapore and South Korea bypass traditional utility intermediaries to contract directly with renewable developers for 15-20 year tenors. This pattern concentrates most visibly in Taiwan's science park clusters where semiconductor fabs seek 24/7 clean energy matching through bundled solar-plus-storage contracts.
Asia-Pacific Renewable Energy Market Segmentation
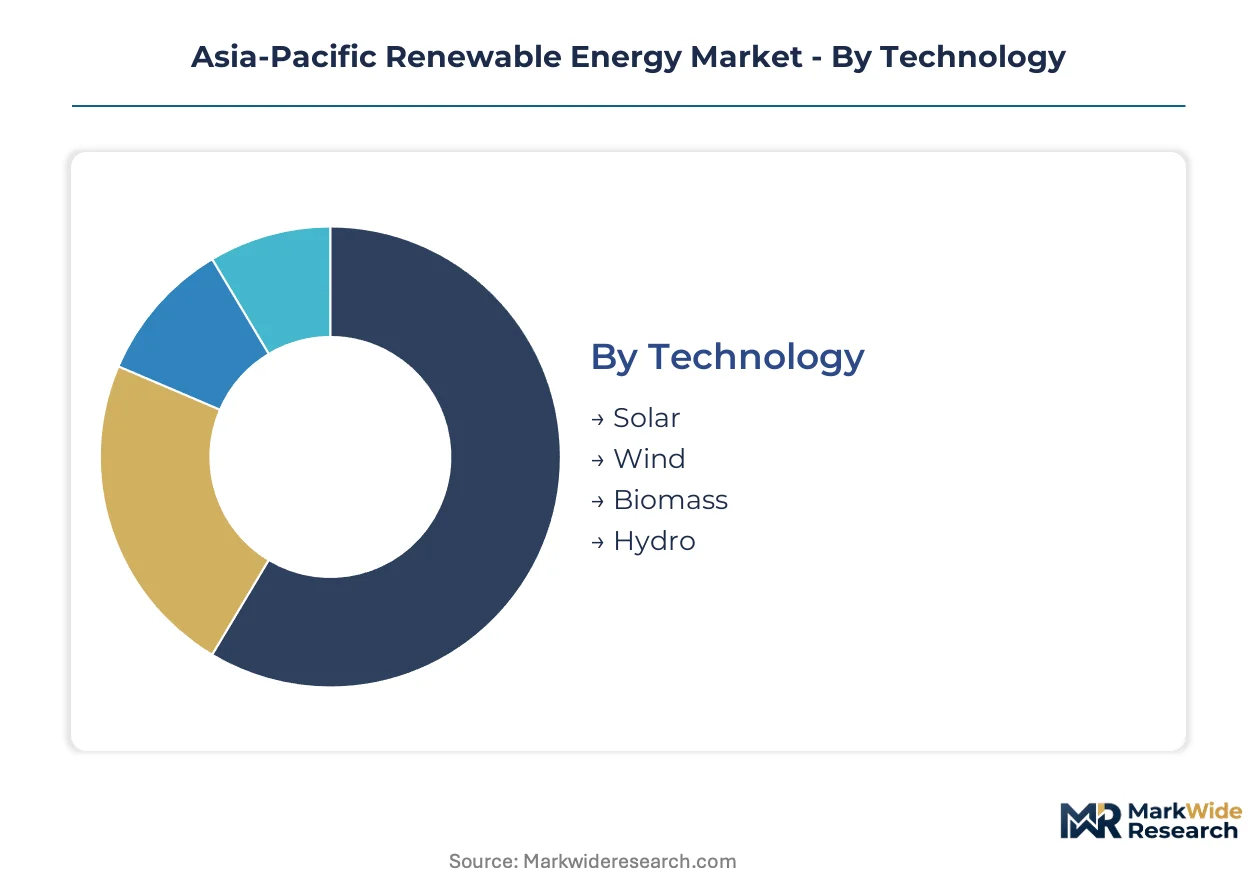
Segmentation in the Asia-Pacific renewable energy market reveals how regulatory frameworks, technology maturation, and capital intensity create divergent investment profiles across deployment channels. Understanding these divisions enables stakeholders to align project development timelines with specific compliance requirements and offtake structures.
Technology:
China's MIIT enforces distinct GB standards for inverter grid-code compliance across each technology class, while India's CEA mandates separate renewable purchase obligation coefficients for solar versus wind procurement.
- Solar:Photovoltaic modules target degradation rates below 0.5% annually with temperature coefficients optimized for tropical humidity cycles. Demand concentrates in Gujarat and Rajasthan where land availability and irradiance levels attract multi-gigawatt project pipelines under India's PLI scheme for domestic module manufacturing.
- Wind:Larger rotor diameters engineered for low-wind regimes dominate Southeast Asian site development. Procurement clusters in Vietnam's shallow continental shelf markets where specialized foundation engineering commands premium margin pools due to limited installation vessel availability.
- Biomass:Thermal conversion systems serve industrial off-takers seeking baseload displacement of coal-fired generation through agricultural residue feedstock supply chains.
- Hydro:Run-of-river configurations engineered for grid synchronization and frequency regulation leverage existing transmission infrastructure in China's southwestern provinces.
Solar handles the majority of throughput; offshore wind is the fastest mover on share.
Application:
Cost tier differentiation separates merchant-exposed projects from contracted revenue streams across deployment modes.
- Power Generation:Utility-grade specifications rotate toward higher capacity factors and longer asset lifespans under competitive auction frameworks in Vietnam, Thailand, and the Philippines.
- Heating:Biomass thermal systems serve district heating networks in northern Chinese municipalities under municipal clean heat mandates.
- Transportation:Green hydrogen offtake from Australian and Malaysian renewable-to-hydrogen projects supplies Japan's METI-subsidized ammonia co-firing programs.
- Industrial:Corporate power purchase agreements dominate procurement for semiconductor manufacturing loads in Taiwan's science park clusters seeking 24/7 clean energy matching through bundled solar-plus-storage contracts.
Power generation captures the dominant capital deployment; industrial offtake is expanding most quickly as manufacturing decarbonization accelerates.
End User:
Customer type determines financing structure complexity and contract tenor length across deployment scales.
- Utilities:State electricity boards tender multi-gigawatt pipelines under renewable purchase obligations that utilities satisfy through certified green power procurement certificates tracked through India's quarterly digital registry platforms.
- Commercial:Data center and semiconductor manufacturing loads in Singapore and South Korea bypass traditional utility intermediaries for 15-20 year direct contracts with renewable developers.
- Residential:Distributed solar accelerates fastest in Australian markets with net metering enforcement and battery storage incentives.
- Governments:Public procurement anchors demand in Indonesian archipelago markets where weak transmission infrastructure otherwise limits renewable penetration.
Utilities handle the majority of throughput; commercial offtake is gaining share fastest as corporate sustainability commitments harden.
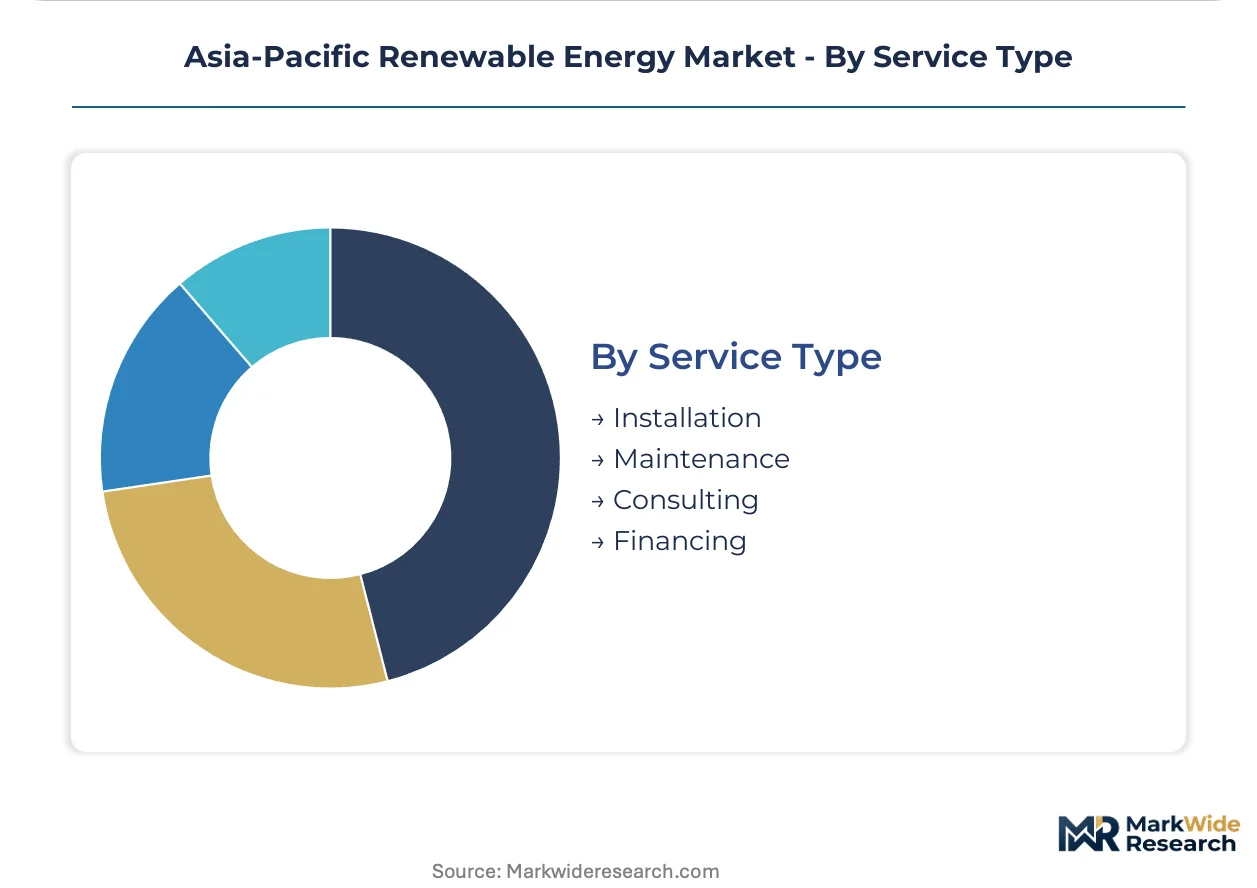
Service Type:
Supply concentration in specialized vessel availability and firmware recertification cycles shapes margin distribution across the service stack.
- Installation:Heavy-lift and jack-up vessel scarcity constrains offshore wind construction windows across Asia-Pacific waters, compressing project development timelines for foundation engineering specialists.
- Maintenance:Turbine maintenance and high-voltage substation commissioning face talent shortages in emerging Southeast Asian markets.
- Consulting:Grid integration capacity assessments dominate in Indonesian markets where abundant solar and geothermal resources exceed transmission infrastructure.
- Financing:Project finance structures pivot from guaranteed tariffs toward merchant price exposure as Japan's METI revises feed-in-tariff schedules.
Installation commands the largest service revenue pool; financing advisory is climbing the fastest as regulatory transitions reshape equity return thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian renewable developers export green hydrogen derivatives to Japan's ammonia co-firing facilities, establishing a cross-border trade corridor that anchors regional capital flows. This trade pattern concentrates procurement decisions in Tokyo while project development capital deploys across Southeast Asian manufacturing hubs.
China
State-owned generation groups procure multi-gigawatt renewable capacity under dual carbon targets for carbon peak and neutrality. MIIT enforces GB standards for inverter grid-code compliance that firmware developers must satisfy before equipment deployment. Yangtze River Delta manufacturers supply integrated cell-to-module facilities serving domestic utility tenders.
India
Western states of Gujarat and Rajasthan attract multi-gigawatt project pipelines where land availability and irradiance levels converge. CEA mandates renewable purchase obligations that utilities satisfy through certified green power procurement certificates tracked via quarterly digital registry platforms. Maharashtra, Karnataka, and Tamil Nadu developers adjust offtake strategies toward hybrid storage configurations.
Vietnam
Shallow continental shelf geology positions the country for foundation engineering specialization in offshore wind. State electricity boards tender multi-gigawatt pipelines under competitive auction frameworks that compress project development timelines. Specialized installation vessel scarcity constrains construction windows despite accelerating permitting frameworks.
Japan
METI revises feed-in-tariff schedules to shift subsidy exposure toward merchant-price exposure for newer projects, reshaping project finance structures. Ammonia co-firing subsidy programs create demand anchors for Australian and Malaysian renewable-to-hydrogen imports. Corporate power purchase agreements dominate procurement for semiconductor manufacturing loads in science park clusters.
Australia
Net metering enforcement and battery storage incentives accelerate residential distributed solar adoption beyond utility-scale dominance. Green hydrogen offtake agreements supply Japanese METI-subsidized ammonia co-firing programs through dedicated export corridors. Data center and technology firms contract directly with renewable developers for 15-20 year tenors.
Asia-Pacific Renewable Energy Market Vendor Landscape
Listed leaders compete with private specialists across capital access and development velocity. State-owned enterprises anchor transmission-linked developments through integrated hydropower-to-grid infrastructure, while independent power producers secure offtake contracts through competitive auction participation. Three archetypes dominate: utility-backed developers with balance sheet capacity, manufacturing-integrated specialists with captive module supply, and offshore wind foundation engineers with heavy-lift vessel partnerships. Competitive moves concentrate on backward integration into cell manufacturing and strategic partnerships for installation vessel access.
Among China-based state enterprises, China Three Gorges Corporation and State Power Investment Corporation exemplify the utility-backed archetype with transmission infrastructure control. Adani Green Energy Limited represents the manufacturing-integrated model through its position in solar cell production. Xinjiang Goldwind Science & Technology Co., Ltd. occupies the specialized equipment tier with low-wind regime engineering capabilities.
| Leading Market Players |
|---|
| China Three Gorges Corporation |
| State Power Investment Corporation |
| Adani Green Energy Limited |
| ReNew Power Ventures |
| Vena Energy |
| Xinjiang Goldwind Science & Technology Co., Ltd. |
| Trina Solar Ltd. |
| Tata Power Company Limited |
| Sungrow Power Supply |
| Others |
Supply Flow & Price Mechanics
Ninety-day polysilicon inventory cycles in Xinjiang-based production hubs concentrate input cost leverage among a handful of raw material suppliers, compressing module manufacturer margins while amplifying pricing power for integrated cell-to-module producers in Gujarat and Rajasthan. This inventory-to-pricing dynamic forces project developers to lock in long-term offtake contracts before commissioning timelines slip.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across utility-scale procurement channels. Price differentiation separates premium-tier bifacial modules with tracking systems from standard fixed-tilt monofacial configurations, with certification grade under India's BIS standards and volume scale driving tier separation. Cost compression in standard-tier equipment is intensifying because China's MIIT firmware recertification cycles delay deployment and extend working capital requirements. State electricity boards exhibit highest price sensitivity due to renewable purchase obligation compliance pressures, while corporate offtakers in Taiwan's semiconductor clusters show lowest sensitivity given 24/7 clean energy matching requirements.
Supply Chain Analysis
Strategic stockpiling of polysilicon feedstock dominates over just-in-time preferences as Xinjiang-based producers control critical raw material flows. Module manufacturing draws from China, Vietnam, and Malaysia for cell assembly, while inverter production rests on IGBT semiconductor sourcing from China and Japan. Single-source vulnerability in jack-up and heavy-lift vessel availability constrains offshore wind construction windows across Asia-Pacific waters. Distribution runs through state-owned generation groups with transmission infrastructure control and independent power producers securing competitive auction slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology-application-end user intersections creates specialist niches as corporate power purchase agreements displace traditional utility intermediaries and reshape procurement channel economics.
For Market Incumbents: Compound transmission infrastructure control through integrated hydropower-to-grid assets in China's southwestern provinces. Defend auction participation rates by securing captive polysilicon supply chains before Xinjiang logistics bottlenecks deepen. State Power Investment Corporation and China Three Gorges Corporation anchor this consolidation logic through balance sheet capacity and grid access leverage.
For New Entrants and Emerging Players: Differentiate on foundation engineering specialization for Vietnam's shallow continental shelf offshore wind sites where installation vessel scarcity constrains incumbent expansion. Target Indonesia's archipelago markets where weak transmission infrastructure limits utility-scale penetration and distributed solar-plus-storage configurations bypass grid integration bottlenecks. Pursue direct corporate offtake contracting with Singapore data center operators seeking 15-20 year renewable supply tenors.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned enterprise renewable generation subsidiaries facing dual carbon target compliance deadlines and capital reallocation pressures. Long-term viability centers on developers with secured land banks in Gujarat and Rajasthan where irradiance levels and PLI scheme incentives converge. Watch Japan's METI feed-in-tariff revision schedules as the inflection signal for merchant-price exposure thresholds reshaping project finance structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Adani Green Energy Limited anchors module supply security through captive polysilicon-to-cell production in Rajasthan. |
| Power Purchase Agreement Expansion | Corporate offtakers in Taiwan's science park clusters lock 24/7 clean energy matching through bundled solar-plus-storage contracts. |
| Installation Vessel Partnership | Vietnam's offshore wind pipeline advances through heavy-lift vessel access agreements with Singapore marine contractors. |
| Green Certification Program | India's CEA quarterly digital registry platforms verify renewable purchase obligation compliance for utility procurement. |
| Hybrid Storage Configuration Deployment | Maharashtra and Karnataka developers meet dispatchable obligation requirements through co-located solar-plus-battery systems. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation across IEA reports, FERC filings, project development databases, and customs records. Bottom-up capacity aggregation from individual project pipelines triangulates against top-down regulatory target analysis for India's PLI scheme and China's dual carbon goals.
Variance decomposition across technology, generation capacity tier, project scale, regulatory framework, and regional grid type segments isolates growth contribution drivers over the projection horizon. CAGRs derive from installed capacity buildout trajectories, capacity factor assumptions, and merchant price exposure transitions under Japan's METI schedule revisions. Forecast inputs incorporate polysilicon supply elasticity and installation vessel availability constraints specific to Asia-Pacific offshore wind development.
Material uncertainties — polysilicon supply disruptions, feed-in-tariff cancellation cascades, and grid integration capacity shortfalls — sit outside the modeled envelope. Forecasts reflect assumptions documented in regulatory filing trajectories and disclosed project commissioning schedules. Revision becomes warranted when inverter firmware recertification backlogs or land acquisition friction in India's western states cross thresholds that compress development timelines beyond financing covenant windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Solar Highway Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Hydroelectric Cells Market