
 South Europe Battery Market | 2026-2036
South Europe Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South Europe Battery Market Analytics
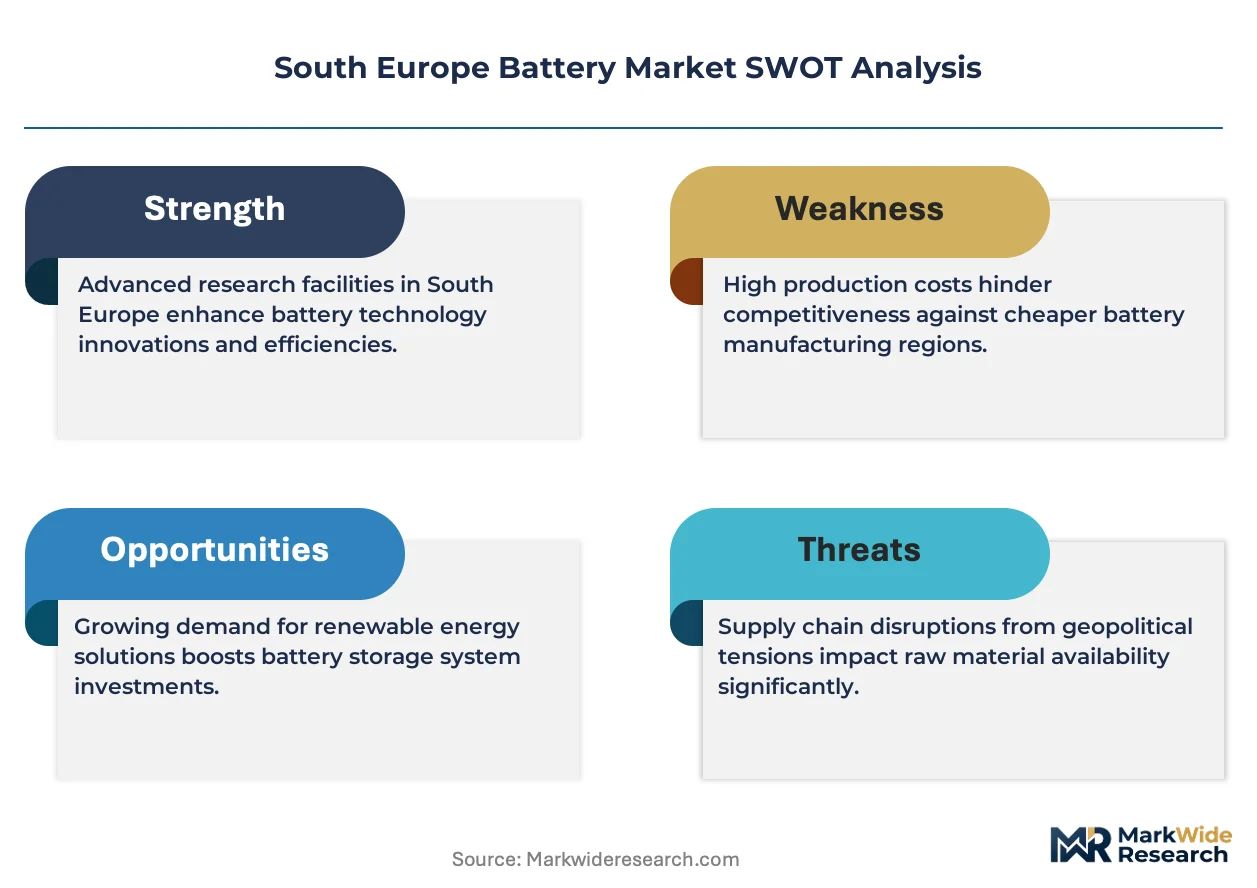
Solid-state electrolyte research is hardening the cost-performance calculus for next-generation cells. Contemporary Amperex Technology Co. Limited leverages its cylindrical cell expertise to anchor supply contracts with Mediterranean automotive assemblers. Saft Groupe specializes in nickel-based industrial batteries and dominates backup power installations across French and Italian critical infrastructure. Samsung SDI extends its prismatic battery platform into Southern European EV module production, competing on energy density benchmarks against Chinese cell imports.
A battery is an electrochemical device that stores and releases electrical energy through reversible redox reactions, typically operating at nominal voltages from 1.2V to 3.7V depending on chemistry, with energy densities ranging from 30 Wh/kg for lead-acid systems to over 250 Wh/kg for advanced lithium-ion formats. Its primary commercial purpose is to decouple energy generation from consumption, enabling portable electronics, vehicle propulsion, and grid stabilization where continuous wired supply is impractical. Lithium-ion chemistry leads product type revenue due to its dominance in electric vehicles and consumer electronics, while lead-acid retains margin pools in industrial backup and starter applications where capital cost sensitivity outweighs cycle life requirements. Among end users, automotive and renewable energy segments are absorbing the fastest capacity additions as Southern European utilities procure battery storage to balance intermittent solar generation.
The EU Battery Regulation, CE marking requirements, and Spain's national waste management framework are converging to mandate recycled content thresholds and carbon footprint disclosures for cells sold across the region. Italy's environmental ministry enforces extended producer responsibility rules that oblige manufacturers to finance collection networks, directly elevating operational costs for non-compliant importers. ECHA's REACH restrictions on nickel and cobalt compounds are forcing reformulation efforts in cathode active materials. Stakeholders must monitor how the EU Green Deal's evolving critical raw materials list reshapes sourcing obligations before committing to long-term offtake agreements.
Market Dynamics
EU battery passport mandates and Spain's domestic recycling thresholds are compressing supply chain timelines for lithium-ion pack assemblers serving Iberian and Italian automotive OEMs. These compliance pressures are redrawing procurement criteria faster than production capacity can adapt.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Spain's alignment with Brussels-mandated carbon footprint disclosures forces domestic pack assemblers to certify supply chain provenance, accelerating demand for traceable cathode materials from EU-sourced refiners.
- Grid-scale solar pairing:Italian utilities in the northern industrial corridor are procuring lithium-ion storage to balance photovoltaic intermittency, creating dedicated offtake channels for battery developers with TSO interconnection expertise.
- Logistics fleet electrification:Iberian last-mile delivery operators are replacing diesel vans with electric alternatives, concentrating procurement of mid-size battery packs from regional module integrators.
Market Restraints
- Raw material concentration risk:Cathode-grade lithium hydroxide supply concentrates in Chilean and Australian hard-rock refiners, exposing Spanish pack assemblers to shipping cost volatility and currency fluctuation.
- REACH nickel compound restrictions:ECHA's evolving classification of nickel salts as substances of very high concern is forcing reformulation of NMC cathode recipes, delaying product recertification timelines.
- Lead-acid substitution ceiling:Industrial backup power segments in southern Italian manufacturing zones retain capital-cost sensitivity, capping lithium-ion penetration in forklift and stationary applications.
Strategic Opportunities
- Portuguese lithium conversion infrastructure:Underdeveloped spodumene refining capacity in the Iberian Peninsula creates white space for integrated mine-to-cell projects serving EU battery passport requirements.
- V2G aggregation platforms:Bidirectional charging hardware converging with utility demand-response software enables Italian EV fleet operators to monetize parked vehicle storage capacity.
- Extended producer responsibility financing:Italy's environmental ministry mandates for collection network funding allow compliant producers to capture end-of-life material streams before non-compliant importers.
Industry Challenges
- Electrolyte formulation talent scarcity:Solid-state battery development requires polymer chemists and ceramic processing specialists that Spanish universities and vocational programs currently undersupply.
- CE marking timeline compression:Notified body backlogs for battery safety testing under the EU Battery Regulation are extending product launch windows for Italian module integrators.
- Legacy industrial power infrastructure:Aging transformer capacity in Sicily and Calabria restricts grid-connection permits for utility-scale storage projects, forcing developers into costly upgrade negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Europe Battery Market |
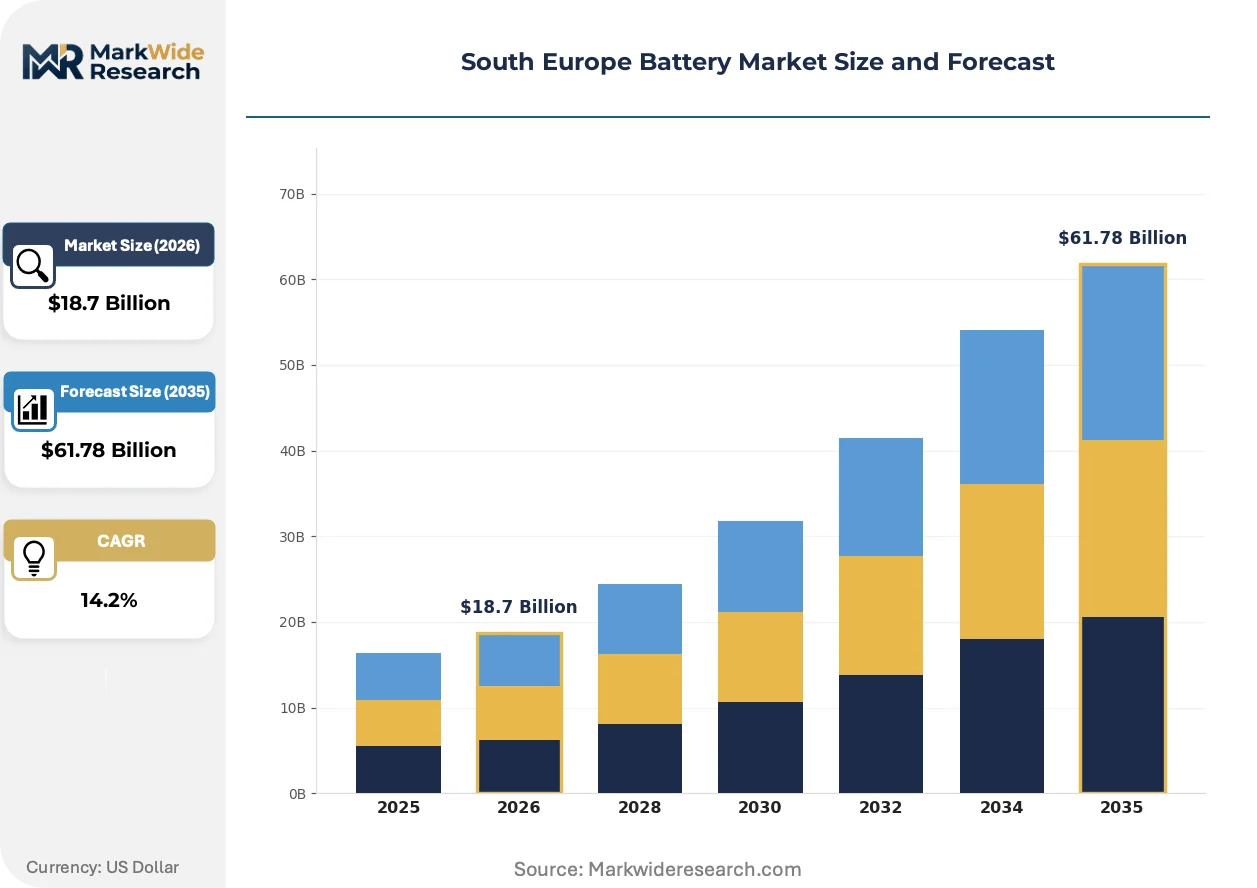
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Application: Energy Storage Systems, Electric Vehicles, Power Tools, Smart Grids Technology: Battery Management Systems, Rechargeable Batteries, Fuel Cells, Supercapacitors |
| Companies Covered | Toshiba Corporation, Contemporary Amperex Technology Co. Limited, BYD Company Limited, Panasonic Corporation, Duracell Inc., Sovema Group, SIA Industria Accumulatori, Saft Groupe, Samsung SDI, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Europe Battery Market Evolving Landscape
Solid-state electrolyte architectures and silicon-anode formulations are compressing the cost-performance frontier for next-generation cells. Southern European automotive OEMs are accelerating validation timelines to secure supply positions before capacity constraints harden.
Silicon-dominant anode technology is converging with dry electrode coating processes to reduce manufacturing energy intensity. BMW and Stellantis validation programs in northern Italy are advancing pilot production volumes for 2026 platform integration. This convergence is compressing incumbent graphite anode cost advantages and forcing Chinese cell imports to compete on cycle-life warranties rather than upfront pricing.
Spain's national waste management framework is tightening enforcement of extended producer responsibility for battery collection networks. The country's environmental ministry now mandates financing mechanisms that elevate operational costs for non-compliant importers. Italian automotive OEMs are responding by consolidating supplier audits around EU Battery Regulation carbon footprint disclosure requirements.
Fleet operators across Iberian logistics networks are unbundling battery procurement from vehicle acquisition, signing separate lease structures for pack replacement and residual value management. This separation disrupts traditional OEM captive financing models and elevates the influence of independent battery asset managers. Portuguese and Spanish last-mile delivery cooperatives are pioneering this structure to isolate technology obsolescence risk.
South Europe Battery Market Segmentation
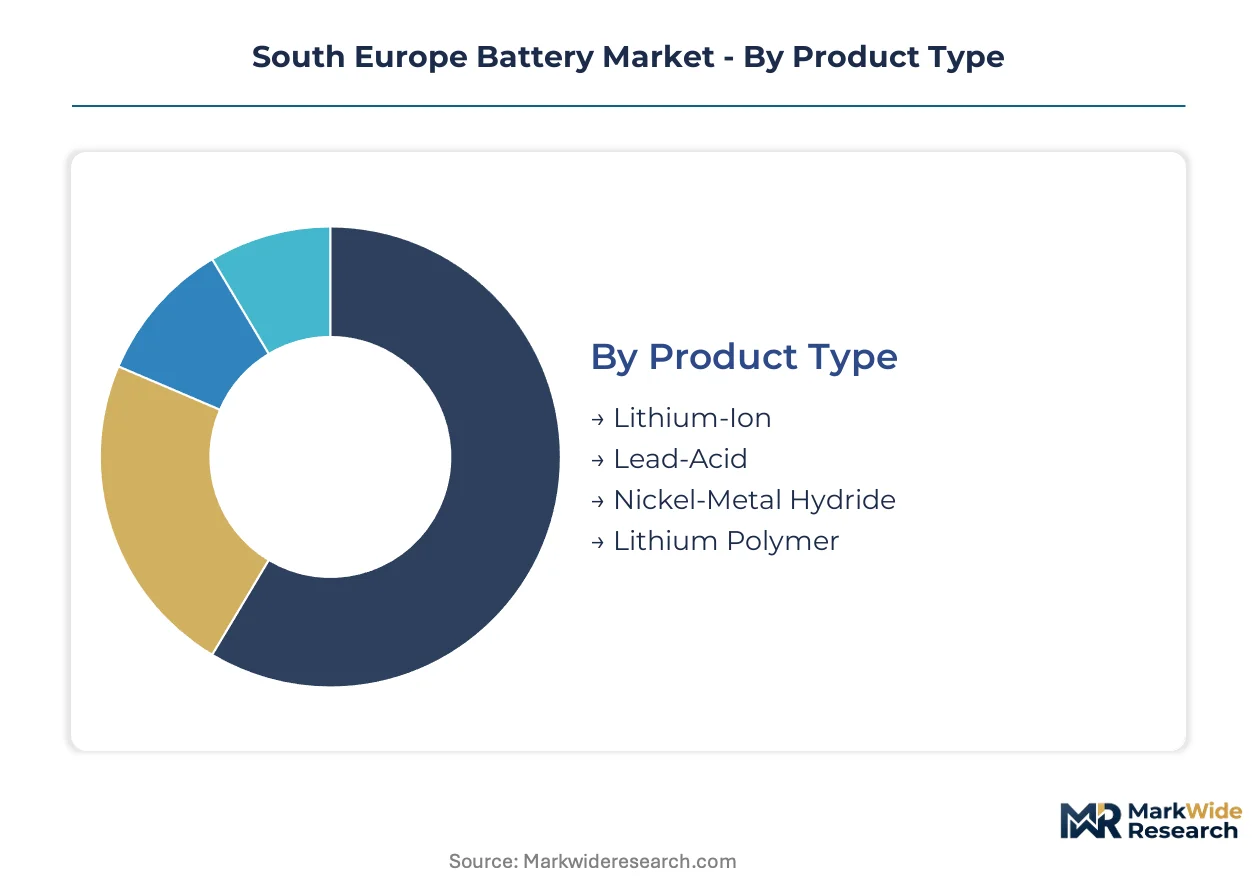
South Europe's battery market segments reflect divergent replacement cycles and upgrade pressures across chemistries and applications. Procurement patterns in Iberian and Italian industrial corridors vary sharply by voltage class and duty cycle requirements.
Product Type:
Replacement cycle timing drives chemistry selection, with shorter upgrade windows favoring advanced lithium formats over legacy lead-acid infrastructure.
- Lithium-Ion:These cells deploy layered oxide or phosphate cathode architectures with energy densities exceeding 200 Wh/kg. Italian automotive OEMs in the northern industrial corridor are consolidating procurement around NMC and LFP packs for EV platforms, pressured by EU Battery Regulation carbon footprint disclosure mandates.
- Lead-Acid:Flooded and valve-regulated designs dominate starter-lighting-ignition applications and forklift fleets. Southern Italian manufacturing zones retain these batteries for capital-cost-sensitive backup power, though lithium-ion substitution is accelerating in Iberian logistics electrification.
- Nickel-Metal Hydride:These cells utilize rare-earth hydrogen storage alloys with moderate energy density. Hybrid vehicle programs at Stellantis facilities in Italy sustain residual demand for this chemistry.
- Lithium Polymer:Pouch-cell configurations with gel electrolytes enable flexible form factors. Consumer electronics assemblers in Spain's Catalonia cluster source these for wearable and portable device integration.
Volume placements concentrate in Lithium-Ion; the faster expansion belongs to Lithium Polymer.
End User:
Customer procurement scale determines contract structure, with fleet operators unbundling battery leases from vehicle acquisition.
- Consumer Electronics:Smartphone and laptop manufacturers in Spain's Barcelona-Tarragona corridor drive demand for compact pouch cells with rapid charge capability.
- Automotive:OEM assembly plants in Turin, Milan, and Martorell anchor lithium-ion pack procurement for BEV and PHEV platforms, with Stellantis and SEAT-Skoda validation timelines compressing supplier selection windows.
- Industrial:Forklift fleets and uninterrupted power supply installations across Portuguese manufacturing parks favor lead-acid for capital cost containment, though lithium-ion penetration is climbing in multi-shift operations.
- Renewable Energy:Italian utilities in the northern industrial corridor are procuring grid-scale lithium-ion storage to balance photovoltaic intermittency, creating dedicated offtake channels for developers with TSO interconnection expertise.
Contract values peak in Automotive; Renewable Energy is climbing the fastest.
Application:
Duty cycle intensity shapes cell specification, with deep-discharge applications demanding distinct cathode formulations.
- Energy Storage Systems:Containerized lithium-ion installations provide frequency regulation and peak shaving. Spanish grid operators in the Madrid region are pairing these with solar farms to meet REPowerEU storage targets.
- Electric Vehicles:Passenger cars, vans, and buses require thermal-managed packs with 800V architectures. Iberian last-mile delivery cooperatives are pioneering battery lease structures to isolate technology obsolescence risk.
- Power Tools:Cordless construction equipment utilizes cylindrical cells with high discharge rates. Italian professional tool manufacturers source these from regional module integrators.
- Smart Grids:Distributed battery assets enable demand-response aggregation. V2G platforms in Italy allow fleet operators to monetize parked vehicle storage capacity.
Deployment scale favors Energy Storage Systems; Smart Grids show the steepest expansion trajectory.
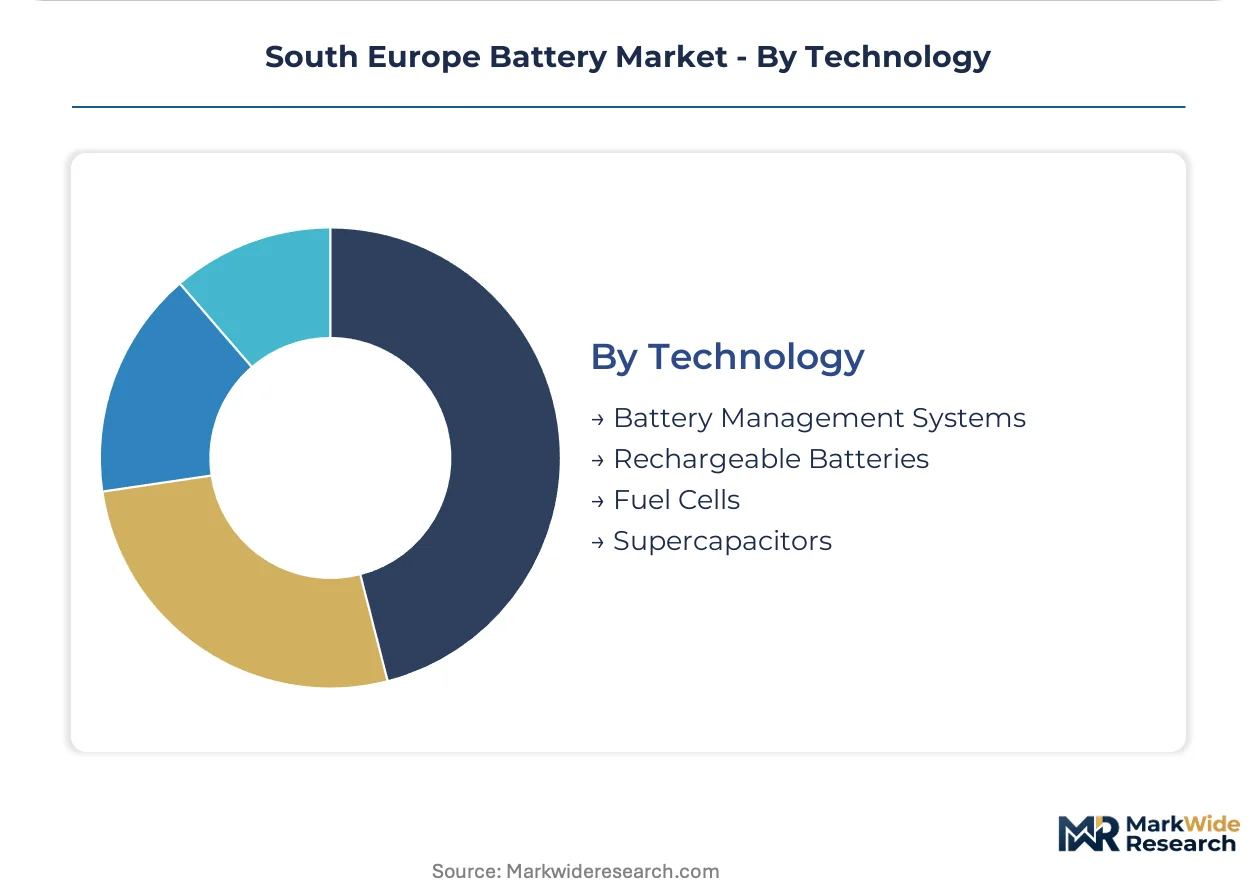
Technology:
System-level integration determines value capture, with software-enabled battery intelligence commanding margin premiums over commodity cell supply.
- Battery Management Systems:These electronic control units monitor cell voltage, temperature, and state-of-charge with ASIL-D functional safety ratings. Italian module integrators are developing in-house BMS capabilities to reduce dependence on Asian semiconductor suppliers.
- Rechargeable Batteries:Secondary electrochemical cells dominate commercial revenue across all chemistries. Spanish pack assemblers are certifying supply chain provenance to meet Brussels-mandated recycled content thresholds.
- Fuel Cells:Hydrogen proton-exchange membrane systems provide extended range for heavy commercial vehicles. Portuguese port authorities are piloting fuel cell yard tractors in Sines.
- Supercapacitors:Electric double-layer capacitors deliver burst power for regenerative braking and grid frequency response. Italian rail operators deploy these alongside batteries in hybrid tram systems.
Revenue concentration sits with Rechargeable Batteries; Fuel Cells are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PILA Value in Spain's Basque Country and Italy's Lombardy incentives zone are concentrating battery assembly investments. These fiscal accelerators are pulling cathode material processing and module integration into Southern European industrial corridors faster than pure market dynamics would predict.
Italy
Stellantis validation programs in Turin and Milan are compressing supplier selection timelines for EV platforms. The national environmental ministry enforces extended producer responsibility rules that oblige manufacturers to finance collection networks. Lombardy's northern industrial corridor hosts co-located manufacturing partnerships between automotive OEMs and grid-scale storage developers.
Spain
Iberian last-mile delivery cooperatives are pioneering battery lease structures to isolate technology obsolescence risk. The national waste management framework mandates recycled content thresholds and carbon footprint disclosures for cells sold across the region. Catalonia's Barcelona-Tarragona corridor anchors consumer electronics pouch cell demand from smartphone and laptop manufacturers.
Portugal
Sines port authorities are piloting fuel cell yard tractors for heavy commercial vehicle applications. Underdeveloped spodumene refining capacity creates white space for integrated mine-to-cell projects serving EU battery passport requirements. The country's lithium conversion infrastructure remains underdeveloped relative to extraction potential.
France
Saft Groupe dominates backup power installations across French critical infrastructure with nickel-based industrial batteries. ECHA's REACH restrictions on nickel and cobalt compounds are forcing reformulation efforts in cathode active materials. The country's automotive suppliers are consolidating procurement around EU Battery Regulation compliance timelines.
South Europe Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The market exhibits tiered concentration with Asian cell giants anchoring supply positions while regional integrators capture module assembly value. Three archetypes dominate: cylindrical cell specialists leveraging automotive validation relationships, industrial battery incumbents with critical infrastructure lock-in, and prismatic platform providers competing on energy density benchmarks. Capacity expansion and strategic partnerships represent the dominant competitive moves as players race to secure offtake ahead of regulatory deadlines.
Within the cylindrical cell tier, Contemporary Amperex Technology Co. Limited anchors supply relationships with Mediterranean automotive assemblers. Saft Groupe exemplifies the industrial incumbent archetype through its specialization in nickel-based systems. Samsung SDI occupies a position in the prismatic platform segment, extending its format into Southern European EV module production. These three represent distinct strategic postures rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Contemporary Amperex Technology Co. Limited |
| BYD Company Limited |
| Panasonic Corporation |
| Duracell Inc. |
| Sovema Group |
| SIA Industria Accumulatori |
| Saft Groupe |
| Samsung SDI |
| Others |
Value Network & Pricing Analysis
EU Battery Regulation carbon footprint disclosure mandates are forcing Italian and Spanish pack assemblers to certify cathode material provenance, elevating procurement costs for traceable supply chains and compressing margins on non-compliant inventory. This specification-driven sourcing pressure is reshaping how regional integrators negotiate cell supply contracts and manage working capital exposure to price volatility.
Pricing Analysis
Premium pricing for short lead-time delivery of NMC and LFP cells dominates contract negotiations with Turin and Milan automotive OEMs, while spot inventory of lead-acid systems trades at discounts reflecting capital-cost sensitivity in southern Italian forklift fleets. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified cells with full passport documentation from Asian imports with limited traceability and refurbished industrial batteries. Pricing pressure stems from REACH nickel compound restrictions forcing NMC reformulation and delayed recertification timelines. Fleet operators in Iberian logistics networks exhibit highest price sensitivity, prioritizing total cost of ownership over upfront cell pricing.
Supply Chain Analysis
Polymer chemists and ceramic processing specialists remain scarce across Spanish universities and vocational programs, constraining solid-state electrolyte development timelines and elevating recruitment costs for module integrators. Cathode-grade lithium hydroxide supply concentrates in Chilean and Australian hard-rock refiners, with Spanish pack assemblers drawing from these distant sources for EU battery passport compliance. Raw material dependencies rest on cobalt sulfate from the DRC, nickel sulfate from Indonesia, and separator films from South Korean manufacturers. Single-source vulnerability in Chilean lithium refining exposes assemblers to shipping cost volatility and currency fluctuation. Distribution runs through regional module integrators in Lombardy and the Basque Country serving automotive OEMs and grid-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell production capacity with EU battery passport compliance remains the binding constraint propping pricing power for certified suppliers, as Iberian and Italian demand outpaces qualified domestic refining and module integration capacity.
For Market Incumbents: To counter REACH nickel compound restrictions delaying NMC product recertification, Saft Groupe and Samsung SDI should accelerate LFP platform qualification with Stellantis and SEAT-Skoda while securing backward integration into Portuguese spodumene conversion infrastructure to anchor EU-sourced material streams. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the most penetrable route for battery asset managers seeking to unbundle pack procurement from vehicle acquisition in Iberian last-mile delivery cooperatives, bypassing traditional OEM captive financing relationships. For Investors and Strategic Acquirers: The window for entry favors integrated mine-to-cell projects with EU battery passport positioning; material deviation in ECHA's evolving critical raw materials list or Iberian environmental permitting timelines warrants pause and re-evaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Conversion | Portuguese spodumene refining addresses EU battery passport provenance requirements for Italian automotive OEMs. |
| Battery-as-a-Service Platform Launch | Fleet operators in Iberian logistics networks isolate technology obsolescence risk through separate pack leases. |
| Solid-State Electrolyte Partnership | BMW and Stellantis validation programs in northern Italy compress supplier selection windows for next-generation cells. |
| Extended Producer Responsibility Network | Compliant producers capture end-of-life material streams before non-compliant importers under Italian ministry mandates. |
| V2G Aggregation Software Development | Bidirectional charging hardware enables Italian fleet operators to monetize parked vehicle storage capacity. |
Research Methodology
Independent corroboration across primary interviews with cell procurement directors at Stellantis and SEAT-Skoda, module integration engineers in Lombardy and the Basque Country, and utility storage planners at Italian TSOs underwrites the qualitative findings, validated against EU Battery Regulation implementation guidance, ECHA REACH restriction updates, Iberian customs trade data, and automotive production databases from IHS Markit. Bottom-up capacity assessments and top-down demand projections were triangulated to anchor segment-level outputs.
Comparable-period anchoring to historical lithium-ion deployment volumes in Iberian logistics electrification and Italian grid-scale solar pairing established the forecast baseline across the projection horizon. Segmentation modeling incorporated chemistry format, end-use application, voltage class, and regional regulatory cluster dimensions. CAGRs were derived from supply-demand balance analysis and capacity expansion announcements, with electrolyte formulation talent availability and CE marking timeline compression treated as industry-specific forecast modifiers.
The model holds under stable EU Battery Regulation implementation timelines and REACH nickel classification boundaries; deviation in ECHA's substances of very high concern list or Iberian environmental permitting backlogs would shift capacity addition assumptions and pricing trajectories. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc Carbon Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Elastic Battery Binders Market
Batteries
Residential Battery Market
Batteries
HIT Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Military Battery Market
Batteries
AAA Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Thin Film and Printed Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
North America Consumer Battery Market
Batteries
Nanicl Battery Market
Batteries
Alkaline Secondary Battery Market