
 Europe Power to Gas Market | 2026-2036
Europe Power to Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power to Gas Market Foresight
Electrolyzer hardware margins is narrowing as commoditization pressures stack against proprietary stack designs. Siemens Energy anchors its position through alkaline and proton exchange membrane technology leadership. Sunfire GmbH specializes in high-temperature solid oxide electrolysis for industrial steam integration. Nel ASA competes on PEM stack manufacturing scale with automated production lines in Norway.
Power to gas converts surplus renewable electricity into hydrogen or synthetic methane through water electrolysis followed by optional methanation, typically operating at pressures between 15 and 30 bar for grid injection compatibility. The technology serves primarily as seasonal energy storage and carbon-neutral feedstock supply for hard-to-abate industries. Electrolysis occupies the dominant revenue position given its position as the mandatory first conversion stage across all downstream applications. Energy Storage leads application demand as utilities seek multi-day buffering against renewable intermittency. Industrial Feedstock is expanding fastest as chemical manufacturers retrofit crackers and ammonia plants for hydrogen-ready operation.
The EU Green Deal and REPowerEU framework mandate hydrogen-ready infrastructure and carbon intensity thresholds that directly shape electrolyzer procurement specifications. ECHA REACH compliance and CE marking requirements govern stack materials and pressure vessel certification for cross-border equipment trade. Germany's KBA and France's ANSM participate in safety protocol harmonization for hydrogen transport and storage systems. Stakeholders must monitor how the EU AI Act and incoming CSRD reporting obligations will reshape project finance due diligence and operational transparency requirements.
Market Dynamics
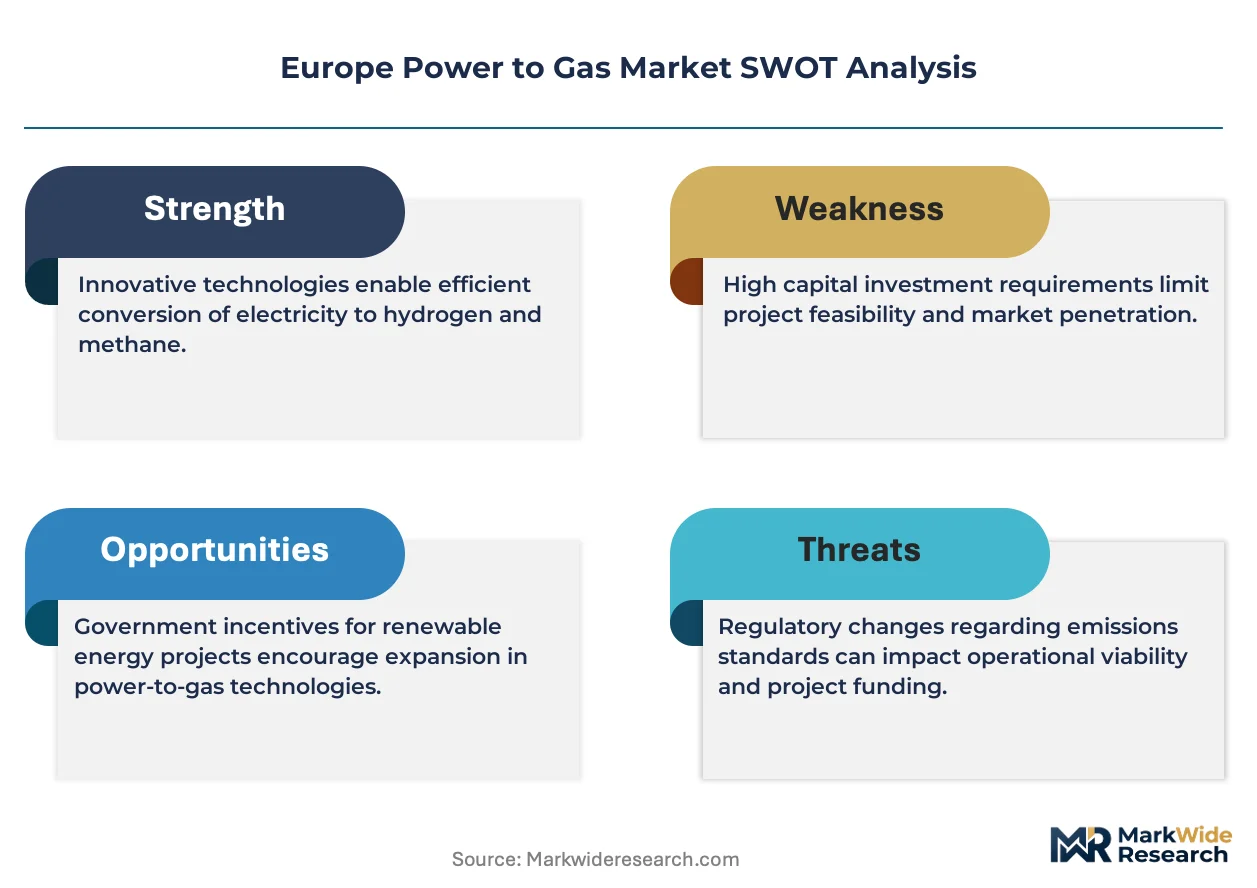
Electrolyzer commoditization is compressing hardware margins while REPowerEU deployment mandates pull capacity expansion faster than supply chains can absorb, creating a structural tension between cost pressure and delivery urgency.
Growth Catalysts
- REPowerEU Framework:Binding hydrogen-ready infrastructure mandates across member states are accelerating electrolyzer procurement timelines for ammonia and methanol producers in the Netherlands and Germany.
- Industrial Cluster Concentration:Chemical parks around Ludwigshafen and the Ruhr region are aggregating offtake demand sufficient to underwrite multi-hundred-megawatt electrolyzer installations.
- Solid Oxide Electrolysis:High-temperature stack designs that integrate with industrial steam networks are opening efficiency advantages for refineries and steelmakers retrofitting for carbon-neutral feedstock.
Market Restraints
- Critical Mineral Supply Concentration:Proton exchange membrane stacks depend on iridium and platinum group metal supply chains concentrated in South Africa and Russia, exposing procurement to geopolitical disruption.
- Grid Connection Queues:Transmission system operators in Germany and France face multi-year backlogs for renewable electricity interconnection, delaying electrolyzer commissioning.
- Natural Gas Price Volatility:Synthetic methane cost competitiveness against fossil alternatives fluctuates with TTF hub pricing, undermining long-term offtake contract security.
Strategic Opportunities
- Port Hydrogen Hubs:Rotterdam and Hamburg are developing import terminals for renewable hydrogen derivatives, creating demand for domestic electrolyzer capacity to blend with imported molecules.
- CSRD Reporting Obligations:Corporate sustainability reporting mandates are forcing chemical manufacturers to document Scope 3 emissions reductions, favoring power-to-gas certificates with verifiable carbon intensity.
- Alkaline-PEM Hybrid Systems:Configurations combining alkaline base-load capacity with PEM rapid-response stacks are emerging as a technology convergence path for utilities managing renewable intermittency.
Industry Challenges
- Pressure Vessel Certification:CE marking and PED compliance for 30-bar hydrogen storage systems require 18-24 month validation cycles that delay project commercial operation.
- Electrolyzer Technician Shortage:Stack assembly and membrane maintenance demand specialized skills that vocational programs in Germany and the Netherlands have not yet scaled to match deployment targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power to Gas Market |
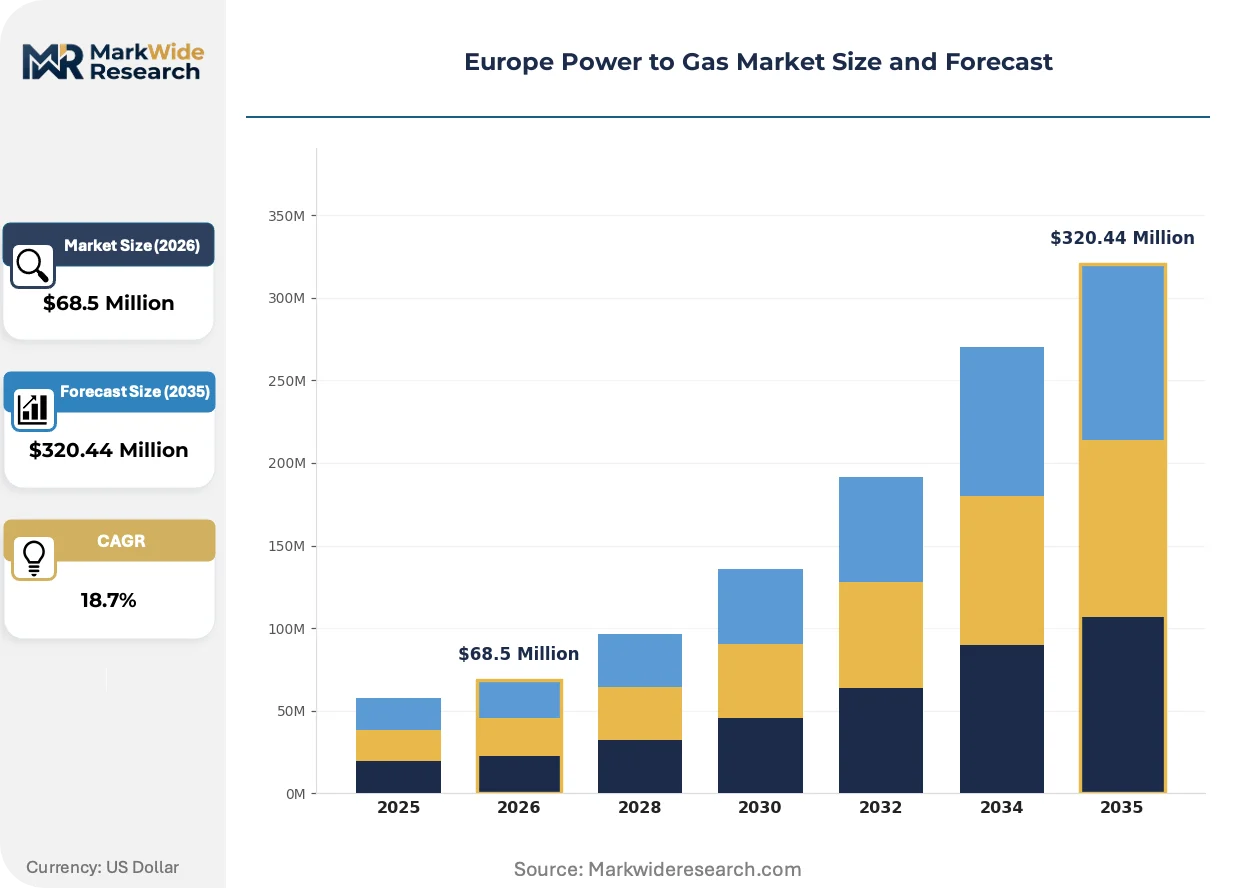
| Market Size in 2026 | $68.5 Million |
| Market Size in 2035 | $320.44 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Methanation, Biomethanation, Power-to-Liquid Application: Energy Storage, Transportation Fuel, Industrial Feedstock, Grid Balancing End User: Utilities, Industrial Sectors, Transportation Providers, Chemical Manufacturers Installation: Onshore, Offshore, Power Plants, Dedicated Facilities |
| Companies Covered | Ineratec GmbH, Siemens Energy AG, Nel ASA, MAN Energy Solutions, Sunfire GmbH, Sempra Energy, Electrochaea GmbH, ENTSOG AISBL, GRT Gaz SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power to Gas Market Shifts & Advancements
Technology trajectories in the Europe Power to Gas Market center on stack efficiency gains, regulatory compliance automation, and procurement model restructuring that favors long-term service over equipment ownership.
Solid oxide electrolysis is migrating from pilot demonstrations to commercial scale at industrial heat users seeking steam integration. Steelmakers in Sweden and chemical producers in Belgium are installing 10-20 MW units to validate thermal efficiency claims against alkaline alternatives. This migration is compressing the addressable market for pure hydrogen-only applications while expanding the total serviceable market for integrated industrial decarbonization.
The EU AI Act and incoming CSRD reporting obligations are reshaping project finance due diligence requirements. Lenders now demand automated carbon intensity tracking and predictive maintenance documentation that legacy SCADA systems cannot provide. Electrolyzer vendors in Germany and France are responding by embedding edge computing modules for real-time efficiency certification.
Long-term service contracts are displacing equipment-only sales as the dominant commercial model. Utilities in Denmark and the Netherlands prefer availability guarantees and performance-based maintenance over capital expenditure ownership. This shift concentrates vendor risk on operational uptime but locks in 15-year revenue streams that improve project bankability.
Europe Power to Gas Market Segmentation
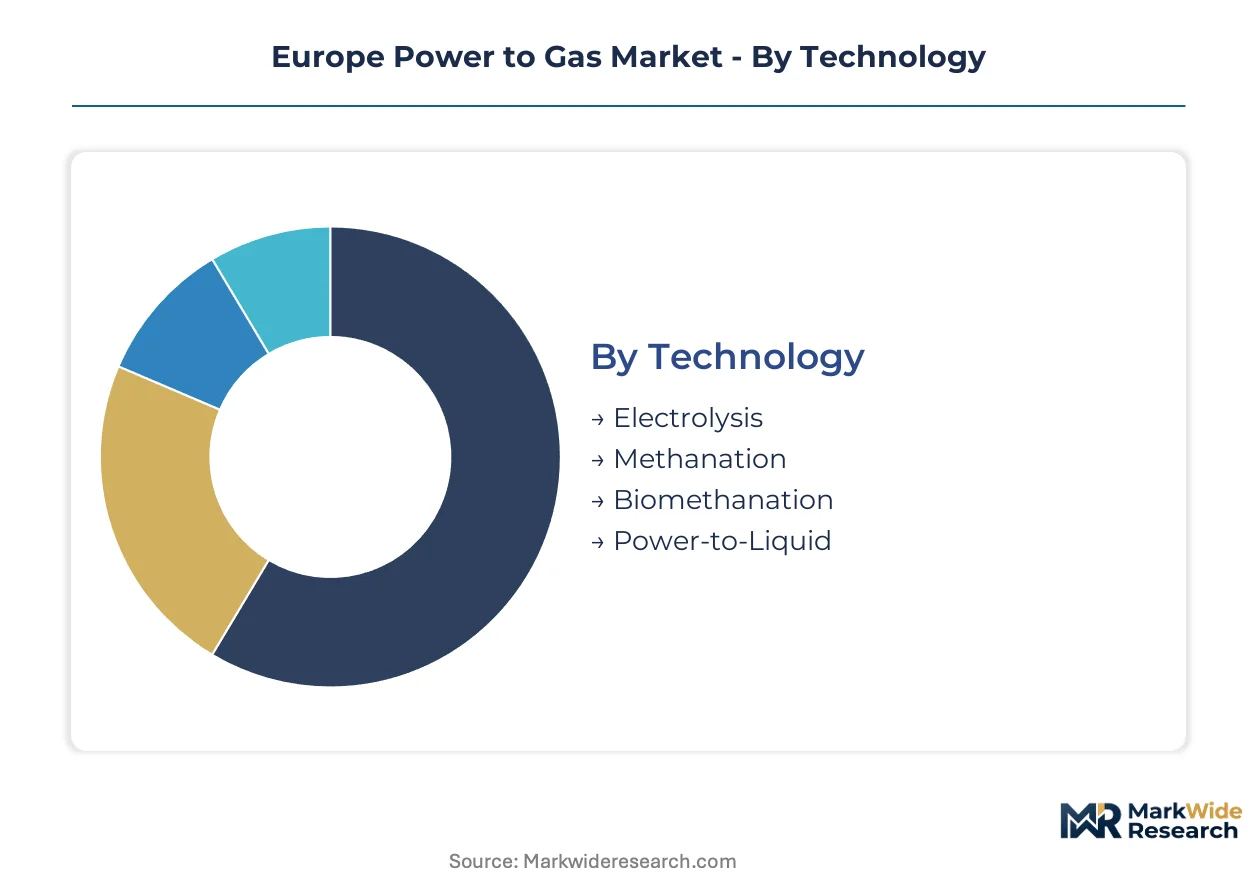
Power-to-gas deployments in Europe fragment across conversion technologies, end-use applications, and installation configurations that each carry distinct procurement cycles and regulatory footprints. Understanding these segment boundaries clarifies where electrolyzer vendors compete on efficiency versus where methanation specialists capture value from carbon capture integration.
Technology:
Electrolysis systems turn over on 5-7 year replacement cycles driven by membrane degradation, while methanation catalyst beds extend to 10-15 years before regeneration, creating divergent revenue timing for equipment suppliers.
- Electrolysis:Water splitting via alkaline, PEM, or solid oxide stacks operates at 15-30 bar for direct hydrogen output or methanation feedstock. German chemical parks in Ludwigshafen and the Ruhr cluster are aggregating multi-hundred-megawatt procurement to anchor this segment's volume base.
- Methanation:Catalytic hydrogenation of carbon dioxide into synthetic methane requires captured CO2 from industrial sources or biogas upgrading. Dutch ammonia producers and Belgian steelmakers are retrofitting crackers to accept this carbon-neutral feedstock, though TTF price volatility constrains offtake contract security.
- Biomethanation:Biological conversion routes using archaea microorganisms operate at lower temperatures but slower throughput than catalytic alternatives.
- Power-to-Liquid:Fischer-Tropsch synthesis of hydrogen and CO2 into synthetic fuels targets aviation and maritime applications with stringent certification requirements.
Electrolysis anchors the volume base while power-to-liquid gains share at the steepest rate as aviation decarbonization mandates tighten.
Application:
Cost tiers separate seasonal storage investments by utilities from spot-market grid balancing services, with industrial feedstock commanding premium pricing for carbon intensity certification.
- Energy Storage:Multi-day buffering against renewable intermittency leverages salt caverns and depleted gas fields for hydrogen or synthetic methane storage. Danish and German utilities prefer long-term service contracts with availability guarantees over capital ownership.
- Industrial Feedstock:Ammonia and methanol production in the Netherlands and Germany drives retrofit demand for hydrogen-ready crackers. CSRD reporting obligations are forcing chemical manufacturers to document Scope 3 reductions, favoring power-to-gas certificates with verifiable carbon intensity.
- Transportation Fuel:Synthetic methane and hydrogen for heavy road and rail applications competes with battery electrification on total cost of ownership.
- Grid Balancing:Rapid-response electrolyzer stacks provide frequency regulation and demand-side flexibility to transmission system operators facing renewable integration challenges.
Energy storage dominates installed capacity while industrial feedstock expands most quickly as ammonia producers accelerate decarbonization timelines.
End User:
Customer type determines procurement sophistication, with utilities favoring standardized specifications and chemical manufacturers demanding customized integration with existing steam and pressure systems.
- Utilities:Grid operators and energy retailers in Germany, Denmark, and the Netherlands aggregate demand for standardized electrolyzer platforms with automated production lines.
- Industrial Sectors:Steelmakers in Sweden and refineries in Belgium are installing 10-20 MW solid oxide units to validate thermal efficiency against alkaline alternatives.
- Transportation Providers:Rail operators and shipping lines seek synthetic fuel offtake agreements with certified carbon intensity for scope 3 reporting compliance.
- Chemical Manufacturers:BASF and comparable producers in Ludwigshafen are underwriting dedicated facility installations with 15-year hydrogen supply contracts.
Utilities anchor procurement volume while chemical manufacturers drive the steepest capacity expansion through cluster aggregation models.
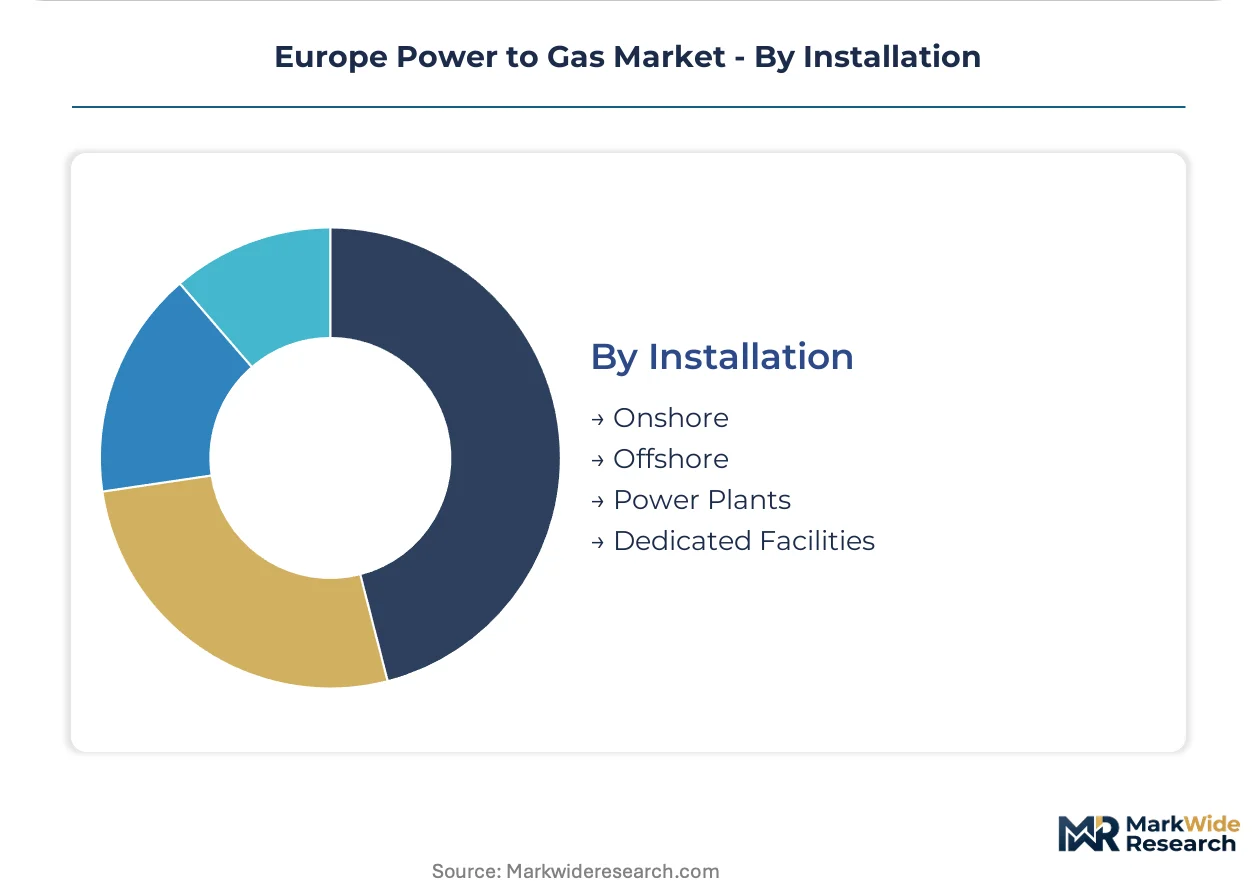
Installation:
Geography and infrastructure integration level segment projects by development timeline, with offshore and dedicated facilities facing extended permitting against power plant retrofits.
- Onshore:Industrial cluster installations at existing chemical parks leverage available grid connection and carbon capture infrastructure, compressing commissioning timelines.
- Offshore:North Sea platforms and coastal locations access dedicated renewable generation but face 18-24 month pressure vessel certification cycles under PED and CE marking requirements.
- Power Plants:Retrofit of existing gas turbine sites for hydrogen blending or synthetic methane firing reduces greenfield development risk.
- Dedicated Facilities:Greenfield electrolyzer parks at Rotterdam and Hamburg port hubs integrate import terminals for renewable hydrogen derivatives with domestic production capacity.
Onshore installations anchor deployment volume while dedicated facilities gain share fastest as port hydrogen hubs aggregate multimodal offtake demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes power-to-gas capacity for industrial feedstock at rates exceeding neighbors focused on grid storage, while Dutch demand clusters around port hydrogen hubs and French procurement emphasizes nuclear-coupled electrolysis for seasonal buffering.
Germany
Ruhr industrial clusters and Ludwigshafen chemical parks are aggregating multi-hundred-megawatt electrolyzer offtake for ammonia and methanol production. The KBA safety protocol harmonization with France's ANSM accelerates pressure vessel certification for cross-border hydrogen transport. North Rhine-Westphalia hosts the densest concentration of solid oxide pilot installations validating steam integration at steelmakers.
Netherlands
Rotterdam port hydrogen hubs are blending domestic electrolyzer output with imported renewable hydrogen derivatives for chemical manufacturers. REPowerEU binding mandates accelerate procurement timelines for hydrogen-ready ammonia plants. Eindhoven-region technical universities are scaling vocational programs to address electrolyzer technician shortages.
France
Nuclear-coupled electrolysis dominates capacity planning for seasonal energy storage against renewable intermittency. ANSM participation in German KBA safety harmonization streamlines cross-border equipment certification. Auvergne-Rhône-Alpes industrial zones are piloting alkaline-PEM hybrid configurations for rapid-response grid balancing.
Sweden
Steelmakers in northern industrial zones are installing 10-20 MW solid oxide units to validate thermal efficiency against alkaline alternatives. The country's carbon pricing framework exceeds EU ETS levels, forcing faster industrial feedstock decarbonization. Gothenburg port authorities are developing synthetic fuel terminals for maritime offtake agreements.
Belgium
Antwerp chemical refineries are retrofitting crackers for synthetic methane acceptance under CSRD Scope 3 reporting obligations. ECHA REACH compliance governs stack materials for electrolyzer imports from German suppliers. Flanders industrial clusters concentrate demand for biomethanation routes using captured CO2 from cement production.
Europe Power to Gas Market Competitive Landscape
Capability concentration sits with specialized stack designers; scale advantage sits with automated production fabricators. The vendor base separates into three tiers: integrated energy conglomerates with project development arms, pure-play electrolyzer specialists with proprietary membrane technology, and industrial gas incumbents leveraging existing hydrogen distribution infrastructure. Consolidation pressure is accelerating through strategic partnerships between stack manufacturers and utility offtakers, alongside capacity expansion announcements for gigawatt-scale electrolyzer factories.
Among Germany-based technology developers, Siemens Energy AG and Sunfire GmbH exemplify divergent technology archetypes—alkaline and proton exchange membrane leadership versus high-temperature solid oxide specialization. Nel ASA, a Norwegian public limited company, anchors the scale-driven tier with automated PEM stack manufacturing. These three entities represent the competitive spectrum from proprietary efficiency optimization to production volume capture.
| Leading Market Players |
|---|
| Ineratec GmbH |
| Siemens Energy AG |
| Nel ASA |
| MAN Energy Solutions |
| Sunfire GmbH |
| Sempra Energy |
| Electrochaea GmbH |
| ENTSOG AISBL |
| GRT Gaz SA |
| Others |
Supply & Pricing Matrix
Iridium supply concentration in South Africa and Russia determines both the cost spread between PEM and alkaline electrolyzer tiers and the geographic shape of component sourcing strategies. Procurement teams in Germany and the Netherlands hedge this exposure through dual-stack configurations that blend alkaline base-load capacity with PEM rapid-response units.
Pricing Analysis
Long-term offtake contracts with 15-year hydrogen supply commitments dominate chemical manufacturer procurement in Ludwigshafen and the Ruhr, while utilities prefer availability-based service agreements with performance guarantees. Price differentiation rests on carbon intensity certification grade and membrane efficiency specifications, with CSRD-compliant documentation commanding premium positioning. Cost compression in alkaline stack manufacturing is intensifying because Chinese capacity expansion is flooding standardized segments. Chemical manufacturers with Scope 3 reporting obligations show least price sensitivity; spot-market grid balancers exhibit highest sensitivity to capital expenditure timing.
Supply Chain Analysis
Upstream feedstock for proton exchange membrane stacks draws from South African platinum group metal mines and Russian palladium refining capacity, creating concentrated geopolitical exposure. Alkaline electrolyzer production sources nickel-coated steel from Chinese rolling mills and separator membranes from Japanese chemical suppliers. Single-source vulnerability in iridium anode coating creates procurement risk for PEM vendors targeting industrial clusters. Distribution runs through EPC contractors with utility relationships in Germany, Denmark, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology archetypes creates white-space opportunities as REPowerEU mandates pull divergent stack designs into adjacent industrial applications. Chemical manufacturers retrofitting ammonia plants and steelmakers validating solid oxide steam integration generate distinct procurement specifications that resist vendor consolidation.
For Market Incumbents: Entrench position through captive iridium sourcing arrangements with South African refiners and alkaline stack manufacturing scale in Norway. Siemens Energy and Sunfire GmbH face emerging pressure from Chinese alkaline competitors with automated production lines; backward integration into membrane coating capacity secures margin protection against commoditization. For New Entrants and Emerging Players: French nuclear-coupled electrolysis for seasonal storage represents underpenetrated territory with limited incumbent specialization. Belgian steelmakers and Dutch port hydrogen hubs offer white-space entry points through alkaline-PEM hybrid configurations. Go-to-market positioning should emphasize automated carbon intensity tracking for CSRD compliance documentation. For Investors and Strategic Acquirers: Specialized solid oxide stack designers with validated steam integration at 10-20 MW scale present acquisition targets with defensible technology moats. Long-term viability over the next decade hinges on methanation catalyst regeneration cycles extending revenue timing beyond electrolysis replacement windows. Watch for TTF price stabilization as inflection indicator for synthetic methane offtake contract security.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Gigawatt-scale electrolyzer factories in Norway and Germany anchor automated PEM stack manufacturing scale. |
| Backward Integration | Captive iridium and platinum group metal sourcing from South African suppliers reduces geopolitical procurement risk. |
| Technology Licensing | Solid oxide electrolysis patents licensed to Swedish steelmakers validate thermal efficiency against alkaline alternatives. |
| Long-term Supply Agreement | 15-year hydrogen offtake contracts with BASF in Ludwigshafen secure project bankability for multi-hundred-megawatt installations. |
| Green Certification Program | Automated carbon intensity tracking modules embedded in German electrolyzer designs satisfy incoming CSRD reporting obligations. |
Research Methodology
A spread of perspectives from utility planning officers, electrolyzer procurement leads at chemical manufacturers, EPC contractors with grid interconnection expertise, and solid oxide R&D directors converged on the working assumptions underlying capacity deployment timelines. Primary fieldwork combined structured interviews with secondary validation against EIA data, IEA hydrogen reports, FERC filings for grid interconnection queues, and project development databases tracking electrolyzer commissioning schedules. Bottom-up electrolyzer shipment tallies and top-down REPowerEU mandate trajectories were triangulated to anchor volume estimates.
Demand-supply-balance framing modeled electrolyzer procurement cycles against manufacturing capacity expansion announcements across the analysis window. Segmentation dimensions included conversion technology type, end-use application, installation configuration, and regional regulatory cluster. CAGRs were derived from electrolyzer deployment trajectories mandated under EU Green Deal frameworks and validated against industrial feedstock retrofit timelines. Forecast inputs incorporated TTF price volatility scenarios and pressure vessel certification cycle durations under PED compliance.
Macroeconomic conditions sit as an overlay; deviation in renewable electricity curtailment rates, natural gas price volatility, or critical mineral export restrictions would shift the trajectory of synthetic methane cost competitiveness. Cross-checking against ENTSOG hydrogen infrastructure development benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Heating Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Point Absorber Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Solar EPC Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market