
 Philippines Wind Energy Market | 2026-2036
Philippines Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Wind Energy Market Analytics
Power purchase agreement channels is tilting toward competitive green energy auctions and direct corporate offtake. ACEN Corporation leverages its renewable portfolio to secure auction slots across Luzon and Mindoro. Aboitiz Power Corporation anchors its position through integrated generation and distribution control in key franchise areas. Copenhagen Infrastructure Partners competes with long-dated capital structures suited to multi-gigawatt offshore pipelines.
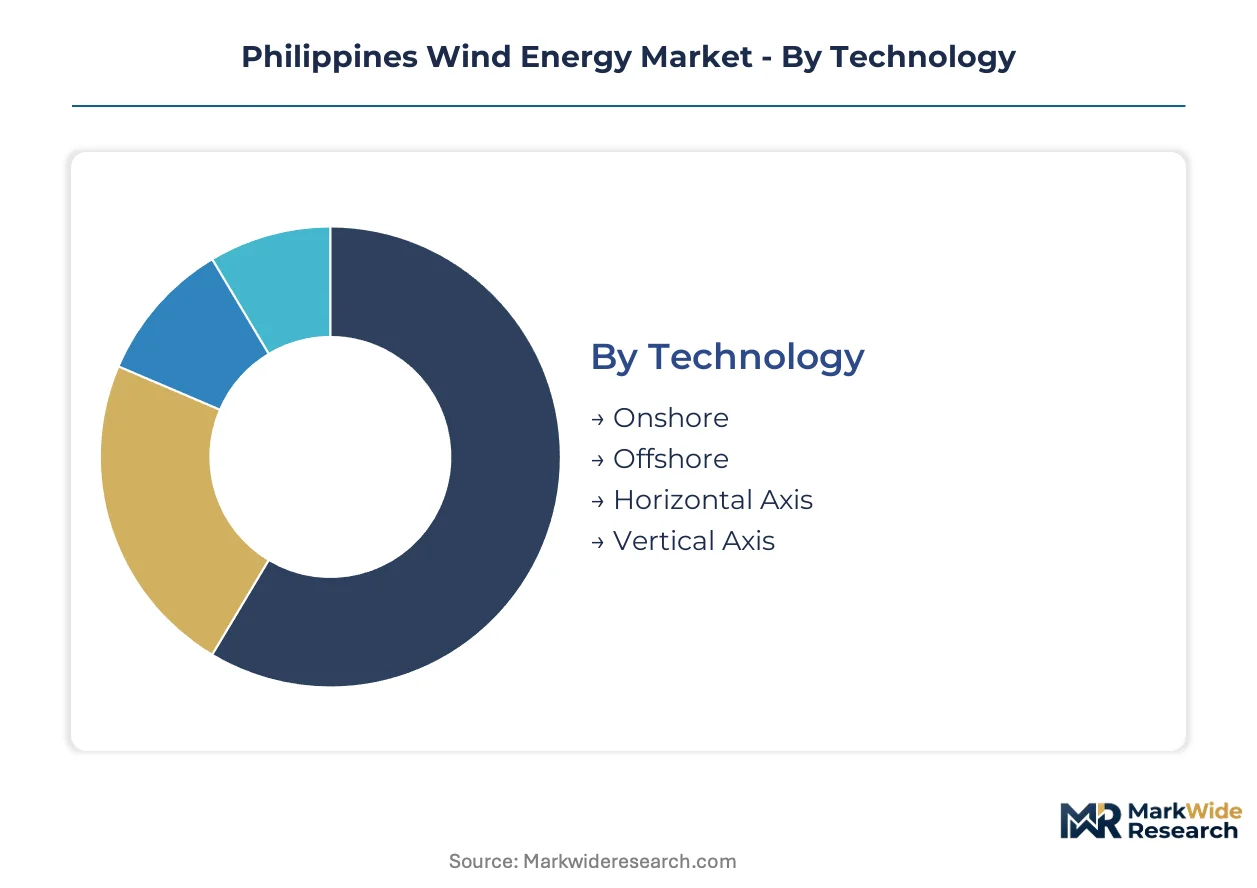
Philippines wind energy encompasses turbine-based systems converting kinetic wind flow into grid-synchronized electricity, typically employing horizontal-axis rotors with 80-120 meter hub heights and 2-5 MW unit ratings for utility-scale deployment. Onshore installations dominate current capacity, while offshore technology represents the fastest-expanding segment as water-depth-appropriate foundations mature. Utility-scale application leads by megawatt contribution, though corporate offtake structures are deepening the end-user pool beyond traditional utilities.
The Department of Energy administers green energy auctions under the Renewable Energy Act, while the Energy Regulatory Commission sets transmission access and wheeling charges that shape project economics. Grid interconnection standards from the National Grid Corporation impose technical compliance burdens that filter developer capability. Stakeholders must monitor auction schedule density against transmission buildout timelines to calibrate development pacing.
Market Dynamics
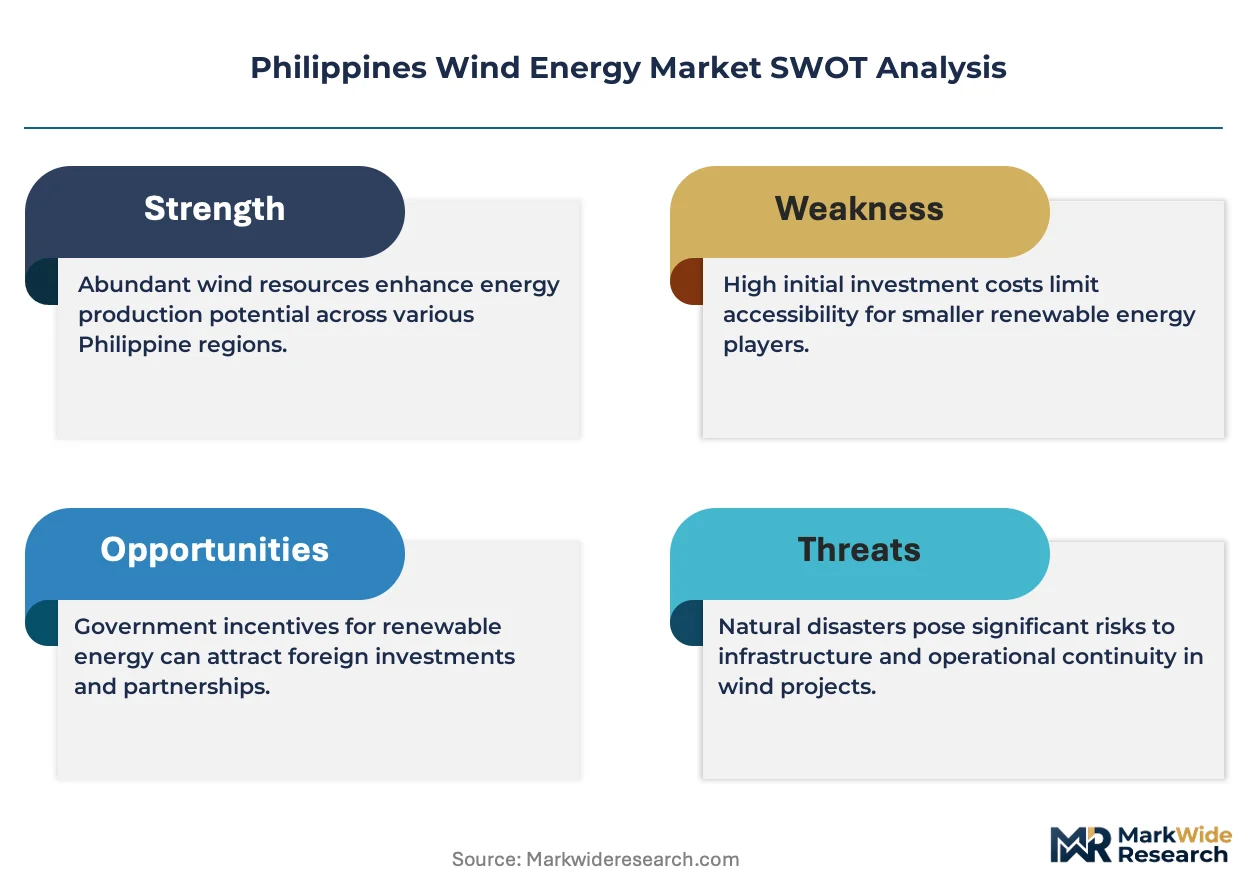
Feed-in tariff phase-out is compressing developer returns and forcing auction-based procurement models across the Philippine archipelago. The Department of Energy's green energy auction program now dictates project viability timelines.
Growth Catalysts
- Green Energy Auction Program:The Department of Energy's competitive procurement mechanism guarantees offtake prices for winning bids, de-risking capital deployment for Luzon and Visayas grid connections.
- Ilocos Norte wind corridor:Consistent 7-9 m/s average wind speeds and existing transmission infrastructure attract utility-scale development clusters with lower per-megawatt balance-of-plant costs.
- Corporate renewable energy supply contracts:Open access retail rules enable direct power purchase agreements between wind farms and large commercial offtakers, bypassing traditional utility intermediaries.
Market Restraints
- Grid interconnection queuing:National Grid Corporation of the Philippines transmission upgrade timelines lag project development schedules, creating connection backlogs in northern Luzon.
- Specialized vessel scarcity:Domestic jack-up barge and heavy-lift marine equipment availability constrains offshore foundation installation windows during monsoon-safe periods.
- Lithium-ion battery price volatility:Co-located storage project economics fluctuate with imported cell costs, complicating hybrid wind-plus-storage financing structures.
Strategic Opportunities
- Mindoro offshore zone:Unleased seabed leases in the Verde Island Passage corridor offer untapped capacity for floating foundation pilots as water depths exceed fixed-bottom viability.
- Green hydrogen offtake:Ammonia and e-fuel export demand from Japanese and South Korean industrial buyers creates anchor demand for surplus wind generation beyond grid absorption.
- Repowering early turbines:First-generation 1.5 MW units installed in Bangui and Burgos reach end-of-design-life, opening retrofit opportunities with 4-5 MW class machines on existing access roads and grid taps.
Industry Challenges
- Geotechnical survey capacity:Limited domestic offshore soil investigation vessel availability forces reliance on foreign contractors, extending pre-construction timelines by 8-14 months.
- Metocean data gaps:Sparse long-term wave and current measurement stations in proposed offshore lease blocks increase design uncertainty and lender risk premium requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Wind Energy Market |
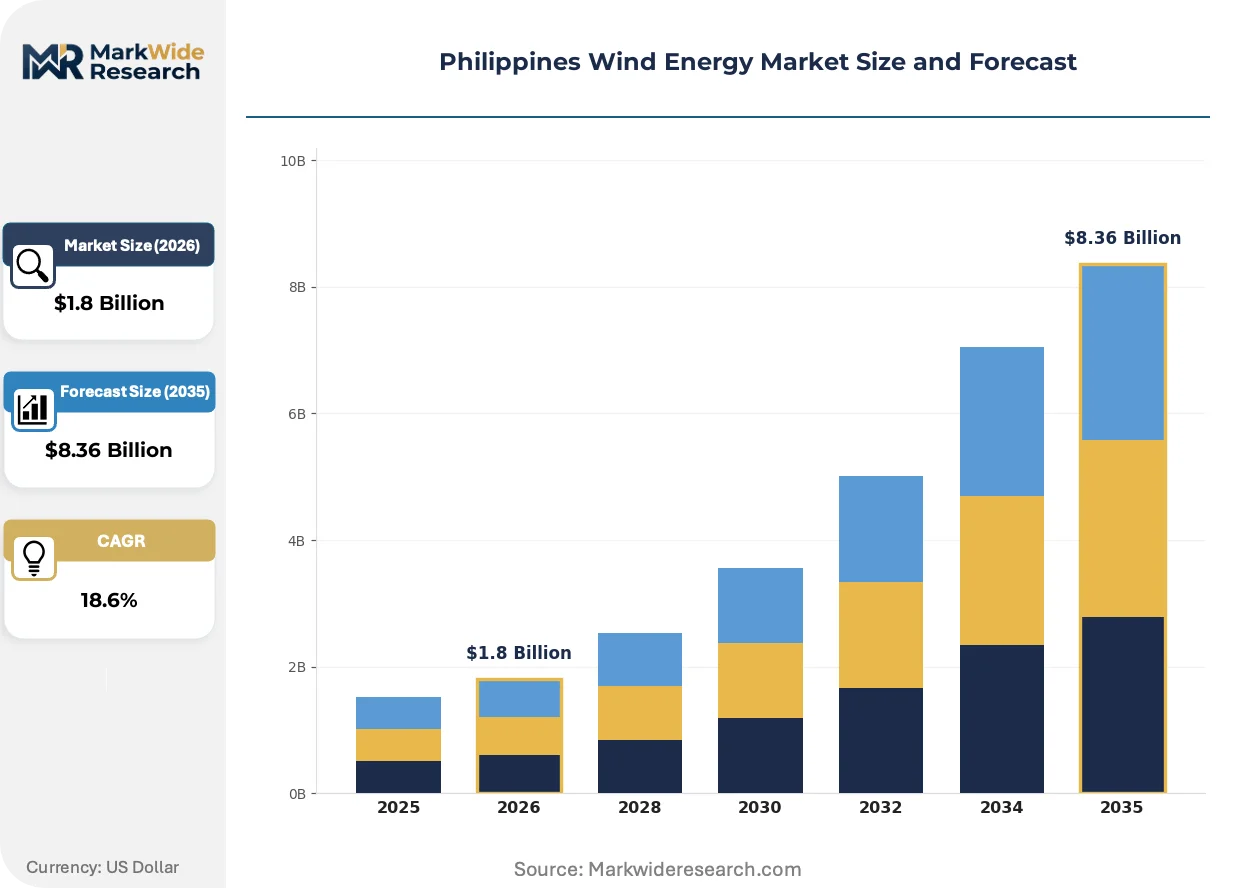
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Horizontal Axis, Vertical Axis Application: Utility-Scale, Commercial, Residential, Hybrid Installation: Fixed, Floating, Ground-Mounted, Rooftop End User: Utilities, Independent Power Producers, Corporates, Governments |
| Companies Covered | Copenhagen Infrastructure Partners, Alternergy Holdings Corporation, ACEN Corporation, Vestas Wind Systems, Siemens Gamesa Renewable Energy, Aboitiz Power Corporation, BlueFloat Energy, PetroGreen Energy Corporation, Vena Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Wind Energy Market Evolving Landscape
Digitalization of turbine operations is reshaping maintenance economics and availability guarantees across Philippine wind portfolios. Remote monitoring platforms now displace scheduled technician visits.
Advanced SCADA analytics platforms are virtualizing condition-based maintenance protocols for gearbox and generator components. ACEN Corporation and Aboitiz Power deploy these systems across their Luzon fleets, compressing unplanned outage detection from weeks to hours. This virtualization is reducing technician dispatch frequency and enabling longer service intervals without availability penalties.
The Renewable Energy Act's feed-in tariff mechanism is transitioning to pure competitive auction structures, eliminating guaranteed price premiums for new entrants. Developers must now underwrite merchant price exposure or secure corporate offtake contracts prior to financial close. Northern Luzon projects face the steepest adjustment as the earliest FiT allocations expire.
Corporate buyers are consolidating renewable energy procurement through aggregated open access structures rather than individual bilateral contracts. Manufacturing facilities in Cavite and Laguna industrial zones pool demand to anchor larger wind farm investments. This concentration is visible in the Batangas corridor where multiple food processing and electronics assembly plants negotiate joint supply agreements.
Philippines Wind Energy Market Segmentation
Technology choices in Philippine wind development lock in 20-25 year asset lifecycles, while application and end-user segments cycle faster as procurement rules shift. Understanding these velocity differences helps calibrate capital deployment timing against policy windows.
Technology:
Cycle times diverge sharply: turbine hardware platforms refresh every 7-10 years while foundation concepts evolve over 15-20 year arcs.
- Onshore:Horizontal-axis turbines with 80-120 meter hub heights and 2-5 MW unit ratings dominate Luzon and Mindoro deployments. Fixed-bottom foundations and established grid interconnection protocols compress development timelines to 3-4 years in Ilocos Norte and northern Luzon corridors.
- Offshore:Water-depth-appropriate foundation technology—fixed monopiles in sub-30 meter zones and floating platforms in deeper Verde Island Passage waters—requires specialized installation vessels and extended environmental permitting. Bureau of Fisheries and Aquatic Resources coastal zone clearances add 18-24 months to pre-construction schedules.
- Horizontal Axis:Upwind rotor configuration with three blades captures prevailing northeast monsoon flows most efficiently. Gearbox and drivetrain designs from Vestas and Siemens Gamesa units installed at Bangui and Burgos establish performance benchmarks for new projects.
- Vertical Axis:Darrieus and Savonius designs suit distributed applications with lower wind speed requirements. Limited utility-scale deployment in the Philippine archipelago restricts supply chain maturity and O&M technician training infrastructure.
Onshore dominates installed base. Offshore is where expansion concentrates.
Application:
Procurement channel economics separate segments: auction-guaranteed offtake versus merchant exposure versus behind-the-meter self-supply.
- Utility-Scale:Grid-connected wind farms above 50 MW capacity serving National Grid Corporation transmission networks. Green Energy Auction Program slots and feed-in tariff legacy contracts anchor revenue certainty for Luzon and Visayas projects.
- Commercial:Open access retail structures enable direct power purchase agreements between 5-50 MW installations and manufacturing facilities in Cavite, Laguna, and Batangas industrial zones. Aggregated demand pools from food processing and electronics assembly plants reshape project finance structures.
- Residential:Small-scale turbines below 100 kW serve off-grid island communities in Palawan and Mindanao. Hybrid solar-wind-battery configurations address diesel displacement goals in areas beyond National Grid Corporation reach.
- Hybrid:Co-located wind-plus-solar or wind-plus-storage configurations optimize transmission utilization and firm capacity contributions. Lithium-ion battery price volatility complicates financing structures for these configurations.
Utility-scale commands megawatt contribution leadership. Commercial is gaining share fastest as open access rules mature.
Installation:
Foundation type determines both capital intensity and the seasonal installation windows constrained by monsoon patterns.
- Fixed:Monopile and jacket foundations anchored to seabed or bedrock suit water depths below 50 meters. Geotechnical survey vessel scarcity from domestic contractors extends pre-construction timelines.
- Floating:Semi-submersible and tension-leg platforms enable deployment in Verde Island Passage zones exceeding 60 meter depths. Mooring system designs from European suppliers dominate pilot project specifications.
- Ground-Mounted:Tubular steel towers on concrete pad foundations standard for onshore utility-scale arrays. Existing access roads and grid taps at Bangui and Burgos sites enable repowering retrofits.
- Rooftop:Small turbines integrated into commercial and industrial building structures. Urban wind resource limitations and zoning restrictions constrain deployment scale.
Ground-mounted anchors current capacity. Floating foundations represent the steepest expansion trajectory as seabed leases in deeper waters advance.
End User:
Counterparty credit quality and offtake duration differentiate procurement risk profiles across buyer categories.
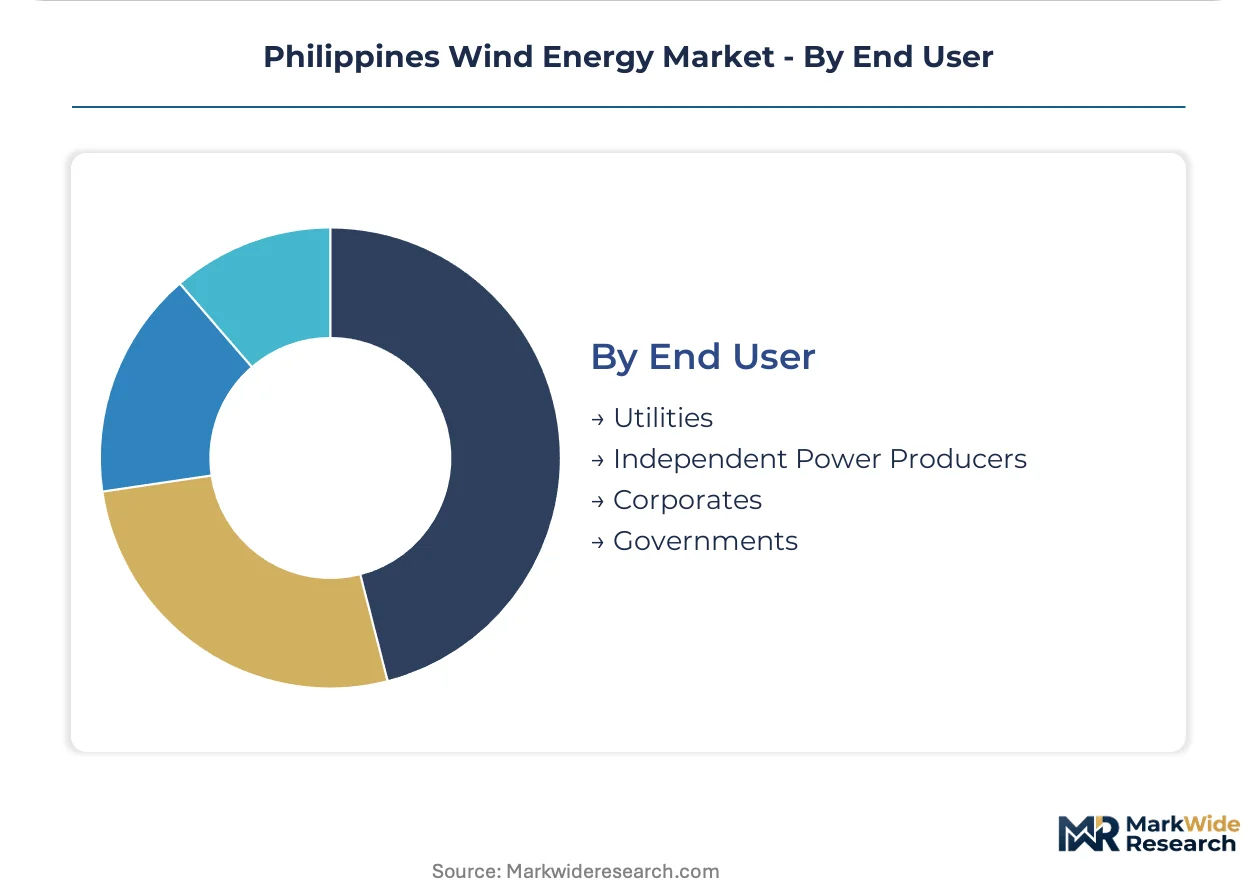
- Utilities:Manila Electric Company and Visayan Electric Company anchor demand through long-term power supply agreements. Distribution utility franchise areas concentrate procurement in Luzon and Visayas load centers.
- Independent Power Producers:ACEN Corporation and Aboitiz Power Corporation develop merchant and contracted capacity across integrated generation portfolios. Auction slot capture and corporate offtake origination capabilities separate competitive positioning.
- Corporates:Manufacturing and data center operators in CALABARzon and Central Luzon pursue renewable energy supply contracts for scope 2 emissions targets. Aggregated procurement structures pool demand to anchor larger wind farm investments.
- Governments:Department of Energy rural electrification programs and local government unit initiatives support off-grid and missionary electrification projects. National Electrification Administration financing structures shape deployment economics.
Utilities dominate contracted capacity. Corporates are climbing the fastest as open access retail rules deepen the end-user pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in northern Luzon wind corridors while southern Mindanao projects absorb higher transmission wheeling charges. Ilocos Norte and Cagayan Valley zones command development premiums from verified wind resource data and existing grid infrastructure. Southern interconnection backlogs compress returns in Mindoro and Palawan zones.
Ilocos Norte
Bangui and Burgos host the country's oldest utility-scale installations with repowering cycles now underway. The Department of Energy green energy auction program prioritizes grid-ready sites with verified resource assessments. ACEN Corporation and Alternergy Holdings Corporation anchor development clusters along the Laoag-Cagayan transmission backbone.
Cagayan Valley
Untapped ridgeline resources in Isabela and Cagayan provinces attract greenfield auction bids. National Grid Corporation transmission expansion timelines determine project sequencing. Copenhagen Infrastructure Partners evaluates seabed leases in the Babuyan Channel corridor for fixed-bottom foundation deployment.
Batangas-Cavite Corridor
Corporate open access demand from CALABARzon manufacturing zones drives commercial-scale procurement. The Energy Regulatory Commission wheeling charge structures shape bilateral power purchase agreement economics. PetroGreen Energy Corporation and Aboitiz Power Corporation compete for aggregated offtake pools from electronics and food processing facilities.
Mindoro Offshore Zone
Verde Island Passage water depths exceed fixed-bottom viability, requiring floating foundation pilots. Bureau of Fisheries and Aquatic Resources coastal zone clearances extend pre-construction timelines. BlueFloat Energy and Vena Energy hold seabed lease applications for semi-submersible platform deployment.
Visayas Grid
Guimaras and Negros Occidental zones offer lower wind speeds but reduced grid congestion. Visayan Electric Company distribution utility procurement anchors demand visibility. Vestas Wind Systems and Siemens Gamesa Renewable Energy supply turbine platforms for hybrid wind-solar configurations.
Philippines Wind Energy Market Competitive Landscape
Integrated Philippine conglomerates and specialized offshore developers split the market into distinct capability tiers. The competitive structure concentrates around auction slot capture and transmission interconnection queue positioning. Domestic holding companies with distribution franchise control and European infrastructure funds with long-dated capital represent the dominant archetypes. Competitive moves center on green energy auction pre-qualification and seabed lease aggregation.
Within the integrated conglomerate tier, ACEN Corporation and Aboitiz Power Corporation exemplify developers combining generation assets with distribution utility relationships. Copenhagen Infrastructure Partners anchors the offshore-focused capital deployment segment with multi-gigawatt pipeline structures. Vestas Wind Systems and Siemens Gamesa Renewable Energy occupy the turbine supply and service provider position, delivering hardware platforms across both onshore and emerging offshore configurations.
| Leading Market Players |
|---|
| Copenhagen Infrastructure Partners |
| Alternergy Holdings Corporation |
| ACEN Corporation |
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| Aboitiz Power Corporation |
| BlueFloat Energy |
| PetroGreen Energy Corporation |
| Vena Energy |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic jack-up barge availability concentrates pricing power among foreign marine contractors during monsoon-safe installation windows, forcing developers to absorb premium day-rates or compress construction schedules. This utilization squeeze propagates through turbine supply agreements and foundation procurement, elevating capital costs for offshore projects against onshore benchmarks.
Pricing Analysis
Configured-to-order pricing for floating foundation platforms commands spreads against standard fixed-bottom designs reflecting water-depth engineering complexity and European mooring system imports. Auction-guaranteed offtake prices under the Department of Energy's green energy auction program anchor utility-scale revenue certainty, while merchant-exposed projects face price softness from corporate offtake negotiation leverage. Price differentiation hinges on grid interconnection queue position and Bureau of Fisheries coastal clearance status. Distribution utilities exhibit lowest price sensitivity given franchise area captive demand; independent power producers face highest sensitivity from auction bid compression.
Supply Chain Analysis
Tariff exposure between China and the Philippines dominates nacelle and blade import economics, with Siemens Gamesa and Vestas manufacturing footprints in Tianjin and Shanghai feeding Philippine project pipelines. The supply chain draws from Denmark for floating platform designs, Spain for specialized installation vessels, and South Korea for high-voltage submarine cable. Single-source vulnerability concentrates in geotechnical survey vessel contracting, where domestic capacity gaps force 8-14 month foreign contractor lead times. Distribution runs through engineering-procurement-construction consortia led by ACEN Corporation and Aboitiz Power Corporation integrated teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines wind energy market is cycling through feed-in tariff expiration recovery, with auction-based procurement resetting developer return thresholds. Green energy auction schedule density serves as the cyclical driver pacing capital deployment windows.
For Market Incumbents: Harden auction slot positioning through pre-qualified seabed lease aggregation in Verde Island Passage corridors ahead of floating foundation technology maturation. Secure transmission interconnection queue priority by co-locating with National Grid Corporation upgrade timelines in Ilocos Norte and Cagayan Valley. Defend against corporate offtake poaching by integrating behind-the-meter solutions for CALABARzon manufacturing clusters.
For New Entrants and Emerging Players: Pursue Mindoro offshore zone entry through joint venture structures with European floating platform technology licensors, leveraging BlueFloat Energy and Vena Energy lease application precedents. Target repowering retrofit opportunities at Bangui and Burgos where first-generation turbine end-of-design-life creates equipment swap demand. Penetrate via aggregated open access procurement pools serving Cavite and Laguna electronics assembly plants.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across offshore floating foundation deployments, favoring long-dated capital structures over traditional project finance. Five-to-ten year viability hinges on Bureau of Fisheries coastal clearance timeline compression and metocean data station deployment density. Acquisition target archetype: integrated developers with distribution utility relationships and green energy auction pre-qualification status. Signal to monitor: National Grid Corporation transmission expansion commitment announcements for northern Luzon corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Energy Auction Slot Capture | Department of Energy guaranteed offtake prices de-risk capital deployment for Luzon grid connections. |
| Floating Foundation Technology Licensing | European mooring system suppliers enable Verde Island Passage deployment in 60-meter water depths. |
| Corporate Offtake Aggregation | Pooled demand from Cavite and Laguna manufacturing plants anchors larger wind farm investments. |
| Transmission Interconnection Queue Positioning | National Grid Corporation upgrade timeline alignment determines project sequencing economics. |
| Repowering Retrofit Execution | Bangui and Burgos existing grid taps enable 4-5 MW class turbine swaps on established access roads. |
Research Methodology
A spread of perspectives from utility planning officers, independent power producer project developers, engineering-procurement-construction contractors, and National Grid Corporation interconnection specialists converged on the working assumptions. Primary interview intelligence combined with secondary validation from Department of Energy auction announcements, Energy Regulatory Commission wheeling charge determinations, and Bureau of Fisheries coastal zone clearance databases. Bottom-up project pipeline aggregation triangulated against top-down renewable energy target allocations from the National Renewable Energy Program.
Demand-supply balance modeling across the projection horizon incorporated green energy auction slot density, transmission buildout timelines, and corporate offtake origination velocity. Segmentation dimensions spanned technology platform, application scale, foundation type, and end-user counterparty category. CAGRs derived from capacity installation run-rates against auction award schedules and seabed lease progression timelines. Forecast inputs included monsoon-safe installation window constraints and lithium-ion battery price trajectory assumptions for hybrid configurations.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates and imported steel tariffs would shift the trajectory. Forecasts reflect documented assumptions on auction participation rates and transmission commissioning schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Rectenna Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Marine Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Nigeria Renewable Energy Market