
 Philippines Power Market | 2026-2036
Philippines Power Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Power Market Analytics
Natural gas is restructuring power economics across the Philippine archipelago as coal retirements accelerate under Department of Energy policy guidance. San Miguel Corporation leverages its integrated LNG terminal and power plant complex in Batangas to dominate gas-to-power value capture. First Gen Corporation anchors its portfolio with geothermal and natural gas baseload assets across Luzon. ACEN Corporation specializes in utility-scale solar and wind development, positioning its pipeline to capture renewable energy certificate premiums.
Philippines Power encompasses electricity generation, transmission, distribution, and retail sale across a fragmented archipelagic grid spanning over 7,600 islands. The system operates at 60 Hz with 230 kV backbone transmission serving Luzon, Visayas, and Mindanao through limited interconnection capacity. Thermal power sources still occupy the largest share of installed capacity, though renewable segments are expanding fastest as feed-in-tariff obligations and green energy auction mechanisms redirect capital. Smart grid technology leads investment intensity among technology segments, driven by distribution utilities' need to manage distributed solar penetration and reduce system losses. Energy storage applications concentrate at substations serving industrial parks in CALABARZON where voltage regulation challenges persist.
The Department of Energy enforces the Renewable Portfolio Standard requiring distribution utilities to source increasing shares from eligible renewable facilities. ERC rate-setting methodologies shape utility returns while the Philippine Grid Code and Distribution Code establish technical interconnection standards. Stakeholders must monitor how the Green Energy Auction Program reserve prices interact with LNG import cost volatility to determine future capacity mix decisions.
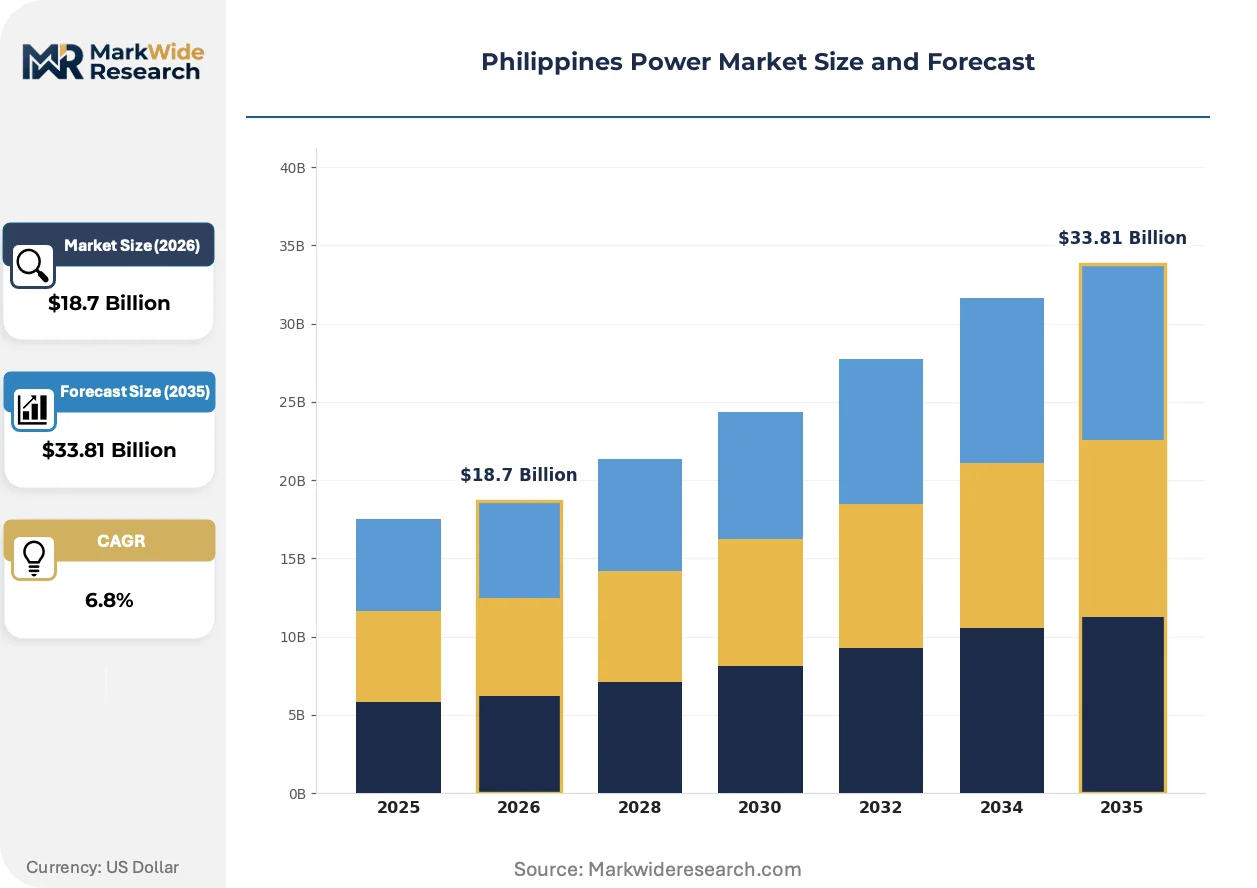
Market Dynamics
The Philippines Power Market is restructuring around the Department of Energy's Renewable Portfolio Standard mandates as coal retirement timelines compress and LNG import dependency reshapes baseload economics across the archipelago.
Growth Catalysts
- Renewable Portfolio Standard:The Department of Energy mandates distribution utilities to source escalating shares from eligible renewable facilities, redirecting procurement toward solar and geothermal developers.
- Luzon grid congestion:Distribution utilities facing transmission bottlenecks accelerate distributed solar PV and battery storage combinations to defer substation upgrades.
- Green Energy Auction Program:Reserve price mechanisms under this framework provide revenue certainty for utility-scale wind and solar projects competing against imported LNG volatility.
Market Restraints
- LNG price volatility:Spot cargo costs for liquefied natural gas expose gas-fired plant operators to margin compression when global supply tightens.
- Inter-island transmission gaps:Limited submarine cable capacity between Luzon, Visayas, and Mindanao isolates resource-rich regions from demand centers.
- Land acquisition friction:Utility-scale solar developers encounter right-of-way disputes in CALABARZON industrial zones where land values have escalated.
Strategic Opportunities
- Mindanao geothermal expansion:Untapped high-enthalpy resources in Mount Apo and Leyte provinces offer baseload renewable capacity with minimal storage requirements.
- Net metering aggregation:Commercial and industrial rooftop solar installations across Cebu and Batangas can pool excess generation for virtual power plant participation.
- Smart grid deployment:Advanced metering infrastructure and distribution automation systems address system loss reduction mandates from the Energy Regulatory Commission.
Industry Challenges
- Grid integration complexity:Variable renewable penetration strains the Philippine Grid Code's frequency regulation standards, requiring synchronous condenser investments.
- Permitting timeline compression:Environmental compliance certificates from the Department of Environment and Natural Resources face multi-year queues for transmission corridor approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Power Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Thermal, Hydropower, Renewable, Natural Gas Application: Industrial, Commercial, Residential, Utilities Technology: Smart Grid, Energy Storage, Transmission, Distribution End User: Manufacturers, Residents, Government Bodies, Power Distributors |
| Companies Covered | Manila Electric Company (Meralco), Meralco Power Generation, San Miguel Corporation, Prime Energy, China Renewable Energy Corporation (CREC), Aboitiz Power, ACEN Corporation, UC38 LLC, First Gen Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Power Market Evolving Landscape
Battery storage integration is accelerating across the Philippine archipelago as distribution utilities confront renewable intermittency and transmission congestion simultaneously.
Solar-plus-storage hybrid configurations are electrifying the investment calculus for industrial offtakers in Batangas and Cebu. Manufacturing facilities with 24-hour operations deploy lithium-ion battery systems sized for 4-6 hour discharge durations to flatten renewable generation curves. This pairing is electrifying the shift from diesel backup reliance toward firm renewable supply contracts that satisfy corporate sustainability commitments.
The Department of Energy's Green Energy Auction Program is restructuring capacity procurement rules for distribution utilities. Winning bidders secure 20-year offtake agreements at administratively set reserve prices, displacing previous bilateral negotiation frameworks. Luzon-based electric cooperatives are responding by consolidating demand pools to achieve scale thresholds required for auction participation.
Captive power arrangements are expanding among energy-intensive manufacturers seeking supply security beyond utility-delivered electrons. Cement and semiconductor plants in CALABARZON industrial parks negotiate direct connections to embedded generation assets, bypassing distribution utility wheeling charges. This behavioral pivot is most visible in Batangas where LNG terminal proximity enables gas-fired self-generation with lower delivered energy costs than grid alternatives.
Philippines Power Market Segmentation
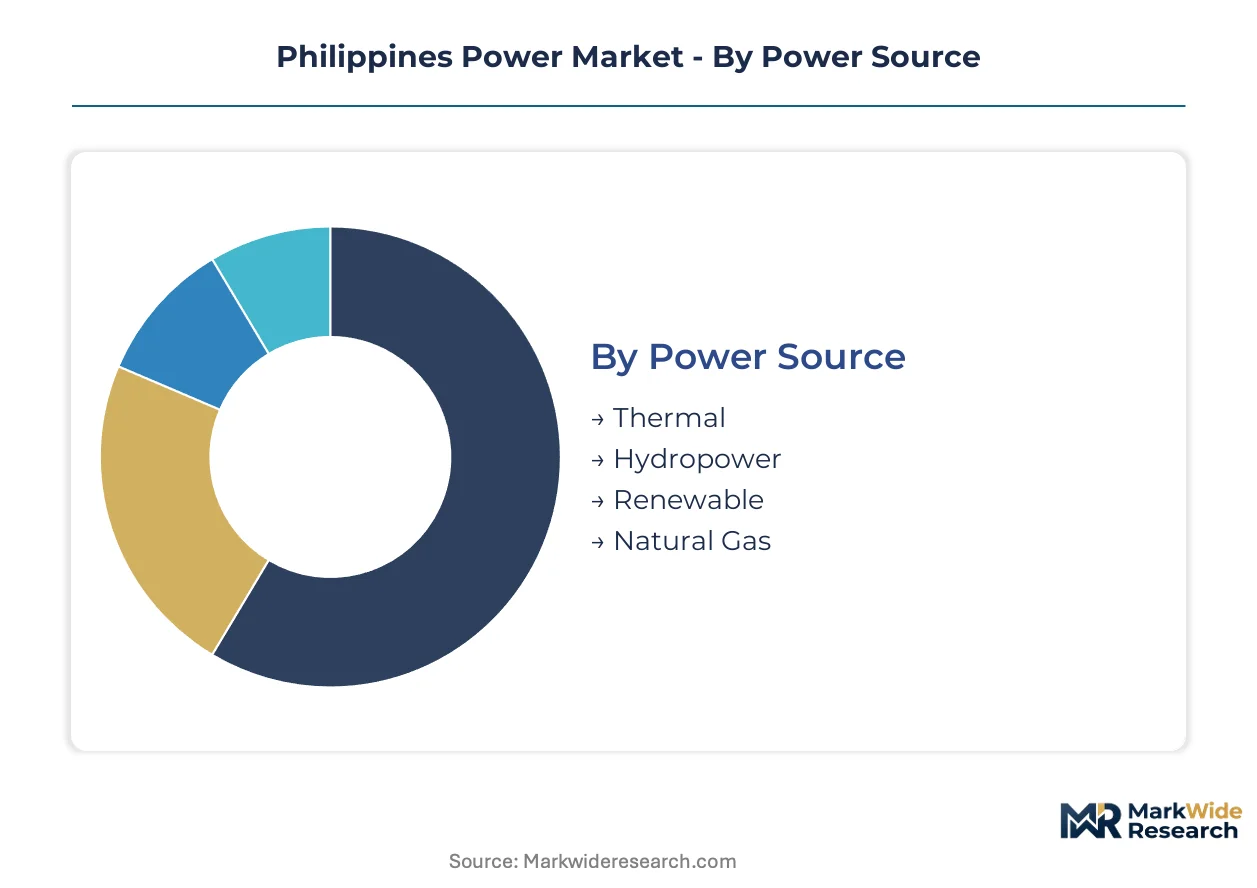
Segmentation reveals how capital allocation priorities diverge across the Philippine archipelago's fragmented grid structure. Procurement patterns split between baseload security and distributed renewable integration, with each segment commanding distinct technology stacks and regulatory navigation.
Power Source:
Standardized baseload contracts dominate the high-volume end, while customized renewable hybrids capture premium pricing through feed-in-tariff eligibility.
- Thermal:Coal-fired plants still anchor Luzon baseload capacity despite Department of Energy retirement mandates accelerating. Batangas and Quezon provinces concentrate remaining fleet operations where existing transmission infrastructure supports bulk dispatch.
- Renewable:Utility-scale solar and onshore wind installations exploit Green Energy Auction Program reserve prices. Developers in Ilocos Norte and Mindoro prioritize sites with simultaneous grid access and land availability.
- Natural Gas:Combined-cycle gas turbines at First Gen and San Miguel facilities provide mid-merit flexibility. LNG import dependency at Batangas terminal shapes dispatch economics against volatile spot cargo pricing.
- Hydropower:Run-of-river schemes in Mindanao supply peaking reserves with minimal storage requirements.
Leading the category by volume: Thermal. Growing fastest: Renewable.
Application:
Volume concentrates in continuous-process loads, while margin accumulates in interruptible commercial contracts with demand-response eligibility.
- Industrial:Cement, semiconductor, and food processing facilities in CALABARZON and Cebu operate 24-hour loads requiring firm supply contracts. Captive power arrangements bypass distribution utility wheeling charges where LNG terminal proximity enables gas-fired self-generation.
- Utilities:Electric cooperatives and private distribution utilities consolidate procurement through Green Energy Auction Program participation. Scale thresholds force Luzon-based cooperatives into demand pooling arrangements.
- Commercial:Shopping malls and data centers in Metro Manila deploy rooftop solar with net metering aggregation.
- Residential:Household consumption spreads across franchise areas with varying reliability profiles.
Dominant by load factor: Industrial. Expanding most quickly: Utilities.
Technology:
Mature transmission hardware commands commodity pricing, while smart grid deployments capture regulatory premiums through system loss reduction mandates.
- Smart Grid:Advanced metering infrastructure and distribution automation systems address Energy Regulatory Commission loss reduction targets. Meralco and Visayan Electric deploy AMI across high-theft distribution circuits.
- Energy Storage:Lithium-ion battery systems sized for 4-6 hour discharge durations flatten solar generation curves. Industrial parks in Batangas and CALABARZON concentrate substation-scale installations.
- Distribution:Medium-voltage network upgrades reduce technical losses in franchise areas with aging infrastructure.
- Transmission:230 kV backbone expansions face multi-year environmental compliance certificate queues.
Highest deployment intensity: Smart Grid. Steepest expansion trajectory: Energy Storage.
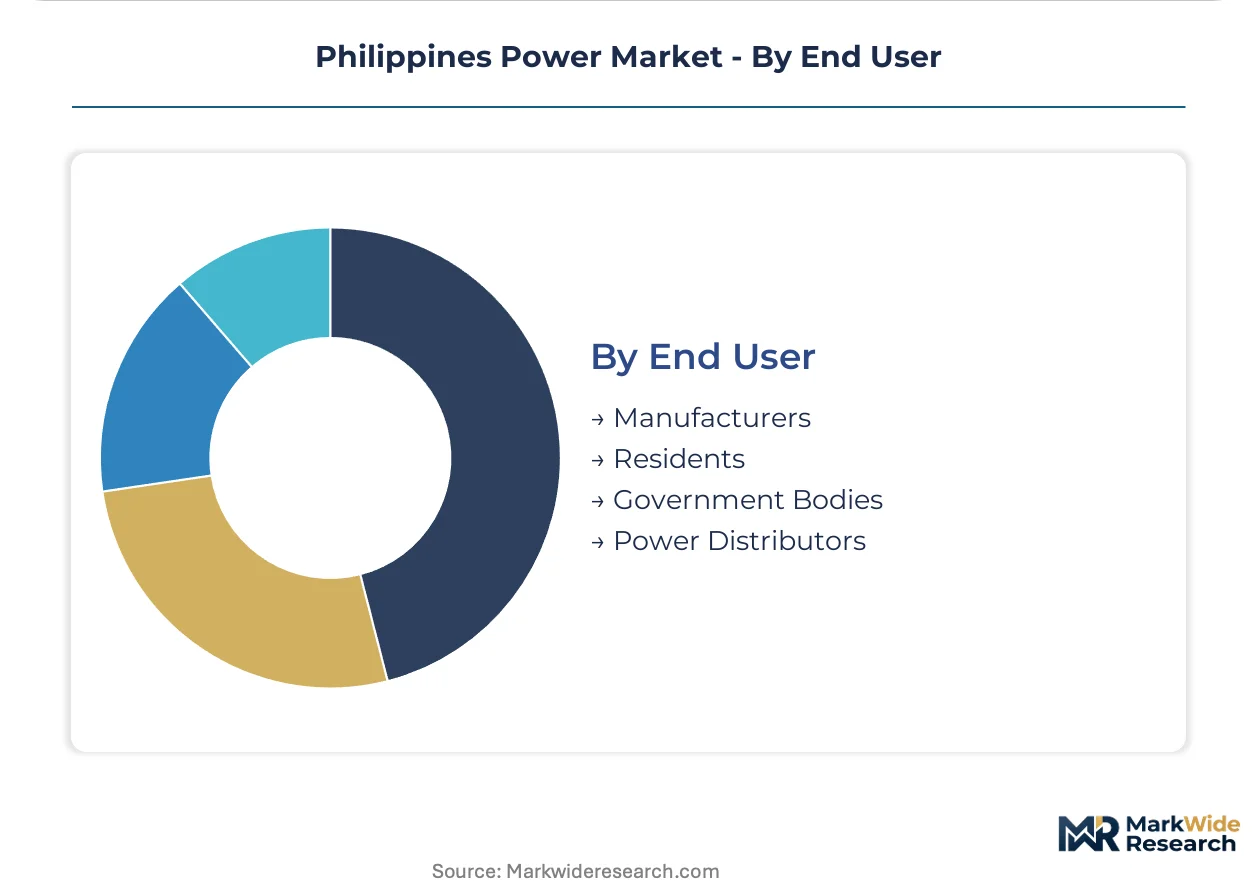
End User:
Procurement sophistication stratifies between price-taking residential accounts and actively hedging industrial offtakers with captive generation options.
- Power Distributors:Meralco, Visayan Electric, and electric cooperatives manage Renewable Portfolio Standard compliance obligations. Green Energy Auction Program participation requires consolidated demand pools.
- Manufacturers:Energy-intensive plants negotiate direct embedded generation connections. Semiconductor and cement facilities in Batangas leverage LNG terminal proximity for gas-fired self-supply.
- Government Bodies:National Electrification Administration and Department of Energy shape procurement rules through auction mechanisms and net metering frameworks.
- Residents:Household consumers face tiered tariff structures with cross-subsidy elements.
Largest procurement volume: Power Distributors. Gaining negotiating leverage fastest: Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power demand concentrates in Luzon's industrial corridors where semiconductor and cement facilities operate continuous loads. The Philippine archipelago's fragmented grid structure creates distinct procurement dynamics across major island groups. Department of Energy mandates reshape investment flows differently in each sub-region.
Luzon
Metro Manila and CALABARZON industrial zones anchor national electricity consumption with 24-hour manufacturing loads. The Department of Energy's Renewable Portfolio Standard forces Meralco and electric cooperatives to source escalating renewable shares. Batangas LNG terminal proximity enables gas-fired captive power at petrochemical and semiconductor clusters.
Visayas
Cebu-based food processing and business process outsourcing facilities drive commercial load growth across the central island group. Net metering rules accelerate rooftop solar deployment on shopping malls and hotels. Negros Island's sugar milling biomass plants feed into distribution utility portfolios under feed-in-tariff eligibility.
Mindanao
Mount Apo geothermal fields supply baseload capacity to Davao City's agro-industrial processing plants. The National Grid Corporation's limited submarine cable capacity isolates the southern island from Luzon-Visayas price arbitrage. Run-of-river hydropower in Bukidnon and Lanao provinces serves peaking requirements for nickel mining operations.
Palawan and Mindoro
Off-grid island provinces rely on diesel-battery microgrids serving tourism and fishing economies. The Department of Energy's missionary electrification program funds hybrid renewable-diesel systems. Puerto Princesa's underground river tourism cluster demonstrates solar-battery mini-grid viability for remote load centers.
Bicol Region
Mayon Volcano geothermal prospects remain underexplored despite high-enthalpy resource indicators. Legazpi City's container port expansion drives demand for firm power supply. Typhoon exposure complicates transmission infrastructure planning across the Pacific-facing peninsula.
Philippines Power Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy groups controlling generation assets while distribution utilities manage last-mile access. The vendor base concentrates around three archetypes: diversified conglomerates with fuel-to-wire integration, pure-play renewable developers auctioning capacity, and captive power operators serving single industrial offtakers. Competitive positioning hardens through Green Energy Auction Program participation and LNG supply contract tenor negotiations.
Among Philippines-based integrated power groups, San Miguel Corporation, First Gen Corporation, and ACEN Corporation exemplify divergent strategic postures. San Miguel anchors gas-to-power value capture through its Batangas LNG terminal and combined-cycle plant complex. First Gen occupies the geothermal and natural gas baseload tier across Luzon transmission nodes. ACEN represents the renewable-pure archetype with utility-scale solar and wind pipelines positioned for certificate premium capture.
| Leading Market Players |
|---|
| Manila Electric Company (Meralco) |
| Meralco Power Generation |
| San Miguel Corporation |
| Prime Energy |
| China Renewable Energy Corporation (CREC) |
| Aboitiz Power |
| ACEN Corporation |
| UC38 LLC |
| First Gen Corporation |
| Others |
Value Network & Pricing Analysis
Green Energy Auction Program participation requirements are forcing Luzon electric cooperatives into demand pooling arrangements that reshape procurement scale thresholds and compress margins for smaller distribution utilities unable to meet minimum bid volumes.
Pricing Analysis
Volume concentrates in long-term offtake contracts under administratively set reserve prices, while margin accumulates in bilateral negotiations for firm capacity during peak demand periods. Price differentiation rests on fuel source certification and grid access priority, with renewable certificate premiums commanding spreads over thermal baseload. Pricing pressure stems from LNG spot cargo volatility exposing gas-fired operators to margin compression when global supply tightens. Industrial offtakers with captive power options exhibit lowest price sensitivity, while residential consumers under tiered tariff structures face highest sensitivity to rate adjustments.
Supply Chain Analysis
Direct-to-utility channels handle bulk generation equipment procurement for Green Energy Auction Program winners, while EPC contractors manage project execution through build-own-operate structures. Geographic supply concentration centers on China for solar PV modules and lithium-ion battery cells, South Korea for combined-cycle gas turbine components, and Japan for advanced metering infrastructure. Raw material dependencies include polysilicon for photovoltaic manufacturing, nickel for battery cathodes, and LNG for thermal generation. Single-source vulnerability in semiconductor components for smart grid systems creates procurement risk. Distribution runs through integrated energy groups controlling both generation assets and terminal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines power sector is transitioning from coal-dominant baseload to renewable-hybrid firm capacity, with battery storage displacing diesel peaking plants across industrial zones.
For Market Incumbents: Anchor portfolio resilience through geothermal baseload expansion at Mount Apo and Leyte fields, where high-enthalpy resources offer synchronous stability against variable renewable penetration. Secure long-term LNG supply contracts at Batangas terminal to insulate gas-fired assets from spot market volatility. Deepen backward integration into solar module assembly to capture equipment margin and reduce import dependency exposure. For New Entrants and Emerging Players: Launch via net metering aggregation platforms serving Cebu and Batangas commercial rooftops, where regulatory frameworks now permit virtual power plant participation. Target Mindanao geothermal development permits, where environmental compliance certificate queues are shorter than Luzon transmission corridors. Pursue direct embedded generation connections with CALABARZON cement and semiconductor facilities seeking supply security beyond utility wheeling charges. For Investors and Strategic Acquirers: The window for entry favors renewable-pure developers with auction-qualified pipelines and established land access in Ilocos Norte or Mindoro. Long-term viability hinges on capturing Green Energy Auction Program reserve price premiums before distribution utility demand pools consolidate procurement scale. Watch LNG import cost spreads against auction clearing prices as the inflection signal for capacity mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Utility-scale solar and wind installations exploit Green Energy Auction Program reserve price mechanisms across Luzon grid nodes. |
| Power Purchase Agreement | Twenty-year offtake contracts provide revenue certainty for geothermal developers competing against LNG price volatility. |
| Technology Licensing | Advanced metering infrastructure deployments address Energy Regulatory Commission system loss reduction mandates for Meralco franchise areas. |
| Vertical Integration into Storage | Solar-plus-storage hybrids at Batangas industrial parks displace diesel backup reliance for continuous manufacturing loads. |
| Green Certification Program | Renewable energy certificate premiums reward ACEN Corporation and pure-play developers with feed-in-tariff eligibility. |
Research Methodology
Document review covered Department of Energy circulars, Philippine Grid Code amendments, and Green Energy Auction Program bidding documents, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from FERC-style regulatory filings, IEA country reports, EIA international energy data, and project development databases tracking capacity additions across the archipelago. Bottom-up capacity aggregation and top-down demand forecasting were triangulated to establish market sizing.
Historical capacity installation patterns were cross-referenced against panel input from distribution utility procurement officers to construct the analytical framework. Segmentation modeling incorporated power source, application type, technology deployment, and end-user category across the projection horizon. CAGRs were derived from regression analysis of installed capacity trends against policy mandate timelines and fuel price scenarios. Forecast inputs included inter-island transmission gap closure assumptions and coal retirement schedule adherence under Department of Energy guidance.
LNG import cost volatility, environmental compliance certificate approval delays, and Renewable Portfolio Standard enforcement intensity are the dominant revision risks for capacity mix projections. Forecasts reflect assumptions regarding auction participation thresholds and distribution utility consolidation behavior. Periodic stress-testing of base assumptions against spot fuel price movements and regulatory timeline shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Highway Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
China Wind Power Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Denmark Renewable Energy Market