
 Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market | 2026-2036
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market Insights
Buyer concentration among offshore wind farm operators is restructuring procurement patterns across the inspection equipment value chain. Ørsted and Equinor-scale operators now bundle blade inspections into long-term service agreements, forcing equipment vendors to adapt contract structures. DJI Enterprise leverages its matricopter platforms to dominate aerial visual surveys of leading-edge erosion. Teledyne FLIR competes through thermal-imaging payloads that detect subsurface delamination invisible to standard cameras. Eddyfi Technologies specializes in phased-array ultrasonic crawlers for high-resolution thickness mapping along the blade laminate stack.
Offshore wind turbine blade leading-edge defect inspection equipment encompasses sensor-integrated platforms and robotic systems engineered to detect erosion, cracking, and delamination on blade surfaces exposed to salt spray, hydrodynamic impact, and UV degradation; these systems operate at tip speeds exceeding 80 meters per second and must resolve defects below 0.5 millimeters to prevent catastrophic fatigue failure. Ultrasonic testing and thermographic inspection now lead product-type demand because both modalities penetrate subsurface damage zones that visual methods miss entirely. Phased-array technology captures the fastest growth trajectory within the technology dimension, displacing conventional single-element probes through faster scan speeds and beam-steering flexibility that reduce turbine downtime. Inspection service providers represent the most concentrated end-user margin pool, as they amortize equipment capital across multiple wind farm contracts and capture recurring revenue from predictive maintenance subscriptions.
FERC offshore wind siting guidelines in the United States, the EU Green Deal's renewable energy directives, and IEC 61400-23 blade measurement standards collectively mandate documented defect baselines and periodic structural audits for warranty retention and insurance compliance. These frameworks compel wind farm operators to maintain calibrated inspection records traceable to certified equipment, directly expanding the addressable market for validated inspection platforms. Stakeholders must monitor how evolving blade-length standards above 115 meters strain current robotic reach capabilities and force platform redesign cycles.
Market Dynamics
Blade length escalation beyond 115 meters is forcing inspection platform redesigns, as robotic reach limitations and aerodynamic load tolerances create bottlenecks in automated defect detection workflows.
Growth Catalysts
- EU Green Deal offshore wind mandates:The directive tightens defect-detection baselines across European waters, compelling operators to upgrade from manual visual checks to sensor-validated systems for warranty retention.
- Phased-array ultrasonic adoption:Wind farm service providers deploy beam-steering crawlers to compress inspection cycles on 100-meter-plus blades, reducing turbine downtime per sweep.
- United Kingdom capacity concentration:Ørsted-scale operators bundle long-term service agreements, aggregating equipment procurement into multi-year contracts that stabilize vendor revenue streams.
Market Restraints
- Corrosion-resistant alloy input costs:Salt-spray-rated robotic chassis require specialized marine-grade aluminum and titanium, exposing manufacturers to commodity price volatility.
- Sensor supplier concentration in East Asia:High-resolution thermal and ultrasonic transducer fabrication concentrates in South Korean and Japanese component houses, creating single-source vulnerability.
- IEC 61400-23 calibration friction:The blade measurement standard mandates traceable defect documentation, extending equipment validation timelines before commercial deployment.
Strategic Opportunities
- Floating offshore wind expansion:Denmark and Norway are deploying pre-commercial floating arrays where dynamic blade motion creates novel inspection requirements for stabilized robotic platforms.
- Thermal-ultrasonic payload convergence:Equipment vendors integrate FLIR thermal cores with phased-array probes to capture surface erosion and subsurface delamination in single passes.
- United States FERC siting compliance:Emerging offshore lease blocks in the Atlantic require documented structural baselines, opening service-provider entry points for predictive maintenance subscriptions.
Industry Challenges
- Marine robotics technician scarcity:Operators struggle to recruit engineers capable of calibrating ultrasonic crawlers and interpreting laminate-stack thickness maps in offshore conditions.
- Multi-modal certification timelines:Platforms combining aerial, surface, and subsea capabilities must satisfy FAA, maritime, and electrical safety frameworks simultaneously, delaying market entry.
- Legacy blade inventory incompatibility:First-generation offshore turbines with 75-80 meter blades lack standardized access points for automated crawler attachment, forcing manual inspection retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market |
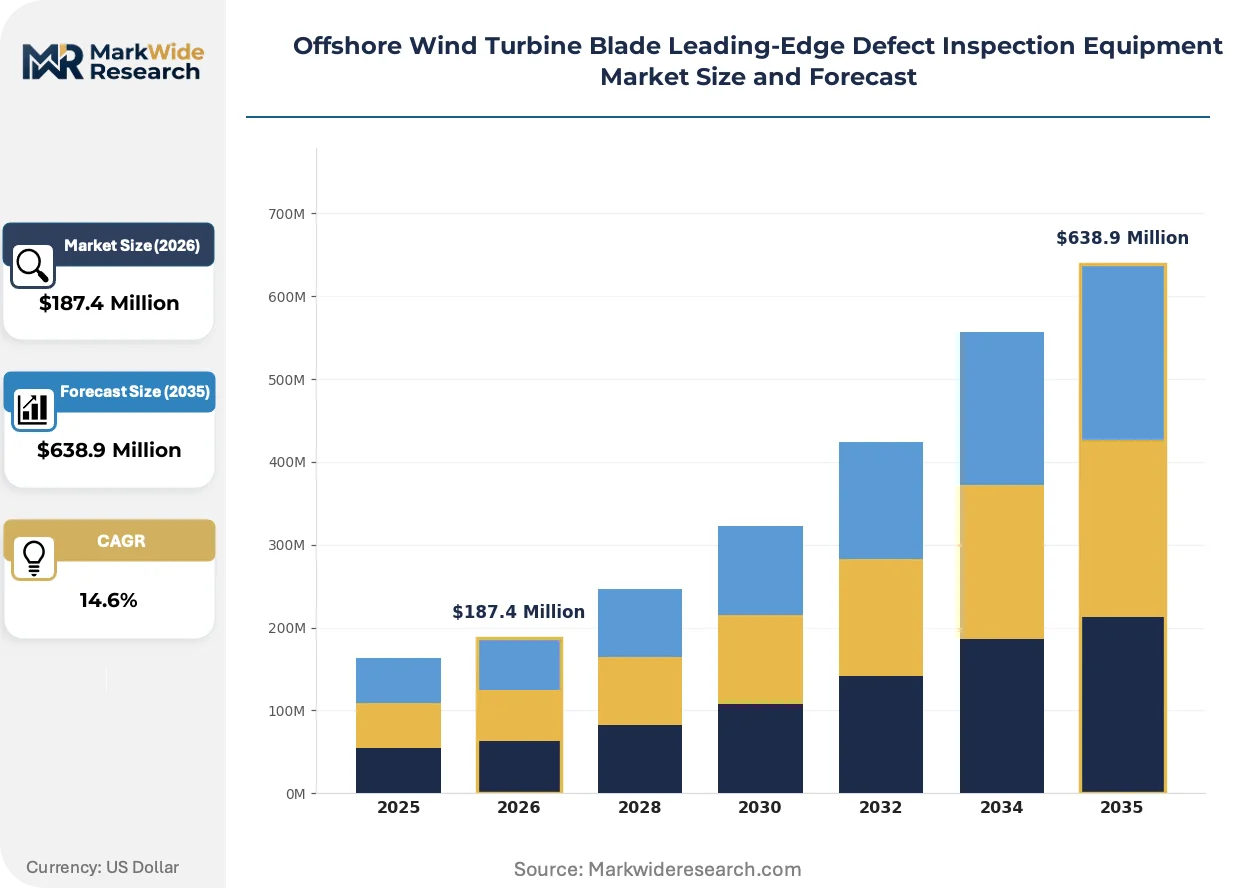
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Visual Inspection, Thermographic Inspection, Laser Scanning, Acoustic Emission Technology: Phased Array, Eddy Current, Infrared Imaging, Photogrammetry, Vibration Analysis Application: Damage Detection, Quality Control, Corrosion Monitoring, Structural Health Monitoring, Maintenance Planning End User: Blade Manufacturers, Inspection Service Providers, Wind Farm Operators, Maintenance Contractors |
| Companies Covered | DJI Enterprise, Skydio, Parrot, Autel Robotics, Flyability, Evident, Teledyne FLIR, Hexagon, Eddyfi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market Trends and Innovations
Inspection modality convergence and procurement restructuring are compressing equipment refresh cycles, as buyers prioritize multi-sensor platforms that amortize capital across diverse defect-detection workflows.
Distributed phased-array architectures are modularizing across offshore service fleets. Blade inspection contractors configure scalable ultrasonic node arrays that adapt to varying laminate geometries without hardware swaps. This flexibility enables a single crawler platform to service both 85-meter legacy blades and 120-meter next-generation units, collapsing the capital intensity of mixed-fleet operations.
The EU Green Deal's renewable energy directives are mandating documented structural baselines for warranty and insurance compliance. Equipment vendors must embed tamper-proof data logging and blockchain-traceable calibration certificates into inspection platforms. Danish and German operators are responding by specifying IEC 61400-23-compliant systems in procurement tenders, disqualifying uncertified equipment from multi-year service contracts.
Long-term service agreements are displacing spot inspection purchases among concentrated buyers. Ørsted and Equinor now contract predictive maintenance subscriptions that bundle equipment, labor, and data analytics into single per-turbine fees. This shift concentrates vendor selection authority with procurement teams in Copenhagen and Stavanger, marginalizing smaller inspection firms lacking capital reserves for multi-asset deployment.
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market Segmentation
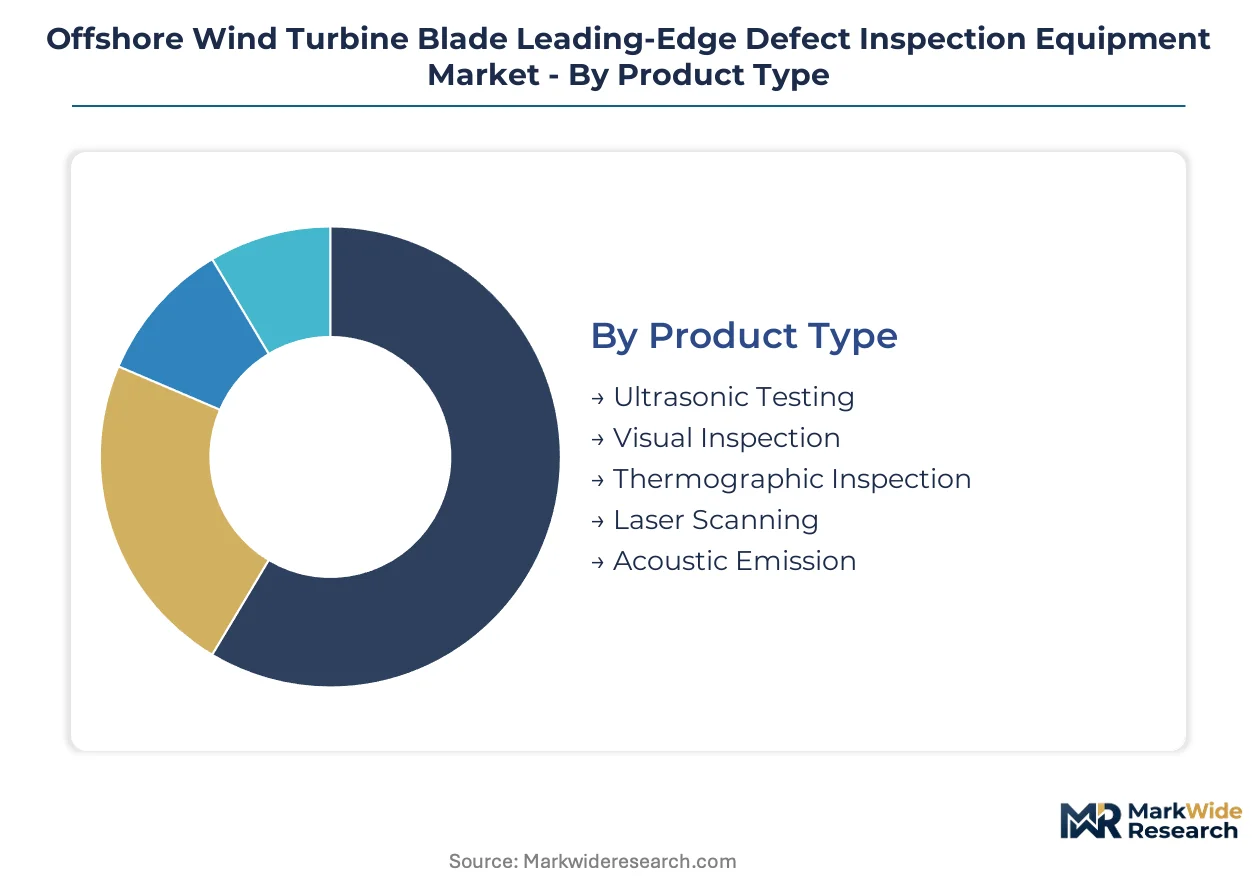
Defect detection requirements vary sharply across blade lifecycle stages and operational environments. Equipment configurations must align with specific damage mechanisms—from leading-edge erosion to subsurface delamination—while accommodating turbine accessibility constraints.
Product Type:
Standardized inspection protocols dominate high-volume deployments, while customized multi-sensor configurations serve complex laminate geometries on next-generation blades.
- Ultrasonic Testing:Phased-array probes penetrate fiberglass-carbon fiber stacks to map thickness variations and void formations beneath the gel coat. Danish service providers deploy these systems across Ørsted's North Sea fleet, where salt spray accelerates internal delamination.
- Thermographic Inspection:Infrared cameras detect subsurface moisture ingress and adhesive disbonds through thermal gradient analysis. German operators specify these payloads for quality control gates at blade manufacturing facilities in Bremerhaven.
- Visual Inspection:High-resolution imaging captures surface erosion patterns and leading-edge pitting.
- Laser Scanning:LiDAR-based systems generate sub-millimeter surface topology maps for aerodynamic performance validation.
- Acoustic Emission:Piezoelectric sensors monitor crack propagation during operational load cycles.
Most installed capacity flows through Ultrasonic Testing. Expansion is steepest in Thermographic Inspection.
Technology:
Cost tiering separates established single-element methods from premium beam-steering architectures that command higher per-inspection fees.
- Phased Array:Electronically steered ultrasonic beams eliminate mechanical scanning, compressing inspection duration on 100-meter-plus blades. United Kingdom contractors prioritize these systems for offshore campaigns where vessel day rates exceed equipment amortization.
- Infrared Imaging:Uncooled microbolometer arrays deliver passive thermal detection without contact requirements. Norwegian floating wind pilots specify stabilized gimbal mounts to compensate for platform motion during blade sweeps.
- Eddy Current:Electromagnetic induction detects surface-breaking cracks in metallic lightning protection systems.
- Photogrammetry:Multi-camera arrays reconstruct 3D surface models from overlapping image sets.
- Vibration Analysis:Accelerometer networks track modal frequency shifts indicating structural degradation.
Phased Array commands the premium tier. Photogrammetry offers the lowest capital entry point.
Application:
Volume concentration clusters around reactive maintenance workflows, while margin pools shift toward predictive regimes that bundle analytics subscriptions.
- Damage Detection:Post-storm assessment protocols mandate rapid deployment of multi-modal platforms to certify blade integrity before restart. German insurers require documented thermal-ultrasonic sweeps following Category 2 equivalent wind events.
- Structural Health Monitoring:Continuous sensor networks track fatigue accumulation across laminate stacks. Danish operators embed fiber optic strain gauges during blade manufacture for lifetime performance modeling.
- Quality Control:Manufacturing-stage validation ensures laminate stack conformity to design specifications.
- Corrosion Monitoring:Salt spray exposure tracking focuses on root section metallic components.
- Maintenance Planning:Degradation forecasting algorithms optimize crane vessel scheduling.
Damage Detection absorbs the highest equipment utilization hours. Structural Health Monitoring is gaining share fastest.
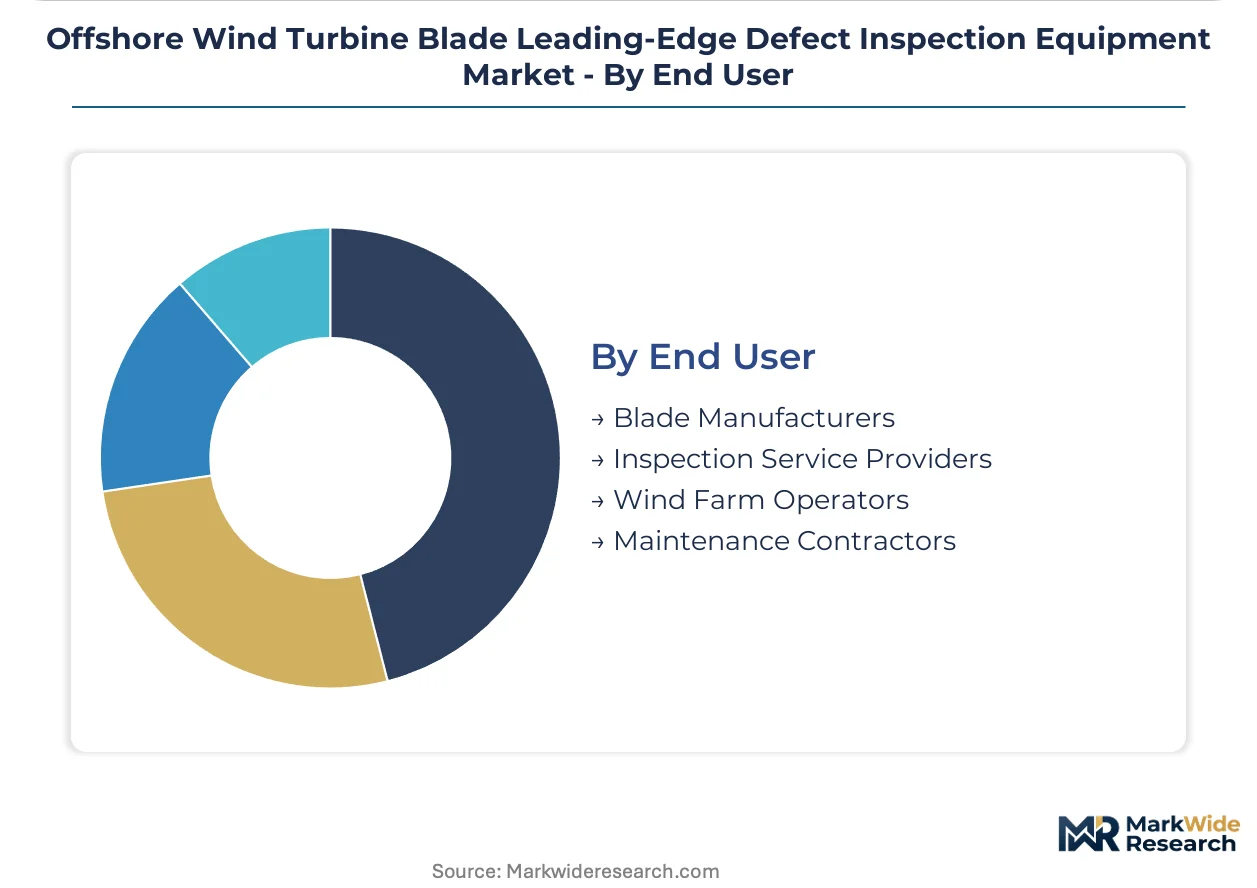
End User:
Customer type determines procurement structure—captive fleets favor capital purchases while independent service providers lease flexible platform configurations.
- Inspection Service Providers:Third-party contractors amortize equipment across multiple wind farm contracts, capturing recurring revenue from predictive maintenance subscriptions. United Kingdom-based specialists dominate North Sea inspection campaigns through vessel-mounted crawler deployments.
- Wind Farm Operators:Ørsted-scale developers internalize inspection capabilities for proprietary fleet management. These buyers specify IEC 61400-23-compliant data logging for warranty retention.
- Blade Manufacturers:Quality control gates at production facilities require high-throughput validation systems.
- Maintenance Contractors:Repair-focused firms deploy inspection equipment to scope intervention requirements.
Inspection Service Providers deploy the broadest platform fleets. Wind Farm Operators are consolidating procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine robotics engineers and offshore wind technicians cluster around North Sea port cities and Atlantic seaboard training centers, creating specialized labor pools that attract equipment vendors and inspection service providers.
United Kingdom
Ørsted and ScottishPower operate the world's largest offshore wind fleets in UK waters, driving demand for automated crawler systems that reduce vessel charter costs during blade surveys. The Offshore Wind Sector Deal mandates annual structural audits for turbines above 8MW capacity, compelling operators to maintain certified inspection records. Port of Grimsby hosts the densest concentration of blade maintenance contractors in Europe, with three specialist firms deploying phased-array platforms across Dogger Bank installations.
Germany
North Sea lease expansions off Lower Saxony and Schleswig-Holstein require defect documentation for grid connection permits under the Bundesnetzagentur offshore framework. The EU Green Deal's renewable energy directives tighten baseline reporting requirements, forcing operators to replace manual visual checks with sensor-validated systems. Bremerhaven manufacturing clusters integrate thermographic quality control gates into blade production lines, creating captive demand for infrared inspection payloads.
Denmark
Ørsted's Copenhagen procurement teams consolidate multi-year service agreements that bundle equipment, labor, and predictive analytics into per-turbine fees. National offshore wind codes mandate IEC 61400-23-compliant data logging for warranty retention, disqualifying uncertified inspection platforms. Esbjerg port infrastructure supports the densest deployment of ultrasonic crawler fleets in the North Sea, with contractors rotating equipment across Horns Rev and Kriegers Flak arrays.
United States
Atlantic lease blocks from Massachusetts to North Carolina require documented structural baselines under FERC offshore wind siting guidelines before commercial operation approval. Vineyard Wind and South Fork Wind developers are contracting inspection service providers for pre-construction blade certification and ongoing maintenance subscriptions. New Bedford Marine Commerce Terminal serves as the primary staging point for crawler deployments to Northeast offshore arrays.
Norway
Equinor's floating wind pilots at Hywind Tampen create novel inspection requirements for stabilized robotic platforms that compensate for platform motion during blade sweeps. The Norwegian Water Resources and Energy Directorate mandates continuous structural monitoring for floating installations exposed to harsher dynamic loading conditions. Stavanger offshore engineering clusters supply specialized technicians capable of interpreting laminate-stack thickness maps in North Sea weather windows.
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology vectors, creating a tiered vendor structure where scale advantages in sensor manufacturing clash with agility in robotic platform integration. The market fragments across three strategic archetypes: aerospace-derived drone manufacturers repurposing matricopter airframes, industrial sensor houses bundling thermal and ultrasonic payloads, and dedicated NDT firms engineering marine-grade crawler chassis. Consolidation pressure intensifies as wind farm operators bundle procurement into long-term service agreements, favoring vendors with capital reserves for multi-asset deployment. Technology licensing partnerships between sensor fabricators and robotics integrators represent the dominant competitive move, followed by vertical integration into predictive maintenance software subscriptions.
Within the aerial platform tier, DJI Enterprise and Skydio occupy positions as scale-driven matricopter suppliers, while Teledyne FLIR anchors the thermal-imaging payload segment through its industrial sensor heritage. Eddyfi Technologies exemplifies the specialized NDT archetype, representing pure-play focus on phased-array ultrasonic systems for laminate-stack inspection. These three firms collectively illustrate how vendor selection authority concentrates with procurement teams demanding multi-modal capabilities bundled into single contract structures.
| Leading Market Players |
|---|
| DJI Enterprise |
| Skydio |
| Parrot |
| Autel Robotics |
| Flyability |
| Evident |
| Teledyne FLIR |
| Hexagon |
| Eddyfi Technologies |
| Others |
Pricing and Supply Chain Analysis
Ørsted-scale procurement consolidation into multi-year service agreements is forcing equipment vendors to absorb upfront platform costs and recover margins through predictive maintenance subscriptions, compressing transactional pricing for standalone crawler sales. This buyer-driven contract restructuring elevates importance of captive sensor fabrication and marine-grade chassis production to defend margin pools.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for high-resolution thermal and ultrasonic transducer arrays, eroding premium tiers that previously commanded certification-linked markups. Three-tier pricing structure across IEC 61400-23-certified, CE-marked, and uncertified equipment levels separates warranty-eligible systems from commodity alternatives. Cost compression in the standard tier is intensifying because Danish and German operators now specify tamper-proof data logging as mandatory, disqualifying lower-grade platforms. Independent inspection service providers exhibit highest price sensitivity due to equipment amortization pressures across fragmented contract portfolios.
Supply Chain Analysis
Refurbishment flows for phased-array probe arrays and thermal camera cores create secondary supply channels that extend component lifecycles and moderate replacement demand. Manufacturing concentrates in China for unmanned aerial platform airframes, South Korea for ultrasonic transducer fabrication, and Germany for precision motion control systems. Raw material dependencies span marine-grade aluminum and titanium alloys for salt-spray-rated chassis, high-purity piezoelectric ceramics for acoustic sensors, and uncooled microbolometer wafers for thermal imaging. Single-source vulnerability in East Asian sensor fabrication exposes vendors to logistics chokepoint risk. Distribution runs through specialized marine robotics integrators who bundle hardware with calibration services and predictive analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential through divergent regulatory enforcement timelines: EU Green Deal mandates already compel sensor-validated inspections in Danish and German waters, while FERC guidelines in United States Atlantic lease blocks create delayed but substantial demand windows for compliant platform vendors.
For Market Incumbents: Anticipate displacement risk from modular phased-array architectures that collapse hardware refresh cycles across mixed blade fleets. Prioritize backward integration into ultrasonic transducer fabrication to reduce exposure to South Korean and Japanese component house concentration. Defend position through IEC 61400-23 certification depth that disqualifies emerging competitors from Ørsted-scale procurement tenders. For New Entrants and Emerging Players: The premium-economy price-point gap in United States Atlantic offshore wind creates white-space opportunity for mid-tier platforms that satisfy FERC structural baseline documentation without full European certification burden. Target inspection service providers in Massachusetts and North Carolina who lack capital reserves for multi-asset deployment but require compliant equipment for Vineyard Wind and South Fork Wind contracts. Pursue vessel-mounted crawler leasing models that transfer capital risk from operators to equipment financiers. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play marine robotics specialists possessing phased-array ultrasonic IP and established North Sea service relationships. Long-term viability hinges on platform adaptability to floating wind dynamic loading conditions as Norway and Portugal advance pre-commercial arrays. Monitor Equinor procurement specifications for stabilized robotic platforms as inflection signal for technology convergence requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Phased-Array Ultrasonic Platform Development | Beam-steering crawlers reduce turbine downtime for Ørsted-scale operators below vessel day-rate thresholds. |
| Marine-Grade Chassis Manufacturing Scale-Up | Salt-spray-rated aluminum and titanium fabrication secures supply continuity against commodity volatility. |
| Sensor Payload Convergence Partnership | Integration of FLIR thermal cores with ultrasonic probes captures surface and subsurface defects in single passes. |
| IEC 61400-23 Certification Investment | Blockchain-traceable calibration certificates satisfy Danish and German warranty retention mandates. |
| Predictive Maintenance Subscription Launch | Per-turbine fee structures align vendor revenue with wind farm operator predictive analytics demand. |
Research Methodology
Direct dialogue with offshore wind farm operators, inspection service providers, marine robotics engineers, and blade manufacturing quality control directors grounded qualitative assessment of procurement preference shifts and technology adoption barriers. Secondary validation drew from FERC offshore wind siting guidelines, EU Green Deal renewable energy directives, IEC 61400-23 blade measurement standards, and vessel charter rate databases. Bottom-up equipment deployment estimates triangulated against top-down market size projections derived from installed offshore capacity forecasts.
Segmentation outputs across product type, technology, application, and end user dimensions were modeled throughout the forecast period using blade length escalation curves and regulatory compliance timeline assumptions. CAGRs were derived from equipment replacement cycles tied to platform reach limitations on 115-meter-plus blades and inspection frequency mandates under evolving national offshore wind codes. Industry-specific inputs incorporated salt spray degradation rates for laminate stacks and floating wind dynamic loading coefficients.
Caveats apply where FERC guideline implementation delays, EU Green Deal enforcement variance across member states, or phased-array probe supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding blade length standardization timelines and robotic platform redesign cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Sweden Wind Power Market