
 Global Small Wind Market | 2026-2036
Global Small Wind Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Wind Market Foresight
The EU Green Deal is consolidating cost-of-entry calculus for small wind developers across member states. Bergey Windpower Co. leverages its decades-long track record in horizontal axis systems to anchor North American rural deployments. Aeolos Wind Energy Ltd. competes through specialized vertical axis designs optimized for low-wind regimes. SD Wind Energy differentiates via modular tower systems that reduce installation labor in remote agricultural settings.
Small wind encompasses turbines rated below 100 kW that convert kinetic wind energy into electrical power through rotor-driven generators, typically featuring blade lengths of one to fifteen meters and cut-in wind speeds near three meters per second. These systems serve distributed generation needs where grid extension proves uneconomical or where end users seek energy cost stabilization. Horizontal axis turbines occupy the dominant share of installed capacity due to higher aerodynamic efficiency and established supply chains. The 10-50 kW capacity band represents the fastest-expanding segment as farm operators and telecom providers seek scalable solutions that avoid utility interconnection delays. Remote residential applications remain mature with slower growth but predictable replacement cycles that sustain aftermarket revenue pools.
FAA guidelines in the United States govern turbine height and placement near airports, while ECHA's REACH framework constrains composite material selection for European manufacturers. China's GB standards and MIIT efficiency mandates shape export competitiveness for rotor and generator suppliers. Stakeholders must monitor evolving national permitting timelines and grid access rules as these administrative variables increasingly determine project viability more than technology cost curves.
Market Dynamics
Feed-in tariff reforms across the European Union are compressing project payback periods and forcing developers to optimize turbine siting algorithms before construction begins. This regulatory recalibration is redrawing competitive boundaries between horizontal and vertical axis architectures.
Growth Catalysts
- EU Green Deal implementation:Member state harmonization of permitting timelines is reducing administrative delays for sub-100 kW installations in rural electrification zones.
- Telecom tower operators:Off-grid power requirements for 5G infrastructure are creating dedicated procurement channels for 10-50 kW modular systems.
- Composite blade manufacturing:Automated fiber placement techniques are cutting rotor production costs for distributed wind OEMs serving agricultural markets.
Market Restraints
- Rare earth magnet dependency:Generator suppliers face price volatility for neodymium sourced primarily through Chinese processing facilities.
- FAA height restrictions:United States airport proximity rules limit tower elevation options in the Great Plains corridor where wind resources concentrate.
- Solar PV substitution:Declining photovoltaic module costs are capturing overlapping distributed generation budgets from commercial and residential buyers.
Strategic Opportunities
- India's rural electrification mandate:The country's CEA guidelines for decentralized renewable systems are opening captive-use frameworks for village-level microgrids.
- Battery-wind hybridization:Integration with lithium-ion storage is enabling 24-hour power delivery contracts for islanded commercial sites.
- Direct-to-farmer distribution:Bypassing traditional EPC contractors through manufacturer-financed lease programs is penetrating Midwestern United States agricultural counties.
Industry Challenges
- Certification timeline compression:IEC 61400-2 small wind turbine safety standards require extended field testing that delays product launches by 18-24 months.
- Installation labor scarcity:Specialized tower erection crews for guyed mast systems command premium wages in remote deployment zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Wind Market |
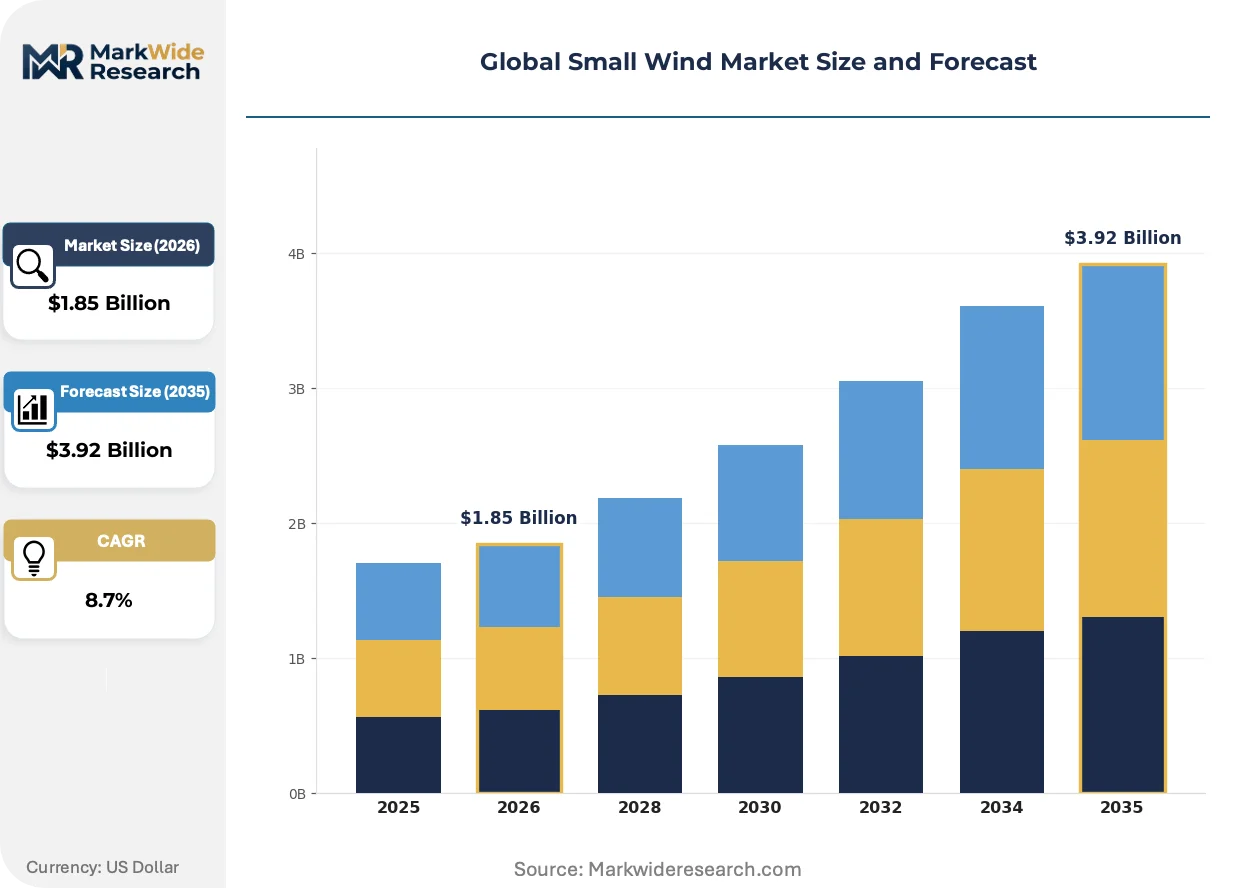
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis Turbines, Vertical Axis Turbines, Darrieus Rotor, Savonius Rotor Capacity: Up to 10 kW, 10-50 kW, 50-100 kW, Above 100 kW Application: Remote Residential, Agricultural Operations, Telecom Towers, Off-Grid Commercial Sites End User: Individual Consumers, Farm Operators, Telecommunications Providers, Small Industrial Units |
| Companies Covered | Bergey Windpower Co., Aeolos Wind Energy Ltd., SD Wind Energy, Ryse Energy, Northern Power Systems, Envergate Energy AG, Kingspan Group, Kliux Energies, EOCYCLE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Wind Market Shifts & Advancements
Permanent magnet generator architectures are displacing conventional gearbox designs across the sub-50 kW segment. This mechanical simplification is reducing maintenance intervals and enabling new ownership models.
Direct-drive permanent magnet generators eliminate gearbox failure modes while cutting nacelle weight by approximately one-third compared to traditional drivetrains. Farm cooperatives in Germany and Denmark are specifying these configurations for unmanned agricultural installations. The technology is consolidating supplier tiers as in-house magnet assembly capabilities become a prerequisite for tier-one component sourcing.
REACH framework amendments under ECHA are restricting epoxy resin formulations used in blade lamination processes. European manufacturers are reformulating composite chemistries to maintain CE marking eligibility for export markets. German rotor suppliers report 8-12 month qualification cycles for alternative resin systems that preserve fatigue resistance specifications.
Energy-as-a-service contracts are displacing capital purchase models for commercial and industrial buyers. Third-party ownership structures transfer performance risk to developers while capturing federal investment tax credits. This financing pivot is most advanced in United States agricultural counties where farmers prioritize cash flow predictability over equipment ownership.
Global Small Wind Market Segmentation
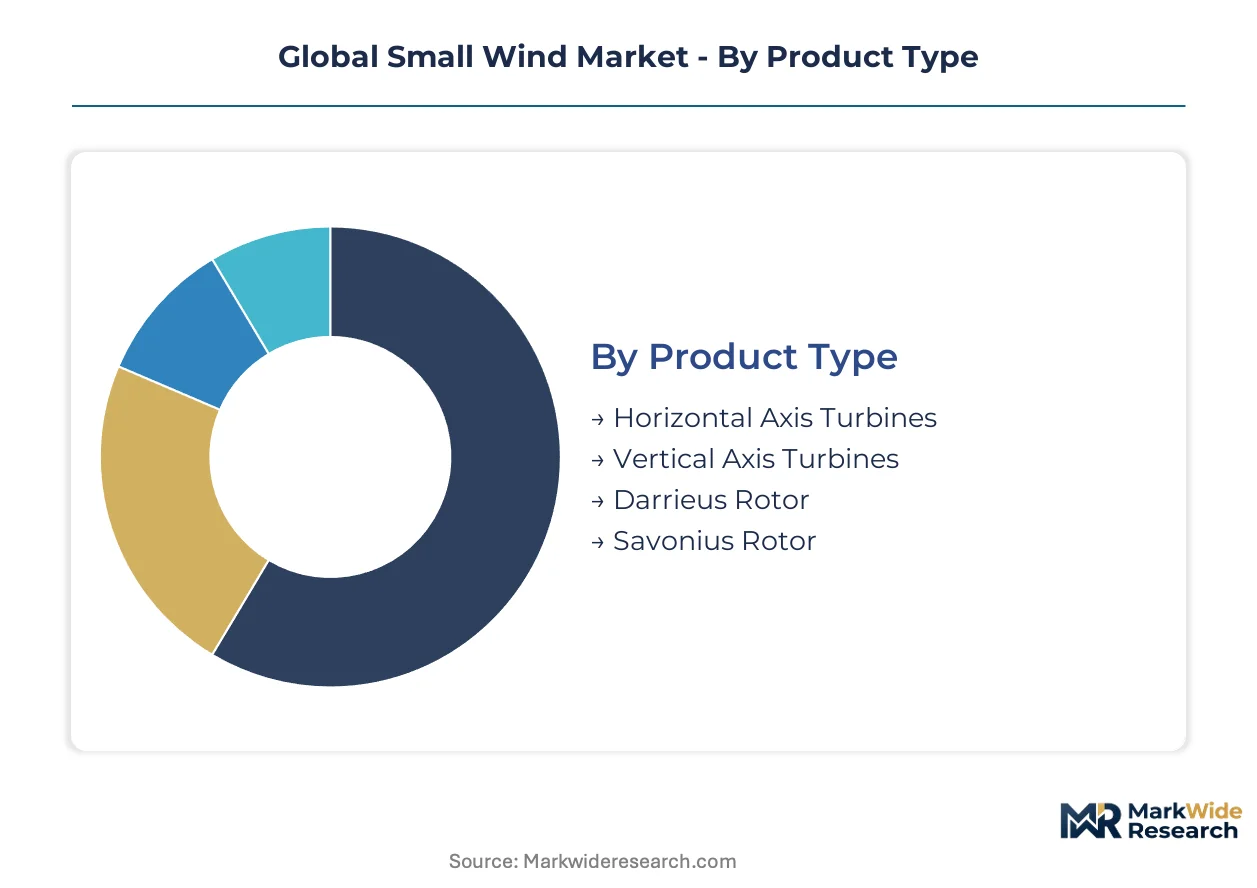
Segmentation in small wind reveals divergent procurement logics across buyer types. Turbine selection hinges on wind resource profiles, grid proximity, and capital constraints rather than uniform technical specifications.
Product Type:
Buyer differentiation centers on aerodynamic efficiency priorities versus installation flexibility requirements.
- Horizontal Axis Turbines:These systems orient rotor blades perpendicular to wind flow, achieving higher tip-speed ratios and energy conversion efficiency. Demand concentrates in Germany and the United States where farm operators prioritize maximizing kilowatt-hour yields per installed square meter.
- Vertical Axis Turbines:Omnidirectional designs capture wind from any angle without yaw mechanisms, simplifying mechanical architecture. Telecom tower operators across India and China specify these configurations for sites with turbulent or variable wind directions where maintenance access is limited.
- Darrieus Rotor:Curved-blade vertical designs generate high starting torque suitable for direct-drive generator coupling. Off-grid commercial sites in remote Australian mining camps deploy these for mechanical reliability.
- Savonius Rotor:Drag-based vertical configurations trade efficiency for extreme simplicity and low cut-in speeds. Individual consumers in Scandinavian coastal regions select these for residential microgeneration where aesthetic constraints prohibit tall towers.
Volume sits with Horizontal Axis Turbines; growth tilts toward Vertical Axis Turbines.
Capacity:
Capital deployment scale separates residential self-consumption from commercial revenue-grade installations.
- Up to 10 kW:Compact systems serve single-family electrification and battery charging with minimal civil works. Remote residential applications in rural Spain and Portugal sustain steady replacement demand as early installations reach end-of-life.
- 10-50 kW:Modular architectures enable phased expansion and hybrid solar-wind configurations. Agricultural operations across the United States Midwest and Canadian prairie provinces are expanding procurement of these systems to power grain drying and irrigation equipment.
- 50-100 kW:Grid-interactive designs require utility interconnection agreements and professional installation crews. Small industrial units in Poland and Romania deploy these for behind-the-meter consumption under EU industrial decarbonization incentives.
- Above 100 kW:Systems at this threshold approach utility-scale engineering and regulatory treatment. Telecommunications providers in Brazil and South Africa pilot these for regional hub powering where diesel generator retirement is mandated.
The 10-50 kW band commands current installation volumes; the 50-100 kW category is climbing the fastest as commercial buyers scale distributed generation portfolios.
Application:
Site infrastructure maturity determines whether buyers prioritize grid independence or energy cost hedging.
- Remote Residential:Stand-alone systems integrate with battery storage and backup generators for complete energy autonomy. Mountain communities in Italy and Austria specify these where grid extension quotes exceed equipment costs by multiples.
- Agricultural Operations:Farm-scale turbines power irrigation pumps, cold storage, and processing equipment with predictable load profiles. Danish and Dutch agricultural cooperatives are consolidating procurement through collective purchasing agreements to reduce per-unit soft costs.
- Telecom Towers:5G infrastructure power requirements favor hybrid renewable systems with diesel backup elimination targets. Tower operators in Nigeria and Kenya are mandating renewable penetration thresholds for new site approvals.
- Off-Grid Commercial Sites:Mining camps, resorts, and research stations require 24/7 power reliability with minimal fuel logistics. Eco-tourism lodges in Costa Rica and New Zealand deploy these to meet sustainability certification requirements.
Agricultural Operations anchor installed base; Telecom Towers are gaining share fastest as 5G rollout accelerates.
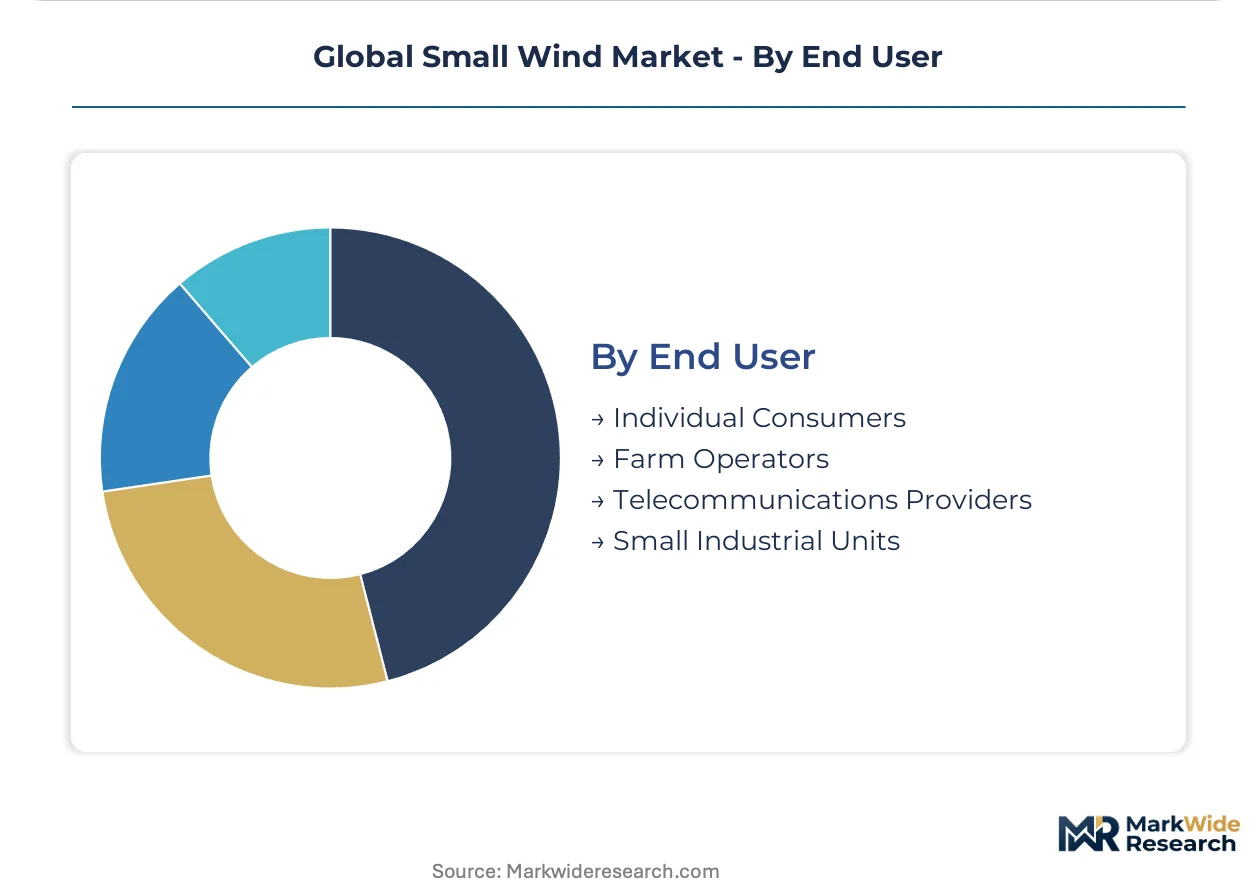
End User:
Technical sophistication and financing access create distinct procurement behaviors across buyer categories.
- Individual Consumers:Purchasers prioritize plug-and-play installation, aesthetic integration, and manufacturer warranty terms. German homeowners leverage KfW development bank financing programs to reduce capital barriers.
- Farm Operators:Buyers evaluate systems against diesel fuel savings and equipment depreciation schedules with ten-year payback horizons. USDA Rural Energy for America Program grants shape United States procurement timing.
- Telecommunications Providers:Corporate procurement teams standardize on modular platforms with remote monitoring and predictive maintenance capabilities. Tower infrastructure funds in the United Kingdom and Ireland specify vendor performance guarantees.
- Small Industrial Units:Energy managers seek power purchase agreement structures that transfer operational risk to developers. Polish manufacturing clusters are aggregating demand to secure volume pricing from turbine OEMs.
Farm Operators dominate current volumes; Telecommunications Providers show the steepest expansion trajectory as infrastructure funds deploy capital into green tower assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rural Enterprise Zones in the United States Midwest and EU cohesion fund territories in Eastern Europe are concentrating small wind deployment through targeted tax abatements and simplified permitting pathways.
United States
Telecom tower electrification and agricultural decarbonization drive procurement across the Great Plains and Midwest. The FAA governs turbine height restrictions near airports, constraining tower elevation in wind-rich corridors. Iowa and Kansas host dense clusters of farm-scale installations powering grain drying operations.
Germany
Agricultural cooperatives and distributed industrial users anchor demand in Lower Saxony and Schleswig-Holstein. The EU Green Deal harmonizes permitting timelines while KfW development bank financing reduces capital barriers. Bavarian rotor suppliers report extended qualification cycles for REACH-compliant resin systems.
China
Rural electrification mandates and telecom infrastructure expansion propel installations across Inner Mongolia and Xinjiang. MIIT efficiency mandates and GB standards shape export competitiveness for generator and rotor suppliers. Yangtze River Delta manufacturing clusters supply permanent magnet assemblies to domestic and international OEMs.
India
Off-grid commercial sites and village-level microgrids create procurement pull in Gujarat and Rajasthan. CEA guidelines for decentralized renewable systems establish captive-use frameworks. Tower operators in Maharashtra and Karnataka mandate renewable penetration thresholds for new 5G site approvals.
United Kingdom
Telecommunications infrastructure funds and agricultural estates drive deployment across Scotland and Northern England. Tower infrastructure funds specify vendor performance guarantees for green tower assets. Welsh upland farming communities pursue hybrid wind-battery configurations for energy autonomy.
Global Small Wind Market Competitive Landscape
North American producers anchor one tier; European specialists hold differentiated positions in vertical axis architectures. The vendor base spans three tiers: established horizontal axis manufacturers, modular system integrators, and emerging vertical axis designers. Strategic moves concentrate on geographic expansion into agricultural counties and technology licensing for permanent magnet generator architectures.
Within the horizontal axis tier, Bergey Windpower Co. and Northern Power Systems exemplify long-tenured North American fabricators with established rural deployment track records. Aeolos Wind Energy Ltd. represents the vertical axis specialization vector, while SD Wind Energy occupies a position in modular tower system integration. These anchors illustrate how competitive positioning stratifies across aerodynamic efficiency priorities versus installation flexibility requirements.
| Leading Market Players |
|---|
| Bergey Windpower Co. |
| Aeolos Wind Energy Ltd. |
| SD Wind Energy |
| Ryse Energy |
| Northern Power Systems |
| Envergate Energy AG |
| Kingspan Group |
| Kliux Energies |
| EOCYCLE |
| Others |
Supply & Pricing Matrix
Telecom tower operators' standardization on modular 10-50 kW platforms with remote monitoring capabilities is compressing supplier margins and forcing permanent magnet generator manufacturers to absorb neodymium price volatility or lose procurement slots to vertically integrated competitors.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to permanent magnet generator orders needed within standard manufacturing cycles, while spot inventory of REACH-compliant resin systems trades at discounts due to qualification uncertainty. Project-based long-term offtake contracts dominate agricultural and telecom procurement, with price differentiation resting on IEC 61400-2 certification tier and after-sales service bundling. Pricing pressure stems from solar PV substitution in distributed generation budgets, with farm operators in the United States Midwest showing highest price sensitivity and telecommunications providers least sensitive due to diesel elimination mandates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing facilities that feed permanent magnet assembly operations in the Yangtze River Delta and German rotor manufacturing clusters. Raw material dependencies encompass rare earth magnets, carbon fiber for blade lamination, and copper windings for generator stators. Tariff exposure on Chinese magnet exports to the United States and European Union creates supply chain risk. Distribution runs through EPC contractors for grid-interactive installations and direct manufacturer relationships for off-grid commercial sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as feed-in tariff compression across the European Union forces sub-scale developers into acquisition or exit, with capital access separating viable players from stranded assets.
For Market Incumbents: Lock in agricultural cooperative procurement through manufacturer-financed lease programs that transfer performance risk and capture USDA Rural Energy for America Program grants. Deepen backward integration into permanent magnet assembly to offset Chinese neodymium price volatility and secure tier-one component sourcing status.
For New Entrants and Emerging Players: Village-level microgrid developers in India's Gujarat and Rajasthan present underserved buyer archetypes with captive-use frameworks under CEA guidelines. Penetrate this segment through battery-wind hybridization offerings that enable 24-hour power delivery contracts, bypassing established EPC channels via direct relationships with state nodal agencies.
For Investors and Strategic Acquirers: The window for entry favors modular tower system integrators with proven installation labor reduction in remote agricultural settings. Target mid-cap specialists with in-house magnet assembly capabilities and established IEC 61400-2 certification timelines. Watch for inflection when FAA height restriction reforms unlock Great Plains corridor deployment density.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Generator Backward Integration | Captive neodymium sourcing insulates margins from Chinese export tariff exposure. |
| Battery-Wind Hybrid System Launch | Lithium-ion integration enables 24-hour delivery contracts for islanded commercial sites. |
| Direct-to-Farmer Lease Program Expansion | Manufacturer financing bypasses EPC contractors in Midwestern United States agricultural counties. |
| REACH-Compliant Resin Qualification | Alternative epoxy formulations preserve CE marking eligibility for European export markets. |
| Telecom Tower Performance Guarantee Partnership | Remote monitoring capabilities meet infrastructure fund requirements for green tower assets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with turbine OEM procurement directors, EPC project developers, agricultural cooperative energy managers, telecom tower infrastructure fund analysts, and composite materials suppliers. Secondary sources encompassed FAA airspace determinations, ECHA REACH amendments, MIIT efficiency mandates, and IEC 61400-2 certification databases. Bottom-up installation volume tracking triangulated against top-down market sizing from national rural electrification program disclosures.
Data-stream reconciliation across manufacturer shipment records, utility interconnection queues, and development bank financing approvals informed the analytical framework. Segmentation dimensions encompassed turbine architecture, capacity tier, application type, and end-user sophistication across the projection horizon. CAGRs derived from fitted growth curves applied to normalized installation data, with cross-validation against permanent magnet generator production volumes and composite blade manufacturing capacity announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal permitting harmonization delays, rare earth export restriction escalations, and solar PV cost curve trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Poland Wind Energy Market