
 South America Renewable Energy Market | 2026-2036
South America Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South America Renewable Energy Market Analytics
The South America renewable energy landscape is recalibrating around a widening split between premium dispatchable renewables with storage and commodity intermittent generation. Enel Green Power S.p.A. leverages its integrated development platform across Brazil and Chile to capture premium pricing for hybrid solar-plus-storage projects. Iberdrola S.A. anchors its position through deep operational expertise in onshore wind across northeastern Brazil. AES Andes S.A. differentiates by dominating the Chilean market with a concentrated portfolio of utility-scale solar and battery assets.
South America renewable energy encompasses electricity generation from solar, wind, hydro, and biomass resources through photovoltaic arrays, wind turbines, hydropower plants, and biogas systems, primarily serving utilities, commercial entities, and industrial offtakers seeking cost-competitive, low-carbon power. Hydropower plants retain structural dominance across the region due to installed base scale and baseload reliability, though photovoltaic deployment is expanding fastest as module costs decline and distributed generation frameworks mature. The industrial end user segment commands concentrated margin pools, particularly from mining and metals processing operations pursuing power purchase agreements to secure price certainty and emissions reductions.
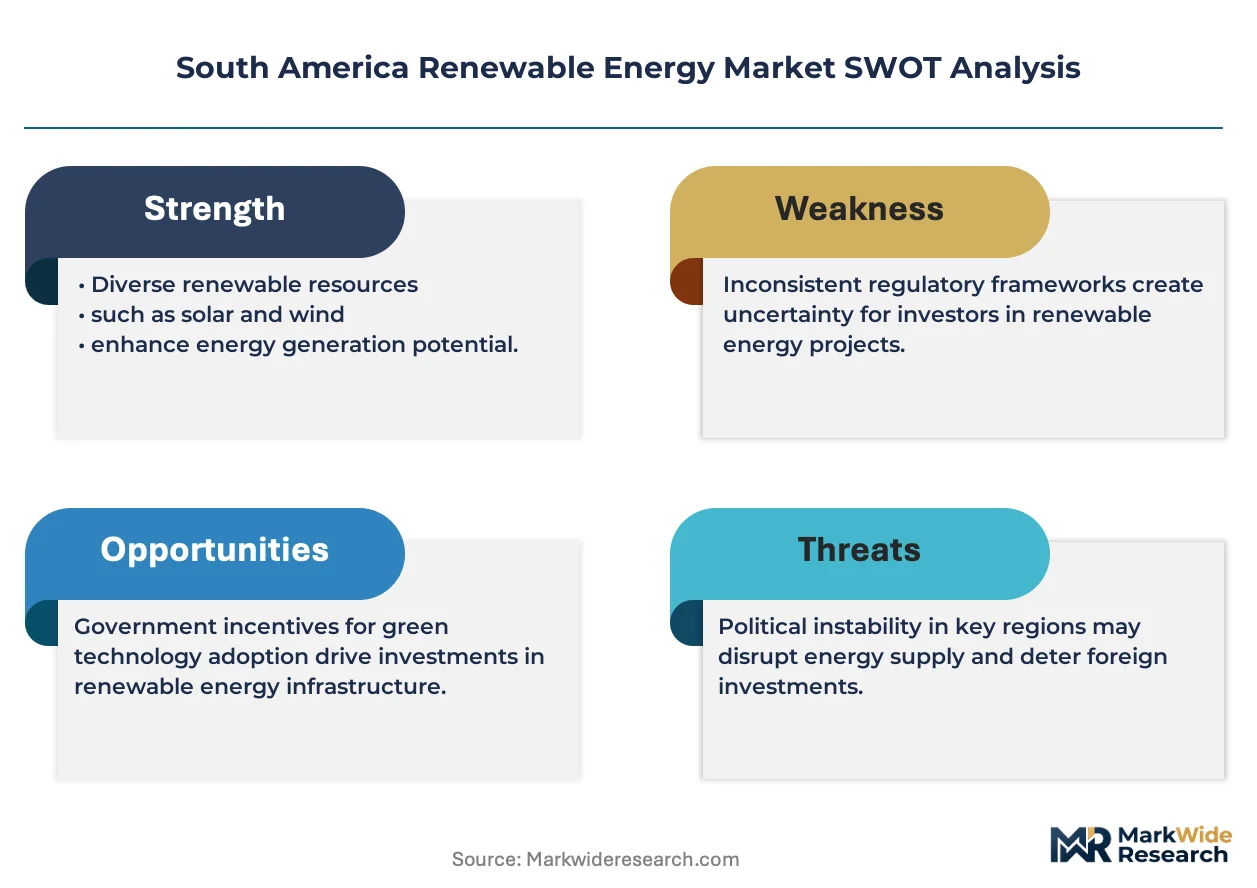
Brazil's ANEEL governs grid access and distributed generation net metering rules that directly shape project economics for residential and commercial solar adopters, while Chile's Ministry of Energy implements carbon neutrality mandates that force mining sector procurement shifts toward renewable supply. Argentina's Secretariat of Energy administers renewable energy auction mechanisms and import tariff structures that condition market entry for foreign developers. Stakeholders must monitor regulatory implementation consistency across these jurisdictions to allocate capital between established markets and reform-driven openings.
Market Dynamics
The South America renewable energy market is recalibrating around dispatchable generation premiums as intermittent solar and wind volumes saturate midday wholesale price windows. Grid operators now prioritize firm capacity, forcing developers to co-locate battery storage or face merchant price collapse.
Growth Catalysts
- Carbon neutrality mandates:Chile's Ministry of Energy binding targets compel mining sector offtakers to procure 100% renewable supply by 2040, creating guaranteed demand pools for utility-scale developers.
- Net metering frameworks:Brazil's ANEEL distributed generation regulations enable commercial and industrial consumers to offset grid purchases with behind-the-meter solar, accelerating rooftop deployment across São Paulo and Minas Gerais industrial zones.
- Atacama Desert irradiance:Exceptional solar resource concentration in northern Chile supports capacity factors exceeding 30% for photovoltaic plants, reducing levelized cost thresholds below fossil alternatives without subsidy.
Market Restraints
- Transmission congestion:Brazil's northeastern wind belt suffers curtailment due to inadequate HVDC corridor capacity to southeastern demand centers, stranding generation assets during high-resource periods.
- Import tariff volatility:Argentina's Secretariat of Energy discretionary duties on solar module imports create capital cost uncertainty that freezes project financing timelines for foreign developers.
- Biomass feedstock competition:Sugarcane bagasse supply prioritization for ethanol production limits availability for power generation, constraining expansion of bioelectricity in Brazil's Center-South region.
Strategic Opportunities
- Green hydrogen offtake:Chile's Magallanes region wind-to-hydrogen pilot projects create anchor demand for otherwise stranded renewable capacity, with mining and maritime fuel applications scaling through 2030.
- Hybrid project economics:Solar-plus-storage configurations in Brazil's northeast capture evening peak pricing premiums as grid-scale battery costs decline, opening merchant revenue streams beyond regulated auctions.
- Corporate PPA aggregation:Argentina's SME sector remains underserved by direct renewable supply contracts, creating white space for retail energy providers to bundle distributed generation portfolios for mid-market buyers.
Industry Challenges
- Grid interconnection queues:ANEEL's procedural backlog for transmission access studies extends project commissioning timelines by 18-24 months, inflating carrying costs and eroding developer returns.
- Local content requirements:Brazil's BNDES financing mandates for domestic equipment sourcing clash with module availability constraints, forcing technology substitutions that compromise plant performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Renewable Energy Market |
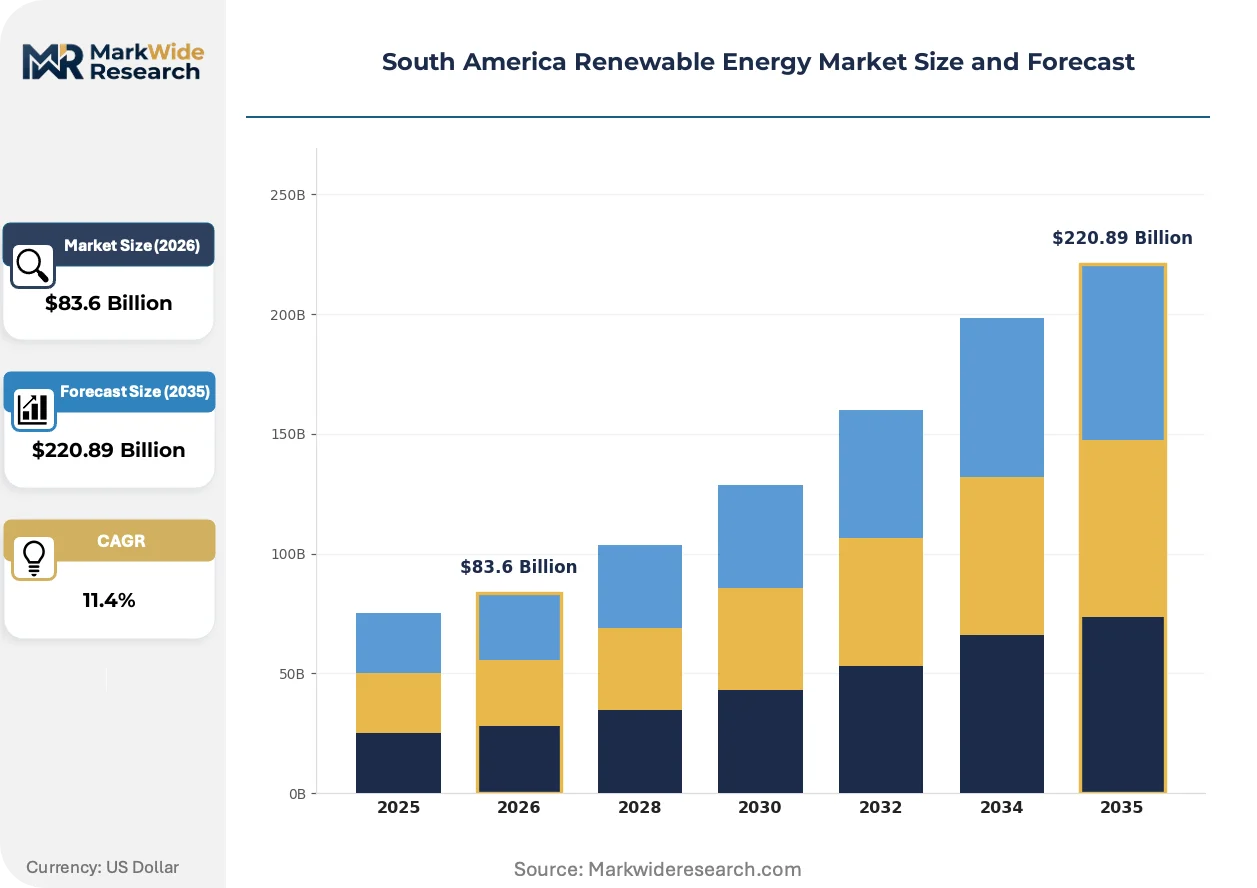
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $220.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Hydro, Biomass Technology: Photovoltaic, Wind Turbines, Hydropower Plants, Biogas Systems End User: Utilities, Commercial, Residential, Industrial Deployment Model: On-grid, Off-grid, Hybrid, Community |
| Companies Covered | Enel Green Power S.p.A., Iberdrola S.A., ENGIE Brasil Energia S.A., Neoenergia S.A., AES Andes S.A., Statkraft, EDF Renewables América Latina, Mainstream Renewable Power, Brookfield Renewable Partners, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Renewable Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing development cycles and redrawing competitive boundaries across South America's renewable energy value chain. Developers now compete on integrated system optimization rather than component cost alone.
Bifacial photovoltaic modules with tracking systems is unifying generation profiles across Brazil's high-latitude sites, capturing reflected irradiance from agricultural and arid ground cover. Mining operators in Minas Gerais and Pará are specifying these configurations for 25-year power purchase agreements. The technology is unifying daytime supply curves with evening demand peaks, reducing battery storage duration requirements by 15-20%.
Argentina's RenovAr auction mechanism is restructuring market access by mandating long-term contract tenors that de-risk project finance for international investors. The program's enforcement of financial closure deadlines filters speculative bidders, concentrating awards on developers with balance sheet capacity. Foreign entrants now prioritize Argentine partnerships over greenfield subsidiaries to navigate local permitting complexity.
Energy attribute certificate unbundling from physical power contracts is fragmenting procurement strategies among corporate buyers. Chilean mining majors now source electrons from the cheapest grid-connected assets while purchasing guarantees of origin from premium renewable projects to satisfy Scope 2 reporting requirements. This bifurcation is most visible in Antofagasta and Coquimbo regions, where copper producers optimize cost and disclosure outcomes separately.
South America Renewable Energy Market Segmentation
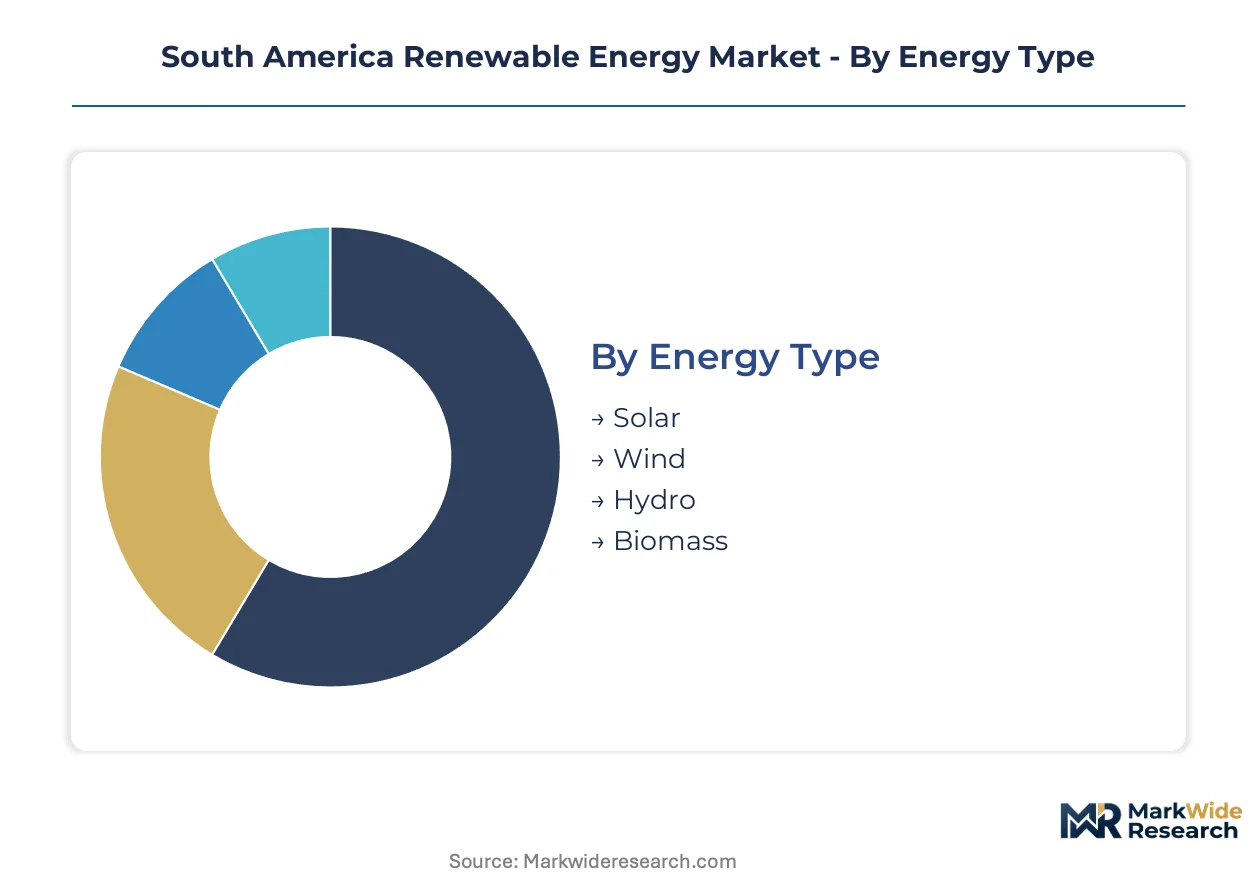
Segmentation in South America's renewable energy market reveals how capital allocation, regulatory frameworks, and resource endowments concentrate investment across distinct technology and customer configurations. Understanding these divisions enables developers to match project economics with offtake risk profiles and grid access conditions.
Energy Type:
Capital intensity varies sharply across generation technologies, with reservoir-based hydroelectric projects demanding the largest upfront commitments while distributed solar requires minimal balance-sheet deployment.
- Hydro:Large-scale reservoir and run-of-river installations dominate Brazil's generation matrix through decades of accumulated infrastructure. ANEEL's modernization auctions now prioritize turbine efficiency upgrades at existing facilities over greenfield development due to environmental licensing constraints.
- Solar:Photovoltaic deployment accelerates fastest across Chile's Atacama Desert and Brazil's northeastern high-irradiance zones, capitalizing on module cost declines and mining sector procurement mandates. Distributed generation net metering in São Paulo industrial corridors drives rooftop capacity additions.
- Wind:Onshore turbines cluster in Brazil's Rio Grande do Norte and Ceará wind belt, where consistent trade winds support capacity factors above 35%. Transmission congestion to southeastern demand centers periodically strands generation during peak resource periods.
- Biomass:Sugarcane bagasse-fired plants concentrate in Brazil's Center-South agricultural belt, supplying baseload power during harvest seasons. Ethanol production competition for feedstock constrains year-round generation availability.
Hydro absorbs the bulk of installed capacity; solar is expanding most quickly.
Technology:
Equipment specifications determine project development timelines, with standardized photovoltaic components enabling faster deployment than custom-engineered hydropower infrastructure.
- Photovoltaic:Crystalline silicon modules with single-axis tracking systems capture elevated irradiance across Chilean and Brazilian high-altitude sites. Bifacial configurations gain share in mining sector procurements for enhanced generation profiles.
- Wind Turbines:Larger rotor diameters and hub heights characterize new installations in Brazil's northeastern wind belt, improving capacity factors at lower-wind-speed sites. Gearless direct-drive designs reduce maintenance requirements for remote installations.
- Hydropower Plants:Francis and Kaplan turbine retrofits dominate Brazil's modernization pipeline, extending asset life without new reservoir impoundment. Small hydro run-of-river projects face heightened environmental scrutiny under revised licensing protocols.
- Biogas Systems:Anaerobic digesters processing agricultural waste and landfill gas supply distributed generation in Argentina's Pampas region and southern Brazil. Feedstock logistics limit project scale below utility-scale thresholds.
Hydropower plants retain the deepest installed base; photovoltaic systems are climbing the fastest.
End User:
Offtake contract structures diverge sharply across customer categories, with industrial miners demanding 15-20 year power purchase agreements while residential adopters rely on net metering arbitrage.
- Industrial:Mining and metals processing operations in Chile's Antofagasta region and Brazil's Minas Gerais state procure renewable supply to satisfy carbon neutrality commitments and secure price certainty. Corporate PPA aggregation models emerge for mid-market manufacturers.
- Utilities:State-owned and private distribution companies acquire capacity through regulated auctions administered by ANEEL and Argentina's Secretariat of Energy. Grid-scale procurement increasingly mandates storage co-location for firm capacity qualification.
- Commercial:Retail chains and office complexes in São Paulo and Santiago deploy behind-the-meter solar to offset peak demand charges. Energy attribute certificate unbundling allows separate optimization of cost and disclosure outcomes.
- Residential:Net metering frameworks in Brazil enable rooftop solar adoption among middle-income households, though upfront capital requirements constrain penetration. Argentina's macroeconomic volatility freezes residential deployment despite favorable solar resources.
Utilities hold the largest contracted capacity; industrial offtakers are gaining share fastest.
Deployment Model:
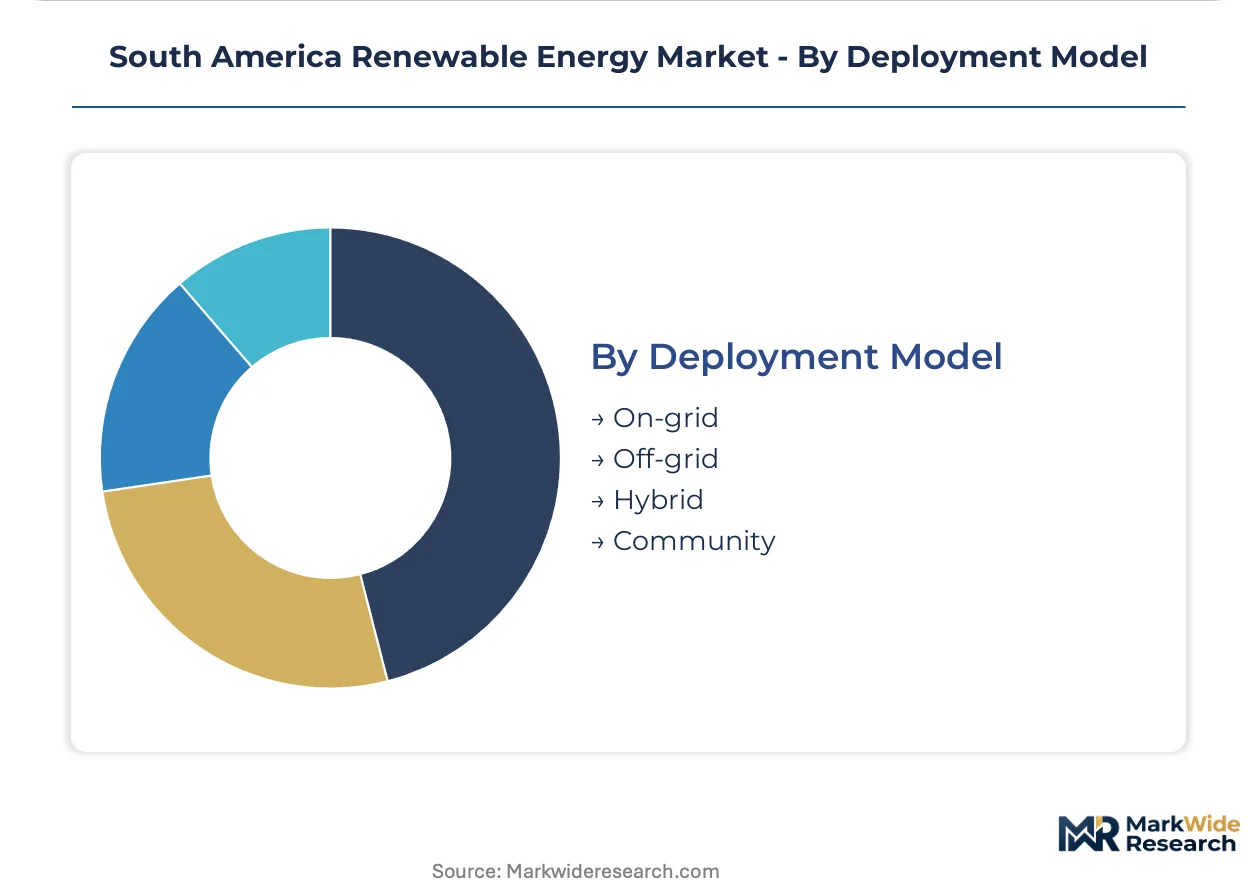
Grid connection status determines revenue predictability, with on-grid projects accessing auction-backed tariffs while off-grid installations serve isolated mining and agricultural operations.
- On-grid:Utility-scale solar and wind connect to national transmission networks under regulated auction contracts or merchant market participation. ANEEL's interconnection queue backlog extends commissioning timelines for new entrants.
- Hybrid:Solar-plus-storage configurations in Brazil's northeast capture evening peak pricing premiums as battery costs decline. Chilean mining operations specify hybrid systems for 24/7 renewable supply without grid dependence.
- Off-grid:Diesel displacement projects serve remote agricultural processing and indigenous communities in Amazonian Brazil and Patagonian Argentina. Mini-grid tariffs exceed national average rates due to isolation premiums.
- Community:Shared solar arrangements allow multiple commercial tenants to aggregate demand and share net metering credits. Regulatory frameworks remain underdeveloped outside Brazil's distributed generation regulations.
On-grid deployment accounts for the predominant share; hybrid configurations are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santiago anchors renewable energy deployment across South America through its concentration of mining sector procurement headquarters and Chile's Ministry of Energy carbon neutrality mandates. The city's financial district structures power purchase agreements for Antofagasta copper operations while serving as coordination hub for Magallanes wind-to-hydrogen pilot projects.
Brazil
Mining operations in Minas Gerais and Pará states drive bifacial solar procurement for 25-year power purchase agreements. ANEEL governs distributed generation net metering rules that accelerate rooftop deployment across São Paulo industrial zones. The northeastern wind belt in Rio Grande do Norte and Ceará suffers periodic curtailment due to inadequate HVDC transmission capacity to southeastern demand centers.
Chile
Copper producers in Antofagasta and Coquimbo regions optimize cost and disclosure outcomes through energy attribute certificate unbundling from physical power contracts. The Ministry of Energy implements binding carbon neutrality targets compelling mining sector procurement shifts toward renewable supply. Atacama Desert irradiance supports capacity factors exceeding 30% for photovoltaic plants, reducing levelized costs below fossil alternatives.
Argentina
The Pampas region hosts anaerobic digester projects processing agricultural waste for distributed generation. The Secretariat of Energy administers RenovAr auction mechanisms mandating long-term contract tenors that de-risk project finance for international investors. Macroeconomic volatility freezes residential solar deployment despite favorable solar resources in northwestern provinces.
Colombia
Andean region hydropower modernization prioritizes turbine efficiency upgrades at existing facilities over greenfield development due to environmental licensing constraints. The mining sector in Antioquia and Cundinamarca departments procures renewable supply to satisfy corporate sustainability commitments. Grid interconnection queues extend project commissioning timelines, inflating carrying costs for new entrants.
South America Renewable Energy Market Competitive Landscape
Capital-heavy integrated utilities compete with asset-light renewable developers for grid-scale project awards across South America. The market consolidates around balance-sheet capacity to absorb long-dated power purchase agreement offtake risk. Three archetypes dominate: European-headquartered majors leveraging integrated development platforms, Latin American utilities with deep regulatory relationships, and independent power producers specializing in hybrid solar-plus-storage configurations. Competitive intensity centers on strategic partnerships with mining sector offtakers and geographic expansion into reform-driven markets.
Among European-headquartered majors, Enel Green Power S.p.A. and Iberdrola S.A. occupy positions reflecting integrated platform scale across Brazil and Chile. AES Andes S.A. anchors the Latin American utility tier through concentrated exposure to Chilean market dynamics. Statkraft exemplifies the independent power producer archetype with European capital backing regional expansion. These entities represent varying approaches to capturing premium pricing for dispatchable generation amid intermittent solar and wind saturation.
| Leading Market Players |
|---|
| Enel Green Power S.p.A. |
| Iberdrola S.A. |
| ENGIE Brasil Energia S.A. |
| Neoenergia S.A. |
| AES Andes S.A. |
| Statkraft |
| EDF Renewables América Latina |
| Mainstream Renewable Power |
| Brookfield Renewable Partners |
| Others |
Value Network & Pricing Analysis
Backward integration into polysilicon and battery cell production anchors supply security for developers pursuing hybrid solar-plus-storage configurations across Brazil and Chile. This upstream control insulates project economics from module import tariff volatility while capturing margin pools that would otherwise accrue to Chinese equipment suppliers.
Pricing Analysis
Value-based pricing tied to firm capacity guarantees anchors contract structures as grid operators prioritize dispatchable generation over intermittent output. Three-tier pricing stratifies across premium hybrid-plus-storage, standard utility-scale solar, and economy wind-without-transmission, with mining sector offtakers absorbing the top tier for 24/7 renewable supply. Cost compression in standard solar runs through module oversupply and inverter commoditization. Industrial miners exhibit lowest price sensitivity; residential distributed generation adopters in São Paulo face highest sensitivity due to upfront capital requirements.
Supply Chain Analysis
Regional distribution centers in São Paulo and Santiago coordinate hub-and-spoke logistics for photovoltaic modules and battery containers arriving through Pacific and Atlantic ports. Manufacturing concentrates in China for crystalline silicon cells, South Korea for lithium-ion battery cells, and Brazil for balance-of-system steel structures. Polysilicon and rare earth magnet supply rests on concentrated Chinese refining capacity. Single-source vulnerability in semiconductor-based power electronics creates procurement risk for inverter and battery management systems. Distribution runs through EPC contractor networks with established ANEEL and Ministry of Energy permitting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photovoltaic-plus-battery hybrid systems are displacing standalone solar and wind as the baseline technology configuration, forcing legacy developers to retrofit or lose dispatchable premium pricing.
For Market Incumbents: Deploy hybrid co-location engineering capabilities to defend auction competitiveness against pure-play solar entrants. AES Andes and Enel Green Power should accelerate battery integration into existing Chilean solar portfolios before grid operators mandate storage for firm capacity qualification. Consolidate control over southeastern Brazil transmission access rights to preempt curtailment risk in the northeastern wind belt. For New Entrants and Emerging Players: Mid-market Argentine manufacturers underserved by direct corporate PPAs represent the most penetrable buyer archetype. Retail energy providers can aggregate distributed generation portfolios for SME offtakers in Córdoba and Rosario industrial corridors. A partnership-first entry model with established local developers navigates RenovAr auction complexity faster than greenfield subsidiary establishment. For Investors and Strategic Acquirers: Exit pathways concentrate in utility-scale hybrid asset acquisitions by European majors seeking South American platform scale. Long-term viability hinges on developers' ability to secure mining sector offtake relationships before carbon neutrality mandates saturate premium contract pools. Watch for ANEEL interconnection queue reform as the signal indicating whether Brazilian project timelines compress or extend.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Plus-Storage Buildout | Captures evening peak pricing premiums as ANEEL prioritizes firm capacity qualifications. |
| Backward Integration into Battery Supply | Reduces exposure to lithium-ion cell import tariffs and secures project completion timelines. |
| Mining Sector PPA Origination | Locks in 15-20 year offtake under Chile's Ministry of Energy carbon neutrality mandates. |
| Transmission Access Rights Consolidation | Preempts curtailment losses in Brazil's northeastern wind belt through HVDC corridor control. |
| Green Hydrogen Pilot Development | Creates anchor demand for stranded Magallanes wind capacity with maritime fuel applications. |
Research Methodology
Document review covered ANEEL regulatory filings, Chile Ministry of Energy auction results, and IEA renewable investment databases, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Brazil, Chile, and Argentina. Secondary validation drew from SEC filings of listed developers, EIA international energy statistics, and project finance database tracking. Bottom-up capacity addition modeling and top-down investment flow analysis were triangulated for consistency.
Historical auction award patterns were cross-referenced against panel input from developer executives and infrastructure fund managers to calibrate deployment assumptions across the analysis window. Segmentation dimensions modeled include generation technology, project scale tier, regulatory framework, and regional grid type. CAGRs were derived from fitted growth curves incorporating module cost decline trajectories and mining sector procurement mandate enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Argentine macroeconomic stability and Brazilian transmission expansion execution. Forecasts reflect documented assumptions on policy continuity and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Europe Biomethane Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
PV Water Heater Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Rectenna Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Renewable Energy Enclosures Market