
 India Residential Solar Inverter Market | 2026-2036
India Residential Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
India Residential Solar Inverter Market Foresight
BIS certification under IS 16221 is rotating vendor eligibility, disqualifying uncertified imports from large-scale residential tenders. Delta Electronics leverages its captive testing infrastructure to fast-track compliance cycles. Luminous anchors its position through deep distribution in Tier-2 and Tier-3 towns. Sungrow Power Supply competes on cost-optimized string inverter platforms tailored to Indian voltage conditions.
A residential solar inverter converts direct current from rooftop photovoltaic arrays into grid-synchronized alternating current at 230V single-phase or 415V three-phase output, with maximum power point tracking algorithms optimizing harvest across variable irradiance. String inverters dominate volume shipments due to lower per-watt installed cost, while hybrid inverters capture expanding margin pools as battery-ready configurations gain preference among villa and row house owners seeking backup resilience. Microinverters remain niche, constrained by price sensitivity in apartment deployments where module-level electronics face payback period scrutiny.
MNRE's ALMM mandate and BIS technical standards govern product eligibility for subsidy-linked residential installations, while state electricity regulatory commissions enforce net metering caps that directly constrain addressable demand. CEA grid connectivity regulations and state-level open access rules further segment where behind-the-meter solar can operate without wheeling charges. Stakeholders must track which states preserve net metering parity versus those shifting toward gross metering or capacity-based restrictions that alter inverter sizing economics.
Market Dynamics
MNRE's ALMM mandate is compressing import-dependent supply chains toward domestic assembly, while state-level net metering policy fragmentation is redrawing demand geography across Maharashtra, Gujarat, and Karnataka clusters.
Growth Catalysts
- PLI scheme for domestic manufacturing:MNRE's production-linked incentive is redirecting capital toward local inverter assembly, shortening lead times for residential tenders.
- Rooftop installations in suburban housing colonies:Gated community procurement is aggregating demand into volume contracts that favor standardized string inverter platforms.
- Net metering policy preservation:State electricity regulatory commissions in western and southern India maintain behind-the-meter parity, sustaining inverter sizing economics for villa owners.
Market Restraints
- Import component concentration:Power semiconductor and capacitor supply remains concentrated in East Asian foundries, exposing domestic assemblers to input cost volatility.
- BIS certification timeline:IS 16221 compliance cycles extend vendor qualification periods, freezing uncertified competitors from subsidy-linked procurement channels.
- Grid-tied string inverter substitution:Hybrid inverter platforms with battery-ready architectures threaten pure grid-tied models in premium residential segments.
Strategic Opportunities
- Tier-2 and Tier-3 town penetration:Distribution infrastructure gaps in Madhya Pradesh, Rajasthan, and Uttar Pradesh create whitespace for localized service networks.
- CEA grid connectivity regulation alignment:Anticipated technical standards for smart inverter functionality will favor early movers with embedded communications hardware.
- Hybrid-battery convergence:Lithium-ion storage integration with residential inverters opens margin pools among row house owners seeking backup resilience.
Industry Challenges
- Power electronics engineering scarcity:MPPT algorithm development and thermal management design talent concentrates in Bengaluru and Pune, constraining expansion timelines for new entrants.
- Legacy net metering reconfiguration:States shifting toward gross metering or capacity-based restrictions force inverter OEMs to resize product portfolios mid-cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Residential Solar Inverter Market |
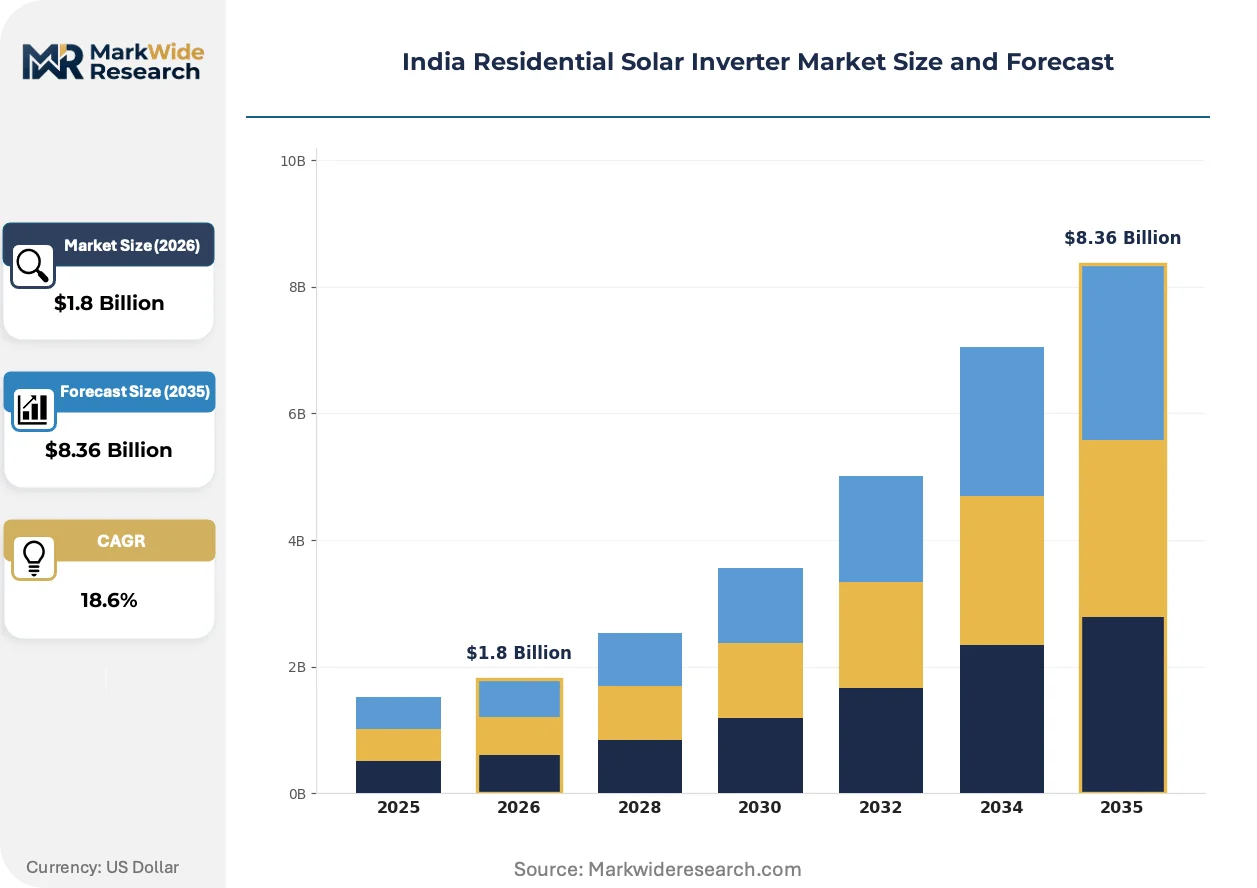
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Power Optimizers, Hybrid Inverters Installation Type: Roof-mounted, Ground-mounted, Off-grid, Grid-tied End User: Residential Buildings, Apartments, Villas, Row Houses Technology: Solar PV, Net Metering, Battery Storage, Smart Inverter |
| Companies Covered | Siemens, Mitsubishi Electric, Huawei Technologies, Luminous, Delta Electronics, Sungrow Power Supply, ABB, UTL, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Residential Solar Inverter Market Shifts & Advancements
Product architecture is splitting between cost-optimized string platforms and premium hybrid systems, while regulatory compliance is becoming a competitive moat rather than a baseline requirement.
Module-level power electronics is fragmenting residential system design. Microinverters and power optimizers enable per-panel MPPT tracking, improving harvest in partially shaded villa rooftops. Premium row house developers in Bengaluru and Pune are specifying these architectures despite per-watt cost premiums. The technology is fragmenting procurement patterns away from centralized string inverter tenders toward distributed electronics sourcing.
BIS technical standards under IS 16221 are hardening product eligibility gates. The mandatory certification regime disqualifies uncertified imports from MNRE subsidy-linked installations. Domestic assemblers with captive testing infrastructure are compressing compliance cycles. Maharashtra and Gujarat regulatory commissions reference these standards in tender specifications, accelerating certified product preference.
Apartment complex procurement is aggregating through developer-channel partnerships rather than individual homeowner decisions. Gated community management associations in Hyderabad and Chennai are negotiating bulk inverter supply contracts with installation firms. This channel consolidation is compressing price transparency and favoring vendors with integrated EPC capabilities over pure equipment suppliers.
India Residential Solar Inverter Market Segmentation
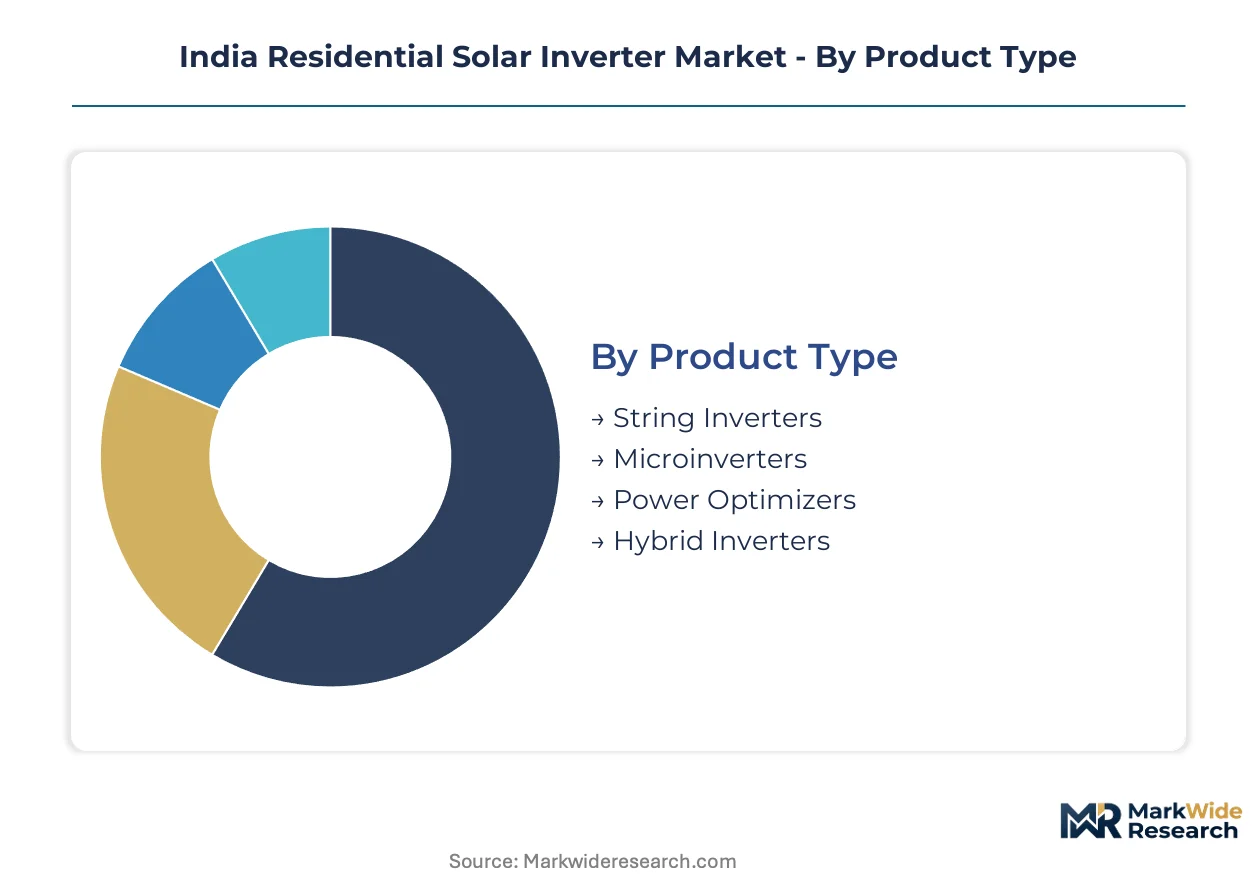
Segmentation in the India residential solar inverter market reveals how procurement patterns diverge across housing typologies, installation configurations, and grid-interconnection regimes. Each dimension carries distinct margin structures and regulatory exposure that reshape vendor positioning.
Product Type:
Hybrid inverter architectures are displacing pure grid-tied platforms across premium residential segments, while string inverters face margin compression from battery-ready substitutes.
- String Inverters:Centralized DC-to-AC conversion platforms deploy single MPPT channels across series-connected PV strings. Maharashtra and Gujarat villa clusters source these for cost-optimized rooftop arrays where shading is minimal and net metering economics favor lower capital outlay.
- Hybrid Inverters:Bidirectional power electronics integrate battery charge controllers with grid-synchronization capability, enabling backup resilience during outages. Row house developers in Bengaluru and Pune specify these for lithium-ion storage pairing despite per-watt premiums, driven by CEA grid connectivity regulations that incentivize dispatchable behind-the-meter generation.
- Microinverters:Module-level AC conversion eliminates string-level mismatch losses in partially shaded apartment rooftops.
- Power Optimizers:DC-conditioning units at panel level enable per-module MPPT tracking with centralized inverter cost structures.
String inverters retain volume leadership across subsidy-linked procurement channels; hybrid inverters hold the steepest expansion curve among battery-ready configurations.
Installation Type:
Roof-mounted configurations dominate addressable volume, though ground-mounted systems gain traction where plot ratios permit dedicated solar structures.
- Roof-mounted:Elevated racking on pitched or flat residential rooftops constitutes the default deployment mode for Indian housing stock. Karnataka and Tamil Nadu regulatory commissions reference these installations in net metering tariff orders that preserve behind-the-meter parity for single-family dwellings.
- Grid-tied:Synchronous inverters without battery buffering maximize export revenue under favorable net metering regimes. Maharashtra SERC maintains these economics for villa owners despite neighboring states shifting toward gross metering structures.
- Ground-mounted:Elevated arrays on residential plots require larger land footprints rarely available in urban density.
- Off-grid:Standalone systems with battery storage serve electrification gaps in rural Madhya Pradesh and Rajasthan where grid extension lags.
Roof-mounted systems capture the deepest procurement volume; grid-tied configurations face the most acute policy reconfiguration risk.
End User:
Villa owners command the highest per-system inverter sizing, while apartment complexes aggregate demand through developer-channel consolidation.
- Villas:Independent single-family dwellings with unobstructed rooftop access deploy 5-10 kW inverter systems. Gujarat gated communities specify these for individual net metering connections where SERC regulations preserve export parity.
- Row Houses:Attached dwellings with shared wall structures and limited roof area favor compact hybrid inverter platforms. Hyderabad developers negotiate bulk supply contracts for these configurations through management association procurement.
- Residential Buildings:Multi-unit structures with common area solar installations split generation across individual meters.
- Apartments:High-rise dwellings with constrained roof-to-unit ratios face payback period scrutiny on module-level electronics.
Villas retain the highest per-system value; row houses are climbing fastest through developer-channel aggregation.
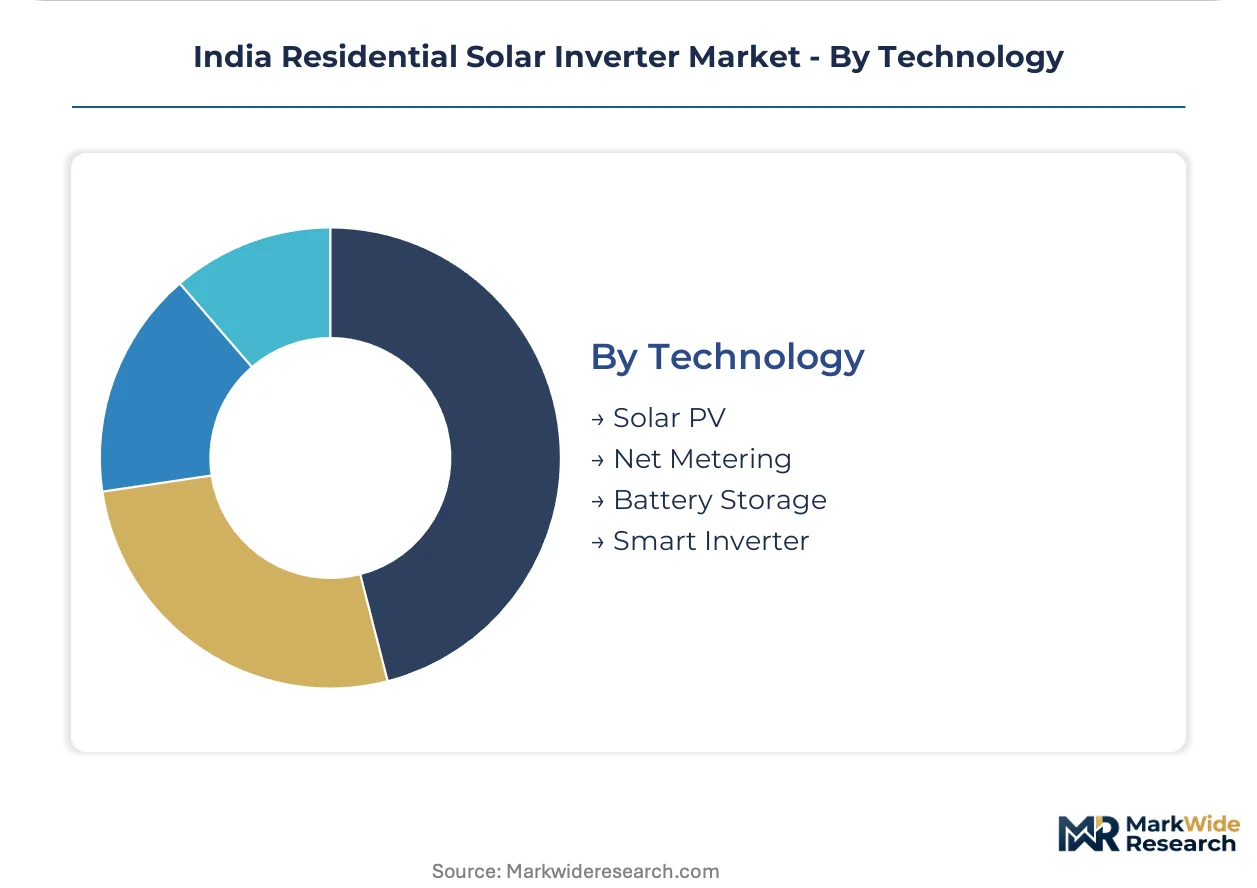
Technology:
Smart inverter functionality is becoming a regulatory mandate rather than a premium feature, while battery storage integration opens new margin pools.
- Solar PV:Photovoltaic-to-AC conversion remains the core technical function across all inverter categories. BIS IS 16221 certification governs these products for MNRE subsidy eligibility, with domestic assemblers compressing compliance timelines through captive testing infrastructure.
- Smart Inverter:Embedded communications and grid-support functions enable remote monitoring and voltage regulation. CEA technical standards anticipated for these capabilities will favor early movers with integrated hardware-software stacks.
- Net Metering:Bi-directional metering infrastructure determines inverter sizing economics through export tariff structures.
- Battery Storage:Lithium-ion integration with hybrid platforms creates dispatchable residential generation.
Solar PV conversion retains foundational volume; smart inverter functionality is gaining share fastest through regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential inverter procurement concentrates in suburban villa clusters and gated housing developments where net metering economics remain viable. State-level regulatory fragmentation is redrawing demand geography across western and southern India.
Maharashtra
Mumbai-Pune corridor villa owners drive 5-10 kW system deployments through Maharashtra State Electricity Regulatory Commission's preserved net metering framework. MSEDCL tender specifications reference BIS IS 16221 certification, accelerating certified product preference among Nashik and Nagpur distributors.
Gujarat
Ahmedabad-Surat gated communities aggregate bulk procurement through developer-channel partnerships under Gujarat Urja Vikas Nigam's rooftop subsidy program. Gujarat Energy Development Agency technical norms enforce grid-synchronization standards that favor domestic assemblers with captive testing infrastructure.
Karnataka
Bengaluru row house developers specify hybrid inverter platforms for lithium-ion storage pairing under Karnataka Electricity Regulatory Commission's gross metering transition timeline. Electronics engineering talent concentrates in Bengaluru's Whitefield and Electronic City corridors, compressing product development cycles for MPPT algorithm refinement.
Tamil Nadu
Chennai apartment management associations negotiate centralized inverter supply for common-area solar installations through Tamil Nadu Generation and Distribution Corporation's net metering orders. Coimbatore and Madurai Tier-2 markets show whitespace for localized service network expansion.
Telangana
Hyderabad's western suburb villa clusters deploy string inverter arrays under Telangana State Electricity Regulatory Commission's behind-the-meter parity regime. Cyberabad developer partnerships are consolidating procurement into volume contracts that favor integrated EPC-inverter vendors.
India Residential Solar Inverter Market Competitive Landscape
Player mix skews toward diversified power electronics conglomerates with captive certification infrastructure and domestic distribution depth. Market structure shows moderate concentration at the premium tier with fragmented competition in subsidy-linked volume segments. Two strategic archetypes dominate: multinational technology licensors with India-specific product variants, and domestic assemblers leveraging PLI scheme incentives for local manufacturing scale. Competitive moves center on BIS compliance acceleration and hybrid-battery portfolio diversification.
Among multinational technology providers, Delta Electronics and Sungrow Power Supply occupy positions exemplifying the premium-tier archetype with cost-optimized platform strategies. Luminous anchors the domestic distribution-focused segment through Tier-2 and Tier-3 town penetration. Siemens, ABB, and Schneider Electric represent diversified industrial conglomerates with power electronics portfolios spanning residential solar applications. Mitsubishi Electric and Huawei Technologies sit within the technology-licensing tier with string and hybrid inverter architectures. UTL occupies a position in the domestic assembly segment with localized manufacturing alignment to ALMM mandate requirements.
| Leading Market Players |
|---|
| Siemens |
| Mitsubishi Electric |
| Huawei Technologies |
| Luminous |
| Delta Electronics |
| Sungrow Power Supply |
| ABB |
| UTL |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with East Asian power semiconductor foundries lock in component supply for domestic inverter assemblers while anchoring price visibility across volatile input cycles. These arrangements shield Maharashtra and Gujarat vendors from spot-market IGBT and MOSFET swings that would otherwise compress margins on subsidy-linked residential tenders.
Pricing Analysis
Cost-plus contracts indexed to copper and rare earth element benchmarks dominate procurement between domestic assemblers and Tier-1 component suppliers. Three-tier pricing structure across BIS-certified premium, ALMM-compliant standard, and uncertified economy levels separates vendors competing for villa owner tenders from those chasing apartment bulk contracts. Cost compression in string inverter tiers is intensifying as hybrid-battery platforms capture margin pools among Bengaluru row house developers. Apartment management associations exhibit acute price sensitivity per-watt, while villa owners prioritize certification grade and after-sales service bundling over unit economics.
Supply Chain Analysis
Port congestion on Nhava Sheva-Mundra lanes and container availability crunches from Shanghai-Singapore trade corridors are extending inbound lead times for power semiconductor modules. Manufacturing concentration in China, Taiwan, and South Korea feeds India's domestic assembly lines with IGBTs, capacitors, and magnetic components. Single-source vulnerability in high-voltage MOSFET supply from Taiwanese foundries exposes assemblers to allocation risk during demand spikes. Distribution runs through state-level EPC contractor networks that aggregate inverter procurement for gated community tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams from remote monitoring subscriptions and annual maintenance contracts are expanding faster than hardware sales among villa and row house segments. This recurring layer justifies upfront pricing premiums for vendors with embedded communications hardware.
For Market Incumbents: Shield margin pools in hybrid-battery configurations by accelerating BIS IS 16221 certification for lithium-ion integration controllers before regulatory mandates harden. Deepen backward integration into power semiconductor module testing to compress compliance timelines against emerging domestic competitors. Channel control through exclusive EPC partnerships in Gujarat and Maharashtra gated communities blocks price-transparent procurement aggregation. For New Entrants and Emerging Players: BIS certification fast-track through captive electromagnetic compatibility testing infrastructure opens subsidy-linked procurement channels frozen to uncertified imports. Tier-2 town whitespace in Madhya Pradesh and Rajasthan offers penetrable distribution gaps where localized service networks outperform incumbent reach. Developer-channel partnerships for Hyderabad and Chennai apartment management associations provide concentrated volume without fragmented homeowner sales cycles. For Investors and Strategic Acquirers: Domestic assemblers with PLI scheme alignment and captive BIS testing infrastructure represent acquisition targets with regulatory moats deepening over the analysis window. Long-term viability hinges on battery storage integration capabilities and smart inverter functionality ahead of CEA technical standards. The signal to watch is Karnataka Electricity Regulatory Commission's gross metering transition timeline, which would force portfolio resizing and compress pure grid-tied inverter valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Inverter Certification | CEA grid connectivity regulations will mandate embedded communications, favoring early hardware-software integrators. |
| Hybrid-Battery Platform Launch | Lithium-ion storage pairing captures margin pools among Bengaluru and Pune row house developers seeking backup resilience. |
| Tier-2 Distribution Expansion | Madhya Pradesh and Rajasthan whitespace rewards localized service networks with faster response than incumbent reach. |
| Backward Integration into Testing | Captive BIS IS 16221 compliance infrastructure compresses qualification cycles and freezes out import-dependent competitors. |
| Developer-Channel Partnership | Cyberabad and Hyderabad gated community aggregation consolidates procurement into volume contracts with price opacity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with MNRE policy officers, state electricity regulatory commission technical staff, EPC contractor procurement heads, and inverter OEM product managers; and secondary validation through CEA grid connectivity filings, state SERC tariff orders, BIS certification registries, and MNRE ALMM-approved models lists. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against state-level rooftop installation targets anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, housing typology, grid-interconnection regime, and state regulatory cluster. CAGRs were derived from regression analysis of historical procurement velocity against policy incentive trajectories. Forecast inputs incorporated MNRE PLI scheme disbursement schedules and anticipated CEA smart inverter technical standards without year-specific anchoring.
Underlying assumptions cover sustained net metering parity in Maharashtra, Gujarat, and Telangana, with deviation risk concentrated in Karnataka's gross metering transition and BIS certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Solar PV Carport Market