
 Rooftop Solar Panels Market | 2026-2036
Rooftop Solar Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Rooftop Solar Panels Market Insights
The installer-dealer channel is fragmenting as vertically integrated manufacturers bypass traditional distributors to sell directly to commercial developers and EPC contractors. JinkoSolar Holding Co., Ltd. leverages its integrated wafer-cell-module capacity to control cost positions across residential and utility-scale rooftop projects. LONGi Green Energy Technology Co. Ltd. anchors the premium monocrystalline segment through proprietary silicon ingot technology and aggressive capacity expansion. Trina Solar competes on module efficiency and tracker compatibility, sustaining market presence across Asia-Pacific and European rooftop markets.
Rooftop solar panels are photovoltaic modules engineered for building-integrated or building-applied installation, typically rated between 300W and 700W per module with tempered glass fronts and aluminum frames designed for structural load compliance. These systems convert incident solar irradiance into direct current electricity for on-site consumption or grid export, reducing facility-level energy procurement costs and Scope 2 emissions. Monocrystalline panels dominate installed value due to superior conversion efficiency and declining wafer costs, while bifacial modules represent the fastest-growing product category as commercial operators capture rear-side albedo gains. Grid-tied technology leads deployment volumes, though hybrid configurations with battery storage are gaining share where time-of-use tariffs and backup power requirements reshape project economics.
Regulatory frameworks including the EU Green Deal, F-Gas Regulation, and national building codes across Germany, France, and Italy mandate minimum renewable energy contributions for new construction and major renovations, directly stimulating rooftop solar specification. The EPA and state-level public utility commissions in the United States enforce net metering standards and interconnection protocols that determine project payback periods and developer participation. Stakeholders must monitor evolving tariff structures and local content requirements as policymakers balance grid stability targets against deployment acceleration.
Market Dynamics
Feed-in tariff reforms across Germany and Japan have fundamentally altered project economics, redirecting developer focus from grid-export maximization toward self-consumption optimization and behind-the-meter storage integration.
Growth Catalysts
- Net Metering Mandates:State-level policies in Maharashtra and Gujarat drive residential adoption by enabling sell-back arrangements that shorten payback periods for distributed installations.
- Module Price Compression:Declining polysilicon and wafer costs reduce system-level capex barriers for commercial real estate developers evaluating multi-tenant rooftop retrofits.
- Building-Integrated Photovoltaics:Architectural integration mandates in EU member states under the Green Deal stimulate specification of solar-active facades and canopy structures alongside traditional rooftop arrays.
Market Restraints
- Interconnection Backlogs:Distribution grid capacity constraints and utility review timelines in jurisdictions with fragmented permitting authorities delay project commissioning.
- Polysilicon Supply Concentration:Ingot and wafer production clusters in Xinjiang create geopolitical and forced-labor compliance exposure for module assemblers sourcing globally.
- Aluminum Tariff Volatility:Frame and mounting structure costs fluctuate with trade policy shifts affecting extruded aluminum imports from major supplying regions.
Strategic Opportunities
- Agrisolar Convergence:Dual-use installations combining elevated photovoltaic canopies with crop cultivation or livestock grazing unlock marginal land value for rural property owners.
- Time-of-Use Arbitrage:Hybrid AC-coupled battery systems paired with rooftop arrays capture peak-demand rate differentials in California and Australian jurisdictions with dynamic tariff structures.
- Installer Certification Gaps:Specialized training and credentialing programs for commercial-scale rooftop projects address workforce shortages in underpenetrated secondary cities across India and Southeast Asia.
Industry Challenges
- Structural Load Assessment:Aging building stock requires costly engineering review and reinforcement to support ballasted or penetrating mounting systems on commercial rooftops.
- Fire Safety Compliance:Rapid shutdown device configuration and rooftop access pathway mandates under NEC Article 690 add design complexity and inspection failure risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rooftop Solar Panels Market |
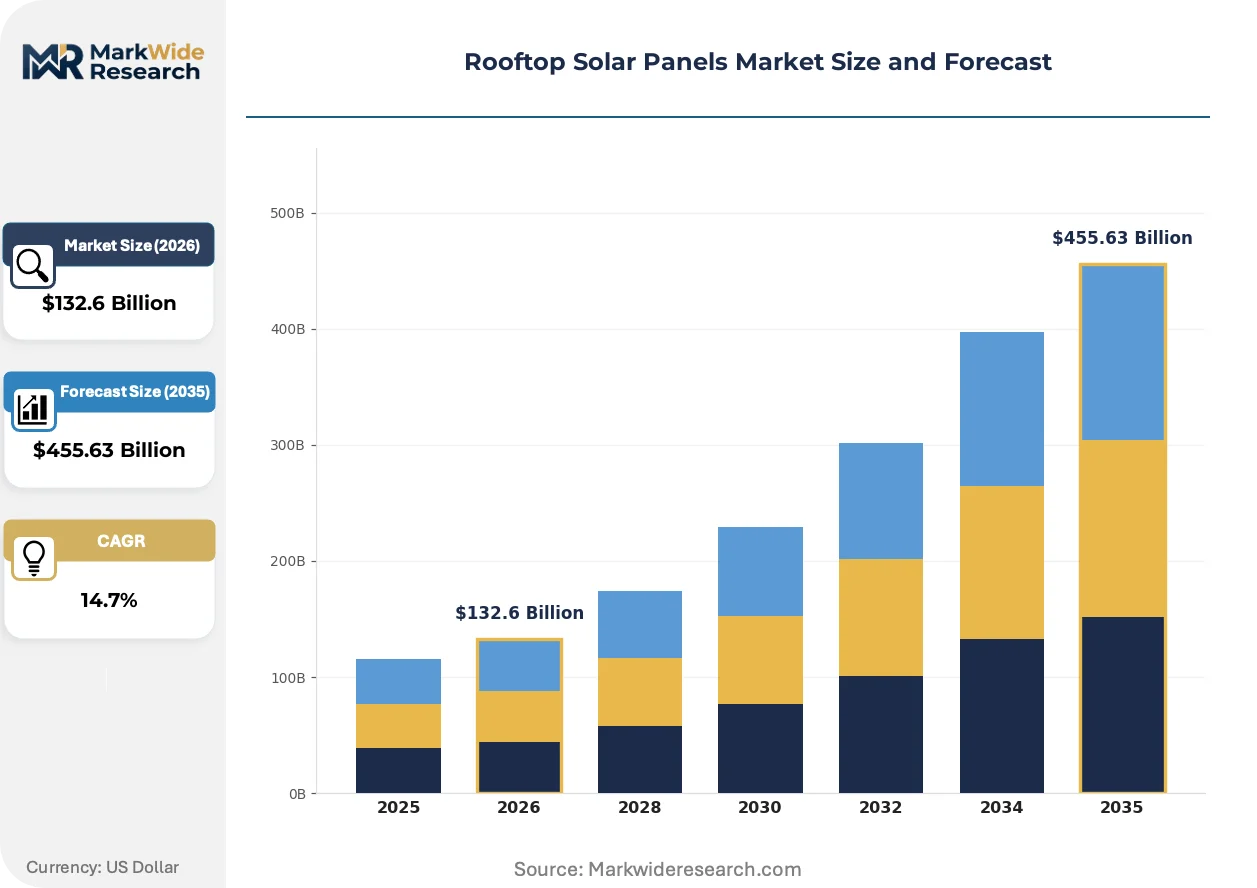
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $455.63 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Agricultural Technology: Grid-Tied, Off-Grid, Hybrid, Net Metering Component: Inverters, Mounting Systems, Batteries, Charge Controllers |
| Companies Covered | Canadian Solar Inc., Trina Solar, JinkoSolar Holding Co., Ltd., SunPower Corporation, Sharp Corporation, LONGi Green Energy Technology Co. Ltd., JA Solar Co., Ltd., Tata Power Solar Systems Limited, Momentum Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rooftop Solar Panels Market Trends and Innovations
Module-level power electronics and bifacial cell architectures are compressing balance-of-system costs while enabling higher energy density from constrained rooftop footprints.
TOPCon cell technology, which deposits a thin tunneling oxide layer between silicon and polysilicon contacts to reduce recombination losses, is rendering obsolete conventional PERC architectures in commercial rooftop specifications. EPC contractors in Germany and Japan now default to n-type TOPCon modules for projects above 500 kW. The efficiency gain of 1-2 percentage points is rendering obsolete previous calculations of viable project scale for constrained rooftops.
The EU F-Gas Regulation phase-down schedule restricts hydrofluorocarbon use in manufacturing processes and end-of-life module recovery, compelling module producers to redesign lamination and encapsulant chemistries. Production lines in France and Italy face retrofit deadlines that compress capital planning horizons. Bifacial glass-glass modules with fluorine-free backsheet alternatives are gaining specification share in tenders with explicit environmental product declaration requirements.
Direct manufacturer-to-developer contracting is displacing traditional distributor intermediaries for commercial projects above 1 MW. Vertically integrated cell-module producers now maintain in-house project development arms that compete with independent EPCs for origination. This channel compression is most visible in India, where state nodal agencies conduct bulk tenders favoring vendors with captive manufacturing and installation capabilities.
Rooftop Solar Panels Market Segmentation
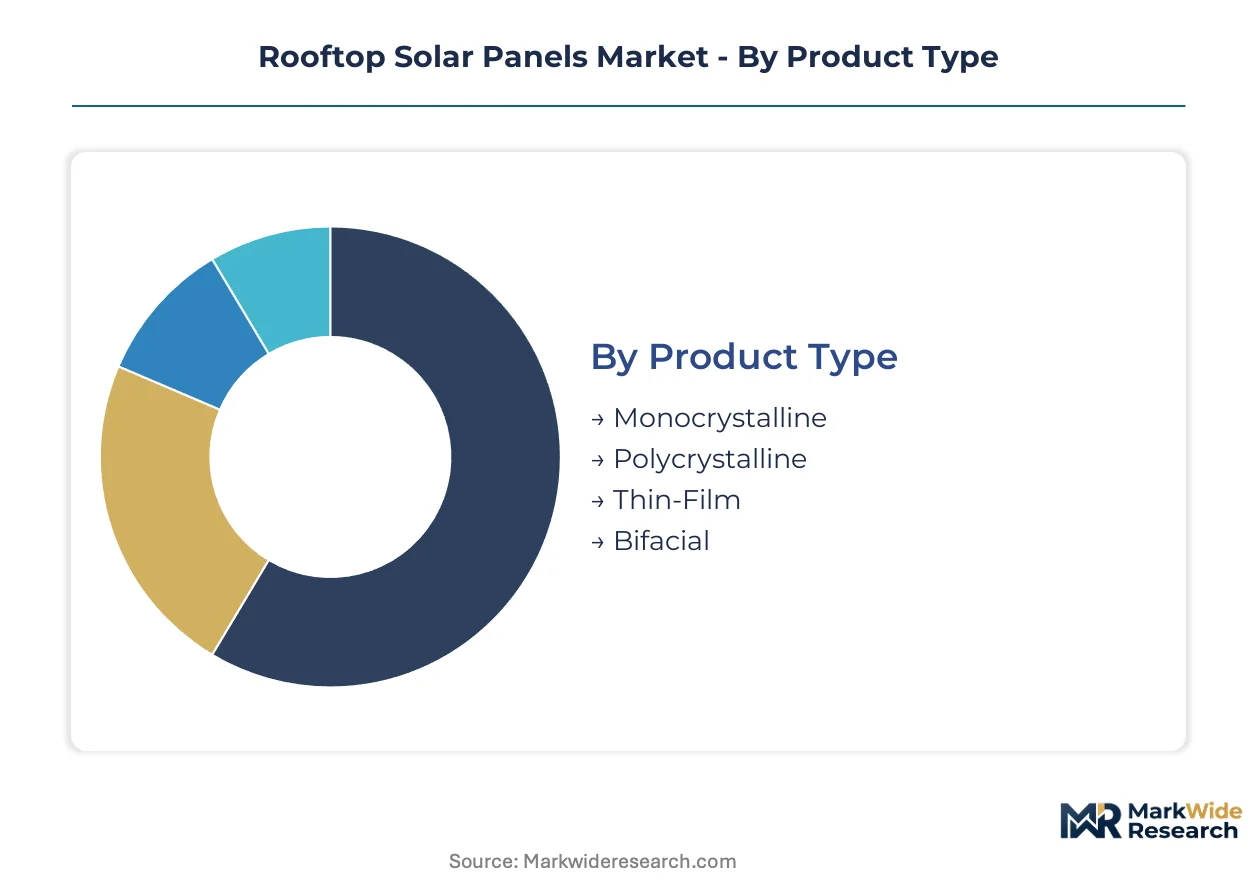
Technology heterogeneity across the rooftop solar panels market creates distinct procurement patterns. Module efficiency tiers, mounting configurations, and grid interconnection modes each command separate pricing dynamics and customer decision frameworks.
Product Type:
Mature crystalline technologies anchor installed volumes while emerging architectures capture premium specification share.
- Monocrystalline:Single-crystal silicon wafers deliver conversion efficiencies exceeding 21% in standard test conditions. Commercial developers in Maharashtra and Gujarat specify monocrystalline modules for multi-tenant office retrofits where rooftop area constraints maximize energy density per square meter.
- Bifacial:Glass-glass encapsulation enables rear-side albedo capture, boosting effective yield by 10-20% on reflective commercial rooftops. German EPC contractors now default to bifacial specification for projects above 500 kW under revised self-consumption tariff structures.
- Polycrystalline:Multi-crystal silicon cells trade efficiency for cost position in price-sensitive residential segments.
- Thin-Film:Cadmium telluride and CIGS architectures suit building-integrated applications with weight or flexibility constraints.
Monocrystalline handles the majority of throughput; bifacial is climbing the fastest on specification share.
Application:
Customer archetypes diverge sharply on financing mechanisms, permitting complexity, and operational sophistication.
- Commercial:Multi-tenant office buildings and retail facilities drive aggregated procurement through power purchase agreements. Falling module prices compress payback periods for real estate developers evaluating rooftop retrofits across secondary Indian cities.
- Residential:Single-family homeowners and housing cooperatives rely on net metering sell-back arrangements. State-level mandates in Gujarat and Maharashtra shorten interconnection timelines for distributed installations below 10 kW.
- Industrial:Manufacturing facilities with flat concrete rooftops optimize for self-consumption and peak demand charge reduction.
- Agricultural:Elevated canopy configurations enable dual-use agrisolar deployment on marginal rural land.
Commercial commands the largest addressable revenue pool; agricultural dual-use applications are expanding most quickly as land-value arbitrage strategies mature.
Technology:
Grid interconnection modes reshape project economics through tariff structure exposure and backup power capability.
- Grid-Tied:Direct utility interconnection without storage dominates deployment volumes where net metering remains viable. Feed-in tariff reforms in Germany and Japan have redirected developer focus toward self-consumption optimization within this category.
- Hybrid:AC-coupled battery integration captures time-of-use arbitrage in California and Australian jurisdictions with dynamic rate structures. Fire safety compliance under NEC Article 690 adds design complexity for rooftop installations.
- Off-Grid:Stand-alone systems serve remote agricultural operations and rural electrification programs beyond distribution grid reach.
- Net Metering:Policy-dependent configuration enabling bidirectional electricity flow and sell-back credits.
Grid-tied retains dominant installation share; hybrid configurations are gaining specification momentum fastest where tariff differentials exceed battery cycle economics.
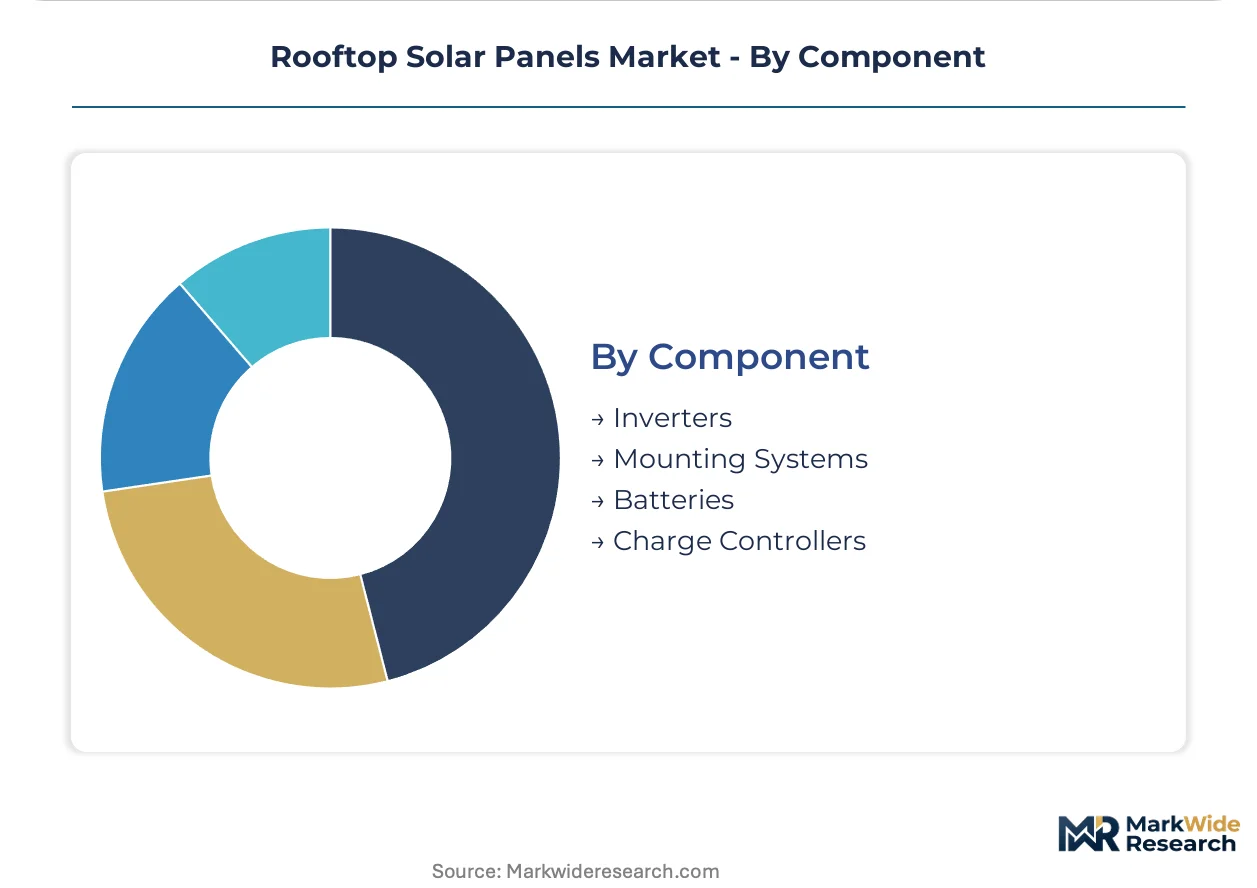
Component:
Balance-of-system procurement is consolidating as module manufacturers extend into in-house component supply.
- Inverters:String and power optimizer architectures convert DC module output to grid-synchronous AC. Module-level power electronics are compressing balance-of-system costs while enabling rapid shutdown compliance.
- Batteries:Lithium-ion storage systems extend self-consumption windows and provide backup power during grid outages. Hybrid configurations gain share where time-of-use tariffs reshape project economics.
- Mounting Systems:Ballasted and penetrating aluminum structures must comply with structural load assessments for aging commercial building stock.
- Charge Controllers:DC voltage regulation devices manage battery charging cycles in off-grid and hybrid configurations.
Inverters absorb the largest component procurement spend; batteries are expanding fastest as storage attachment rates climb in premium commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The HVDC interconnectors linking offshore wind zones to industrial load centers underpin Europe's rooftop solar deployment corridors. India's Green Energy Corridors transmission program channels distributed generation from western states to demand-heavy northern grids.
Germany
Self-consumption optimization drives commercial retrofit activity as feed-in tariff reforms phase out premium export rates. The EU F-Gas Regulation compels module producers to eliminate hydrofluorocarbons from lamination processes. Manufacturing clusters in Saxony and Thuringia retrofit production lines for fluorine-free encapsulants ahead of compliance deadlines.
India
State-level net metering mandates in Maharashtra and Gujarat shorten payback periods for residential installations below 10 kW. The Central Electricity Authority enforces technical standards for distributed generation interconnection through CEA regulations. Ahmedabad and Surat host concentrated EPC contractor networks serving multi-tenant commercial retrofits across Gujarat's industrial corridors.
United States
Time-of-use rate differentials in California drive hybrid storage attachment for commercial peak-shaving applications. The EPA and state public utility commissions enforce net metering standards that determine project economics across jurisdictions. Texas and Arizona secondary cities face installer certification gaps as commercial procurement accelerates beyond trained workforce supply.
Japan
Feed-in tariff expiration for early projects redirects developer focus toward self-consumption and behind-the-meter storage. METI administers grid interconnection protocols that constrain distributed generation export during peak solar hours. Industrial zones in Kyushu and Chubu concentrate manufacturing facility retrofits optimized for captive power consumption.
Australia
Dynamic tariff structures in New South Wales and Victoria reward hybrid AC-coupled battery configurations for time-of-use arbitrage. State-level regulators enforce rapid shutdown compliance under NEC-equivalent standards for rooftop fire safety. Perth and Brisbane commercial districts drive specification of bifacial modules for high-albedo industrial roof surfaces.
Rooftop Solar Panels Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated cell-module producers with captive wafer capacity. Tiered competitive positioning separates premium monocrystalline specialists from scale-driven standard module fabricators. Strategic archetypes include integrated manufacturers controlling upstream silicon through module assembly, and project developers with captive installation arms. Capacity expansion and direct-to-developer channel compression represent dominant competitive moves as distributors lose share to manufacturer-led contracting.
Among integrated Chinese producers, JinkoSolar Holding Co., Ltd., LONGi Green Energy Technology Co. Ltd., and Trina Solar exemplify the scale-driven archetype with in-house wafer-cell-module capacity. These entities anchor the premium efficiency tier through proprietary ingot and cell technologies. Canadian Solar Inc. occupies a position bridging manufacturing scale with project development capabilities. Sharp Corporation and SunPower Corporation represent technology-focused specialists emphasizing module efficiency and architectural integration. Tata Power Solar Systems Limited anchors India-centric deployment with state nodal agency relationships.
| Leading Market Players |
|---|
| Canadian Solar Inc. |
| Trina Solar |
| JinkoSolar Holding Co., Ltd. |
| SunPower Corporation |
| Sharp Corporation |
| LONGi Green Energy Technology Co. Ltd. |
| JA Solar Co., Ltd. |
| Tata Power Solar Systems Limited |
| Momentum Solar |
| Others |
Pricing and Supply Chain Analysis
Xinjiang's polysilicon ingot concentration funnels margin capture toward wafer-cell-module producers with captive upstream capacity, leaving independent distributors and smaller EPCs squeezed between module cost compression and installation labor inflation. This upstream-downstream tension defines competitive economics across residential and commercial rooftop segments.
Pricing Analysis
Volume-discount tiering structures separate utility-scale offtake pricing from commercial project rates and residential single-lot premiums. Three-tier pricing stratifies across premium monocryline efficiency grades, standard PERC-equivalent output, and economy polycrystalline units for price-sensitive rural markets. Cost compression in standard-tier modules intensifies as Chinese wafer producers expand n-type TOPCon capacity ahead of demand curves. Residential single-family buyers in Gujarat and Maharashtra exhibit highest price sensitivity, while German commercial developers with self-consumption mandates absorb premium bifacial premiums for rear-side yield gains.
Supply Chain Analysis
Supplier-financing facilities from integrated Chinese manufacturers now extend 180-day payment terms to EPC contractors in India and Southeast Asia, displacing traditional distributor credit lines. Manufacturing concentration in China, Vietnam, and Malaysia for cell and module assembly draws from polysilicon feedstock anchored in Xinjiang and Inner Mongolia. Single-source vulnerability to forced-labor compliance audits and US Customs detention orders constitutes the dominant structural risk. Distribution runs through direct manufacturer-to-developer contracting for commercial projects above 1 MW, while residential channels retain installer-dealer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified commercial-scale installation capacity trails procurement velocity across secondary Indian cities and US Sun Belt metros, creating a bottleneck that rewards early workforce development investments. This capability gap separates viable expansion from stranded origination capacity.
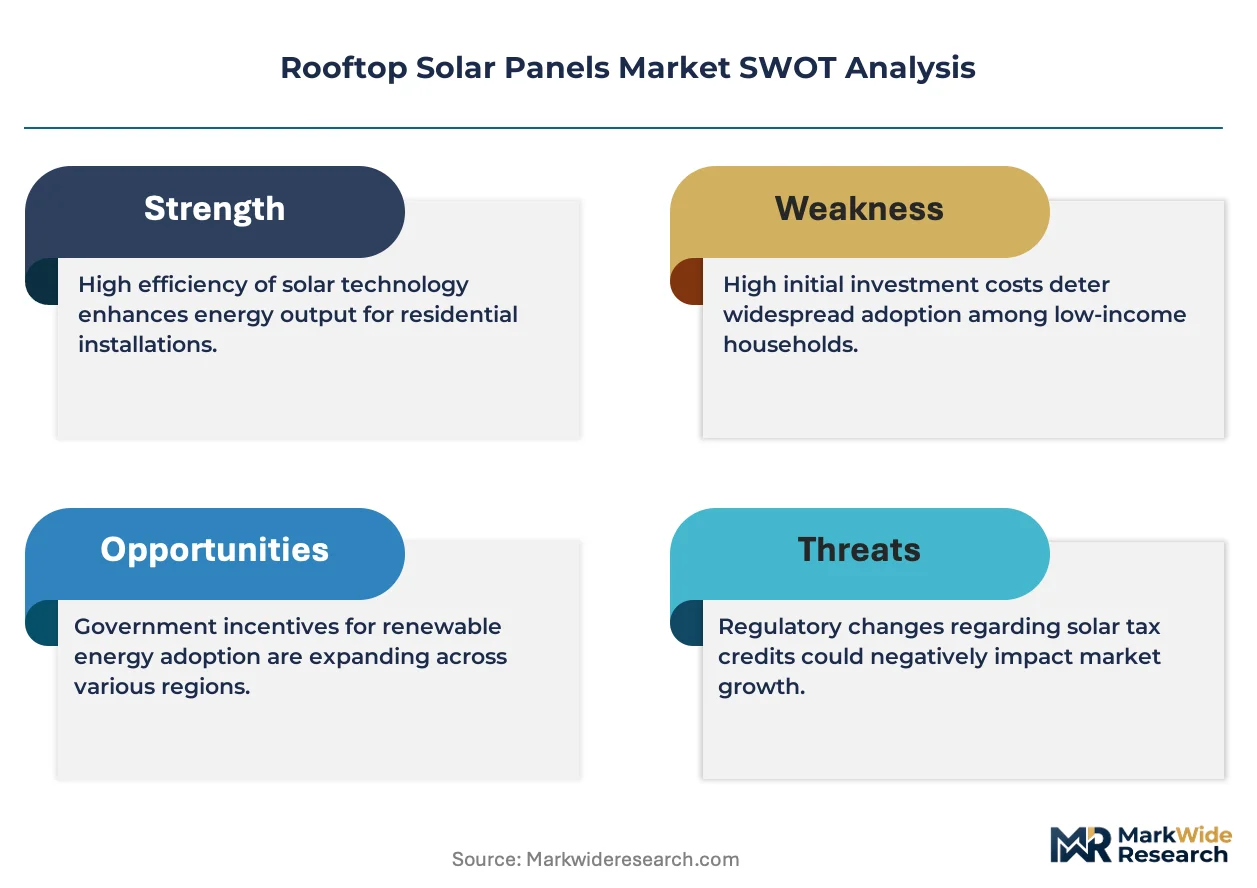
For Market Incumbents: Pre-empt channel compression by acquiring EPC contractors in Gujarat and Maharashtra where state nodal agency tenders favor integrated manufacturing-installation capabilities. Add captive wafer capacity in Southeast Asia to diversify forced-labor compliance exposure away from Xinjiang supply chains. Certification investment in IEC 61215/61730 testing protocols defends position against emerging glass-glass module specialists. For New Entrants and Emerging Players: Build out agrisolar canopy expertise in Maharashtra and Karnataka where marginal land value arbitrage remains underpenetrated by established rooftop specialists. Target commercial real estate developers in secondary Indian cities with design-build offerings that bundle structural engineering with module supply. Go-to-market leverage rests on rapid structural load assessment capabilities that compress permitting timelines for aging building stock retrofits. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed EPC platforms in California and Texas that aggregated residential installer networks during IRA incentive expansion. Long-term viability hinges on storage attachment rate progression as time-of-use tariffs reshape project economics. Watch California NEM 3.0 implementation velocity as the inflection signal for hybrid system specification share across commercial segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Capacity | Captive polysilicon-to-module control insulates margin from Xinjiang supply chain disruptions and US tariff exposure. |
| TOPCon Cell Technology Licensing | n-type tunneling oxide partnerships accelerate efficiency migration for EPC contractors locked into PERC supply agreements. |
| Installer Certification Program Expansion | Specialized commercial rooftop training addresses workforce scarcity in Surat and Ahmedabad industrial corridors. |
| Direct-to-Developer Channel Buildout | Manufacturer-led contracting displaces distributor intermediaries for projects above 500 kW in German and Japanese markets. |
| Fluorine-Free Encapsulant R&D | EU F-Gas Regulation compliance for glass-glass modules secures tender eligibility in French and Italian public procurement. |
Research Methodology
A spread of perspectives from EPC project developers, utility interconnection planners, module procurement managers, and state regulatory affairs leads converged on the working assumptions. Primary interviews across Germany, India, Japan, and the United States were cross-checked against secondary sources including EIA generation databases, IEA renewable energy outlooks, CEA technical standards filings, and FERC interconnection queue data. Bottom-up project pipeline aggregation was reconciled with top-down national installation targets through iterative triangulation.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling rooftop solar deployment by technology type, application segment, grid interconnection mode, and regional regulatory cluster. CAGRs were derived from segmented volume trajectories weighted by module efficiency tier pricing differentials. Forecast inputs incorporated polysilicon capacity expansion schedules, state-level net metering policy trajectories, and aluminum frame cost volatility assumptions.
Practitioners should monitor feed-in tariff reform announcements, interconnection backlog clearance rates, and forced-labor enforcement actions for early signals. Forecasts reflect documented assumptions about module price compression velocity and policy continuity. Macroeconomic deviation, regulatory reversal, or technological substitution beyond TOPCon architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Venezuela Solar Energy Market