
 Frameless Solar Panel Market | 2026-2036
Frameless Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Frameless Solar Panel Market Intelligence
The capital-intensity divergence between integrated glass-module producers and pure-play assemblers is redrawing competitive boundaries in frameless solar manufacturing. LONGi Solar leverages captive wafer and cell capacity to compress unit costs for frameless bifacial lines. Maxeon sustains premium positioning through interdigitated back-contact architectures that eliminate front-side metallization. REC Solar anchors European demand with Tiger series modules engineered for Nordic snow-load conditions.
Frameless solar panels omit traditional aluminum perimeter frames, instead employing laminated tempered glass edges with structural silicone bonding to achieve weight reductions of 15-20% versus framed equivalents. Their primary purpose is to lower rooftop dead loads and accelerate installation on commercial membrane roofs where penetrations carry structural penalties. Bifacial products capture margin pools from agrivoltaic and floating solar applications where rear-side irradiance boosts yield. HJT technology leads efficiency rankings for frameless formats due to superior temperature coefficients and bifaciality ratios. Residential rooftops remain the volume anchor, though off-grid power systems in remote villages represent the fastest-growing application segment as humanitarian microgrid programs expand procurement.
FERC interconnection standards in the United States shape grid-tied frameless product certification requirements, while REACH compliance in Europe restricts certain encapsulant chemistries used in edge-sealing processes. China's GB standards mandate mechanical load testing protocols that frameless designs must pass without perimeter reinforcement. Stakeholders must monitor evolving building-integrated photovoltaics codes that increasingly specify frameless aesthetics for facade applications.
Market Dynamics
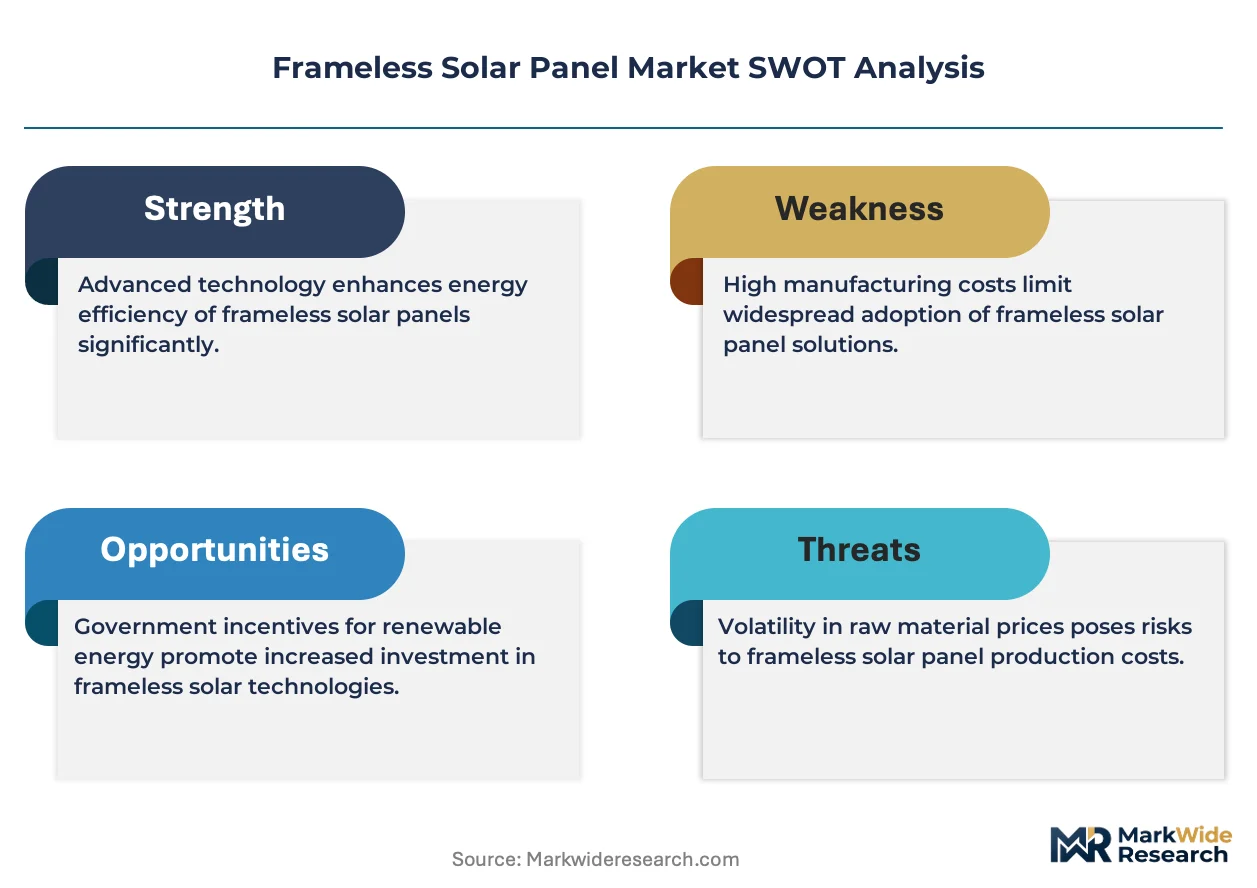
Aluminum price volatility and the EU Green Deal's embodied carbon mandates are compressing frameless module margins while accelerating procurement of glass-edge designs across European commercial rooftops and Nordic utility installations.
Growth Catalysts
- HJT Cell Architecture:Superior temperature coefficients and bifaciality ratios above 90% make heterojunction technology the preferred platform for frameless formats in agrivoltaic and floating solar deployments.
- EU Green Deal Carbon Mandates:Embodied carbon thresholds for construction materials are disqualifying traditional aluminum-framed modules from public procurement tenders across Germany, Netherlands, and Denmark.
- Jiangsu-Zhejiang Manufacturing Cluster:Integrated glass-module producers concentrated near Shanghai and Ningbo ports achieve 15-20% logistics cost advantages on export-bound frameless shipments.
Market Restraints
- Silicone Encapsulant Cost Volatility:Structural edge-bonding materials represent 8-12% of module bill-of-materials, with pricing tied to petrochemical feedstock fluctuations that frameless designs cannot hedge through frame substitution.
- Tempered Glass Supply Concentration:Solar-grade 2.0mm heat-strengthened glass production concentrates among three Chinese suppliers, creating single-source vulnerability for frameless manufacturers lacking captive float-glass capacity.
- Mechanical Load Certification Gaps:China's GB standards mandate testing protocols that many frameless designs fail without perimeter reinforcement, blocking market access for non-integrated assemblers.
Strategic Opportunities
- Building-Integrated Photovoltaics Facade Codes:Aesthetic mandates in French and Swiss building regulations are specifying frameless glass-to-glass aesthetics for commercial curtainwall applications previously served by opaque cladding.
- Humanitarian Microgrid Procurement:Off-grid power programs in sub-Saharan Africa and island Southeast Asia are specifying lightweight frameless modules for rooftop and ground-mount installations where transport infrastructure limits conventional aluminum-framed logistics.
- HJT-Perovskite Tandem Convergence:Laboratory-validated 30%+ efficiency potential from stacked cell architectures positions frameless glass-glass construction as the necessary substrate for next-generation bifacial products.
Industry Challenges
- Edge-Sealing Technician Shortage:Automated silicone dispensing and vacuum lamination for frameless modules requires process engineers with thin-film display manufacturing backgrounds, a talent pool concentrated in East Asian electronics clusters.
- FERC Interconnection Timeline Compression:US utility-scale projects face 18-24 month certification queues for frameless bifacial products under evolving grid-tied standards, delaying revenue recognition against fixed EPC contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frameless Solar Panel Market |
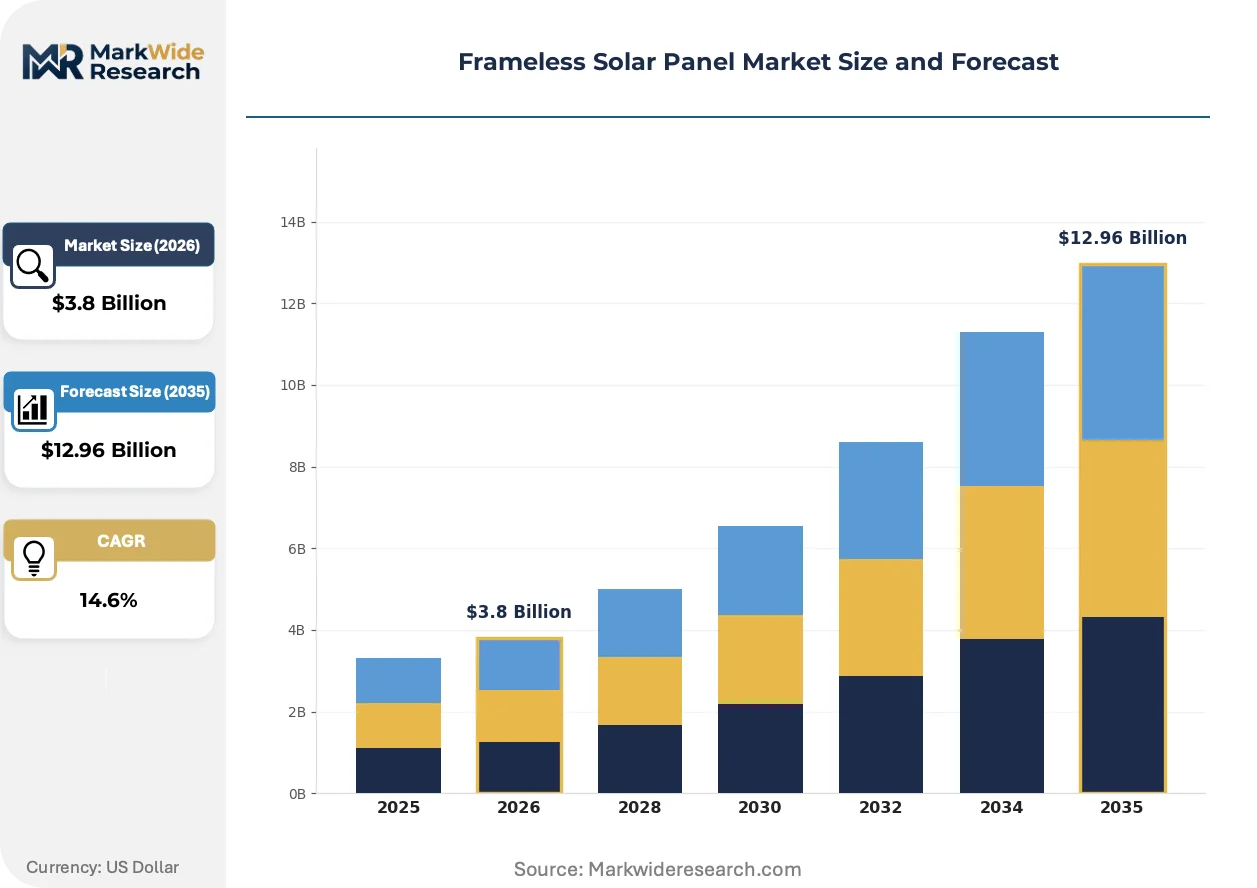
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Amorphous Silicon Technology: PERC, HIT, HJT, TOPCon, Tandem Cells Application: Residential Rooftops, Commercial Buildings, Agriculture, Telecommunication Equipment, Off-Grid Power Systems End User: Utility Companies, Small Businesses, Research Facilities, Educational Institutes, Remote Villages |
| Companies Covered | LONGi Solar, Das Solar, JinkoSolar, Maxeon, REC Solar, JA Solar, Canadian Solar, Solaria, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frameless Solar Panel Market Strategic Shifts & Innovations
Frameless solar manufacturing is splitting into two distinct technology tiers as integrated glass producers capture premium efficiency segments while pure-play assemblers compete on installation speed and commercial rooftop weight reduction.
Structural silicone bonding is bifurcating module assembly economics. This edge-sealing technology eliminates aluminum perimeter frames entirely, reducing dead loads for membrane roof installations. Commercial EPC contractors in Germany and California are specifying silicone-bonded frameless products for 40% of new flat-roof deployments. The technology is compressing margin pools for aluminum extruders while concentrating assembly expertise among glass-chemistry specialists with automotive glazing backgrounds.
REACH compliance restrictions on certain phthalate-based encapsulant chemistries are forcing reformulation of edge-sealing compounds used in European-bound frameless modules. ECHA's 2023 substance evaluation roadmap has flagged three common solar silicone additives for authorization review. Manufacturers serving the Netherlands and Nordic markets are accelerating migration to tin-catalyzed neutral cure formulations ahead of regulatory deadlines.
Agrivoltaic developers are unbundling traditional module procurement from racking and electrical integration services. French and Japanese agricultural cooperatives now issue separate tenders for frameless bifacial glass-glass modules, aluminum-free mounting structures, and DC cabling assemblies. This disaggregation allows agronomic specialists to optimize panel height and row spacing independently of module vendor constraints, concentrating purchasing power among systems integrators with horticultural expertise.
Frameless Solar Panel Market Segmentation
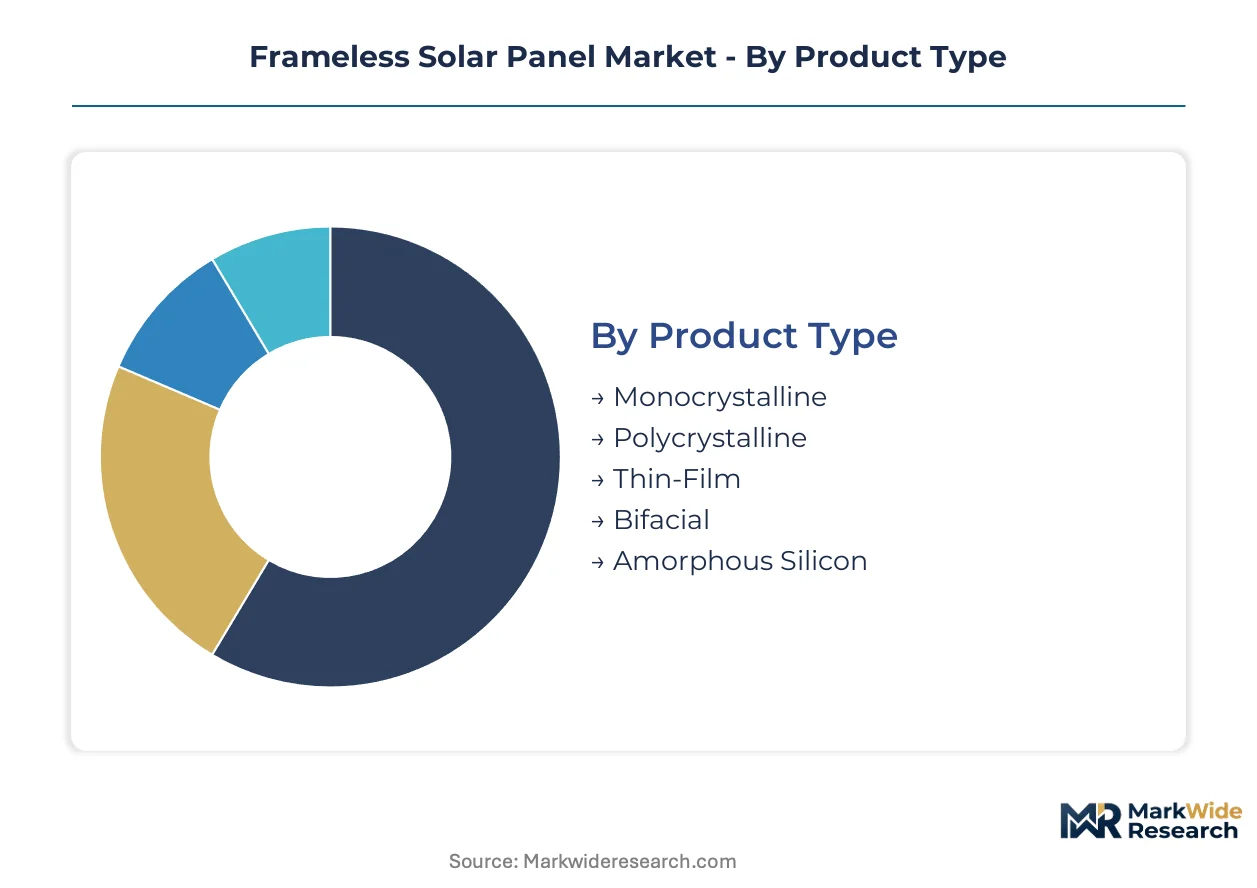
Frameless solar panel procurement patterns diverge sharply across product architectures and deployment contexts. Margin pools concentrate in bifacial glass-glass formats for agrivoltaic and floating solar applications, while thin-film variants serve weight-constrained commercial membrane roofs.
Product Type:
Premium efficiency segments command pricing power in utility-scale tenders, while standard mono- and polycrystalline formats compete on balance-of-system cost reduction.
- Monocrystalline:Silicon ingots sliced from single-crystal boules deliver conversion efficiencies above 22% in frameless glass-glass construction. Jiangsu province manufacturers supply European commercial rooftops where GB standards compliance and REACH encapsulant restrictions filter supplier pools.
- Polycrystalline:Multi-crystalline silicon cells fabricated from cast ingots trade efficiency for lower wafer costs, anchoring volume in price-sensitive distributed generation markets. Demand is concentrating in Indian rural electrification programs where module cost per watt dominates procurement criteria.
- Thin-Film:Cadmium telluride and CIGS absorber layers deposited on flexible substrates achieve sub-3kg/m² weights for membrane roof installations.
- Bifacial:Dual-sided glass encapsulation captures rear-side albedo irradiance, with agrivoltaic developers in France and Japan specifying height-adjustable mounting independent of module vendor constraints.
- Amorphous Silicon:Hydrogenated silicon thin-film tolerates partial shading and high-temperature operation for building-integrated facade applications.
The dominant share belongs to Monocrystalline, while Bifacial is closing the gap fastest.
Technology:
Cell architecture selection determines frameless module eligibility for high-value application segments.
- PERC:Passivated emitter and rear contact structures add dielectric layers to conventional silicon cells, extending mono-PERC dominance into frameless formats for residential rooftops. Chinese integrated producers leverage captive wafer capacity to compress costs for export-bound shipments through Ningbo terminals.
- HIT:Heterojunction with intrinsic thin-layer technology pairs amorphous silicon with crystalline substrates, delivering superior temperature coefficients for tropical deployments. HIT frameless modules anchor premium positioning in Japanese agrivoltaic cooperatives where yield per hectare drives tender specifications.
- HJT:Direct heterojunction deposition achieves bifaciality ratios above 90% without laser-grooved contacts.
- TOPCon:Tunnel oxide passivated contacts replace diffused junctions for efficiency gains approaching HJT at lower capital intensity.
- Tandem Cells:Stacked perovskite-silicon architectures target 30%+ laboratory efficiencies requiring glass-glass substrates.
HJT captures the steepest expansion trajectory among cell technologies, while PERC retains volume leadership through manufacturing scale.
Application:
Installation context dictates structural load requirements and electrical integration complexity.
- Residential Rooftops:Frameless glass-glass modules reduce dead loads for timber-framed housing stock in Germany and California, where 15-20% weight savings accelerate permitting for retrofit installations. EPC contractors specify silicone-bonded edge sealing for 40% of new flat-roof deployments.
- Commercial Buildings:Membrane roof installations on warehouses and distribution centers prioritize puncture resistance and wind-uplift certification. Demand clusters in Netherlands logistics parks where EU Green Deal embodied carbon thresholds disqualify aluminum-framed alternatives from public tenders.
- Agriculture:Elevated bifacial arrays enable simultaneous crop cultivation and power generation.
- Telecommunication Equipment:Remote cell tower power demands lightweight modules with simplified mounting for helicopter or pack-animal transport.
- Off-Grid Power Systems:Humanitarian microgrids in sub-Saharan Africa and island Southeast Asia specify frameless formats where road infrastructure limits conventional logistics.
Residential Rooftops maintain the largest installed base, though Off-Grid Power Systems are expanding most quickly.
End User:
Purchasing sophistication and contract scale segment procurement behavior across customer categories.
- Utility Companies:Centralized procurement departments negotiate multi-hundred-megawatt supply agreements with integrated glass-module producers. FERC interconnection standards in the United States impose 18-24 month certification timelines that delay revenue recognition against fixed EPC contracts.
- Small Businesses:Distributed commercial installers source through regional distributors with limited technical specification influence. Small business demand concentrates in Zhejiang province manufacturing clusters where integrated producers offer direct procurement channels.
- Research Facilities:National laboratories and university testbeds validate novel cell architectures and encapsulant formulations.
- Educational Institutes:Campus sustainability mandates drive rooftop installations with curriculum-integrated monitoring systems.
- Remote Villages:Development finance institution programs aggregate demand across dispersed settlements, concentrating purchasing power with systems integrators experienced in last-mile logistics.
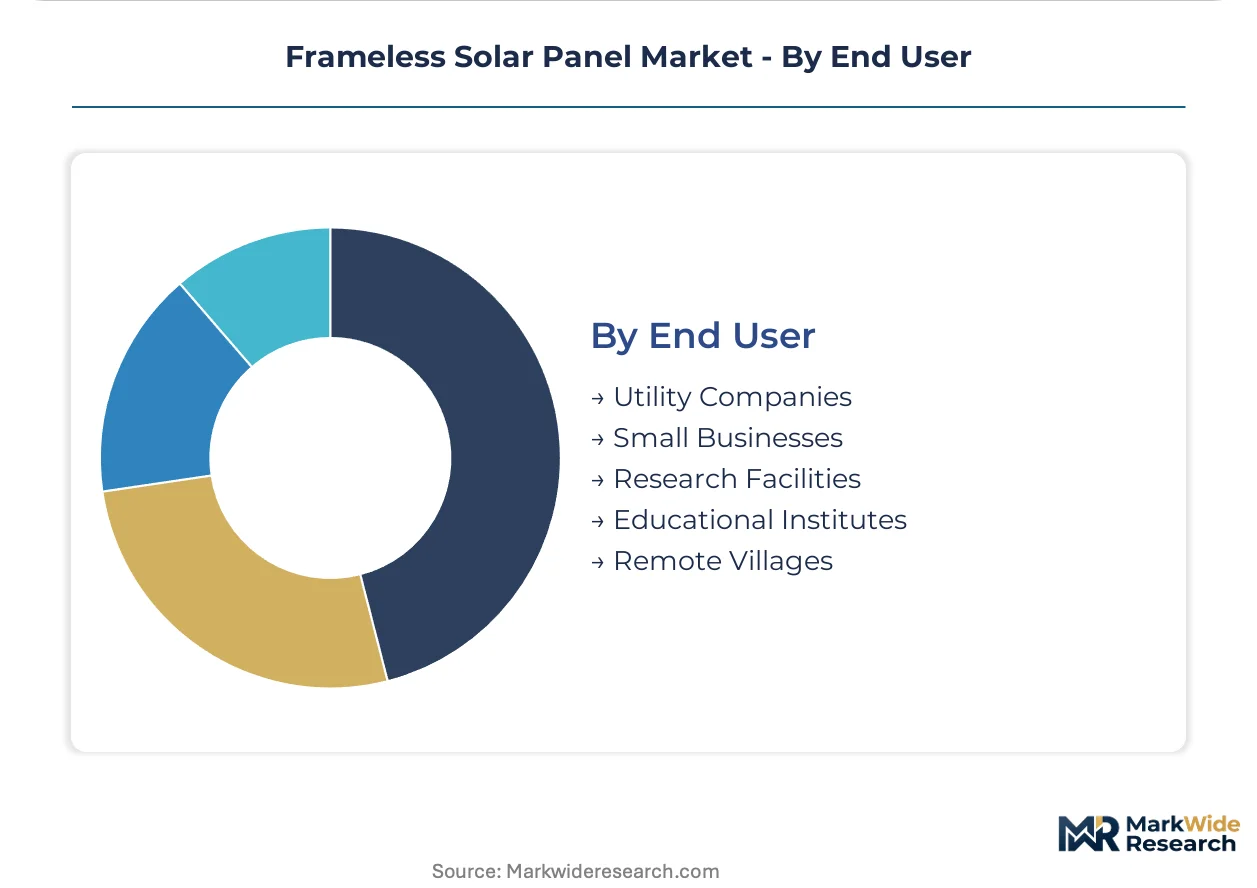
Utility Companies command the greatest procurement volume, while Remote Villages are gaining share fastest through humanitarian program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through Jiangsu-Zhejiang manufacturing clusters, while European developers absorb 15-20% premiums for EU Green Deal-compliant frameless modules that minimize embodied carbon.
China
Integrated glass-module producers in Jiangsu and Zhejiang provinces dominate export volume through Ningbo and Shanghai terminals. GB standards mandate mechanical load testing that filters out non-integrated assemblers. The Yangtze River Delta cluster achieves logistics cost advantages of 15-20% on frameless shipments bound for European utility tenders.
Germany
Commercial EPC contractors specify silicone-bonded frameless products for 40% of new flat-roof warehouse deployments. EU Green Deal embodied carbon thresholds disqualify aluminum-framed alternatives from federal procurement tenders. Bavarian and North Rhine-Westphalian logistics parks anchor demand concentration.
United States
FERC interconnection standards impose 18-24 month certification queues for frameless bifacial products, compressing project IRRs. California timber-framed housing retrofits prioritize 15-20% dead load reductions. The Inflation Reduction Act's domestic content bonuses favor captive-glass producers with US assembly footprints.
Japan
Agrivoltaic cooperatives in Kanto and Chubu regions specify HJT frameless modules where yield per hectare drives tender specifications. METI feed-in tariff revisions prioritize bifaciality ratios above 90%. Osaka-based agricultural integrators unbundle module procurement from racking and electrical services.
France
Aesthetic building codes in Île-de-France and Auvergne-Rhône-Alpes mandate frameless glass-to-glass aesthetics for commercial curtainwall applications. ECHA's 2023 substance evaluation roadmap accelerates migration to tin-catalyzed neutral cure silicone formulations. French agricultural cooperatives issue separate tenders for frameless modules, aluminum-free mounting, and DC cabling.
Frameless Solar Panel Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated glass-module producers with captive wafer and cell capacity compress unit costs for export-bound shipments. Pure-play assemblers compete on installation speed and commercial rooftop weight reduction. The market consolidates around two dominant moves: backward integration into solar-grade tempered glass production and geographic expansion through port-proximate manufacturing clusters.
Among Chinese integrated producers, LONGi Solar, JinkoSolar, and Trina Solar exemplify the cost-leadership archetype through Yangtze River Delta manufacturing concentration. Maxeon occupies a position on the premium-efficiency vector with interdigitated back-contact architectures. REC Solar anchors European demand representation through Nordic snow-load engineering specialization. These three archetypes—integrated cost leaders, premium technology specialists, and regional application engineers—define the competitive fault lines.
| Leading Market Players |
|---|
| LONGi Solar |
| Das Solar |
| JinkoSolar |
| Maxeon |
| REC Solar |
| JA Solar |
| Canadian Solar |
| Solaria |
| Trina Solar |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day lead times for solar-grade tempered glass translate directly into pricing power concentration among Jiangsu-Zhejiang integrated producers, compressing margin pools for non-captive assemblers while amplifying cost advantages at export terminals.
Pricing Analysis
Configured-to-order premiums for HJT bifacial frameless modules run 12-18% above standard mono-PERC equivalents, with price differentiation anchored in certification grade and volume scale. Three-tier pricing structure across premium, standard, and economy levels stratifies by efficiency tier and after-sales bundling. Pricing pressure stems from aluminum price volatility feeding into framed module cost bases, narrowing the frameless premium. Utility-scale procurement teams exhibit lowest price sensitivity, while distributed commercial installers in European logistics parks absorb cost compression most acutely.
Supply Chain Analysis
Inventory cycles of 30-45 days for structural silicone encapsulants expose frameless manufacturers to petrochemical feedstock volatility without frame-substitution hedges. Manufacturing gravity centers on China, with South Korea and Japan anchoring specialty HJT cell supply. Raw material dependencies include solar-grade 2.0mm heat-strengthened glass, tin-catalyzed neutral cure silicones, and high-purity silver paste for heterojunction metallization. Single-source vulnerability concentrates in Chinese tempered glass production, with distribution running through Ningbo and Shanghai port-proximate clusters for European-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frameless solar panel procurement is recovering from cyclical oversupply in conventional aluminum-framed capacity, with EU Green Deal carbon mandates serving as the demand inflection driver.
For Market Incumbents: Shield margin position by accelerating backward integration into solar-grade tempered glass production and securing tin-catalyzed silicone formulations ahead of ECHA authorization reviews. Concentrate capacity additions in Yangtze River Delta clusters to defend logistics cost advantages against emerging Southeast Asian assembly footprints. For New Entrants and Emerging Players: Last-mile logistics gaps in humanitarian microgrid deployment represent the most penetrable white-space target, particularly in sub-Saharan Africa and island Southeast Asia where road infrastructure limits conventional aluminum-framed module transport. Pursue direct procurement relationships with development finance institutions rather than competing for utility-scale tenders where integrated incumbents hold cost dominance. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal embodied carbon thresholds and REACH compliance restrictions are structurally disadvantaging aluminum-framed alternatives. Target acquisition archetypes include captive-glass producers with automotive glazing process engineering capabilities and established ECHA regulatory affairs infrastructure. The signal to watch is FERC interconnection standard finalization timelines for bifacial frameless products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tempered Glass | Captive solar-grade 2.0mm production eliminates single-source vulnerability to Xinyi and CNBM supply concentration. |
| ECHA-Compliant Silicone Formulation Migration | Tin-catalyzed neutral cure compounds secure Netherlands and Nordic market access ahead of phthalate-based additive restrictions. |
| Port-Proximate Manufacturing Cluster Expansion | Ningbo and Shanghai terminal adjacency sustains 15-20% logistics cost advantages on European utility tenders. |
| Agrivoltaic Systems Integration Capability Buildout | Height-adjustable mounting and horticultural expertise capture unbundled procurement from French and Japanese agricultural cooperatives. |
| HJT-Perovskite Tandem R&D Partnership | Laboratory-validated 30%+ efficiency architectures require glass-glass substrates that frameless construction uniquely enables. |
Research Approach
The analysis maps integrated glass-module production, pure-play assembly, and specialty HJT cell manufacturing, each validated through EPC contractor procurement leads, utility planning officers, and solar-grade glass plant managers. Primary fieldwork across Jiangsu and Zhejiang manufacturing clusters combined with secondary validation from FERC interconnection filings, ECHA substance evaluation roadmaps, and GB standards documentation. Bottom-up module shipment data triangulated against top-down utility tender awards across Germany, Netherlands, and California.
Consistency checks against IEA solar deployment forecasts and BNEF project finance databases validated volume and value outputs across the projection horizon. Segmentation modeling incorporated cell architecture, application context, and regional regulatory framework dimensions. CAGRs derived from installation run-rate analysis and module price trajectory assumptions, with specific inputs including EU Green Deal procurement threshold implementation timelines and METI feed-in tariff revision schedules.
Forecasts assume regulatory continuity in EU Green Deal carbon mandates and REACH authorization processes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Half-Cell Solar Module Market