
 Solar Shingles Market | 2026-2036
Solar Shingles Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Shingles Market Intelligence
The US Inflation Reduction Act (IRA) is broadening the market's addressable base by directly lowering the cost of ownership for homeowners. This policy shift creates opportunities for specialized manufacturers. Tesla leverages its direct-to-consumer model to secure premium projects. GAF Energy utilizes its extensive roofing distributor network to deploy its Timberline Solar product, while CertainTeed integrates solar shingles within its building materials portfolio.
Solar shingles are photovoltaic devices engineered to function as both a roofing material and a power generator, blending with traditional shingle aesthetics. These products often use monocrystalline silicon cells for higher efficiency, laminated with durable top layers. The monocrystalline product type leads the market due to superior power output. Demand is overwhelmingly concentrated in the residential roofing application, where homeowners prioritize weather protection and clean energy generation.
Market access is governed by a combination of electrical and building regulations. The US National Electrical Code (NEC) and standards from the International Electrotechnical Commission (IEC) dictate safety requirements. Concurrently, mandates within the EU's Energy Performance of Buildings Directive (EPBD) and specific codes in California drive adoption. The primary challenge for stakeholders is aligning manufacturing capacity with the specialized installer training needed for deployment.
Market Dynamics
The central force shaping the market is the convergence of renewable energy policy with residential building codes. This dynamic pressures the construction industry to adopt integrated solutions that satisfy both aesthetic and power generation requirements, moving beyond traditional solar panels.
Growth Catalysts
- Favorable Government Policies:The US Inflation Reduction Act and EU Green Deal offer direct subsidies and tax credits, lowering the effective purchase price for homeowners.
- Monocrystalline Silicon Efficiency:Superior power output from monocrystalline cells makes solar shingles practical for space-constrained residential roofs in dense urban areas.
- New Construction Mandates:Building codes in markets like California requiring solar on new homes create a non-discretionary demand for integrated photovoltaic roofing.
Market Restraints
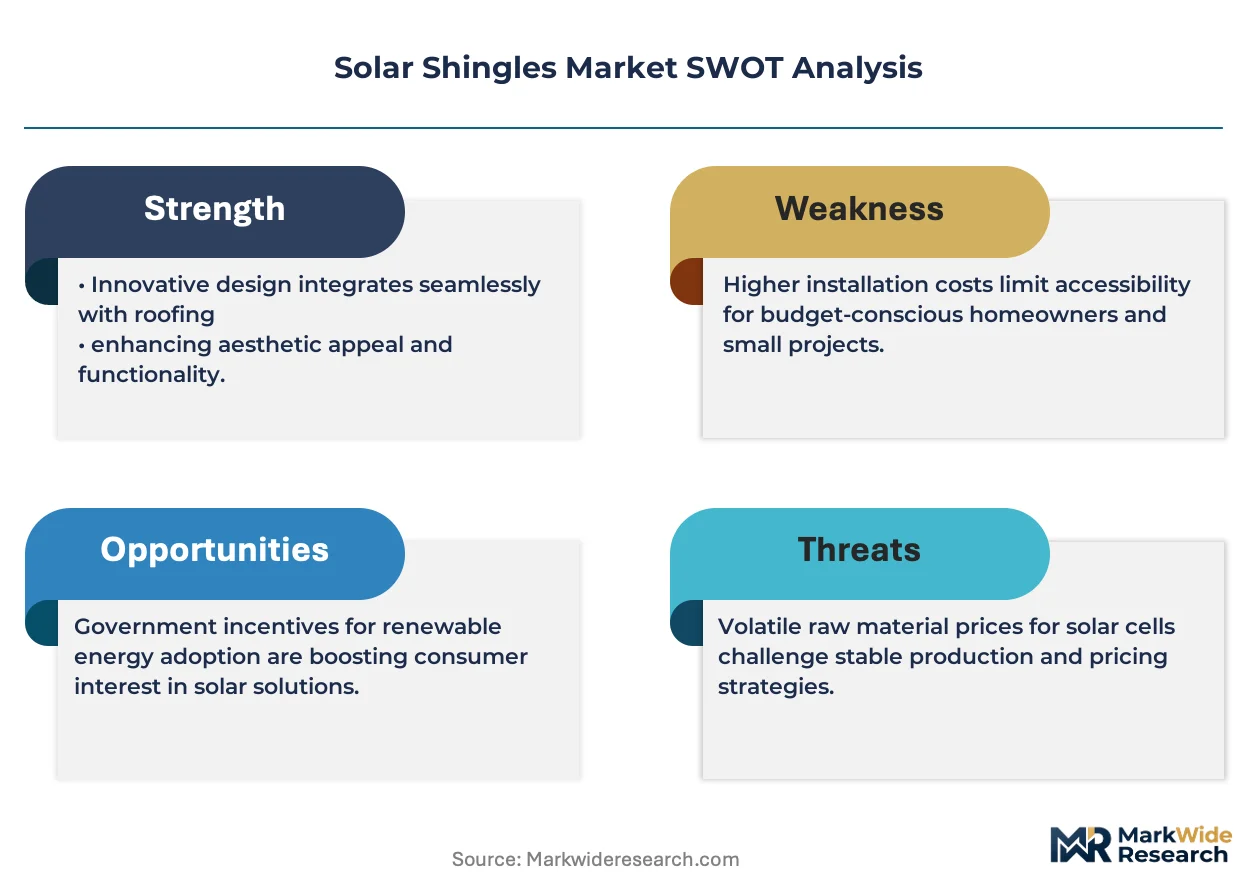
- High Upfront Installation Cost:The initial capital outlay for solar shingles significantly exceeds traditional asphalt roofing combined with separate rack-mounted solar panels.
- Specialized Installer Shortage:A lack of roofers cross-trained in electrical work creates deployment bottlenecks, limiting installation velocity and raising labor costs.
- Complex Permitting Processes:Inconsistent local building codes and utility interconnection agreements under standards like the NEC introduce significant project delays.
Strategic Opportunities
- Expansion into Sunbelt Geographies:Markets like Australia and Spain, with high solar irradiance, represent underpenetrated residential segments for aesthetically integrated solar products.
- Commercial Building Applications:Developing larger format tiles for low-slope commercial roofs opens a new market beyond the core residential sector.
- Alliances with Homebuilders:Collaborating with developers to standardize solar shingles in new housing tracts streamlines sales and installation at scale.
Industry Challenges
- Installer Training Scalability:The primary operational hurdle is developing and scaling certification programs to qualify a workforce for the unique electrical and roofing requirements.
- Manufacturing Capacity Alignment:Aligning capital-intensive cell production and shingle lamination capacity with fluctuating regional demand and project timelines is a major operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Shingles Market |
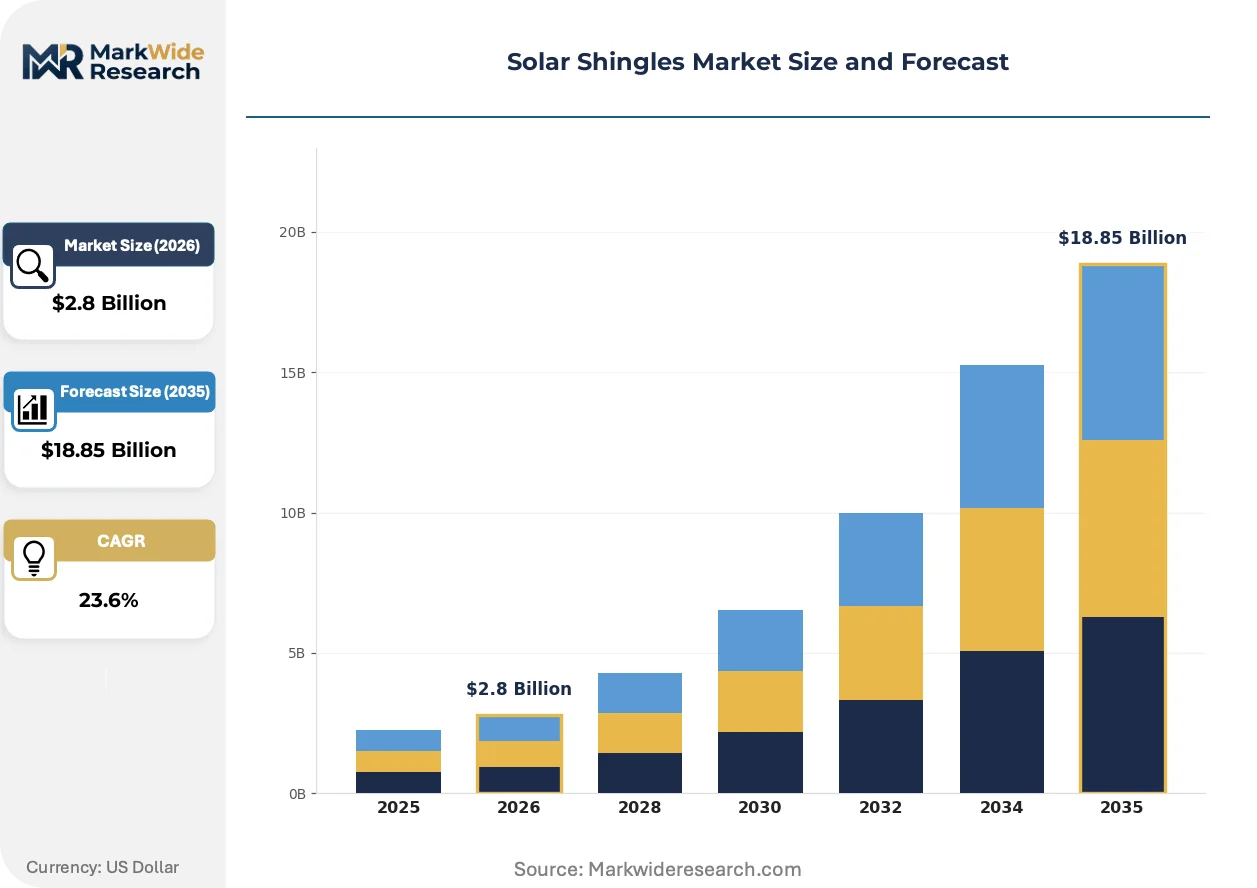
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $18.85 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Building-Integrated Photovoltaics Technology: Crystalline Silicon, Amorphous Silicon, Copper Indium Gallium Selenide, Perovskite Application: Residential Roofing, Commercial Roofing, Industrial Roofing, Agricultural Structures End User: Homeowners, Real Estate Developers, Construction Firms, Renewable Energy Contractors |
| Companies Covered | CertainTeed, GAF Roofing, GAF Energy, Standard Industries, VOLTAIC, Tesla, Suntegra, Timberline Solar, Luma Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Shingles Market Strategic Shifts & Innovations
Aesthetic integration and performance parity are the primary forces at play. Solar shingles are evolving from a niche alternative into a mainstream building material, driven by innovations that erase the compromise between curb appeal and energy generation.
Monocrystalline silicon cells are engineered into durable, weather-resistant laminates that precisely mimic the texture and color of traditional roofing materials. The residential sector, particularly in new construction and high-end reroofing, is rapidly adopting these products. This advancement is integrating power generation so seamlessly into the building envelope that it becomes an indistinguishable element of the home’s architecture.
The European Union’s Energy Performance of Buildings Directive (EPBD) mandates stricter energy efficiency standards for new and renovated structures. This compels property owners and developers to incorporate on-site renewable energy generation to achieve compliance. Consequently, the residential construction segment in EU member states like Germany and France faces a mandated demand for building-integrated photovoltaics.
Homeowner purchasing criteria are shifting from a pure cost-per-watt calculation to a total value proposition including aesthetics, roof longevity, and property value. This shift disrupts the traditional solar sales model, elevating roofing distributors and building material suppliers into the primary channel. The trend is most visible in North American suburbs where curb appeal is a major factor.
Solar Shingles Market Segmentation
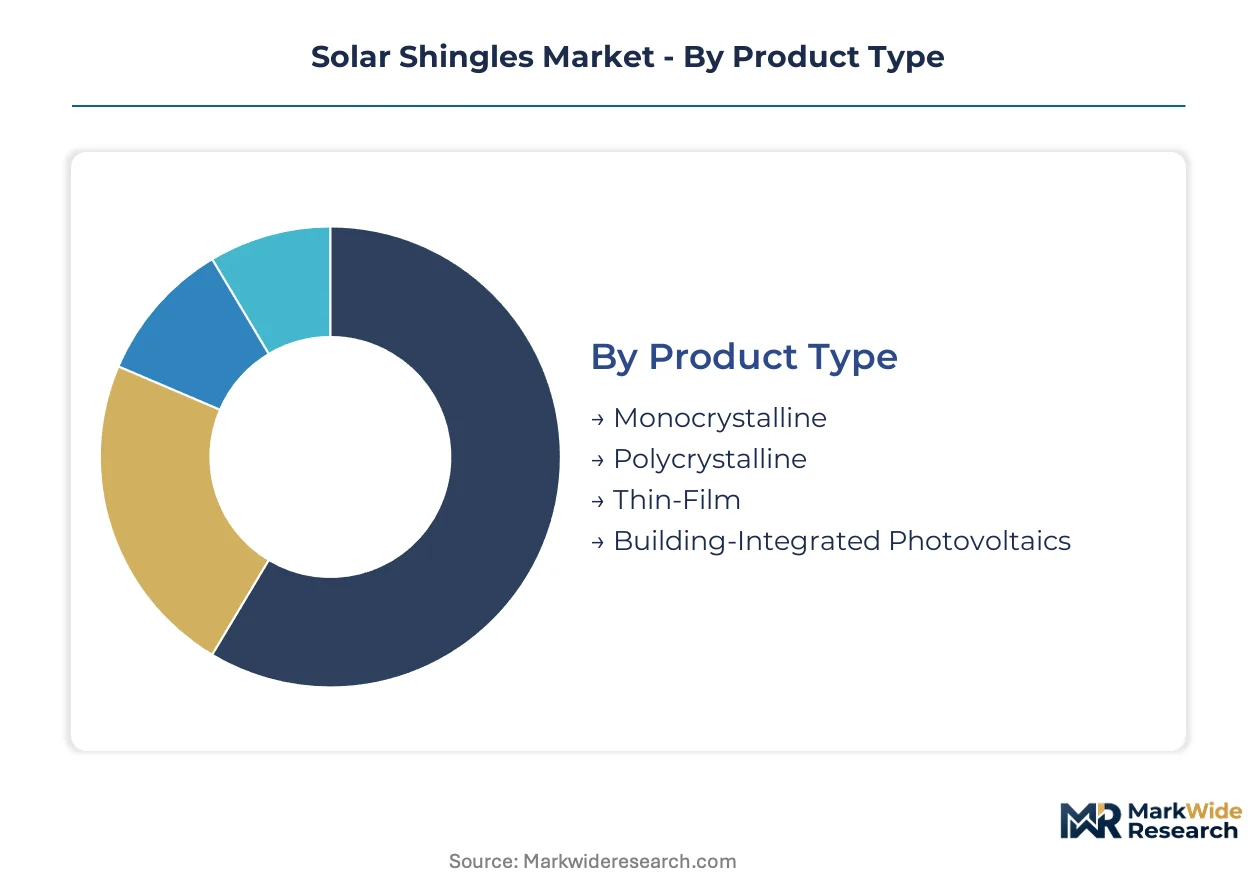
The solar shingles market segmentation provides a granular understanding of product evolution, technological advancements, and the diverse end-user demands driving adoption. Analyzing these distinct segments helps stakeholders identify core growth areas and tailor strategies for specific market niches.
Product Type:
The product type segmentation reveals a clear distinction between premium, high-efficiency solutions driving value and more cost-effective options targeting broader volume adoption in the solar shingles market.
- Monocrystalline:These products utilize highly pure silicon cells, offering superior efficiency and a sleek, uniform appearance, making them ideal for residential roofs with limited space in dense urban areas. Demand concentrates in regions like California and Germany, where homeowners prioritize both aesthetics and maximum power output from compact roof footprints.
- Polycrystalline:Comprising multiple silicon crystals, these shingles offer a more cost-effective solution with slightly lower efficiency compared to monocrystalline, suitable for larger residential or commercial installations where initial investment cost is a primary concern.
- Thin-Film:Characterized by their flexibility, lightweight nature, and ability to perform well in low-light conditions, thin-film solar shingles find niche applications in architectural integration where form factor is critical, often for curved or unconventional roof designs.
- Building-Integrated Photovoltaics:These are solar energy systems seamlessly integrated into the building envelope, acting as both roofing material and power generator, driven by new construction mandates and the EU's Energy Performance of Buildings Directive. Demand is accelerating in new housing developments and high-end reroofing projects across European member states.
Today's leader: Monocrystalline. Tomorrow's challenger: Building-Integrated Photovoltaics.
Technology:
Technology differentiation in solar shingles centers on conversion efficiency, material flexibility, and long-term durability across diverse environmental conditions.
- Crystalline Silicon:This dominant technology segment, encompassing both monocrystalline and polycrystalline cells, offers proven reliability and high energy conversion rates, making it the industry standard for residential and commercial solar shingle installations. Established manufacturing processes ensure consistent quality for homeowners and developers.
- Amorphous Silicon:Known for its flexibility and lower manufacturing cost, amorphous silicon technology offers less efficiency but performs well in diffuse light conditions, often used in applications requiring lightweight or flexible solar solutions.
- Copper Indium Gallium Selenide:CIGS technology represents a thin-film alternative providing good performance in varying light conditions and aesthetic versatility due to its thin, dark appearance.
- Perovskite:An emerging technology, perovskite cells promise high efficiency and potentially lower manufacturing costs, currently a significant focus for research and development to address stability and scalability challenges for future market disruption.
Crystalline Silicon technologies currently dominate the installed base, while Perovskite-based solutions show the steepest expansion trajectory for future market penetration.
Application:
Application segments highlight distinct demand drivers, ranging from homeowner aesthetic preferences to large-scale commercial energy mandates.
- Residential Roofing:This segment represents the overwhelming majority of demand, driven by homeowners seeking aesthetic integration, weather protection, and clean energy generation for their properties. Purchasing criteria extend beyond pure cost-per-watt to include curb appeal and long-term property value.
- Commercial Roofing:This application segment presents a strategic opportunity for larger format solar shingles on low-slope commercial buildings, enabling businesses to reduce operational energy costs and meet sustainability targets. Demand is growing as companies seek to incorporate renewable energy into their infrastructure.
- Industrial Roofing:Industrial facilities with large, often flat roof surfaces utilize solar shingles for significant on-site power generation, contributing to operational efficiency and reduced grid reliance.
- Agricultural Structures:Solar shingles are finding utility on barns, greenhouses, and other agricultural buildings, providing reliable power for farm operations and contributing to rural energy independence.
Residential Roofing applications command the largest market share, with Commercial Roofing poised for significant gains as building codes evolve.
End User:
End user segmentation delineates the primary decision-makers and beneficiaries, influencing product features and sales channel strategies.
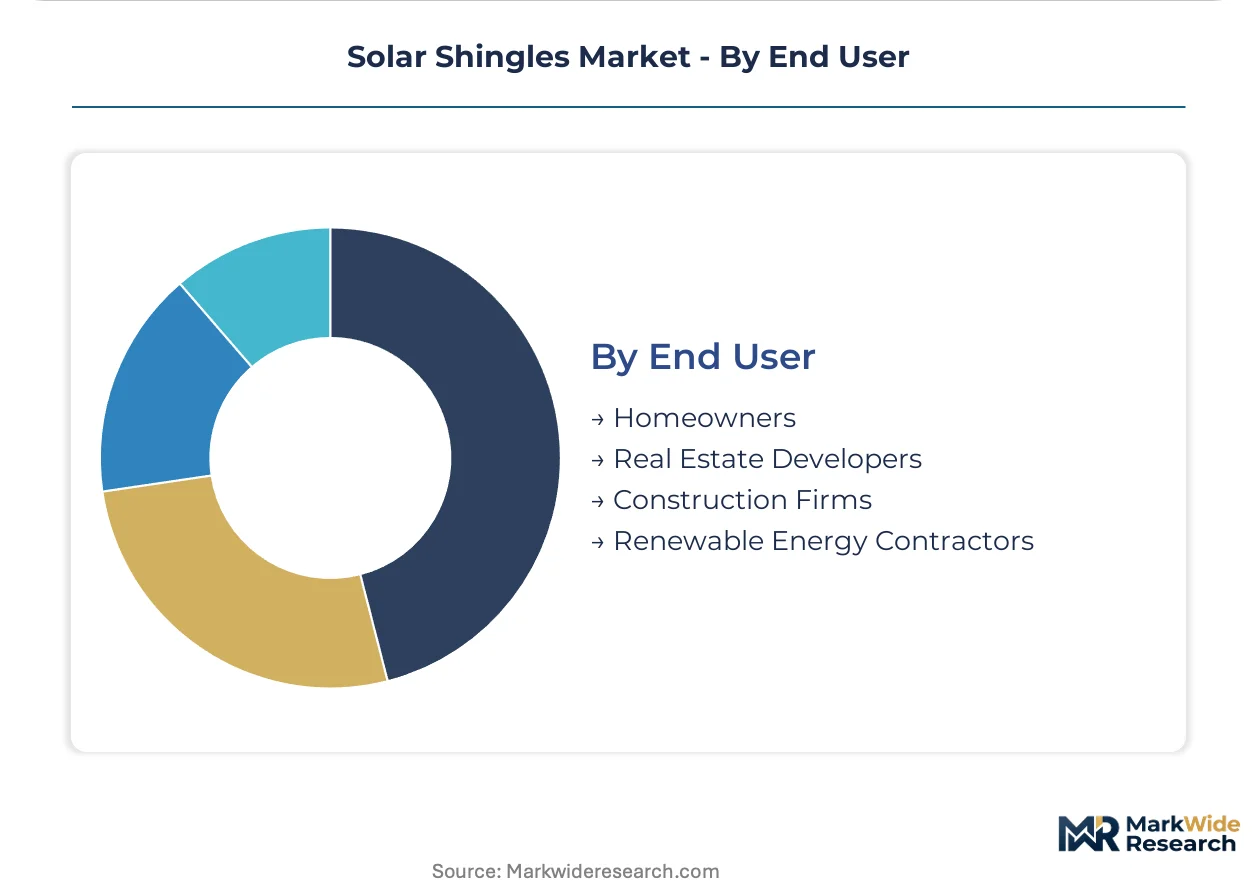
- Homeowners:As direct consumers, homeowners prioritize the blend of aesthetic appeal, long-term durability, and the financial benefits of reduced electricity bills and government incentives like the US Inflation Reduction Act. Their purchasing decisions are often influenced by roofing distributors and building material suppliers.
- Real Estate Developers:These entities integrate solar shingles into new housing tracts and planned communities, driven by new construction mandates in regions like California and a desire to offer energy-efficient, high-value properties. Alliances with developers streamline sales and installation at scale.
- Construction Firms:These firms incorporate solar shingles into broader building projects, requiring cross-trained installers capable of handling both roofing and electrical integration. They focus on project timelines and compliance with local building codes.
- Renewable Energy Contractors:Specialists in solar installations, these contractors provide technical expertise, manage complex permitting processes, and ensure seamless utility interconnection for solar shingle projects.
Homeowners represent the largest direct purchasing segment, while Real Estate Developers are increasingly influencing demand through new construction projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized installer workforce, crucial for solar shingle deployment, anchors regional growth in key geographies. This talent concentration supports the complex integration of roofing and electrical systems required for these advanced photovoltaic products. Markets with established solar industries and skilled labor pools are experiencing accelerated adoption.
United States
United States demand drivers include homeowner aesthetic preferences and the financial benefits of reduced electricity bills. The US Inflation Reduction Act offers significant tax credits, directly lowering the cost of ownership. California's new construction mandates drive demand for integrated photovoltaic roofing solutions across its major metropolitan areas.
Germany
Germany's market is shaped by strict energy efficiency standards and a strong push for clean energy generation. The EU Green Deal and Energy Performance of Buildings Directive (EPBD) compel renewable energy integration in new and renovated structures. Cities like Munich and Berlin are seeing increased adoption in both new builds and high-end renovations.
France
French demand is influenced by national sustainability targets and the desire for aesthetic integration into diverse architectural styles. French energy regulations, aligned with the EU Green Deal, actively promote on-site renewable energy generation. New housing developments around Paris and Lyon are increasingly incorporating solar shingles to meet compliance.
Australia
Australia, with its high solar irradiance, presents significant residential demand for aesthetically integrated solutions. National renewable energy targets and various state-level incentives support broad solar deployment. Sunbelt geographies, particularly around Sydney and Brisbane, represent underpenetrated residential segments for these products.
Spain
Spain, benefiting from a favorable climate for solar energy, sees strong homeowner interest in energy independence. Spanish energy policies actively encourage self-consumption and building-integrated photovoltaics. Coastal regions and major urban centers like Madrid and Barcelona are witnessing a rise in integrated solar roofing projects.
Solar Shingles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the solar shingles market structure. The market exhibits a tiered structure, with established roofing material manufacturers leveraging existing distribution networks to reach homeowners. Strategic archetypes include building material giants, specialized solar integrators focusing on installation, and technology-driven disruptors emphasizing aesthetic and performance. Dominant competitive moves involve strategic partnerships with homebuilders, capacity expansion, and continuous product innovation in material science to enhance durability and efficiency.
Within the building material giants, CertainTeed, a US-based manufacturer, exemplifies portfolio integration by offering solar shingles as part of its broader construction material offerings. GAF Energy, a subsidiary of Standard Industries, occupies a strong position through its extensive roofing distributor network, anchoring the traditional roofing channel. Tesla, a US-based technology company, represents the direct-to-consumer model, leveraging its brand and innovation to secure premium residential projects.
| Leading Market Players |
|---|
| CertainTeed |
| GAF Roofing |
| GAF Energy |
| Standard Industries |
| VOLTAIC |
| Tesla |
| Suntegra |
| Timberline Solar |
| Luma Solar |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and diversified conglomerates exert significant influence on solar shingle supply behavior and pricing discipline. Their established manufacturing footprints and distribution networks often dictate market entry barriers and cost structures for new entrants.
Pricing Analysis
The bundled installation and product service split significantly influences solar shingle pricing. Project-based pricing dominates, where the total cost encompasses product, installation, and interconnection. Aesthetic integration and monocrystalline silicon efficiency drive price differentiation, commanding a premium over traditional roofing solutions. Pricing pressure stems from the high upfront capital outlay for homeowners, yet it is partially offset by government incentives like the US Inflation Reduction Act. Homeowners typically exhibit high price sensitivity to initial installation costs but prioritize long-term value and aesthetics, while real estate developers balance cost with compliance.
Supply Chain Analysis
Certification and qualification gating angles impose strict requirements on the solar shingle supply chain. Monocrystalline silicon cells, primarily sourced from China, form the core raw material dependency. Durable laminates and specialized electrical components are also critical inputs. A structural risk involves single-source vulnerability for advanced manufacturing equipment. Distribution runs through established roofing distributors, direct-to-consumer models, and strategic alliances with homebuilders, connecting manufacturers to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU Green Deal and California's new construction mandates driving sustained demand for integrated solar solutions.
For Market Incumbents: Deepen existing channel partnerships with roofing distributors to leverage their established customer bases and installation capabilities. Invest in scaling specialized installer training programs to alleviate labor shortages, a primary operational bottleneck. Focus R&D on enhancing durability and aesthetic integration to maintain a premium position against emerging competitors. This defends market share against the threat of new entrants and ensures efficient deployment.
For New Entrants and Emerging Players: Underserved new housing developments represent a significant white-space opportunity for integrated solar shingles. Target sunbelt geographies like Australia and Spain, where high solar irradiance and residential demand align. Develop strategic alliances with homebuilders and real estate developers to streamline sales and installation at scale, offering a compelling value proposition from the outset. This go-to-market angle bypasses traditional distribution challenges.
For Investors and Strategic Acquirers: Specialized roofing material manufacturers are the most active acquirers in this space, seeking to integrate solar capabilities into their portfolios. The market demonstrates long-term viability over the next decade, driven by policy support and technological advancements. Target acquisition archetypes include specialized installer networks and innovative technology disruptors, particularly those developing next-generation cell technologies like Perovskite. A model refresh is warranted upon material change in installer certification rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Installer Training Programs | Scales the specialized workforce needed to overcome deployment bottlenecks and accelerate market growth. |
| Form Alliances with Homebuilders | Standardizes solar shingle integration in new construction, streamlining sales and installation processes. |
| Invest in Monocrystalline Efficiency R&D | Enhances power output and aesthetic appeal, maintaining product competitiveness in dense urban areas. |
| Target Sunbelt Residential Markets | Opens underpenetrated geographies with high solar irradiance and strong homeowner interest in clean energy. |
| Acquire Advanced Lamination Technology | Secures intellectual property for durable, weather-resistant products critical for long-term roof performance. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct this market analysis. Stakeholder roles interviewed included roofing contractors, electrical engineers, building material manufacturers, and real estate developers. Secondary data sources comprised government energy reports, building codes like the US National Electrical Code, and industry association publications, alongside company financial disclosures.
Data-stream reconciliation informed the analytical framework used to project market dynamics. Segmentation dimensions modeled included product type, technology, application, end-user, and regional policy environment across the analysis window. Compound annual growth rates were derived from historical trends and projected market expansion, integrating industry-specific forecast inputs such as energy efficiency mandates and solar irradiance data.
Underlying measurement precision varies by segment; residential roofing and monocrystalline products carry tighter precision than others. Forecasts reflect assumptions regarding technological evolution and regulatory stability. A model refresh is warranted upon material change in policy incentives or raw material price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Films Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market