
 High Concentration Photovoltaics Market | 2026-2036
High Concentration Photovoltaics Market Size, Share, and Industry Trends Forecast 2026-2036
High Concentration Photovoltaics Market Foresight
Utility procurement consolidation is repositioning supplier relationships across the high concentration photovoltaics value chain. Soitec leverages its engineered substrate expertise to sustain multi-junction cell leadership. SunPower Corporation anchors North American project pipelines through integrated tracker and module offerings. Solar Junction competes on lattice-matched III-V semiconductor architectures that differentiate performance in desert climates.
High concentration photovoltaics deploys optical systems that concentrate sunlight onto multi-junction III-V semiconductor cells achieving conversion efficiencies above 40 percent under direct normal irradiance conditions, primarily serving utility-scale and industrial power generation applications where land constraints favor maximum output per unit area. The technology dimension shows multi-junction cells commanding premium margin pools while thermal management systems represent the fastest-growing segment as heat dissipation requirements intensify at concentration ratios exceeding 500 suns. Ground-mounted installations dominate current deployment volumes though BIPV integration is gaining traction in commercial segments seeking dual-purpose facade systems.
FERC interconnection standards and the EU Green Deal's renewable energy directives shape market access requirements across major demand centers, with California's CEC building codes and Spain's national renewable plans creating additional compliance layers for system designers. IEC 62108 concentrator photovoltaic module qualification standards govern product certification pathways in most developed markets. Stakeholders must monitor evolving tracker reliability metrics and inverter compatibility protocols as concentration ratios climb toward next-generation architectures.
Market Dynamics
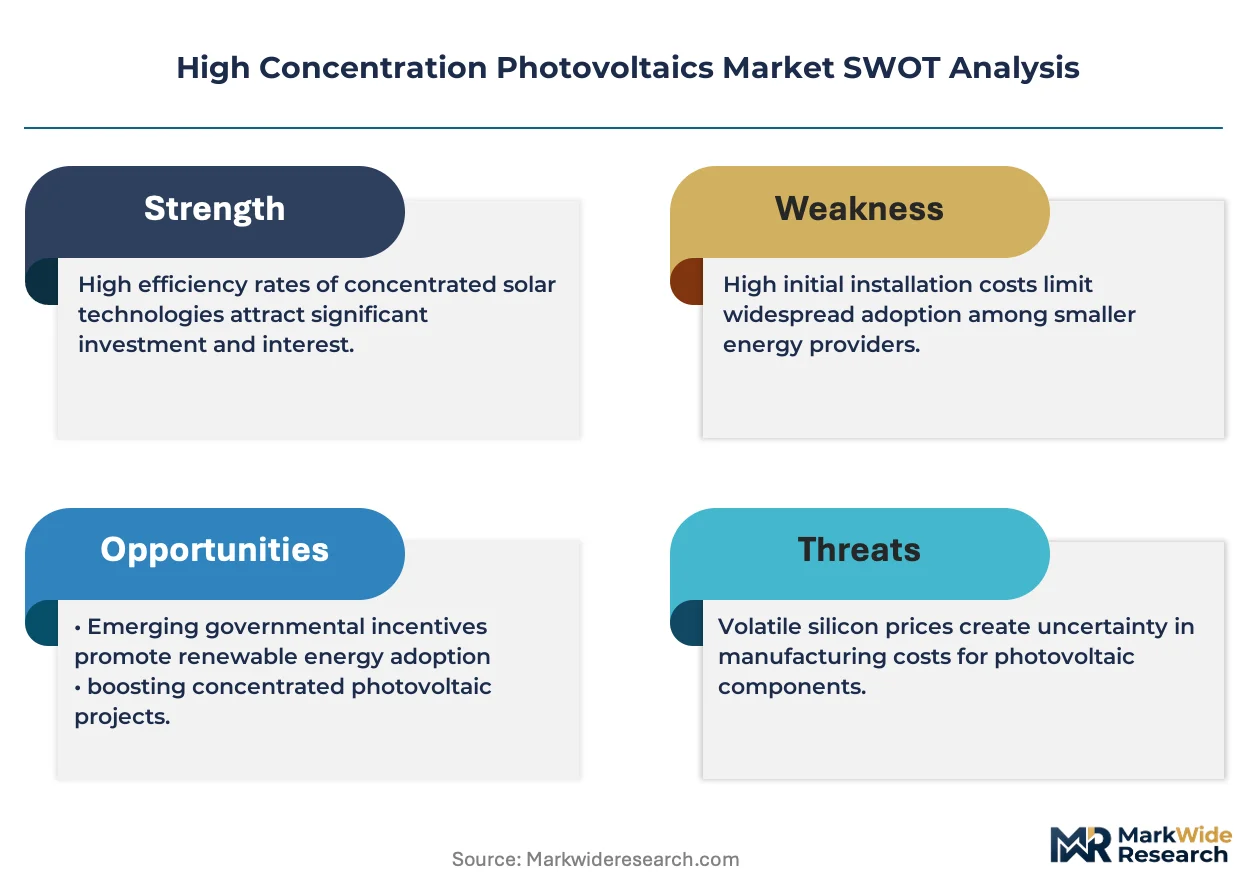
Utility-scale developers are consolidating procurement around high-efficiency concentrator systems that maximize output per hectare, compressing supplier margins while elevating technical qualification barriers for module and tracker vendors.
Growth Catalysts
- EU Green Deal renewable targets:The directive mandates accelerated module efficiency thresholds that favor multi-junction concentrator architectures over conventional silicon panels in utility-scale tenders.
- Spain's direct normal irradiance concentration:Arid plateau regions in Extremadura and Castilla-La Mancha deliver optimal deployment economics for 500+ sun concentration ratios.
- Multi-junction III-V semiconductor efficiency:Lattice-matched gallium indium phosphide and gallium arsenide layers achieve conversion rates above 40 percent under concentrated illumination.
Market Restraints
- Germanium substrate cost volatility:Concentrated supply from China and Russia exposes cell manufacturers to input price swings that compress margin pools at concentration ratios exceeding 300 suns.
- Tracker mechanical reliability thresholds:Precision dual-axis tracking systems face accelerated wear rates in desert climates, elevating OPEX and warranty reserve requirements.
- Flat-plate silicon substitution threat:Passivated contact and heterojunction silicon modules below USD 0.20 per watt undermine concentrator economics in markets without land constraints.
Strategic Opportunities
- Industrial cogeneration applications:High-temperature thermal extraction from concentrator arrays opens district heating and process steam markets in Spain's agricultural processing zones.
- Building-integrated concentrator facades:Dual-purpose commercial envelope systems capture facade real estate for power generation in Madrid and Barcelona commercial corridors.
- FERC Order 2023 interconnection reforms:Streamlined grid access procedures reduce project development timelines for utility-scale concentrator installations in California and Texas ISO zones.
Industry Challenges
- III-V epitaxy talent scarcity:Molecular beam epitaxy and metalorganic chemical vapor deposition specialists command premium compensation, constraining cell fabrication capacity expansion.
- IEC 62108 certification timeline compression:Module qualification protocols require 12-18 months for concentrator-specific thermal cycling and humidity freeze testing, delaying revenue recognition.
- Tracker-inverter protocol integration:Proprietary communication standards between tracking controllers and central inverters force custom engineering on each project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Concentration Photovoltaics Market |
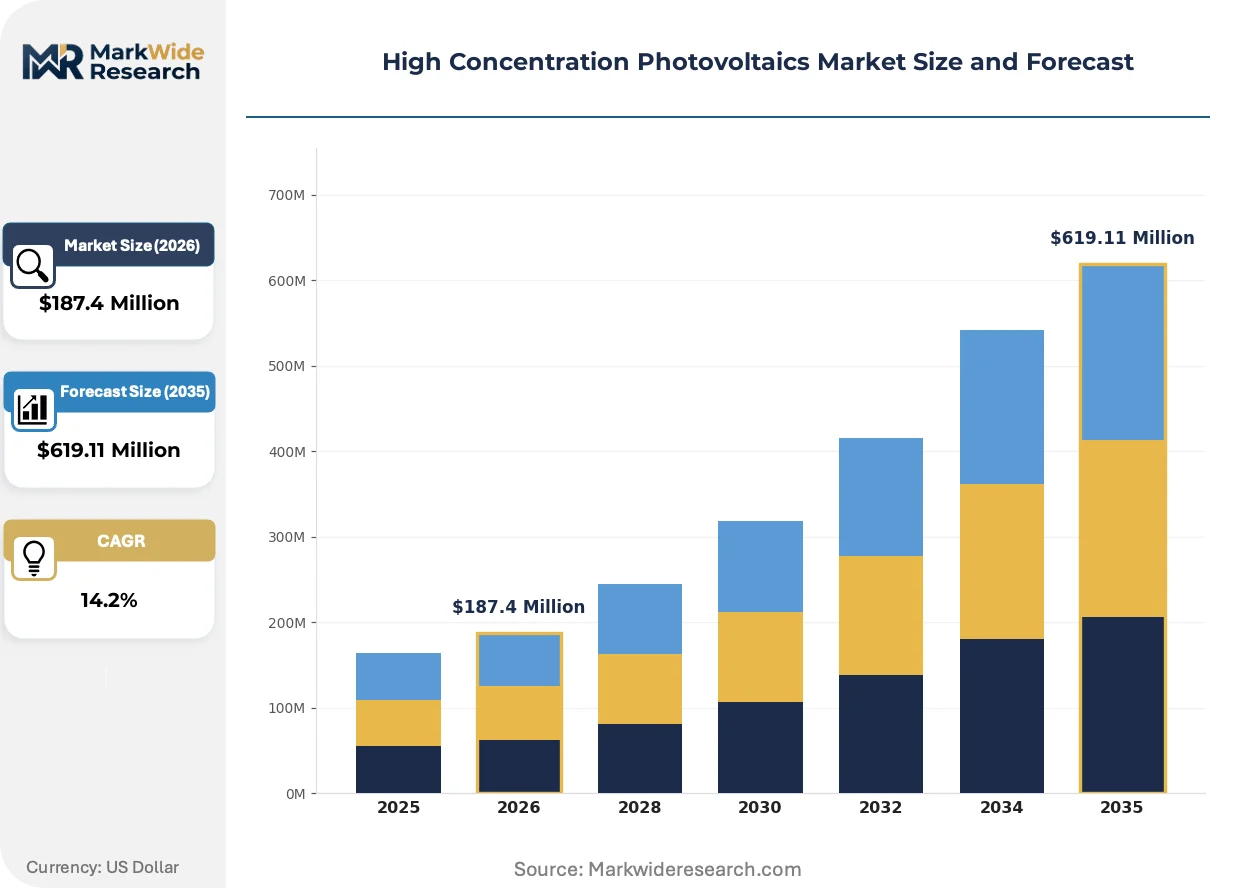
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Module, Inverter, Tracker, Cooling System Technology: Multi-Junction Cells, Concentrator Photovoltaics, Optical Components, Thermal Management End User: Utilities, Commercial, Industrial, Residential Installation: Ground-Mounted, Rooftop, BIPV, Offshore |
| Companies Covered | Soitec, SunPower Corporation, Solar Junction, Semprius, Magpower, SunCore Energy Group, Morgan Solar, Amonix, Arzon Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Concentration Photovoltaics Market Shifts & Advancements
Optical concentration architectures are converging with advanced thermal management and smart tracking systems, redefining system-level efficiency benchmarks while compressing balance-of-plant costs.
Silicone-on-glass primary optics is integrating with secondary homogenizing elements to achieve uniform flux distribution across multi-junction cell surfaces. Spanish and Australian utility developers are specifying these configurations in 2024-2025 tenders to reduce current mismatch losses. This integration is compressing the performance gap between laboratory cell efficiencies and field-deployed module outputs.
The EU Green Deal's delegated acts on renewable energy deployment are mandating stricter lifecycle carbon accounting for imported photovoltaic components. Module suppliers must now document embodied emissions from germanium mining through cell fabrication to qualify for European Investment Bank financing. Concentrator manufacturers with European substrate sourcing are capturing preferential offtake terms in Iberian Peninsula auctions.
Spanish renewable energy developers are consolidating engineering-procurement-construction contracts under single-point accountability structures that bundle tracker supply, installation, and performance guarantees. This model displaces fragmented subcontractor arrangements that previously separated mechanical and electrical scopes. The shift is most visible in Castilla y León and Andalusia where 100+ MW concentrator parks are advancing through final investment decision.
High Concentration Photovoltaics Market Segmentation
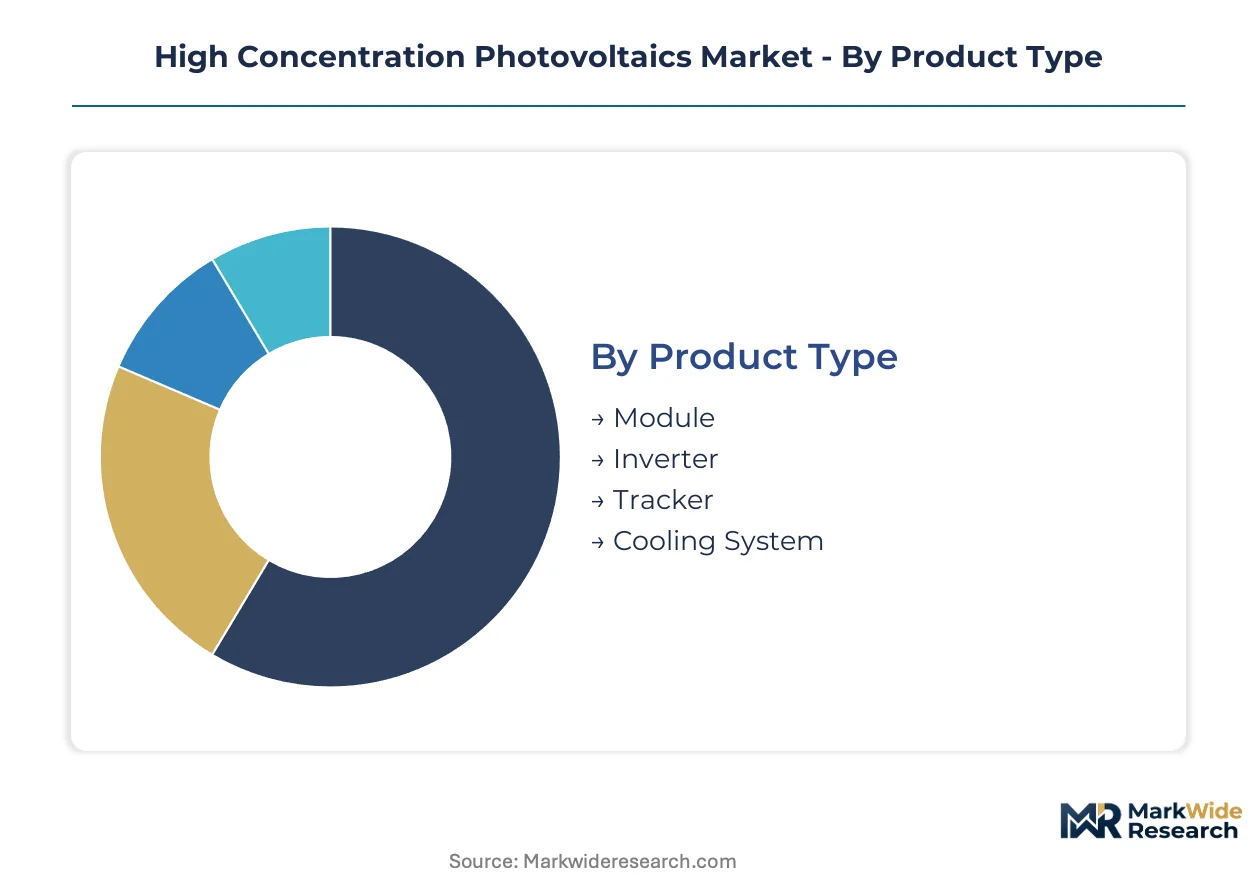
Concentrator photovoltaic systems fragment across four structural dimensions that determine procurement economics and deployment feasibility. Product type and technology segments define the upstream supply architecture, while end-user and installation categories shape downstream demand patterns and margin capture.
Product Type:
Supply concentration in precision optics and thermal engineering disciplines has concentrated vendor capabilities unevenly across component categories.
- Module:Multi-junction III-V cell assemblies mounted on engineered substrates dominate capital allocation in utility-scale deployments. Spanish developers in Extremadura and Castilla-La Mancha specify these modules for 500+ sun concentration ratios where land constraints maximize output per hectare.
- Tracker:Dual-axis precision tracking systems with sub-degree accuracy requirements command specialized mechanical engineering capabilities. Arid desert climates accelerate wear rates, elevating OPEX and warranty reserve requirements for EPC contractors bundling performance guarantees.
- Inverter:Central inverters adapted to concentrator output profiles handle high DC voltage conversion with proprietary communication protocols.
- Cooling System:Active thermal management components dissipate heat loads exceeding 300 suns concentration ratios.
Module assemblies absorb the bulk of installed capacity; cooling systems are expanding most quickly as concentration ratios climb toward next-generation architectures.
Technology:
Cost tier differentiation separates mature optical components from emerging thermal management architectures that capture premium engineering margins.
- Multi-Junction Cells:Lattice-matched gallium indium phosphide and gallium arsenide semiconductor layers achieve conversion efficiencies above 40 percent under direct normal irradiance. EU Green Deal delegated acts on lifecycle carbon accounting favor European substrate sourcing for EIB financing eligibility.
- Concentrator Photovoltaics:Integrated optical-electrical systems combining primary concentrators with cell receivers represent the core system architecture. Spanish EPC consolidation under single-point accountability structures is displacing fragmented subcontractor arrangements in Castilla y León and Andalusia.
- Optical Components:Silicone-on-glass primary optics with secondary homogenizing elements reduce current mismatch losses in Australian and Iberian tenders.
- Thermal Management:Heat extraction systems for high-concentration ratios enable industrial cogeneration applications in agricultural processing zones.
Multi-junction cells command the dominant share of technology value; thermal management is climbing the fastest as industrial cogeneration applications proliferate.
End User:
Customer type determines financing structures and performance guarantee requirements across deployment scales.
- Utilities:Grid-scale developers consolidating procurement around high-efficiency concentrator systems compress supplier margins while elevating technical qualification barriers. FERC Order 2023 interconnection reforms streamline project development timelines in California and Texas ISO zones.
- Commercial:Building-integrated concentrator facades capture dual-purpose envelope real estate in Madrid and Barcelona commercial corridors.
- Industrial:Process heat extraction from concentrator arrays serves district heating and agricultural processing applications.
- Residential:Limited deployment due to tracking complexity and maintenance requirements at small scale.
Utilities absorb the bulk of installed capacity; commercial applications are gaining share fastest through BIPV facade integration.
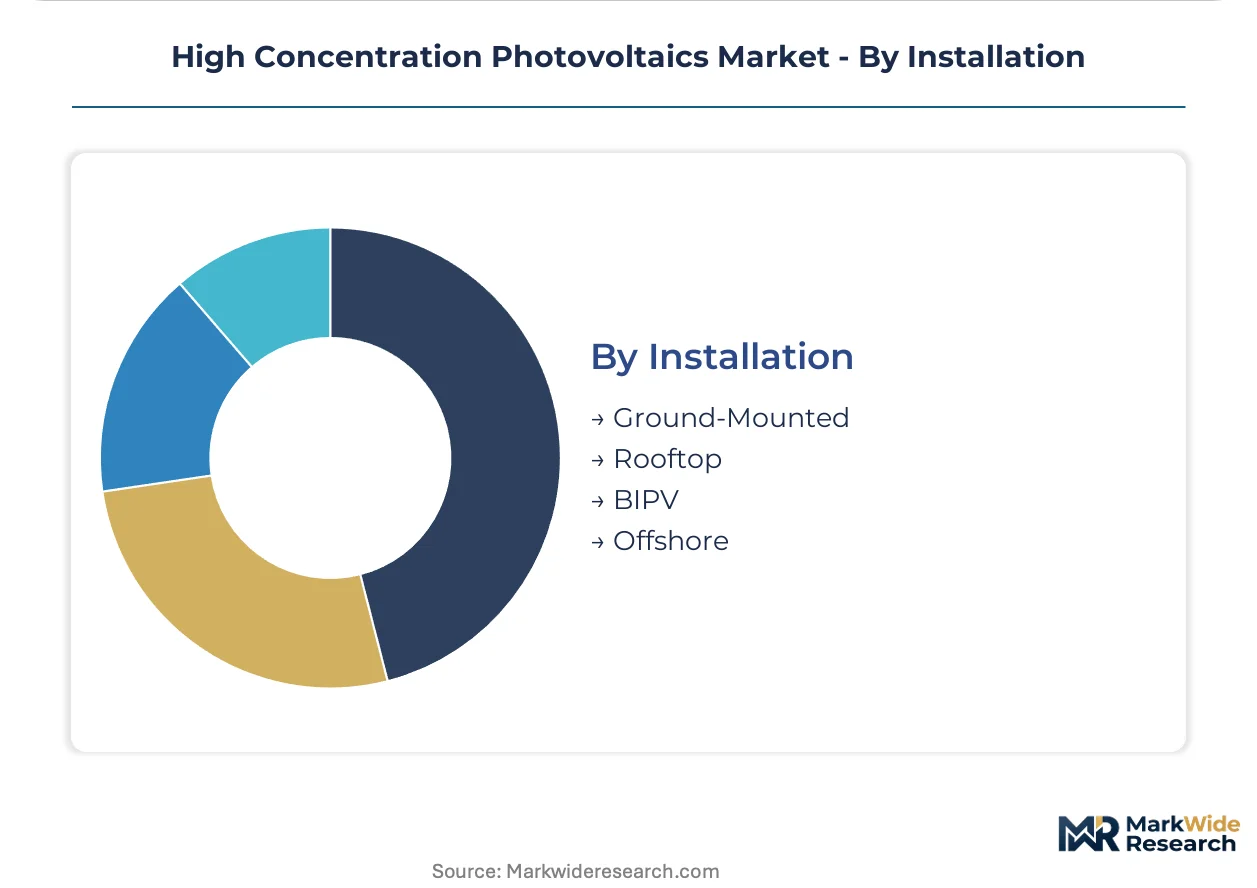
Installation:
Geography and land availability dictate mounting architecture selection and balance-of-plant cost structures.
- Ground-Mounted:Dominant deployment volume in arid plateau regions with optimal direct normal irradiance economics. Precision dual-axis tracking systems maximize energy harvest per hectare where land constraints apply.
- Rooftop:Limited applicability due to structural load requirements and tracking mechanism complexity.
- BIPV:Building-integrated concentrator systems serve dual-purpose commercial envelope functions in urban corridors seeking facade-based generation.
- Offshore:Nascent category with unproven economics for marine concentrator deployment.
Ground-mounted systems absorb the bulk of installed capacity; BIPV installations are expanding most quickly through commercial facade integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale procurement concentrates in Spain's arid plateau regions where direct normal irradiance supports optimal deployment economics for 500+ sun concentration ratios. The EU Green Deal's renewable energy targets are accelerating module efficiency requirements across Iberian Peninsula auction rounds. FERC interconnection standards and state-level renewable portfolio standards shape parallel demand formation in North American ISO zones.
Spain
Arid plateau regions in Extremadura and Castilla-La Mancha deliver superior direct normal irradiance economics for utility-scale concentrator deployments. Spain's national renewable energy plans and EU Green Deal delegated acts create compliance frameworks favoring high-efficiency multi-junction architectures. Engineering-procurement-construction contracts are consolidating under single-point accountability structures in Castilla y León and Andalusia where 100+ MW concentrator parks advance through final investment decision.
United States
California and Texas ISO zones concentrate utility-scale developer procurement around high-efficiency concentrator systems that maximize output per hectare. FERC Order 2023 interconnection reforms streamline grid access procedures and compress project development timelines. The California Energy Commission building codes and renewable portfolio standards create additional compliance layers for system designers deploying precision tracking infrastructure.
Australia
Utility developers in New South Wales and Queensland are specifying silicone-on-glass primary optics with secondary homogenizing elements in 2024-2025 tenders. The Australian Renewable Energy Agency funding programs support demonstration projects validating concentrator performance under high-insolation desert conditions. Remote mining and agricultural processing clusters in Western Australia are piloting industrial cogeneration applications extracting high-temperature thermal from concentrator arrays.
China
Concentrated supply of germanium substrates from domestic mining operations exposes cell manufacturers to input price volatility that compresses margin pools. The national dual carbon goals and renewable energy deployment targets under the 14th Five-Year Plan create demand pull for high-efficiency photovoltaic technologies. Industrial zones in Inner Mongolia and Xinjiang are emerging as deployment corridors where land constraints favor maximum output per unit area.
Saudi Arabia
NEOM Northwest and the Eastern Province are anchoring gigawatt-scale renewable energy ambitions where direct normal irradiance conditions match concentrator technology requirements. The Public Investment Fund renewable energy mandates and Saudi Vision 2030 diversification targets are reshaping procurement specifications toward high-efficiency architectures. Riyadh-based developers are bundling tracker supply with performance guarantees under long-term power purchase agreements.
High Concentration Photovoltaics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue thermal management specialization and building-integrated facade applications. The supplier base concentrates around three strategic archetypes: engineered substrate specialists sustaining multi-junction cell leadership, integrated tracker-and-module vendors anchoring North American project pipelines, and lattice-matched III-V semiconductor architects differentiating desert climate performance. Competitive dynamics center on backward integration into substrate supply and capacity expansion in precision optical fabrication.
Within the substrate-engineering tier, Soitec represents established European capabilities in engineered wafer production. SunPower Corporation and Solar Junction occupy positions across the integrated system and semiconductor architecture vectors respectively. These three entities exemplify divergent strategic postures: Soitec anchors upstream material control, SunPower Corporation bridges mechanical and electrical system integration, and Solar Junction concentrates on epitaxial cell fabrication processes.
| Leading Market Players |
|---|
| Soitec |
| SunPower Corporation |
| Solar Junction |
| Semprius |
| Magpower |
| SunCore Energy Group |
| Morgan Solar |
| Amonix |
| Arzon Solar |
| Others |
Supply & Pricing Matrix
Backward integration into germanium substrate supply anchors pricing power for multi-junction cell manufacturers while exposing them to concentrated mining economics in China and Russia. Utility-scale EPC contractors bundling tracker performance guarantees capture margin pools that module vendors forfeit under procurement consolidation pressure.
Pricing Analysis
Volume procurement by Spanish and Australian utility developers compresses module margins while thermal management specialists defend premium pricing tiers. Three-tier pricing structure across premium multi-junction assemblies, standard optical configurations, and economy tracker tiers reflects certification grade and volume scale differentiation. Cost compression in standard tracker tiers intensifies because flat-plate silicon substitution threatens concentrator economics in land-abundant markets. Commercial BIPV buyers exhibit lowest price sensitivity due to dual-purpose facade value capture, while utility procurement teams drive hardest bargain terms.
Supply Chain Analysis
Dual-sourcing requirements for III-V epitaxy equipment constrain cell fabrication capacity expansion as molecular beam epitaxy specialists command premium compensation. Supply concentrates in China for germanium substrates, Germany for engineered wafer processing, and the United States for precision tracker manufacturing. Raw material dependencies span gallium, indium, and germanium feedstocks. Single-source vulnerability in Chinese germanium mining exposes margin pools to geopolitical disruption. Distribution runs through EPC contractors consolidating under single-point accountability structures in Iberian Peninsula deployment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
III-V epitaxy talent scarcity props pricing for multi-junction cell output as fabrication capacity expansion hits hard constraints. Molecular beam epitaxy specialist availability limits throughput scaling regardless of capital deployment.
For Market Incumbents: Anchor substrate supply security through captive germanium sourcing or long-term offtake agreements with Chinese mining operations. Defend multi-junction cell leadership by accelerating IEC 62108 certification timelines for next-generation concentration architectures above 500 suns. Tracker mechanical reliability investments in desert climate engineering reduce warranty reserve drag on EPC performance guarantees.
For New Entrants and Emerging Players: Industrial cogeneration buyers in Spain's agricultural processing zones represent the most penetrable segment for thermal extraction system specialists. Building-integrated concentrator facade integration in Madrid and Barcelona commercial corridors offers white-space entry with lower capital intensity than ground-mounted utility competition. Partner with established EPC contractors as subsystem supplier rather than pursuing full system integration.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated solar developers seeking tracker-module bundling capabilities. Long-term viability favors thermal management specialists with industrial heat extraction expertise over pure-play optical component vendors. Watch FERC Order 2023 implementation velocity as inflection indicator for California and Texas project development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Germanium Substrate Supply Security | Captive mining offtake or backward integration insulates margin pools from Chinese supply volatility. |
| IEC 62108 Certification Acceleration | Compressed qualification timelines enable faster revenue recognition for next-generation concentration ratios. |
| Desert Climate Tracker Engineering | Enhanced mechanical reliability reduces OPEX and warranty reserves in Extremadura and Castilla-La Mancha deployments. |
| Industrial Cogeneration Partnership | Thermal extraction integration opens district heating markets in Spain's agricultural processing zones. |
| BIPV Facade System Development | Dual-purpose commercial envelope capture penetrates Madrid and Barcelona urban corridors with premium positioning. |
Research Methodology
Document review covered EU Green Deal delegated acts, FERC interconnection standards, IEC 62108 qualification protocols, and Spanish national renewable energy plans, complemented by interviews with utility-scale EPC contractors, III-V epitaxy equipment specialists, tracker mechanical engineers, and concentrator procurement officers at Iberian Peninsula developers. Secondary validation drew from project development databases, EIA renewable generation statistics, IEA technology roadmaps, and customs trade data for germanium and gallium feedstocks. Bottom-up module shipment estimates triangulated against top-down utility auction capacity allocations.
Cross-reference between historical deployment trajectories in Spain and Australia and panel input from tracker manufacturers and cell fabricators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled span product type, technology tier, end-user category, and installation architecture. CAGRs derived from slope analysis of utility procurement volume trends and efficiency improvement curves for multi-junction cell architectures. Forecast inputs incorporated direct normal irradiance economics by region and concentration ratio scaling assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to germanium price volatility, tracker mechanical reliability field data, and flat-plate silicon cost trajectories. Deviation in EU Green Deal delegated act implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
US Solar Market