
 Metallic Hot Stamping Foils Market | 2026-2036
Metallic Hot Stamping Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Hot Stamping Foils Market Foresight
EU Green Deal packaging recyclability mandates is decoupling metallic foil demand from non-recyclable laminate structures across European cosmetics and luxury goods. LEONHARD KURZ leverages captive holographic mastering and vacuum metallization infrastructure to sustain premium positioning in automotive interior trim. API Foilmakers anchors its competitiveness through specialized diffraction-pattern foils for anti-counterfeiting applications. UNIVACCO Foils Corporation dominates thin-film transfer technologies across Asian electronics packaging corridors.
Metallic hot stamping foils are vacuum-metallized polyester or polypropylene films, typically 12–25 micrometers thick, carrying a release layer, lacquer coat, and aluminum or alloy deposition that transfers under heat and pressure onto substrates. The primary purpose is imparting metallic luster, brand differentiation, and functional barrier properties to consumer-facing surfaces without bulk metal use. Transfer foils lead volume consumption in high-speed labeling lines, while specialty foils command margin concentration through holographic security and tactile effects. Packaging applications absorb the largest share of metallized foil output, though textile decoration represents the fastest-growing demand channel as fashion brands adopt foil-based sustainable embellishment.
FDA food-contact substance regulations and REACH chemical authorization constrain adhesive and lacquer formulations in foils destined for food packaging and European consumer goods. Japan's METI enforces JIS standards for heavy metal content in decorative foils used in children's products and electronics housings. ECHA's restriction roadmap on per- and polyfluoroalkyl substances threatens conventional release coatings, compelling reformulation investments across the supply base. Stakeholders must monitor regulatory divergence between EU chemical hazard classifications and US FDA food-contact thresholds when configuring regional product portfolios.
Market Dynamics
EU Green Deal packaging recyclability mandates are decoupling metallic foil demand from non-recyclable laminate structures across European cosmetics and luxury goods, forcing reformulation investments across vacuum metallization supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Premium cosmetic brands in Germany and France are abandoning conventional plastic labeling for metallized transfer foils that meet extended producer responsibility requirements.
- Textile decoration channel:Fashion brands are adopting foil-based sustainable embellishment as an alternative to water-intensive dyeing and chemical finishing processes.
- Electronics packaging corridors:Thin-film transfer technologies are penetrating Asian consumer electronics housings as brand differentiation intensifies in saturated smartphone and wearable markets.
Market Restraints
- Aluminum price volatility:Vacuum metallization input costs fluctuate with London Metal Exchange pricing, compressing margins for mid-tier foil converters without captive metal supply.
- Release coating dependency:Conventional per- and polyfluoroalkyl substance formulations face ECHA restriction roadmap timelines, requiring expensive reformulation before viable alternatives achieve scale.
- Polyester substrate concentration:Biaxially oriented polyester film supply clusters in East Asian petrochemical corridors, exposing converters to shipping cost spikes and currency exposure.
Strategic Opportunities
- India packaging modernization:BIS standards adoption and FSSAI food-contact compliance investments are opening premium foil applications in domestic FMCG and pharmaceutical blister packs.
- Holographic security convergence:Anti-counterfeiting diffraction-pattern foils are penetrating pharmaceutical serialization and tax stamp applications as regulatory traceability mandates expand.
- Automotive interior trim:Captive holographic mastering infrastructure enables tier-one suppliers to capture value from EV cabin differentiation strategies emphasizing premium surface finishes.
Industry Challenges
- Vacuum metallization technician scarcity:Specialized thin-film deposition expertise concentrates in Japan's Kansai industrial corridor and Germany's Rhine-Main packaging cluster, constraining capacity expansion elsewhere.
- REACH chemical authorization timelines:Lacquer and adhesive substance dossier preparation extends months beyond product development cycles, delaying commercialization of reformulated recyclable foils.
- Legacy labeling line integration:Hot stamping equipment retrofits for transfer foil compatibility require capital outlays that smaller converters defer amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Hot Stamping Foils Market |
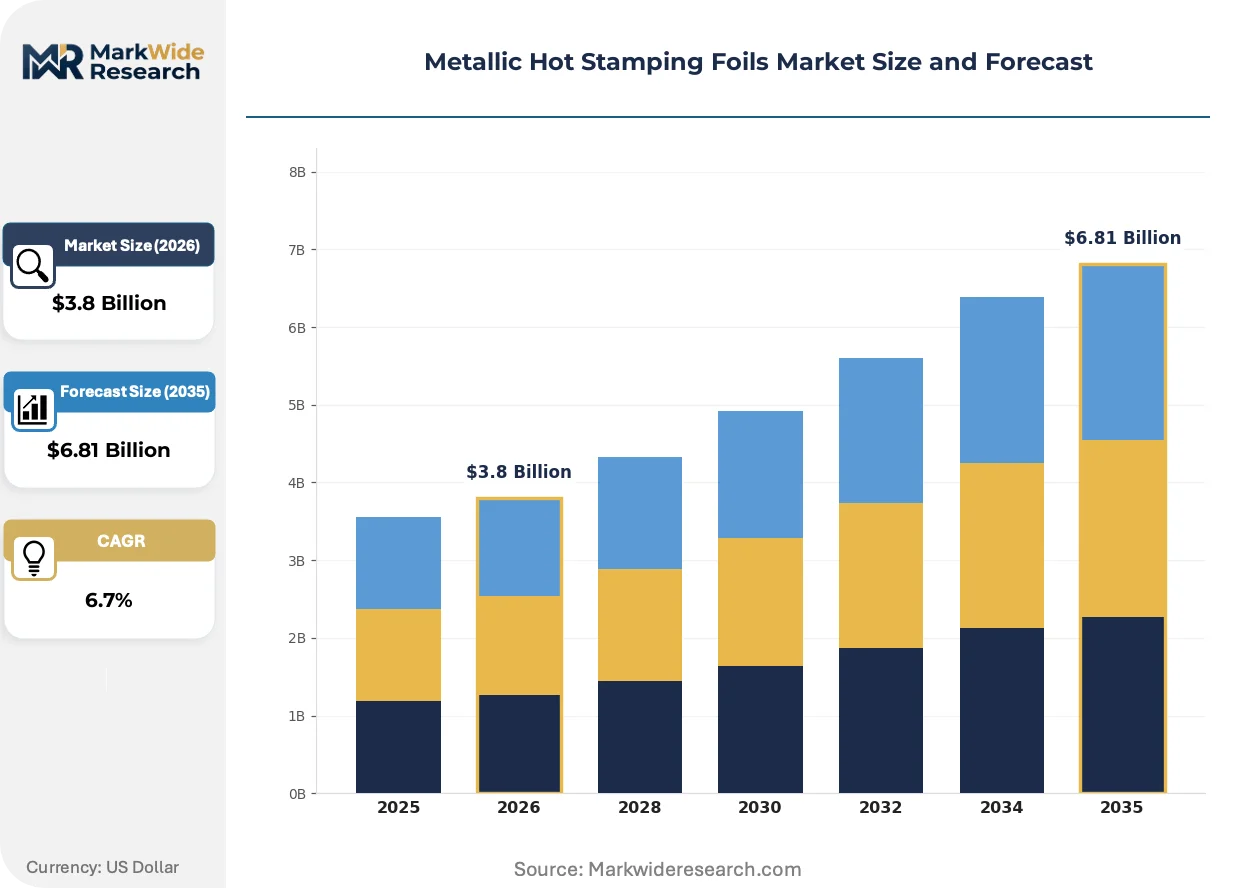
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfer Foils, Specialty Foils, Adhesive Foils, Standard Foils Application: Labeling, Packaging, Greeting Cards, Textile Decoration End User: Printing Industry, Packaging Manufacturers, Textile Companies, Crafting Businesses Technology: Hot Stamping, Digital Printing, Offset Printing, Flexographic Printing |
| Companies Covered | LEONHARD KURZ, API Foilmakers, UNIVACCO Foils Corporation, Crown Roll Leaf, CFC International, Nakai Industrial Group, Washin Chemical Industry, Mitsubishi Polyester Film, Dai Nippon Printing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Hot Stamping Foils Market Shifts & Advancements
Reformulation chemistry, digital mastering capabilities, and sustainability-driven procurement are compressing product lifecycles and reshaping competitive positioning across metallic foil value chains.
Water-based release coatings are converging with UV-curable lacquer systems to eliminate per- and polyfluoroalkyl substances from foil constructions. European cosmetics packagers in Germany's Rhine-Main corridor are piloting these formulations at commercial scale. The technology is converging with circular packaging mandates to create first-mover advantage for converters with validated recyclable structures.
REACH chemical authorization restrictions on per- and polyfluoroalkyl substances are forcing 18-month reformulation cycles across European foil supply bases. Manufacturers must resubmit lacquer and adhesive safety dossiers before existing formulations face sunset dates. Cosmetic and food packaging segments are accelerating qualification programs to avoid supply discontinuity.
Brand-led sustainable sourcing mandates are compressing supplier qualification timelines and unbundling technical service from material supply contracts. Major European luxury houses now require third-party recyclability certification before contract award. Germany and France exhibit the most aggressive audit frequency, with Japanese electronics brands following similar protocols for packaging components.
Metallic Hot Stamping Foils Market Segmentation
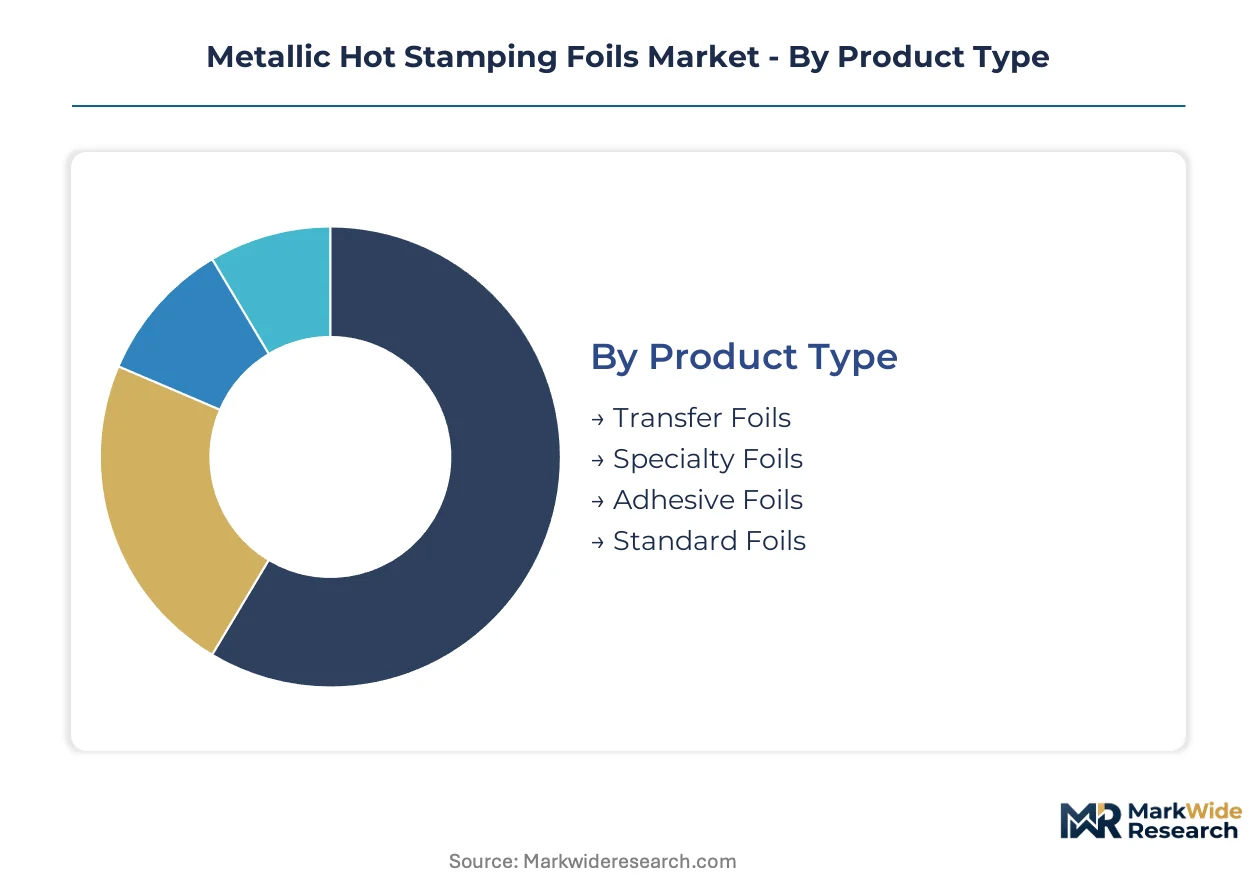
Metallic hot stamping foils fragment across four critical dimensions that determine procurement priorities and margin capture. Product type governs capital intensity and technical service requirements, while application channels dictate regulatory exposure and sustainability certification needs.
Product Type:
Purchase decisions in this category hinge on line speed compatibility and substrate adhesion requirements.
- Transfer Foils:Multi-layer constructions with release coatings, lacquer, and vacuum-deposited aluminum transfer cleanly under heat and pressure. Rhine-Main packaging clusters in Germany favor these for high-speed cosmetic labeling lines where EU recyclability mandates drive format switching.
- Specialty Foils:Holographic mastering and diffraction-pattern surfaces command premium positioning. API Foilmakers anchors competitiveness here through anti-counterfeiting applications in pharmaceutical serialization and tax stamp programs.
- Adhesive Foils:Pressure-sensitive constructions with pre-applied bonding layers suit short-run customization and prototyping workflows.
- Standard Foils:Conventional metallized polyester constructions serve cost-sensitive decorative applications with limited barrier requirements.
Volume sits with Transfer Foils; growth tilts toward Specialty Foils.
Application:
End-use concentration varies sharply by sustainability compliance burden and brand differentiation intensity.
- Packaging:Cosmetic and luxury goods absorption dominates European demand as brands abandon non-recyclable laminate structures. Washin Chemical Industry and Nakai Industrial Group are expanding metallized capacity specifically to serve this transition.
- Textile Decoration:Foil-based embellishment displaces water-intensive dyeing processes across fashion supply chains. This channel climbs the fastest as sustainable sourcing mandates compress supplier qualification timelines.
- Labeling:High-speed beverage and food applications require FDA food-contact substance compliance and REACH chemical authorization for adhesive systems.
- Greeting Cards:Seasonal demand concentration and lower regulatory exposure characterize this mature decorative segment.
Revenue concentrates in Packaging; expansion momentum favors Textile Decoration.
End User:
Customer technical sophistication determines service bundling and specification development intensity.
- Packaging Manufacturers:Tier-one converters in Germany's Rhine-Main corridor and Japan's Kansai industrial corridor drive qualification protocols for recyclable foil constructions. LEONHARD KURZ leverages captive holographic mastering to serve automotive interior trim differentiation.
- Printing Industry:Commercial printers balance equipment retrofit costs against transfer foil compatibility for legacy hot stamping lines.
- Textile Companies:Fashion brands now require third-party recyclability certification before contract award, with German and French houses exhibiting the most aggressive audit frequency.
- Crafting Businesses:Fragmented small-format demand with limited technical service requirements and price-sensitive procurement patterns.
Specification leadership rests with Packaging Manufacturers; fastest account expansion occurs among Textile Companies.
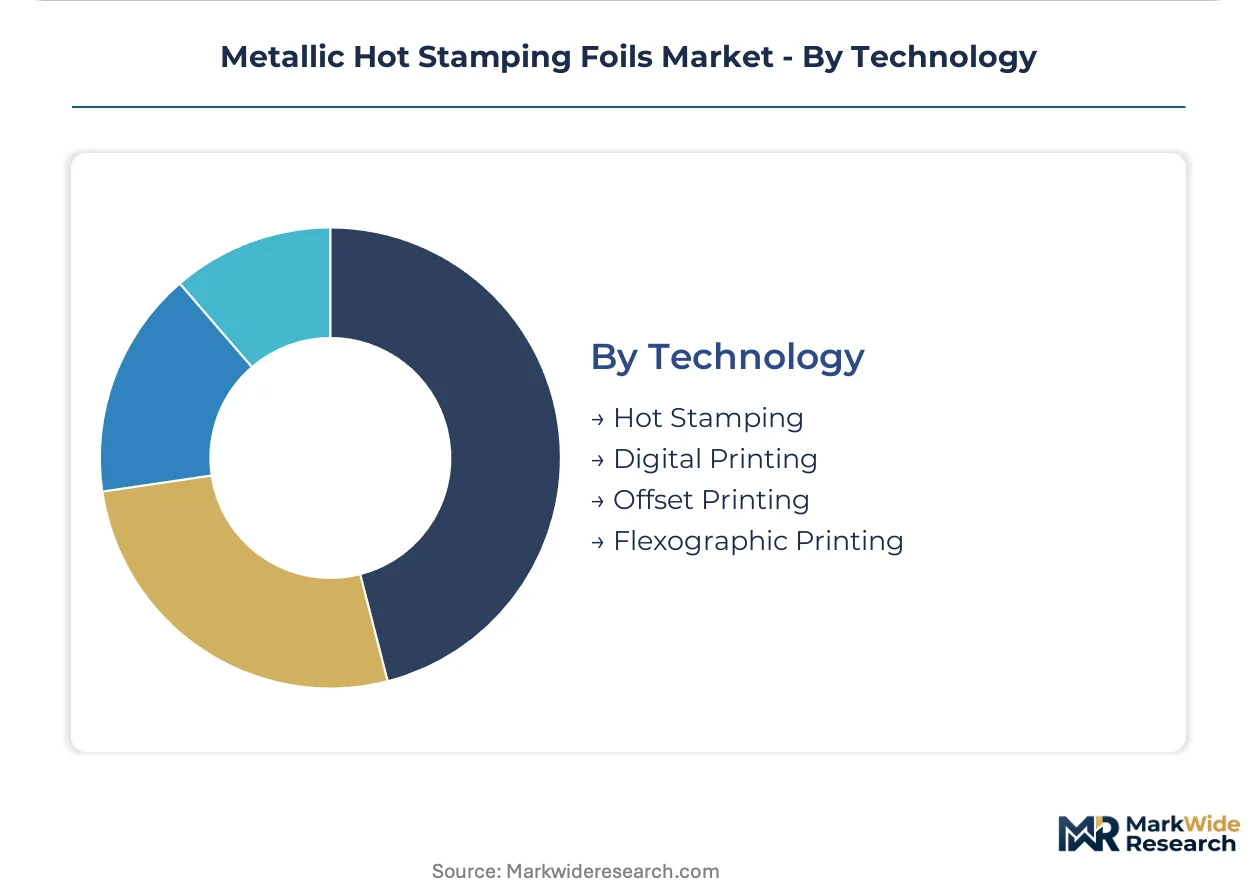
Technology:
Process selection constraints emerge from substrate sensitivity, run length economics, and registration precision requirements.
- Hot Stamping:Thermal transfer of metallized layers under pressure remains dominant for premium cosmetic and automotive applications demanding tactile surface effects.
- Digital Printing:Variable data integration and short-run flexibility serve personalized packaging and anti-counterfeiting serialization requirements.
- Flexographic Printing:Continuous-web efficiency suits high-volume beverage labeling with moderate metallic luster requirements.
- Offset Printing:Sheet-fed precision for greeting card and premium paperboard applications with established foil integration workflows.
Equipment installed base favors Hot Stamping; capability investment flows toward Digital Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Main packaging cluster concentrates European metallized foil demand as cosmetic brands accelerate format switching under EU Green Deal mandates.
Germany
Rhine-Main corridor converters drive qualification protocols for recyclable foil constructions serving premium cosmetic houses. ECHA's restriction roadmap on per- and polyfluoroalkyl substances forces 18-month reformulation cycles across lacquer and adhesive supply chains. Frankfurt-area packaging manufacturers now require third-party recyclability certification before contract award.
Japan
Kansai industrial corridor hosts specialized vacuum metallization expertise for electronics housings and automotive interior trim applications. METI enforces JIS standards for heavy metal content in decorative foils used in children's products. Osaka-based technicians concentrate thin-film deposition capabilities that constrain capacity expansion elsewhere.
United States
FDA food-contact substance regulations govern adhesive and lacquer formulations in foils destined for beverage labeling and food packaging segments. EPA oversight intersects with state-level extended producer responsibility frameworks emerging in California and New York. Midwestern converters balance legacy hot stamping equipment retrofits against transfer foil compatibility requirements.
France
Paris-based luxury houses exhibit aggressive audit frequency for sustainable sourcing mandates in packaging components. EU Packaging and Packaging Waste Regulation drives abandonment of conventional plastic labeling for metallized transfer foils. Cosmetic packagers in the Île-de-France region pilot water-based release coatings at commercial scale.
India
Domestic FMCG and pharmaceutical blister pack applications expand as BIS standards adoption and FSSAI food-contact compliance investments mature. Maharashtra and Gujarat packaging corridors attract premium foil converters targeting modernization opportunities. Mumbai-area manufacturers qualify recyclable constructions for export markets while serving growing domestic demand.
Metallic Hot Stamping Foils Market Competitive Landscape
Premium-margin players sit above commodity-margin players across holographic mastering and vacuum metallization infrastructure depth. The vendor base stratifies between captive technology holders and toll metallization converters. Three archetypes dominate: integrated holographic masters with in-house deposition capacity, specialized diffraction-pattern security foilists, and regional toll converters serving high-speed labeling lines. Competitive moves center on capacity expansion in Asian electronics corridors and strategic partnerships for PFAS-free formulation development.
Within the integrated infrastructure tier, LEONHARD KURZ and API Foilmakers exemplify divergent specialization strategies. LEONHARD KURZ anchors German engineering-intensive positioning through captive holographic mastering and vacuum metallization assets. API Foilmakers occupies British Isles-based security specialization focused on anti-counterfeiting diffraction-pattern applications. UNIVACCO Foils Corporation represents Asian thin-film transfer technology concentration across consumer electronics packaging corridors. These three entities illustrate how geographic clustering around industrial corridors shapes competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| LEONHARD KURZ |
| API Foilmakers |
| UNIVACCO Foils Corporation |
| Crown Roll Leaf |
| CFC International |
| Nakai Industrial Group |
| Washin Chemical Industry |
| Mitsubishi Polyester Film |
| Dai Nippon Printing |
| Others |
Supply & Pricing Matrix
Water-based release coating adoption across European cosmetic packaging corridors simultaneously compresses production cost curves and redistributes supply leverage toward converters with validated PFAS-free formulations. This chemistry transition rewards early movers in Germany's Rhine-Main cluster while penalizing legacy coating dependencies.
Pricing Analysis
Throughput-based pricing anchors foil procurement contracts, with converters charging per-thousand-impression rates tied to line speed compatibility and substrate adhesion performance. Three-tier pricing structure across premium holographic, standard transfer, and economy-grade decorative foils separates security-certified pharmaceutical grades from commodity cosmetic applications. Pricing pressure stems from aluminum London Metal Exchange volatility compressing margins for non-integrated converters. Mid-tier labeling manufacturers exhibit highest price sensitivity, while automotive interior trim buyers prioritize tactile surface consistency over unit cost.
Supply Chain Analysis
Release liner recovery and metallized film edge-trim reclamation flows are emerging as cost-recovery channels for converters facing raw material headwinds. Vacuum metallization capacity concentrates in Germany, Japan, and South Korea, with biaxially oriented polyester substrate supply anchored in East Asian petrochemical corridors. Aluminum deposition feedstock draws from London Metal Exchange-linked suppliers, while lacquer formulations hinge on REACH-authorized chemical distributors. Single-source vulnerability in specialized vacuum metallization technician pools constrains capacity expansion outside Kansai and Rhine-Main clusters. Distribution runs through converter-direct relationships with tier-one packaging manufacturers and regional toll metallization partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PFAS-free reformulation chemistry is displacing conventional release coatings, forcing a capability-transition window where first-mover validation determines contract access. This technology shift compresses qualification timelines and unbundles technical service from material supply.
For Market Incumbents: To counter ECHA restriction roadmap timelines threatening conventional coating formulations, LEONHARD KURZ and API Foilmakers should accelerate captive holographic mastering capacity additions in Asian electronics corridors. Backward integration into water-based release coating chemistry secures formulation control before viable alternatives achieve commodity scale. Certification investment in third-party recyclability validation preserves contract access with Paris-based luxury houses and German cosmetic packagers.
For New Entrants and Emerging Players: Regional Indian pharmaceutical blister pack converters represent the most penetrable buyer archetype, with BIS standards adoption creating qualification entry points for FSSAI-compliant foil suppliers. Maharashtra and Gujarat packaging corridors offer white-space expansion as domestic FMCG modernization accelerates. A toll metallization partnership model with established lacquer suppliers minimizes capital intensity while building regulatory dossier experience.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging conglomerates seeking holographic security capabilities. Long-term viability favors converters with validated PFAS-free portfolios and captive vacuum metallization infrastructure across the analysis window. Acquisition targets should demonstrate thin-film deposition expertise in electronics packaging applications. Practitioners should monitor ECHA sunset date announcements for early signals of supply discontinuity windows.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Development | ECHA restriction timelines force 18-month reformulation cycles across European lacquer supply chains. |
| Captive Holographic Mastering Expansion | In-house diffraction-pattern capabilities capture automotive interior trim differentiation value from EV manufacturers. |
| India Market Entry Partnership | BIS standards adoption and FSSAI compliance investments open premium foil applications in domestic pharmaceutical packaging. |
| Textile Decoration Channel Development | Fashion brand sustainable sourcing mandates compress supplier qualification timelines for foil-based embellishment alternatives. |
| Recyclability Certification Investment | Third-party validation requirements from German and French luxury houses determine contract award eligibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this metallic hot stamping foils assessment. Primary interviews with vacuum metallization plant managers, cosmetic packaging procurement leads, automotive tier-one supplier engineers, and distribution channel partners combined with secondary validation from ECHA restriction roadmaps, FDA food-contact substance databases, and METI JIS standards documentation. Bottom-up foil consumption estimates by application channel triangulated against top-down vacuum metallization capacity assessments across Germany, Japan, and South Korea.
Product-level granularity modeled transfer foil, specialty holographic, adhesive, and standard foil constructions separately across packaging, textile decoration, labeling, and greeting card applications. End-user segmentation captured packaging manufacturer, printing industry, textile company, and crafting business procurement patterns. Technology dimensions included hot stamping, digital printing, flexographic, and offset integration requirements. CAGRs derived from segment-level volume build-ups and value-per-unit trajectories, with aluminum price volatility and REACH authorization timelines as explicit forecast sensitivities.
Revisions become necessary when ECHA per- and polyfluoroalkyl substance restriction dates accelerate, London Metal Exchange aluminum price bands shift beyond historical ranges, or vacuum metallization technician migration patterns alter capacity availability. Forecasts reflect assumptions about reformulation chemistry scale-up timelines and brand-led sustainable sourcing mandate adoption rates. Practitioners should monitor ECHA sunset date confirmations and EU Packaging and Packaging Waste Regulation implementation schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Mesoporous Silica Market