
 South America Wheat Market | 2026-2036
South America Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
South America Wheat Market Analytics
Specialty flour bundling is shifting buyer procurement patterns across South American millers. Bunge leverages its Rosario crushing complex to sustain export-grade wheat flows into Brazilian northeast markets. Cargill anchors Atlantic port logistics, while Archer Daniels Midland differentiates through protein-content blending services for industrial bakeries.
Wheat comprises the harvested grain of Triticum aestivum and related species, with protein content typically ranging from 8% to 15% depending on cultivar and growing conditions; its endosperm hardness determines suitability for bread leavening, pasta extrusion, or feed formulation. Hard Red Winter wheat dominates milling volumes across the Mercosur trade zone due to its gluten strength and drought tolerance in Argentine cultivation zones. Food Grade classification commands premium positioning among Brazilian supermarket chains, while Animal Feed applications absorb lower-protein harvests from marginal rainfall seasons. Organic grade remains nascent but occupies expanding shelf space in São Paulo and Buenos Aires retail channels.
ANVISA enforces maximum mycotoxin thresholds under Mercosur harmonized standards, while Argentina's National Service for Agri-Food Health and Quality (SENASA) mandates phytosanitary certificates for cross-border grain movements. Brazil's MAPA operates inspection protocols at Paranaguá and Santos terminals that directly determine import clearance speed and storage demurrage costs. Stakeholders must monitor evolving SENASA-MAPA bilateral recognition agreements, as procedural friction between these bodies could reroute trade flows through Uruguayan transshipment corridors.
Market Dynamics
ANVISA's updated mycotoxin thresholds and MAPA's traceability mandates are compressing import clearance timelines at Brazilian ports, forcing millers to requalify supplier networks and absorb higher inspection-related demurrage costs.
Growth Catalysts
- Hard Red Winter demand:Bakery chains across Brazil's northeast corridor are absorbing larger volumes of Argentine-origin grain as consumer bread consumption intensifies.
- MAPA traceability protocols:Brazil's mandatory silo-to-port documentation systems are creating quality premiums for compliant suppliers in the Pampas corridor.
- Protein-content blending:Industrial bakeries are specifying custom gluten-strength formulations that reward suppliers with in-house laboratory capabilities.
Market Restraints
- Port logistics concentration:Argentina's export throughput depends on Rosario-Paraná river depth, creating chokepoint vulnerability during drought cycles.
- Mercosur phytosanitary friction:SENASA-MAPA bilateral recognition gaps generate inspection delays that reroute grain through Uruguayan transshipment.
- Feed-grade absorption:Marginal rainfall seasons in Córdoba and Santa Fe provinces force protein downgrades into lower-margin animal feed channels.
Strategic Opportunities
- Organic grade expansion:São Paulo and Buenos Aires retail channels are dedicating expanding shelf space to certified organic flour despite nascent supply.
- Atlantic port infrastructure:Santos terminal operators are investing in dedicated wheat silo capacity to capture redirected Argentine export flows.
- Cross-border silo integration:Digital inventory tracking between Argentine Pampas elevators and Brazilian millers is compressing working capital cycles.
Industry Challenges
- Phytosanitary certification timelines:SENASA documentation processing creates 7-14 day pre-shipment delays that conflict with just-in-time miller procurement.
- Laboratory capability scarcity:mycotoxin testing capacity at Paranaguá and Santos remains insufficient for MAPA's stepped-up inspection frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Wheat Market |
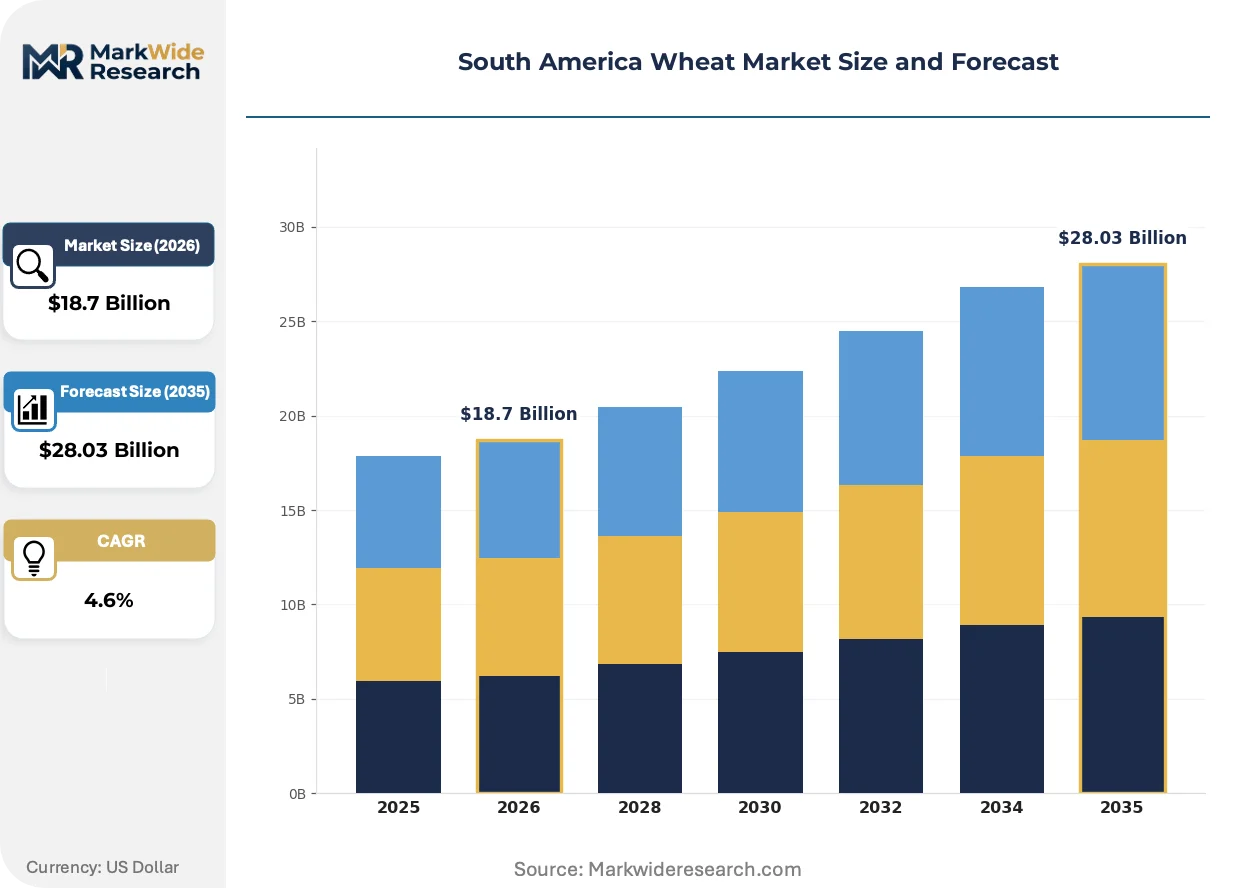
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Red Winter, Soft Red Winter, Hard Red Spring, Durum Application: Baking, Pasta Production, Animal Feed, Brewing Grade: Feed Grade, Food Grade, Organic, Non-GMO Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce |
| Companies Covered | Bunge, Cargill, Archer Daniels Midland, Viterra, COFCO International, Tereos, Ingredion, Cunaco, Windmill Agriculture Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Wheat Market Evolving Landscape
Digital traceability systems and protein-content customization are compressing traditional procurement cycles, while regulatory harmonization pressures force simultaneous compliance investments across multiple national frameworks.
Blockchain-enabled grain provenance tracking is decentralizing quality verification away from port-side inspection stations toward origin-silo certification. Argentine cooperatives in the Pampas corridor are adopting distributed ledger systems at accelerating rates. This shift is decentralizing trust mechanisms and reducing clearance-time variance for export-grade shipments.
ANVISA's mycotoxin threshold harmonization with Mercosur standards is tightening maximum allowable levels for aflatoxin and deoxynivalenol in food-grade wheat. Brazilian millers must now maintain dual-certification documentation for both domestic sale and cross-border re-export. The industrial bakery segment is responding by demanding supplier-provided pre-shipment laboratory certificates.
Specialty flour bundling is compressing traditional spot-market procurement toward annual protein-content contracts with specified gluten-strength tiers. Brazilian supermarket chains are consolidating supplier relationships to secure consistent baking performance across private-label bread lines. This pattern is most visible in São Paulo's metropolitan distribution networks, where centralized purchasing desks now dominate volume allocation decisions.
South America Wheat Market Segmentation
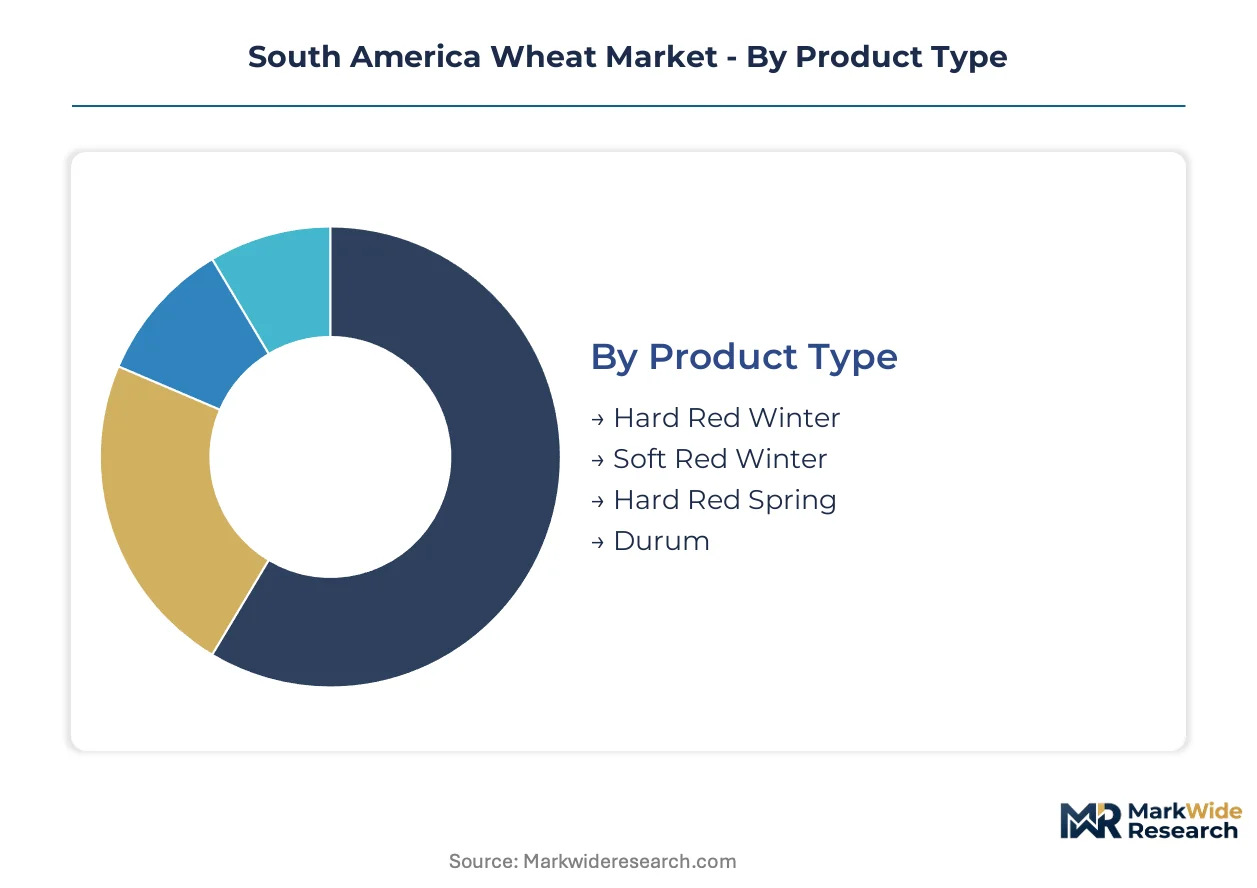
Wheat segmentation across South America reflects protein specification hierarchies that determine milling value and end-use compatibility. Argentine Pampas cultivation patterns and Brazilian import protocols create divergent demand profiles across product categories.
Product Type:
Protein content and gluten strength define the technical axis for milling performance and end-use suitability.
- Hard Red Winter:Gluten strength ranges from 11-13% protein, delivering the elastic dough structure required for industrial bread leavening. Brazilian northeast bakery chains absorb the largest volumes as consumer bread consumption intensifies across Fortaleza and Recife metropolitan corridors.
- Durum:Semolina extraction from this 12-14% protein wheat enables pasta extrusion with superior cooking integrity. Argentine pasta manufacturers in Buenos Aires province concentrate procurement here, though drought cycles in Córdoba occasionally compress supply reliability.
- Soft Red Winter:Lower protein at 8-10% suits cake flour and biscuit applications requiring tender crumb structure. São Paulo confectionery processors specify this grade for private-label cookie lines.
- Hard Red Spring:Highest protein concentration at 13-15% supports specialty high-gluten blends. Limited Argentine cultivation confines this segment to premium artisanal bakery contracts.
Mature deployment sits with Hard Red Winter across Mercosur trade corridors. Newer deployment is concentrated in Durum as Argentine pasta exports gain European market access.
Application:
End-use specifications create divergent procurement patterns across industrial buyers and commodity channels.
- Baking:Industrial bread production demands consistent gluten-strength profiles for automated line performance. Brazilian supermarket chains now specify protein-content tiers in annual supplier contracts rather than spot-market purchasing.
- Animal Feed:Lower-protein harvests from marginal rainfall seasons in Santa Fe province absorb into poultry and swine rations. Feed-grade pricing discounts of 15-20% below food-grade thresholds redirect surplus volumes.
- Pasta Production:Durum semolina extraction requires precise granulation control for extrusion die compatibility. Argentine processors maintain captive supply relationships with Pampas cooperatives.
- Brewing:Malt wheat specifications demand specific enzymatic activity profiles for fermentation performance. Craft brewery expansion in São Paulo and Buenos Aires is climbing the fastest for this niche segment.
Volume concentration favors Baking applications. Margin expansion is migrating toward Brewing as craft segment premiums justify specialized procurement.
Grade:
Certification thresholds separate commodity flows from premium-positioned channels.
- Food Grade:ANVISA mycotoxin compliance and MAPA traceability documentation command supermarket shelf placement. Brazilian northeast retail chains now require dual-certification for cross-border re-export eligibility.
- Organic:Certified cultivation absence of synthetic inputs occupies expanding shelf space in São Paulo and Buenos Aires premium retail channels. Supply scarcity limits volume despite price premiums of 25-35% above conventional.
- Feed Grade:Relaxed quality tolerances absorb protein-downgraded harvests from drought-affected cultivation zones. SENASA phytosanitary requirements still apply for cross-border movements.
- Non-GMO:Identity-preserved supply chains satisfy European export specifications and domestic consumer preference segments. Segregation infrastructure costs compress margins relative to organic certification.
Established certification infrastructure supports Food Grade dominance. Fastest share gains are occurring in Organic as retail channel expansion outpaces Pampas cultivation conversion timelines.
Distribution Channel:
Logistics configuration and buyer scale determine channel selection across the value chain.
- Wholesale:Bulk silo-to-mill transfers dominate Argentine-Brazilian trade flows. Paranaguá and Santos terminal operators provide dedicated wheat handling infrastructure for major miller procurement.
- Direct Sales:Large industrial bakeries and pasta manufacturers contract directly with Pampas cooperatives for specified protein-content harvests. Digital inventory tracking compresses working capital cycles.
- Retail:Packaged flour sales through Brazilian supermarket chains support private-label bread program consistency. Centralized purchasing desks now dominate volume allocation.
- E-commerce:Specialty and organic flour segments leverage direct-to-consumer platforms in São Paulo metropolitan distribution networks. Logistics costs constrain viability for standard-grade bulk sales.
Volume concentration remains with Wholesale channel infrastructure. Emerging deployment is concentrating in E-commerce as specialty grade fragmentation rewards direct consumer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina produces surplus wheat for export while Brazil consumes more than it grows, creating a structural trade flow across Mercosur borders. Uruguay and Paraguay occupy intermediate positions as transshipment corridors and niche suppliers. Chile and Colombia import from regional sources to supplement limited domestic cultivation.
Brazil
Northeast bakery chains in Fortaleza and Recife absorb expanding volumes of Argentine Hard Red Winter wheat as bread consumption intensifies. ANVISA enforces updated mycotoxin thresholds that compress import clearance timelines at Paranaguá and Santos terminals. São Paulo's metropolitan distribution networks concentrate procurement decisions through centralized supermarket purchasing desks.
Argentina
The Pampas corridor generates export-grade surpluses with protein content specifications that command Brazilian miller premiums. SENASA mandates phytosanitary certificates for cross-border grain movements, creating documentation bottlenecks before vessel loading. Rosario's river port infrastructure anchors Atlantic export throughput, though drought cycles periodically constrain Paraná river depth.
Uruguay
Transshipment corridors gain volume when SENASA-MAPA bilateral recognition gaps generate inspection delays at direct Argentine-Brazilian border crossings. The country's national agricultural health regulator maintains phytosanitary protocols aligned with Mercosur harmonized standards. Montevideo terminal operators provide alternative clearance pathways for grain rerouted from Buenos Aires province elevators.
Paraguay
Lower-protein harvests from marginal rainfall seasons absorb into regional animal feed channels at 15-20% discounts below food-grade thresholds. The country's grain export documentation system interfaces with Brazilian MAPA traceability requirements for cross-border movements. Silo infrastructure along the Paraná river supports barge consolidation for downstream Brazilian miller delivery.
Chile
Domestic wheat cultivation concentrates in central valley zones with insufficient volume to satisfy Santiago metropolitan bakery demand. Import dependence drives procurement from Argentine Pampas sources despite higher logistics costs versus Brazilian northeast markets. Valparaíso port operators handle bulk grain discharge for distribution to Concepción industrial baking clusters.
South America Wheat Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South American wheat handling and processing. The market structure concentrates around integrated agribusiness groups with crushing, milling, and export terminal assets. Strategic archetypes include river-logistics-anchored traders, protein-blending service providers, and cooperative-origin direct sellers. Competitive moves center on Atlantic port capacity expansion and cross-border digital inventory integration.
Among integrated agribusiness groups, Bunge, Cargill, and Archer Daniels Midland occupy positions representing distinct operational models. Bunge exemplifies river-system-anchored trading with Rosario complex infrastructure. Cargill represents Atlantic port logistics specialization. Archer Daniels Midland occupies the protein-content blending service tier for industrial bakery specifications.
| Leading Market Players |
|---|
| Bunge |
| Cargill |
| Archer Daniels Midland |
| Viterra |
| COFCO International |
| Tereos |
| Ingredion |
| Cunaco |
| Windmill Agriculture Company |
| Others |
Value Network & Pricing Analysis
Labor concentration among specialized grain inspectors at Paranaguá and Santos terminals widens pricing spreads between compliant and non-compliant wheat lots, as demurrage cost absorption separates premium-tier food-grade suppliers from feed-grade discount channels.
Pricing Analysis
Margin tightening in food-grade tiers reflects ANVISA mycotoxin compliance costs and MAPA documentation burdens that compress clearance speed premiums. Three-tier pricing structure across organic, food-grade, and feed-grade levels rewards pre-certified Pampas cooperatives with faster working capital turns. Price differentiation hinges on protein-content verification and dual-certification status for cross-border re-export eligibility. Industrial bakeries exhibit lowest price sensitivity due to formulation consistency requirements, while animal feed processors absorb marginal harvests at steepest discounts during drought cycles.
Supply Chain Analysis
River-barge freight rates from Rosario to Atlantic terminals fluctuate with Paraná water depth, amplifying cost variance across Argentine export seasons. Supply concentrates in Argentina's Pampas corridor, with secondary flows from Uruguay transshipment and Paraguayan feed-grade surplus. Raw material dependencies include phosphate fertilizers, glyphosate inputs, and certified seed stock. Single-source vulnerability sits with Rosario port infrastructure during drought-constrained navigation windows. Distribution runs through wholesale silo-to-mill transfers, with direct sales gaining share among protein-specifying industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over origin-silo certification and Atlantic port capacity determines margin capture across quality-tiered procurement channels.
For Market Incumbents: Deploy captive laboratory capabilities at Pampas elevator sites to preempt SENASA documentation delays and secure MAPA fast-track clearance. Consolidate Rosario river-terminal assets to defend against drought-cycle logistics disruption. Threats from digital-traceability specialists and organic-certification entrants demand backward integration into cooperative origination networks. For New Entrants and Emerging Players: Specialty flour distributors in São Paulo metropolitan networks represent the most penetrable channel partner type for organic-grade market share gains. White-space targets include craft brewery malt-wheat specifications and e-commerce direct-to-consumer organic flour. Go-to-market execution should leverage ANVISA pre-certification partnerships to bypass incumbent inspection-queue advantages. For Investors and Strategic Acquirers: Re-rating potential sits with protein-blending service providers given industrial bakery demand for custom gluten-strength formulations. Long-term viability favors operators with integrated Pampas-Atlantic logistics footprints over pure-trading intermediaries. Inflection signal to watch: SENASA-MAPA bilateral recognition agreement progress that eliminates Uruguayan transshipment arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pampas Silo Networks | Captive origin certification compresses SENASA-MAPA clearance timelines for export-grade flows. |
| Atlantic Port Capacity Expansion | Santos terminal operators capture redirected Argentine export volumes during Paraná drought constraints. |
| Digital Inventory Tracking Deployment | Blockchain-enabled provenance reduces demurrage variance and accelerates working capital cycles. |
| Organic Certification Program Buildout | São Paulo retail channel expansion outpaces Pampas cultivation conversion, creating supply scarcity premiums. |
| Protein-Content Blending Service Investment | In-house laboratory capabilities command industrial bakery contracts specifying gluten-strength tiers. |
Research Methodology
Document review covered SENASA phytosanitary filings, MAPA import clearance records, and Mercosur harmonized standards, complemented by interviews with grain elevator operators, port terminal managers, and industrial bakery procurement directors. Secondary validation drew from customs trade data, ANVISA regulatory bulletins, and cooperative export disclosures. Bottom-up volume triangulation against top-down trade flow analysis ensured cross-verification of Pampas corridor throughput estimates.
Segment-level projections across the analysis window incorporated protein-grade specifications, application-specific demand elasticity, and certification-tier pricing premiums. The analytical framework modeled Hard Red Winter, Durum, and Soft Red Winter varietals alongside food-grade, organic, and feed-grade certification channels. CAGRs derived from historical trade flow velocity and projected bakery consumption intensity in Brazilian northeast corridors. Forecast inputs included Paraná river depth variability and ANVISA inspection frequency trends.
Caveats apply where SENASA-MAPA bilateral friction, drought-cycle export constraints, or organic supply scarcity could materially shift the outlook. Forecasts embed assumptions regarding Mercosur regulatory harmonization progress and Pampas infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Brazil Maize Market
Grains
IQF Rice Market
Grains
Asia Pacific Maize Market
Grains
Paraguay Grains Market
Grains
Grain Silos and Storage System Market
Grains
Argentina Maize Market
Grains
Argentina Grains Market
Grains
Masa Corn Products Market
Grains
Africa Maize Market
Grains
Egypt Rice Market
Grains
Barley Market
Grains
Global Oats Market
Grains
Grain Augers Market
Grains
Heritage Grain Market
Grains
Canada Pulses Market
Grains
Lentil Market