
 Phytogenic Poultry Feed Additives Market | 2026-2036
Phytogenic Poultry Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Phytogenic Poultry Feed Additives Market Insights
Synthetic antibiotic growth promoters is shifting toward essential oils and herbal extracts across integrated poultry operations. DSM-Firmenich leverages its nutrition science platform to develop standardized phytogenic compounds with reproducible bioactive profiles. Cargill, Incorporated anchors its feed additive division through backward integration into botanical sourcing networks across multiple continents. Delacon Biotechnik GmbH specializes in species-specific phytogenic formulations that target gut microbiome modulation in broiler flocks.
Phytogenic poultry feed additives comprise plant-derived bioactive compounds—primarily essential oils, herbal extracts, spices, and oleoresins—delivered through premixes, straight feeds, or liquid forms to enhance feed conversion efficiency, gut health, and pathogen resistance. These additives typically contain specified concentrations of terpenoids, phenolics, and alkaloids that exert antimicrobial, anti-inflammatory, or antioxidant effects at the intestinal level. Essential oils currently lead product type revenue due to established supply chains and standardized extraction protocols, while herbal extracts represent the fastest-expanding category as extraction technologies improve yield consistency. Among applications, broiler operations command the largest volume share given their scale and margin sensitivity, whereas layer and breeder segments attract premium phytogenic formulations tied to egg quality and hatchability metrics.
The European Food Safety Authority (EFSA) evaluates phytogenic safety and efficacy claims under feed additive authorization procedures, while the FDA maintains enforcement discretion for certain botanical preparations in US poultry rations pending formal additive status determinations. Brazil's Ministry of Agriculture (MAPA) and ANVISA coordinate on import and domestic manufacturing standards for phytogenic inputs serving the country's export-driven poultry complex. Stakeholders must monitor evolving regulatory divergence between jurisdictions that accept generic botanical claims versus those demanding clinical trial dossiers comparable to synthetic additives.
Market Dynamics
The EU's pharmacological zinc oxide ban has redirected formulation investment toward botanical alternatives, compressing the window for synthetic additive incumbents to defend their positions in European poultry operations.
Growth Catalysts
- Antibiotic Reduction Mandates:EFSA's tightened authorization procedures for synthetic growth promoters accelerate phytogenic substitution in broiler and layer feeds across member states.
- Export Certification Requirements:Brazil's integrated processors demand phytogenic documentation for EU and Asian market access, pulling inclusion rates upward in São Paulo and Paraná production clusters.
- Essential Oil Standardization:Improved chromatographic fingerprinting protocols enable reproducible terpenoid profiles, reducing batch-to-batch variability that previously limited commercial scale-up.
Market Restraints
- Botanical Raw Material Volatility:Climate-driven supply fluctuations for oregano, thyme, and cinnamon bark concentrate price risk in Mediterranean and Southeast Asian sourcing corridors.
- Clinical Validation Burden:EFSA's requirement for multi-site trial dossiers comparable to synthetic additives imposes timeline and capital barriers for novel phytogenic entrants.
- Synthetic Acidifier Competition:Buffered organic acids maintain cost advantages in margin-sensitive broiler operations, limiting phytogenic penetration in price-driven procurement segments.
Strategic Opportunities
- Layer Segment Premiumization:Egg quality and extended laying cycle metrics create pull for specialized phytogenic formulations targeting omega-3 enrichment and shell strength.
- Precision Delivery Systems:Microencapsulation technology convergence with site-specific release profiles enables intestinal-targeted bioactive delivery, differentiating premium product tiers.
- ANVISA Harmonization Pathway:Brazil's coordinated MAPA-ANVISA standards development for export-oriented phytogenic certification creates first-mover advantages for dossier-ready suppliers.
Industry Challenges
- Phytochemical Analytical Talent Scarcity:The specialized skill set combining botany, analytical chemistry, and poultry nutrition remains concentrated among a limited pool of formulation scientists.
- Multi-Jurisdiction Registration Complexity:Divergent evidentiary standards between EFSA's clinical trial requirements and FDA enforcement discretion create compliance fragmentation for multinational suppliers.
- Legacy Feed Mill Integration:Retrofitting existing premix infrastructure for heat-sensitive essential oil handling requires capital outlay that mid-scale operations defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytogenic Poultry Feed Additives Market |
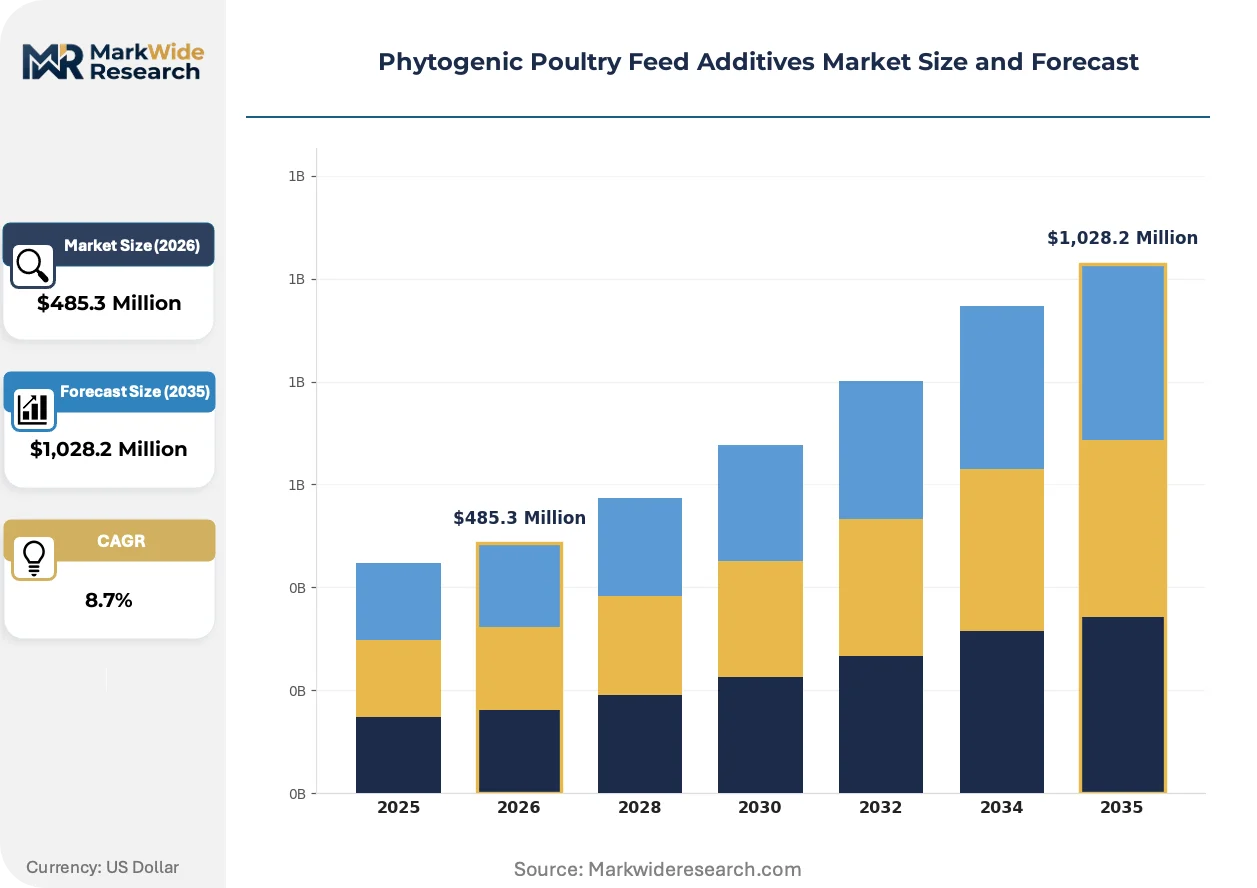
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbal Extracts, Spices, Oleoresins Application: Poultry, Broilers, Layers, Breeders Formulation: Premixes, Straight Feed, Complementary Feed, Liquid Form Distribution Channel: Online Stores, Agricultural Cooperatives, Retail Outlets, Direct Sales |
| Companies Covered | Cargill, Incorporated, DSM-Firmenich, Kemin Industries, Inc., ADM, Nutreco, Phytobiotics Futterzusatzstoffe GmbH, Alltech, Inc., Delacon Biotechnik GmbH, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytogenic Poultry Feed Additives Market Trends and Innovations
Formulation science is advancing beyond simple essential oil blends toward synergistic compound design, while regulatory pressure and procurement sophistication compress the viable competitive set.
Microencapsulation technology is converging with precision release engineering to protect heat-labile terpenoids through pelleting temperatures exceeding 85°C. Leading premix manufacturers in Germany and the Netherlands adopt these systems to maintain bioactive integrity through conventional feed processing. The structural consequence is a bifurcation between premium encapsulated products and commodity-grade straight feeds.
EFSA's 2024 updated guidance on botanical feed additive characterization demands expanded toxicological and residue datasets for authorization renewals. This industrial consequence extends development timelines by 18-24 months for novel submissions. Layer and breeder segments absorb the compliance costs most readily due to longer production cycles and higher margin structures.
Integrated poultry processors in Thailand and Vietnam now specify phytogenic inclusion certificates in supplier qualification protocols, displacing spot-market commodity purchasing. Distributor networks face disintermediation pressure as direct technical partnerships between additive developers and large integrators consolidate procurement channels. This pattern concentrates most visibly in Southeast Asian export-oriented complexes supplying Japanese and South Korean buyers.
Phytogenic Poultry Feed Additives Market Segmentation
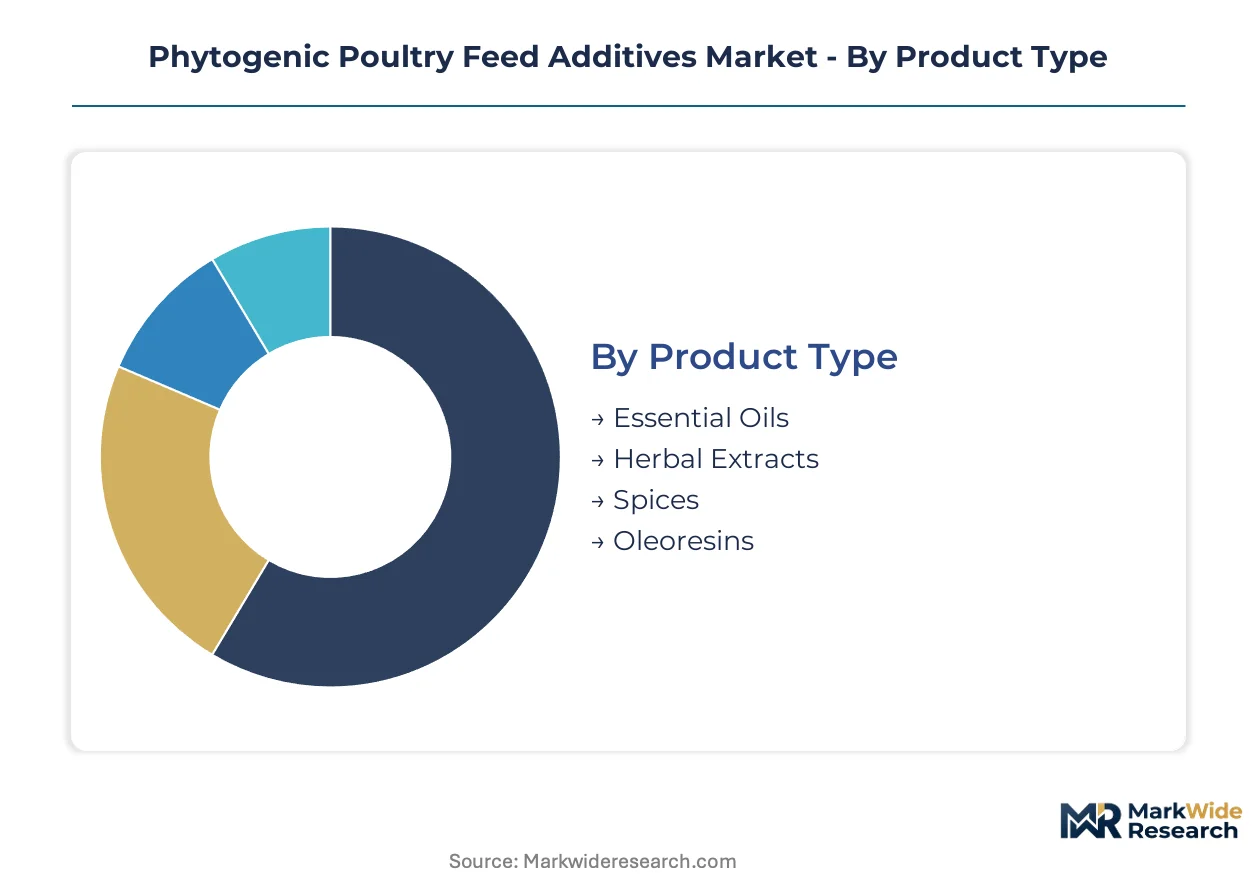
Phytogenic poultry feed additives fragment across four dimensions that determine procurement economics and formulation strategy. Product type governs bioactive standardization costs. Application dictates performance metrics and margin tolerance. Formulation and distribution channel choices reflect feed mill infrastructure and integrator scale.
Product Type:
Volume concentration sits with established extraction categories, while premium pricing attaches to advanced botanical processing.
- Essential Oils:Terpenoid-rich volatile compounds derived through steam distillation or cold pressing, with standardized thymol, carvacrol, and cinnamaldehyde concentrations. Broiler operations in Brazil's São Paulo cluster specify these for feed conversion efficiency documentation required by EU export auditors. Synthetic acidifier cost pressure limits penetration in margin-sensitive procurement segments.
- Herbal Extracts:Non-volatile bioactive fractions—polyphenols, flavonoids, alkaloids—recovered via solvent or supercritical CO2 extraction. Layer operations across Vietnam and Thailand absorb premium pricing to support extended laying cycle and shell strength claims for Japanese retail contracts. EFSA's multi-site trial requirements compress the viable supplier set for novel entrants.
- Spices:Ground or processed botanical materials retaining native fiber matrices alongside bioactive compounds.
- Oleoresins:Concentrated resin-soluble fractions combining essential oils with resinous plant constituents.
Mature deployment sits with essential oils. Newer deployment is concentrated in herbal extracts.
Application:
Scale economics favor high-turnover categories, while specialized breeding cycles sustain premium formulation tiers.
- Poultry:Broad-category designation encompassing all avian production systems without species or purpose specification.
- Broilers:Meat-focused operations with compressed production cycles demanding rapid gut health modulation and pathogen resistance. Integrated processors across Paraná state mandate phytogenic inclusion certificates for EU and South Korean market access, pulling formulation standardization upward. Heat-labile terpenoid protection through microencapsulation differentiates supplier tiers.
- Layers:Egg production systems where extended laying cycles and quality metrics justify premium bioactive investments. Omega-3 enrichment and shell strength specifications from Japanese buyers concentrate demand for specialized phytogenic formulations in Thai and Vietnamese export complexes. Longer production cycles absorb compliance cost burdens more readily than broiler operations.
- Breeders:Parent stock operations where hatchability and chick quality metrics drive inclusion decisions.
Volume concentration centers on broilers. Premium positioning concentrates in layers.
Formulation:
Processing compatibility and bioactive stability determine adoption patterns across feed mill infrastructure tiers.
- Premixes:Concentrated carrier-based blends enabling uniform micro-dosing in finished feeds. German and Dutch manufacturers adopt microencapsulation systems to protect terpenoid integrity through pelleting temperatures exceeding 85°C, creating bifurcation against commodity-grade alternatives.
- Straight Feed:Single-ingredient phytogenic products requiring on-farm or mill-level blending.
- Complementary Feed:Nutritional supplements administered alongside base rations to address specific physiological phases.
- Liquid Form:Aqueous or oil-based suspensions for drinking water or spray application systems.
Established infrastructure favors premixes. Technology migration is accelerating toward liquid form.
Distribution Channel:
Procurement consolidation among large integrators is restructuring channel economics and intermediary survival.
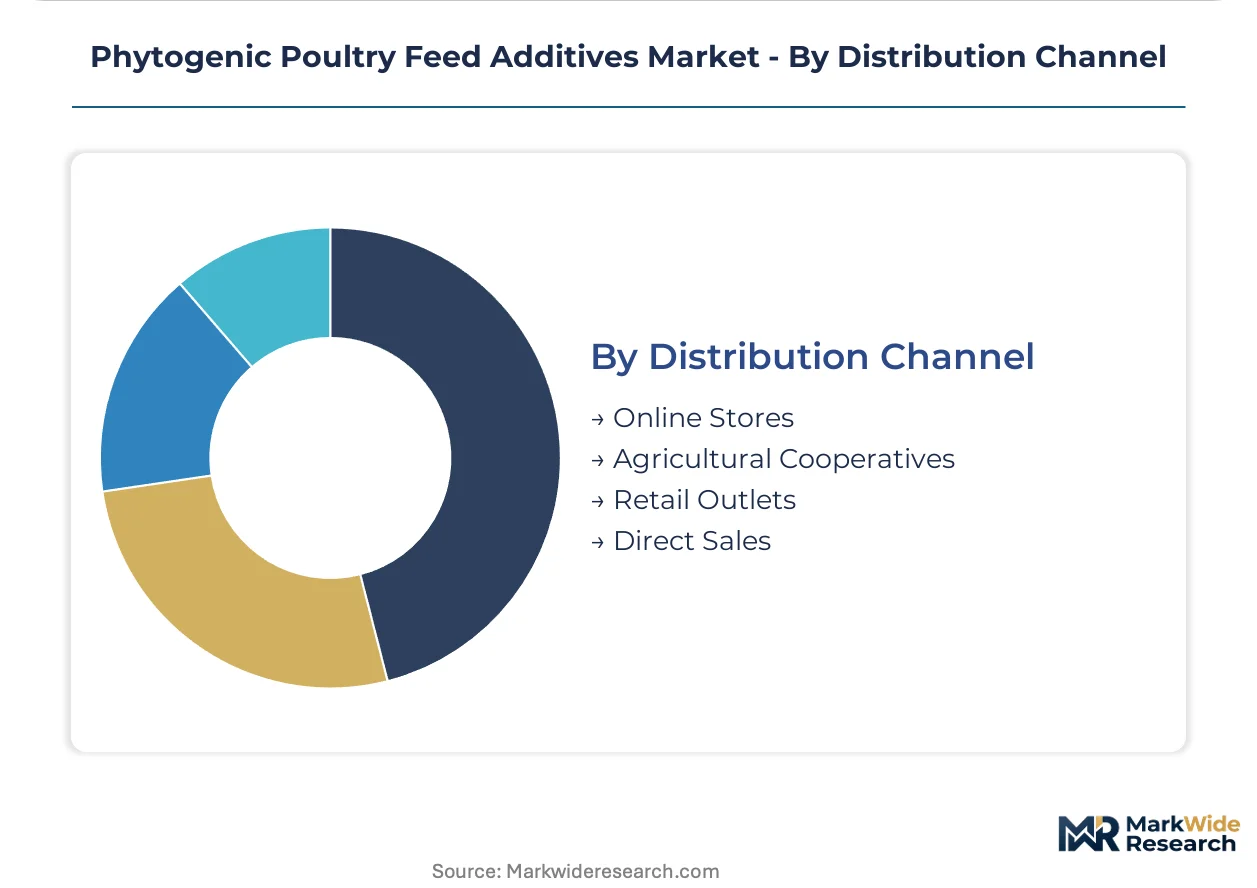
- Online Stores:Digital procurement platforms serving mid-scale independent operations with transparent pricing and technical documentation access.
- Agricultural Cooperatives:Member-owned purchasing bodies aggregating demand across regional producer associations.
- Retail Outlets:Physical distribution points serving smallholder and backyard operations with immediate availability requirements.
- Direct Sales:Technical partnerships between additive developers and large integrated processors, displacing distributor networks in Southeast Asian export-oriented complexes supplying Japanese and South Korean buyers.
Channel consolidation favors direct sales. Cooperative structures retain strength in fragmented production regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phytogenic poultry feed additive demand concentrates in Brazil, Germany, Thailand, Vietnam, and the United States, where export-oriented processors and regulatory pressure reshape procurement patterns. Each geography presents distinct formulation requirements and certification protocols.
Brazil
Integrated processors across São Paulo and Paraná states mandate phytogenic inclusion certificates for EU and South Korean market access. ANVISA coordinates with MAPA on import and domestic manufacturing standards for export-driven poultry complexes. São Paulo's production clusters absorb premium formulation costs to satisfy Japanese retail contract specifications.
Germany
Premix manufacturers adopt microencapsulation systems to protect terpenoid integrity through pelleting temperatures exceeding 85°C. EFSA's tightened authorization procedures for synthetic growth promoters accelerate phytogenic substitution across member states. Dutch and German feed mills create bifurcation between premium encapsulated products and commodity-grade alternatives.
Thailand
Commercial layer operations expand phytogenic inclusion rates to reduce antibiotic dependency ahead of Japanese buyer requirements. EFSA's multi-site trial dossier demands compress the viable supplier set for novel entrants. Bangkok and Chiang Mai production complexes specify phytogenic documentation in supplier qualification protocols.
Vietnam
Layer operations absorb premium pricing to support extended laying cycle claims for Japanese retail contracts. Export-oriented processors displace spot-market commodity purchasing through direct technical partnerships with additive developers. Mekong Delta and Red River Delta clusters concentrate demand for specialized omega-3 enrichment formulations.
United States
Broiler operations face synthetic acidifier competition in margin-sensitive procurement segments. FDA maintains enforcement discretion for certain botanical preparations pending formal additive status determinations. Southeast and Midwest production regions retrofit premix infrastructure for heat-sensitive essential oil handling.
Phytogenic Poultry Feed Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated nutrition platforms commanding formulation standardization while regional botanical processors retain cost advantages in commodity tiers. The supplier set concentrates among agricultural conglomerates with captive sourcing networks and dedicated phytogenic specialists with species-specific expertise. Three archetypes dominate: backward-integrated agricultural traders, biotechnology-focused formulation houses, and extraction-technology specialists. Competitive moves center on microencapsulation capacity expansion and multi-jurisdiction registration dossier accumulation.
Within the biotechnology-focused tier, DSM-Firmenich and Delacon Biotechnik GmbH exemplify divergent approaches to species-specific formulation science. Cargill, Incorporated anchors the backward-integrated archetype through upstream control over botanical sourcing networks. These three entities occupy distinct competitive positions based on regulatory dossier depth and extraction technology access.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DSM-Firmenich |
| Kemin Industries, Inc. |
| ADM |
| Nutreco |
| Phytobiotics Futterzusatzstoffe GmbH |
| Alltech, Inc. |
| Delacon Biotechnik GmbH |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Backward integration into Mediterranean and Southeast Asian botanical sourcing networks anchors both supply security and pricing power for leading premix manufacturers, compressing margins for traders without captive cultivation contracts or extraction facilities.
Pricing Analysis
Volume concentration in commodity-grade essential oils competes with margin capture in microencapsulated premium tiers. Pricing stratifies across EFSA-certified, MAPA-documented, and generic botanical grades, with certification tier and volume scale as primary differentiation drivers. Cost compression in standard essential oil segments intensifies as Brazilian integrators consolidate procurement through direct technical partnerships. Margin-sensitive broiler operations in Southeast Asia exhibit highest price sensitivity, while layer operations serving Japanese retail contracts absorb premium formulations with least resistance.
Supply Chain Analysis
Single-source vulnerability sits with oregano and thyme cultivation concentrated in Turkey, Greece, and Morocco, where climate-driven yield fluctuations concentrate price risk. Feed-grade terpenoid extraction draws from cinnamon bark in Sri Lanka and Indonesia, plus cardamom and clove in India and Madagascar. Tariff exposure on EU-originated extraction equipment feeds into formulation cost structures. Distribution runs through direct sales channels displacing agricultural cooperatives in Brazil and Southeast Asian export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EFSA's multi-site trial dossier requirements is forcing smaller botanical processors without registration infrastructure toward exit or acquisition, concentrating viable supplier ranks among dossier-capable entities.
For Market Incumbents: Extend microencapsulation capacity in Germany and the Netherlands to defend premium positioning against heat-stable synthetic acidifier substitution. Accumulate multi-jurisdiction registration dossiers ahead of ANVISA-MAPA harmonization to preempt competitor access to Brazilian export certification pathways. Channel control through direct technical partnerships with Thai and Vietnamese integrators limits distributor disintermediation risk.
For New Entrants and Emerging Players: Chromatographic fingerprinting standardization offers a technology-first wedge against batch-to-batch variability concerns that limit commercial scale-up. Target layer segment premiumization in Vietnam and Thailand, where extended laying cycle claims justify premium absorption absent in broiler operations. Pursue white-label extraction partnerships with established European premix manufacturers lacking captive botanical sourcing.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by backward-integrated agricultural conglomerates seeking species-specific formulation capabilities. Long-term viability hinges on regulatory dossier depth rather than extraction technology alone, favoring targets with EFSA submission experience. Monitor ANVISA-MAPA coordinated standards development as inflection signal for Brazilian market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capacity Expansion | Protects terpenoid integrity through pelleting temperatures exceeding 85°C, differentiating German and Dutch premix tiers. |
| Multi-Jurisdiction Dossier Accumulation | Builds defensible moats against EFSA's tightened authorization procedures and ANVISA harmonization pathways. |
| Captive Botanical Sourcing Networks | Secures supply continuity for oregano, thyme, and cinnamon bark amid climate-driven Mediterranean volatility. |
| Direct Technical Partnerships | Displaces distributor networks in Southeast Asian export corridors supplying Japanese and South Korean buyers. |
| Species-Specific Formulation Development | Targets gut microbiome modulation in broilers and omega-3 enrichment in layers with distinct bioactive profiles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across feed additive formulation scientists, integrator procurement directors, and EFSA regulatory affairs specialists. Bottom-up triangulation against top-down macroeconomic indicators validated volume estimates. Secondary sources included ANVISA submission databases, MAPA manufacturing standards, EU Feed Additives Register entries, and Brazilian poultry export certification records.
Granularity-level modeling proceeded at product type, application, and formulation dimensions, with additional segmentation by regulatory certification tier and export market destination. CAGRs derived from logistic growth curve fitting to historical trajectory and policy-inflection adjustments. Industry-specific forecast inputs incorporated EFSA authorization timeline assumptions and ANVISA-MAPA coordination progress indicators across the projection horizon.
Several conditions sit outside the modeled scope, including abrupt climate events affecting Mediterranean botanical yields, unilateral regulatory reversals on zinc oxide substitutes, and trade barrier impositions on EU-Asian poultry product flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
North America Molluscicides Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Tembotrione Market
Crop Protection
South America Acaricides Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Pest Control Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Organic Pesticides Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Grain Fumigants Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Pest Control Products Market
Crop Protection
United States Nematicides Market
Crop Protection
South America Nematicides Market