
 Middle East and Africa Turf and Ornamental Grass Protection Market | 2026-2036
Middle East and Africa Turf and Ornamental Grass Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Turf and Ornamental Grass Protection Market Insights
Project finance for large-scale landscaping developments is narrowing the competitive field to capitalized suppliers. Bayer AG leverages its biologicals portfolio to sustain premium positioning across Gulf golf developments. Syngenta anchors its regional footprint through specialized fungicide formulations for Paspalum and Bermuda grass varieties. UPL competes on price-accessible herbicide bundles tailored to municipal sports field contracts.
Turf and ornamental grass protection encompasses chemical and biological inputs formulated to control weeds, insects, and fungal pathogens while delivering plant nutrition, typically applied through foliar spray or soil drench systems with specified active ingredient concentrations. These products preserve aesthetic uniformity, playability, and plant health across managed grass surfaces in arid and semi-arid climates. Herbicides command the largest volume share across Middle East and Africa applications, though fungicide demand accelerates fastest where humidity spikes stress warm-season cultivars. Landscaping applications generate steady recurring revenue, while golf courses concentrate margin pools through technical service bundling.
Saudi Arabia's SFDA and South Africa's Registrar of Act 36 of 1947 govern pesticide registration, with import permit requirements shaping product availability timelines across the region. The EU Green Deal's F-Gas Regulation indirectly influences formulation standards for Gulf suppliers exporting to European-linked developments. Stakeholders must monitor evolving biopesticide registration pathways as water-use restrictions intensify input selection criteria.
Market Dynamics
Water-scarcity mandates across Gulf Cooperation Council states are forcing reformulation of turf protection chemistries toward lower-volume, higher-efficacy concentrates that integrate with precision irrigation systems.
Growth Catalysts
- Saudi giga-project pipeline:NEOM, Red Sea Global, and Qiddiya developments specify warm-season turf establishment across millions of square meters, generating sustained input demand for nematicides and plant growth regulators.
- Drip-irrigation convergence:Subsurface delivery systems in UAE and Qatar golf developments favor water-soluble fungicide formulations over granular alternatives, rewarding suppliers with compatible product architectures.
- SFDA biopesticide pathways:Saudi Arabia's streamlined registration for microbial and botanical actives accelerates market entry for biological turf protection, particularly Bacillus-based solutions for root-feeding insect control.
Market Restraints
- Active ingredient import dependency:Most formulated products rely on Chinese-manufactured technicals, exposing margins to shipping cost volatility and customs clearance delays at Jebel Ali and Durban ports.
- EU F-Gas Regulation spillover:Formulation standards for Gulf suppliers serving European-linked developments must exclude specified fluorinated greenhouse gases, constraining solvent choices and extending R&D timelines.
- Soil salinity incompatibility:High sodium content in desalinated irrigation water across coastal UAE and Qatar reduces efficacy of certain sulfonylurea herbicides, limiting product rotation options.
Strategic Opportunities
- South African municipal sports field underpenetration:Township and school district maintenance programs remain chemically underserved relative to private golf estates, presenting volume-accessible entry points for bundled herbicide-fungicide offerings.
- Drone application services:Aerial spraying contractors in Kenya and Morocco are expanding precision coverage for large-scale ornamental landscaping, creating channel partnerships that bypass traditional distributor markups.
- UAE MOHAP green building incentives:Dubai's Al Safat and Abu Dhabi's Pearl rating systems award credits for reduced-chemical maintenance protocols, pulling biological turf protection into commercial landscaping specifications.
Industry Challenges
- Turf pathology diagnostic scarcity:Qualified plant pathologists capable of distinguishing Pythium root rot from nematode damage are concentrated in Johannesburg and Dubai, leaving remote course superintendents dependent on photographic remote consultation with delayed turnaround.
- Registration timeline compression:South Africa's Registrar of Act 36 of 1947 requires multi-season efficacy trials under local climatic conditions, stretching product launch schedules to 24-36 months despite urgent contractor demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Turf and Ornamental Grass Protection Market |
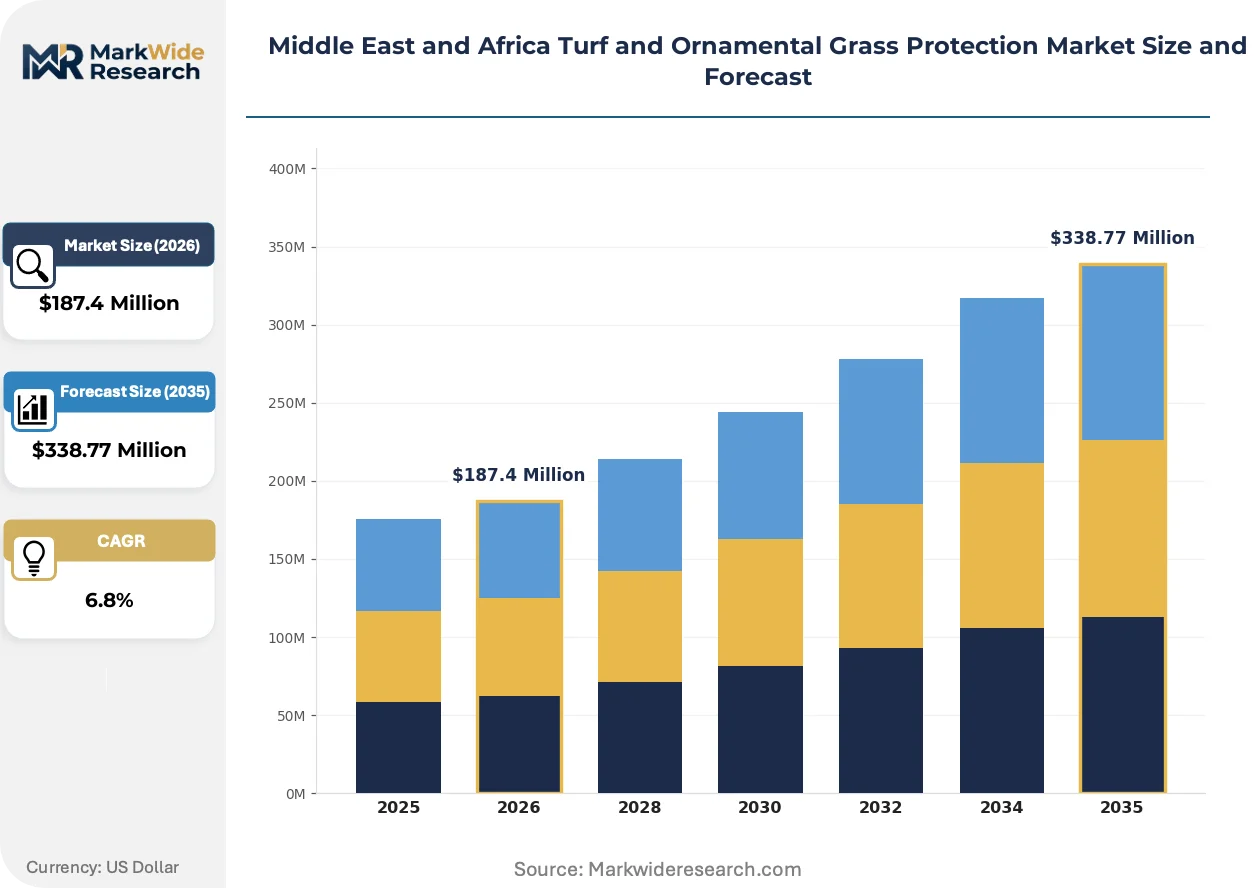
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Fertilizers Application: Landscaping, Sports Fields, Golf Courses, Residential Gardens Distribution Channel: Online Retail, Direct Sales, Garden Centers, Wholesale User Type: Commercial Farmers, Landscape Contractors, Homeowners, Golf Course Managers |
| Companies Covered | Bayer AG, Syngenta, BASF SE, UPL, Nufarm, FMC Corporation, Corteva Agriscience, Adama Ltd, Dow Agrisciences, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Turf and Ornamental Grass Protection Market Trends and Innovations
Biological input integration and precision application hardware are compressing the traditional divide between agronomic efficacy and environmental compliance across managed turf systems in water-stressed climates.
Microbial inoculant formulations containing Trichoderma harzianum and Bacillus subtilis strains are colonizing root zones of Paspalum and Bermuda grass cultivars to outcompete fungal pathogens. Golf course operators in Abu Dhabi and Doha are adopting these biocontrols as foundation treatments before chemical rotation. The technology is rendering obsolete the calendar-based preventive fungicide programs that dominated warm-season turf management for two decades.
South Africa's Registrar of Act 36 of 1947 implemented revised data requirements for honeybee toxicity assessments in 2023, affecting all new turf insecticide registrations. This regulatory tightening extends field trial obligations and increases dossier preparation costs for entrants. Landscape maintenance contractors in the Western Cape wine region, where pollinator pressure is highest, are accelerating adoption of non-neonicotinoid alternatives ahead of formal mandates.
Superintendents and facilities managers are consolidating supplier relationships around technical service bundling rather than discrete product procurement. Premium golf developments in Saudi Arabia now specify multi-year agronomic support contracts incorporating soil testing, irrigation calibration, and pest monitoring. This behavior concentrates purchasing authority with capitalized suppliers capable of fielding dedicated turf agronomists, compressing margins for transaction-only distributors.
Middle East and Africa Turf and Ornamental Grass Protection Market Segmentation
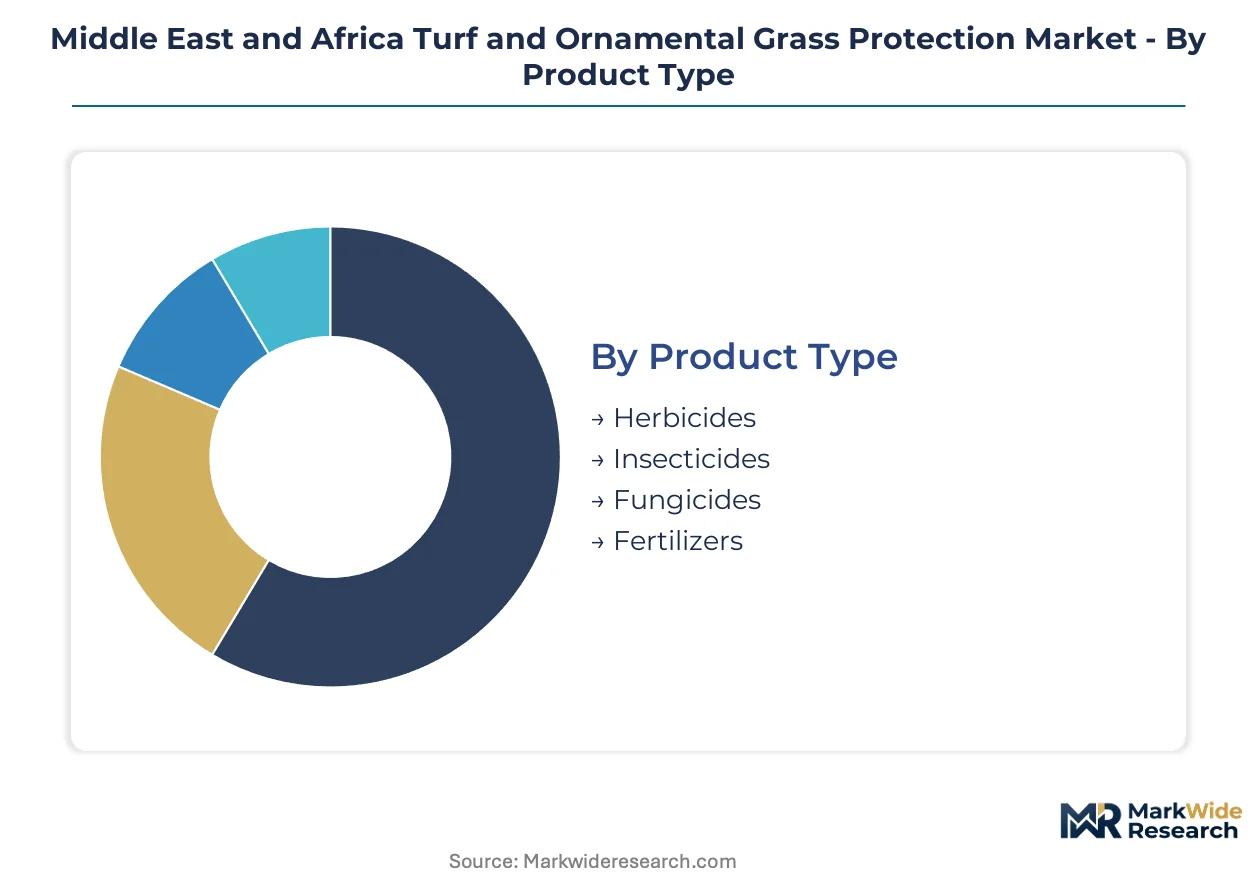
Segmentation reveals how water-scarcity mandates and project-scale economics reshape input procurement across the Middle East and Africa. Product formulation requirements diverge sharply between drip-irrigation golf developments and municipal sports field budgets.
Product Type:
Cost tier determines formulation concentration and active ingredient sourcing, with premium concentrates commanding technical service bundling.
- Herbicides:Sulfonylurea and glyphosate formulations dominate volume, though soil salinity in coastal UAE and Qatar reduces efficacy of certain chemistries. Golf course operators in Saudi Arabia's giga-projects specify selective grass-safe variants for warm-season turf establishment.
- Fungicides:Demand accelerates where humidity spikes stress Paspalum and Bermuda grass cultivars. Water-soluble formulations compatible with subsurface drip systems concentrate procurement in Abu Dhabi and Doha premium developments.
- Insecticides:Root-feeding nematode control drives adoption of non-neonicotinoid alternatives in Western Cape pollinator-sensitive zones.
- Fertilizers:Controlled-release nitrogen formulations integrate with precision irrigation scheduling across Gulf Cooperation Council landscaping contracts.
Herbicides hold installed capacity. Fungicides is rotating up the share rankings.
Application:
Application context dictates technical service intensity and margin structure, with playability standards separating premium from commodity procurement.
- Golf Courses:Technical service bundling concentrates purchasing authority with capitalized suppliers fielding dedicated turf agronomists. NEOM, Red Sea Global, and Qiddiya developments specify multi-year agronomic support contracts incorporating soil testing and pest monitoring.
- Landscaping:Commercial maintenance programs in Dubai's Al Safat and Abu Dhabi's Pearl rating systems award credits for reduced-chemical protocols, pulling biological protection into specifications.
- Sports Fields:Township and school district maintenance programs across South Africa remain chemically underserved relative to private estates.
- Residential Gardens:Price-accessible herbicide bundles through garden centers serve homeowner demand in suburban Johannesburg and Cape Town.
Golf courses capture margin concentration. Landscaping is climbing the fastest as green building incentives expand.
Distribution Channel:
Channel structure determines markup layering and technical consultation access, with direct relationships compressing distributor margins.
- Direct Sales:Multi-year agronomic support contracts with Saudi giga-project developers bypass traditional distributor networks entirely.
- Wholesale:Municipal sports field contracts across South Africa move through agricultural supply cooperatives with seasonal volume terms.
- Garden Centers:Retail-facing outlets in suburban Dubai and Riyadh serve residential maintenance demand with bundled homeowner kits.
- Online Retail:E-commerce penetration remains limited by product registration documentation requirements and import permit verification.
Direct sales holds installed capacity. Wholesale is rotating up the share rankings.
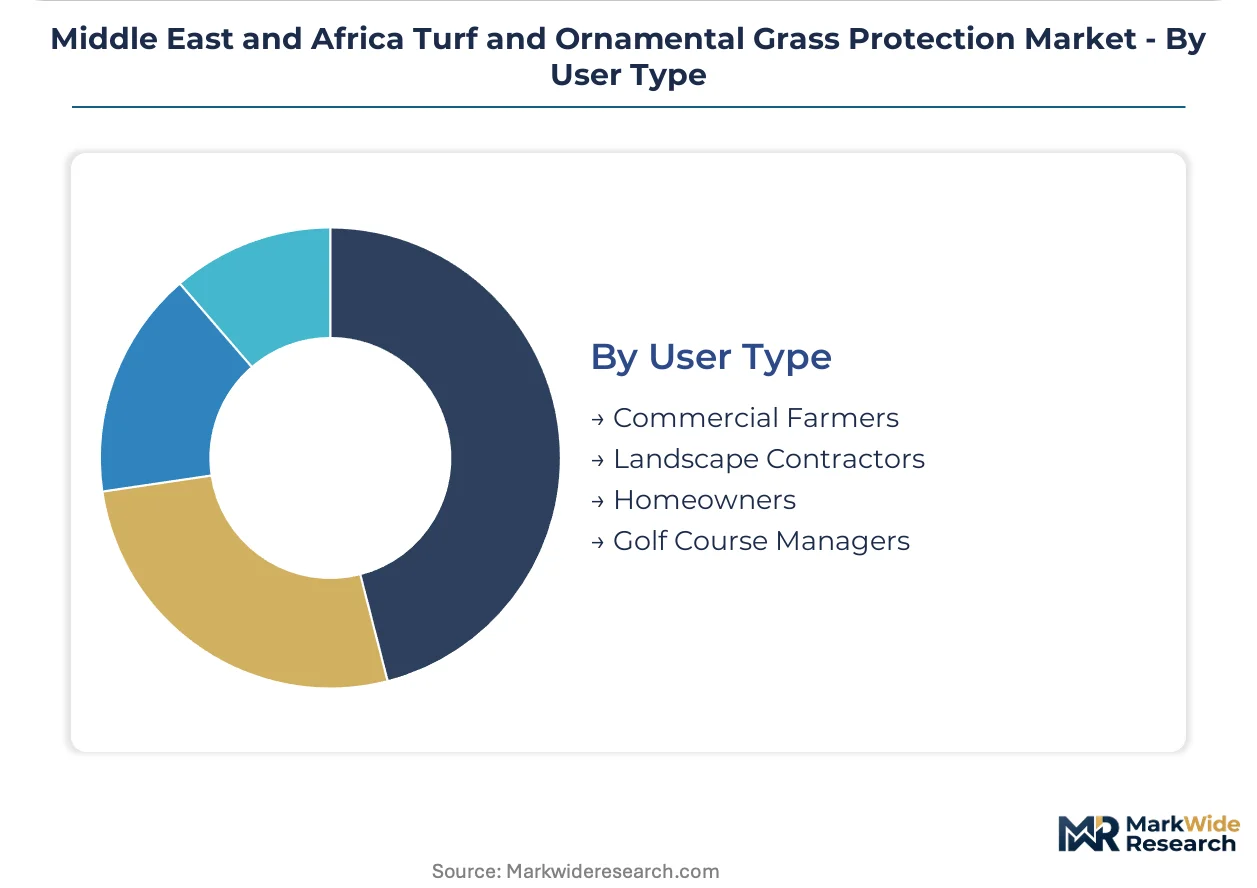
User Type:
Customer sophistication separates specification-driven procurement from price-driven purchasing, with technical diagnostic capability concentrating authority.
- Golf Course Managers:Qualified superintendents in Johannesburg and Dubai command purchasing authority through soil testing and irrigation calibration expertise. Remote course operators depend on photographic remote consultation with delayed turnaround.
- Landscape Contractors:Commercial maintenance firms in Kenya and Morocco are expanding drone application partnerships that bypass traditional distributor markups.
- Commercial Farmers:Agricultural turf protection for fodder grass operations moves through cooperative purchasing with seasonal credit terms.
- Homeowners:Price-sensitive demand concentrates in garden center channels with limited technical consultation.
Golf course managers hold installed capacity. Landscape contractors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium golf developments in Saudi Arabia and the UAE command input prices 40-60% above South African municipal contracts, creating a bifurcated procurement landscape across the region. This pricing-power asymmetry concentrates technical service investment in Gulf Cooperation Council states while compressing margins in price-sensitive African markets.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya developments specify warm-season turf establishment across millions of square meters, generating sustained demand for nematicides and plant growth regulators. The SFDA streamlined registration pathways for microbial and botanical actives in 2023, accelerating market entry for Bacillus-based biological solutions. Riyadh-based agronomic service firms now field dedicated turf specialists for giga-project contracts.
United Arab Emirates
Abu Dhabi and Doha premium golf developments favor water-soluble fungicide formulations compatible with subsurface drip irrigation systems. MOHAP green building incentives through Dubai's Al Safat and Abu Dhabi's Pearl rating systems award credits for reduced-chemical maintenance protocols. Dubai South and Yas Island clusters concentrate landscaping procurement for commercial and hospitality developments.
South Africa
Township and school district maintenance programs remain chemically underserved relative to private golf estates in the Western Cape and Gauteng provinces. The Registrar of Act 36 of 1947 requires multi-season efficacy trials under local climatic conditions, stretching product launch schedules to 24-36 months. Johannesburg anchors qualified plant pathology diagnostic capacity, leaving remote course operators dependent on delayed remote consultation.
Qatar
Coastal desalinated irrigation water with high sodium content reduces efficacy of certain sulfonylurea herbicides, limiting product rotation options for turf managers. Lusail City and Education City developments specify technical service bundling in procurement contracts. Doha-based superintendents increasingly consolidate supplier relationships around multi-year agronomic support agreements.
Morocco
Aerial spraying contractors are expanding precision coverage for large-scale ornamental landscaping, creating channel partnerships that bypass traditional distributor markups. Royal Golf Dar Es Salam and other Casablanca-Rabat corridor developments import formulated products through Tangier Med port facilities. The country's national agricultural regulator maintains import permit requirements that shape product availability timelines.
Middle East and Africa Turf and Ornamental Grass Protection Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying technical actives and formulation intermediates. The supplier base concentrates around capitalized agronomic service providers capable of fielding dedicated turf specialists, compressing margins for transaction-only distributors. Three archetypes dominate: multinational crop science platforms with biologicals portfolios, regional formulators competing on price-accessible bundles, and emerging drone-application service contractors. Competitive dynamics center on multi-year technical service contracting and backward integration into microbial active ingredient production.
Within the multinational platform tier, Bayer AG and Syngenta occupy positions anchored by premium positioning across Gulf golf developments and specialized fungicide formulations for warm-season cultivars respectively. UPL represents the price-accessible regional formulator archetype, competing through bundled herbicide offerings tailored to municipal sports field contracts. These three companies exemplify the strategic segmentation between premium technical service bundling and volume-driven commodity procurement that defines competitive positioning across the region.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta |
| BASF SE |
| UPL |
| Nufarm |
| FMC Corporation |
| Corteva Agriscience |
| Adama Ltd |
| Dow Agrisciences |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese technical-grade active ingredient manufacturing compresses formulation margins for Gulf-based turf protection suppliers while simultaneously enabling aggressive pricing postures in South African municipal tenders. This utilization imbalance rewards backward-integrated multinationals with captive active production while squeezing pure-play formulators dependent on spot-market technical procurement.
Pricing Analysis
Customization-premium spreads of 40-60% separate Gulf golf course technical service bundles from South African township sports field commodity herbicide tenders. Pricing stratifies across premium, standard, and economy tiers with differentiation anchored in agronomic support intensity and active ingredient provenance. Cost compression in the municipal segment intensifies as Chinese technical-grade glyphosate floods Jebel Ali re-export channels. Golf course managers in Riyadh and Dubai exhibit lowest price sensitivity due to playability-driven procurement mandates.
Supply Chain Analysis
Upstream feedstock dependence on Chinese-manufactured sulfonylurea technicals, Indian-sourced glyphosate intermediates, and German-engineered formulation solvents anchors regional supply vulnerability. Formulated products draw from technical-grade inputs concentrated in Shandong province, Mumbai chemical belt, and Ludwigshafen specialty chemical complexes. Single-source vulnerability concentrates around desiccant container shipping routes through the Suez Canal. Distribution runs through Jebel Ali free zone consolidation points for Gulf markets and Durban port clearing for Southern African inland penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turf protection is evolving into a service-attach business where multi-year agronomic support contracts expand faster than discrete chemical offtake. Recurring revenue from soil testing, irrigation calibration, and pest monitoring protocols now exceeds product margin pools in premium Gulf developments.
For Market Incumbents: Insulate premium positioning by deepening backward integration into Bacillus-based biological active production and securing exclusive distribution rights for drip-irrigation-compatible fungicide formulations. Threat substitution from drone-application service contractors in Kenya and Morocco demands channel control investments. Capacity addition in Jebel Ali formulation facilities represents the priority defensive lever. For New Entrants and Emerging Players: South African township and school district sports field maintenance programs represent the most penetrable entry point for bundled herbicide-fungicide offerings with seasonal credit terms. Drone-application partnerships with Moroccan and Kenyan aerial spraying contractors offer a direct go-to-market angle that bypasses traditional distributor markups and captures margin otherwise lost to wholesale layering. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among capitalized suppliers fielding dedicated turf agronomists for multi-year giga-project contracts. Long-term viability across the analysis window favors acquisition targets with microbial active ingredient production capabilities and established SFDA registration dossiers. The signal to watch is SFDA biopesticide pathway expansion accelerating registration timelines for botanical entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Actives | Bayer AG's biologicals portfolio demonstrates premium positioning sustainability through captive Bacillus production. |
| Drip-Irrigation Formulation Compatibility | Syngenta's water-soluble fungicide architectures capture procurement preference in Abu Dhabi and Doha premium developments. |
| Drone-Application Channel Partnerships | Kenyan and Moroccan aerial spraying contractors compress distributor margins while expanding precision coverage reach. |
| SFDA Biopesticide Registration Investment | Streamlined microbial pathways accelerate market entry for root-feeding nematode control solutions in Saudi giga-projects. |
| Municipal Sports Field Bundling | UPL's price-accessible herbicide offerings penetrate South African township maintenance programs with volume-accessible terms. |
Research Methodology
Initial hypotheses were tested against primary input from golf course superintendents, landscape maintenance contractors, agrochemical distribution managers, and SFDA regulatory affairs specialists and refined through secondary validation. Bottom-up demand modeling triangulated with top-down trade flow analysis from customs records, agricultural input distributor databases, and golf industry association membership directories across Saudi Arabia, UAE, South Africa, Qatar, and Morocco.
Demand-supply-balance framing anchored the analytical framework across the projection horizon with segmentation dimensions spanning product type, application context, distribution channel, and user sophistication tier. CAGRs were derived from installed base expansion rates, replacement cycle analysis, and project pipeline tracking for NEOM, Red Sea Global, and Qiddiya developments. Water-scarcity mandate intensity and drip-irrigation penetration curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Gulf construction project financing availability, Chinese technical-grade export pricing, and South African rand exchange rate volatility would shift the trajectory. Cross-checking against golf course development permit databases and agricultural input import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
South America Insecticide Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Termite Control Market
Crop Protection
Fosthiazate Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
India Insecticide Market
Crop Protection
Organic Pesticides Market
Crop Protection
Miticides Market
Crop Protection
Global Aquatic Herbicides Market