
 Monitoring Wristband Market | 2026-2036
Monitoring Wristband Market Size, Share, and Industry Trends Forecast 2026-2036
Monitoring Wristband Market Insights
Subscription-based health analytics is realigning how monitoring wristbands generate recurring revenue beyond hardware sales. Apple leverages its ecosystem integration to sustain premium positioning across consumer and clinical adjacent segments. Xiaomi anchors volume distribution through direct-to-consumer channels in Asia, while Garmin differentiates through specialized athletic performance metrics that command higher attachment rates for advanced coaching services.
A monitoring wristband is a wearable electronic device incorporating photoplethysmography sensors, accelerometers, and low-energy wireless chipsets to capture physiological and kinematic data for health surveillance or performance optimization. Medical monitors represent the highest-margin product category as clinical-grade accuracy requirements create certification barriers that limit competitor entry. Corporate wellness programs constitute the fastest-growing end user segment as self-insured employers deploy wristbands to reduce claims exposure through preventive intervention programs.
FDA software-as-a-medical-device guidance shapes product development timelines for US-bound clinical wristbands, while EU MDR compliance extends certification cycles for European market access. China's NMPA digital health device pathway accelerates domestic approval but imposes data localization requirements that foreign manufacturers must address through local cloud infrastructure partnerships. Stakeholders should monitor evolving reimbursement codes for remote physiological monitoring as payer decisions will determine whether clinical wristbands shift from consumer wellness tools to billable care delivery instruments.
Market Dynamics
Remote patient monitoring reimbursement codes are restructuring demand economics, converting consumer wellness purchases into clinical procurement decisions across United States hospital systems and China's tier-one city hospitals.
Growth Catalysts
- EU MDR compliance:Clinical-grade certification requirements create defensible margin positions for manufacturers who achieve Class IIa medical device status. European hospital procurement now prioritizes CE-marked wristbands over consumer alternatives.
- Photoplethysmography sensor miniaturization:Advanced optical modules enable continuous SpO2 and blood pressure estimation without cuff inflation. Cardiology departments in self-insured employer clinics deploy these for hypertension management programs.
- China's tier-one city hospital networks:Digital health infrastructure mandates require wearable data integration into electronic medical records. Shenzhen and Shanghai public health systems source wristbands through centralized tenders.
Market Restraints
- Lithium-polymer battery cost volatility:Cell-grade cathode material pricing fluctuates with cobalt and nickel spot markets. Battery pack costs represent 18-22% of bill-of-materials for GPS-enabled clinical monitors.
- FDA software-as-a-medical-device validation timelines:Algorithm lockdown requirements extend product development cycles by 14-18 months. Smaller manufacturers lack capital reserves for parallel clinical trials.
- Smartphone substitution:Native health apps on flagship handsets capture casual wellness tracking without dedicated hardware purchase. Apple's HealthKit and Google's Fitbit APIs reduce wristband attachment rates among price-sensitive consumers.
Strategic Opportunities
- India's PLI scheme for wearable electronics:Production-linked incentives cover 4-6% of manufacturing costs for domestic assembly. Contract manufacturers can serve Middle East and African markets from Indian tariff-advantaged bases.
- Behavioral health integration:Continuous galvanic skin response and accelerometry data enable anxiety and depression episode detection. Psychiatric telehealth platforms seek wristband partnerships for medication adherence verification.
- ISO 13485:2016 quality management adoption:Medical device manufacturers with certified quality systems access accelerated regulatory pathways in Brazil, Saudi Arabia, and South Korea. Certification investment amortizes across multiple geography submissions.
Industry Challenges
- Biomedical signal processing talent scarcity:Algorithm engineers with combined expertise in time-series analysis and regulatory documentation command premium compensation. University pipelines produce machine learning generalists, not domain specialists.
- Legacy EMR integration complexity:Hospital information systems use proprietary data formats that require custom HL7 FHIR middleware. Each health system deployment demands 6-12 weeks of engineering adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monitoring Wristband Market |
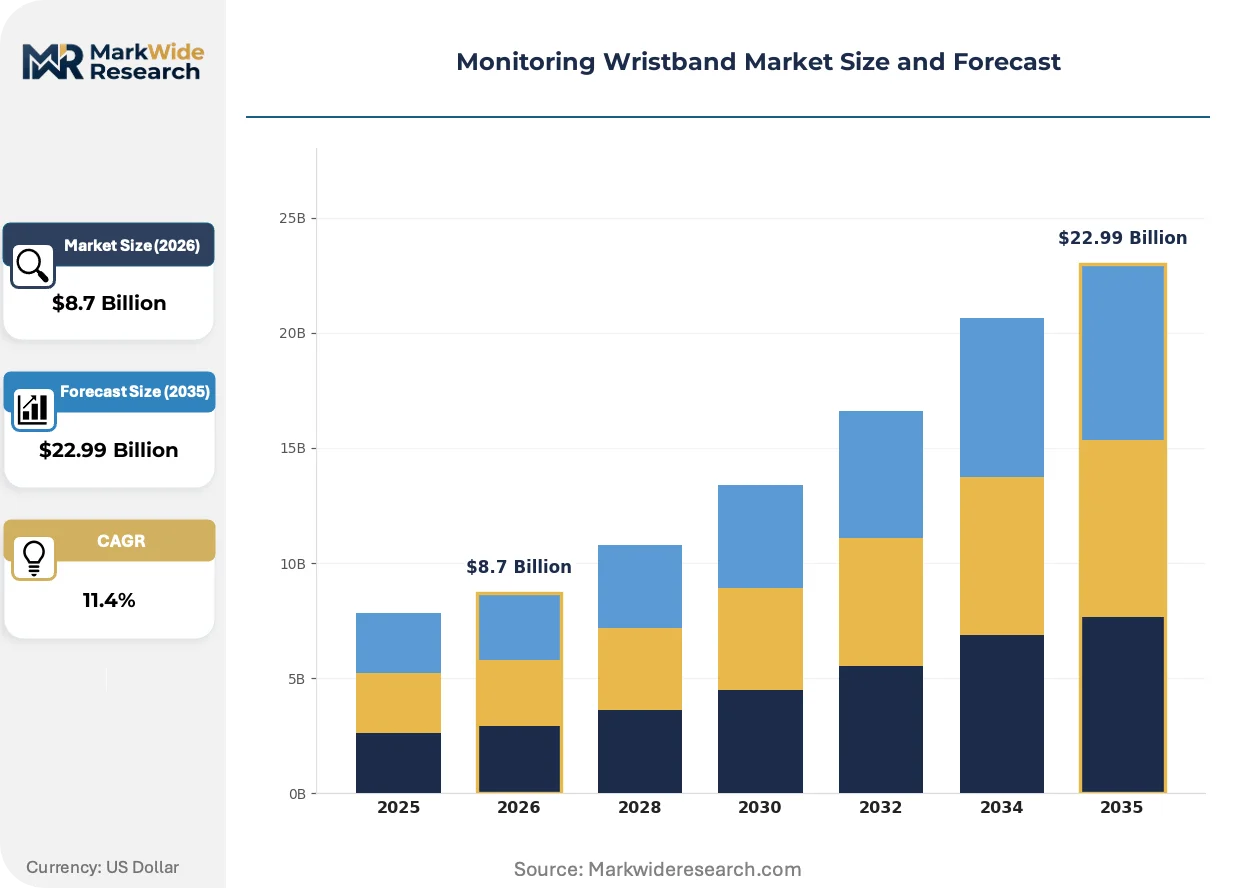
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Medical Monitors, Smart Bands, Wearable Devices End User: Individuals, Healthcare Providers, Fitness Enthusiasts, Corporate Wellness Programs Technology: Bluetooth, Wi-Fi, NFC, GPS Application: Health Monitoring, Activity Tracking, Sleep Analysis, Emergency Alerts |
| Companies Covered | Apple, Xiaomi, Huawei Technologies, Fitbit, Garmin, Samsung Electronics, Polar Electro, Withings, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monitoring Wristband Market Trends and Innovations
Multi-modal sensor fusion and edge computing architectures are compressing the latency between physiological event detection and clinical intervention, enabling real-time cardiac arrhythmia alerts without cloud dependency.
Reflectance-mode photoplethysmography with green and infrared dual-LED arrays is integrating into wristband form factors previously limited to fingertip pulse oximeters. Cardiac rehabilitation centers in Germany and the United States prescribe these devices for post-myocardial infarction monitoring. The technology is integrating clinical-grade vital sign capture into consumer-accessible price tiers, collapsing the historical segmentation between wellness and medical device categories.
FDA's finalized guidance on predetermined change control plans for machine learning-enabled devices establishes a pathway for algorithm updates without full 510(k) resubmission. Manufacturers can deploy improved atrial fibrillation detection models through documented validation protocols. This regulatory accommodation accelerates competitive differentiation for firms with robust post-market surveillance infrastructure, particularly affecting arrhythmia monitoring wristbands targeting United States cardiologist practices.
Employer-sponsored wellness programs are consolidating vendor relationships from multiple point solutions to single-platform contracts. Self-insured corporations in the United States now procure wristbands through benefits administrators rather than direct manufacturer relationships. This channel concentration shifts pricing power toward intermediaries with national account scale, compressing manufacturer margins while expanding device deployment volumes across Fortune 500 workforces.
Monitoring Wristband Market Segmentation
Device replacement cycles in monitoring wristbands compress as sensor accuracy improvements and regulatory recertification requirements accelerate upgrade decisions across consumer and clinical procurement channels.
Product Type:
Upgrade cycles diverge sharply between consumer wellness devices and clinical-grade hardware, with the latter tied to hospital capital equipment refresh schedules.
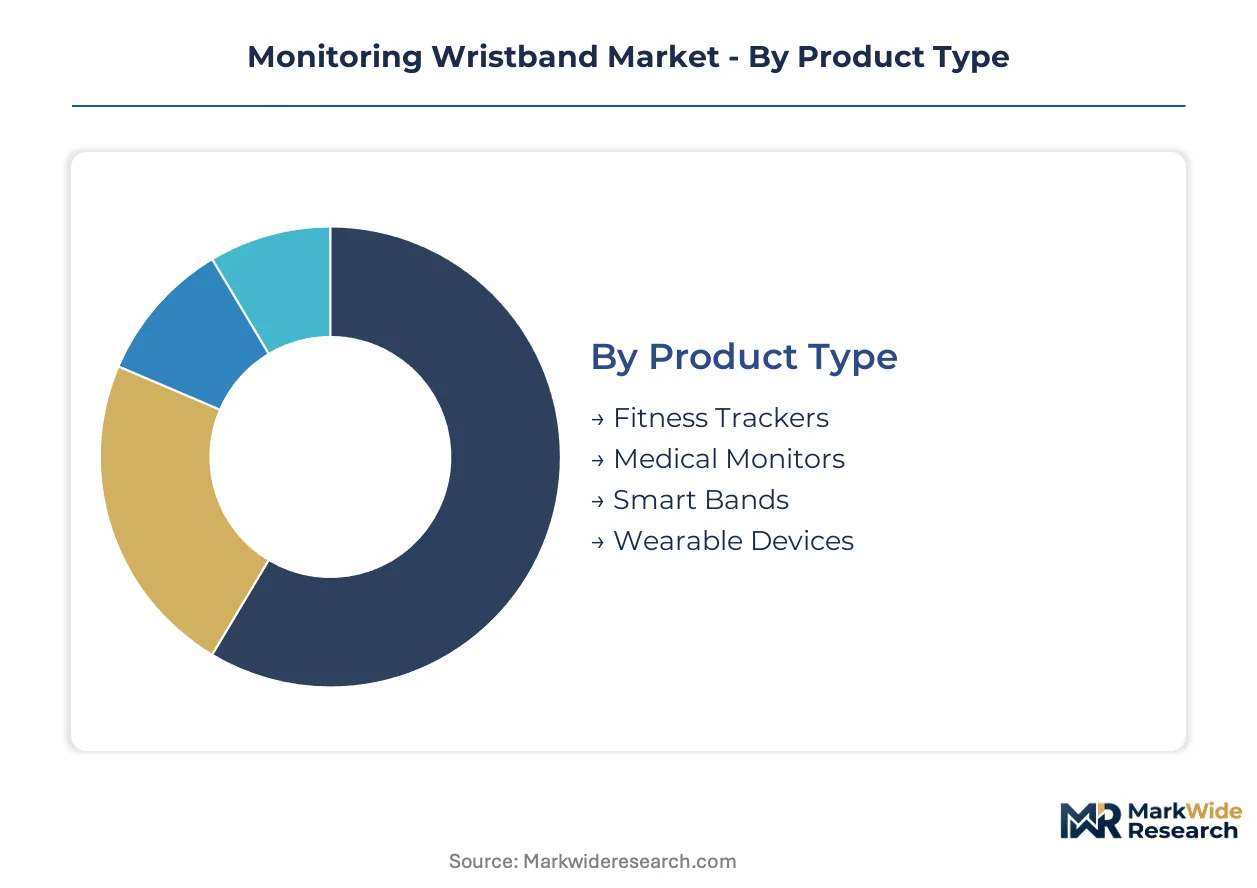
- Fitness Trackers:Consumer-grade accelerometry and optical heart rate sensors power 18-24 month replacement cycles driven by aesthetic redesigns and battery degradation. Shenzhen contract manufacturers dominate volume production for price-sensitive markets in Southeast Asia and Latin America.
- Medical Monitors:FDA-cleared photoplethysmography and ECG algorithms require locked-down firmware architectures that resist feature obsolescence. United States hospital systems and German cardiac rehabilitation centers prioritize ISO 13485-certified suppliers for multi-year service contracts.
- Smart Bands:Hybrid positioning between wellness and clinical use cases drives 30-36 month upgrade patterns. China's tier-one city hospital networks source these through centralized procurement tenders that emphasize EMR integration over standalone functionality.
- Wearable Devices:Broad category encompassing experimental form factors and pediatric adaptations. Niche demand concentrates in Japanese eldercare facilities and United States pediatric epilepsy monitoring programs.
Fitness Trackers sits at the top of the volume ranking, with Medical Monitors climbing the fastest.
End User:
Procurement authority consolidation is reshaping how manufacturers access distinct customer types, with intermediaries capturing pricing power in corporate channels.
- Individuals:Direct-to-consumer purchases through e-commerce platforms and electronics retailers. Amazon and Tmall account for dominant distribution share in North America and China respectively.
- Healthcare Providers:Hospital systems and physician practices purchasing through group purchasing organizations. United States remote patient monitoring reimbursement codes convert these from capital expenditures to billable service components.
- Fitness Enthusiasts:Dedicated athletes and amateur competitors demanding specialized metrics. Garmin and Polar command loyalty through proprietary training load algorithms and recovery score methodologies.
- Corporate Wellness Programs:Self-insured employers deploying devices for preventive health intervention. Benefits administrators like Virgin Pulse and Vitality now consolidate vendor relationships, compressing manufacturer margins while expanding deployment scale.
Individuals generate the highest absolute unit volumes, though Corporate Wellness Programs are expanding most quickly as benefits administrators consolidate procurement.
Technology:
Connectivity module selection determines power consumption profiles and regulatory compliance boundaries across geographic markets.
- Bluetooth:Low-energy protocols enable continuous smartphone pairing with minimal battery drain. Universal adoption across all price tiers makes this the baseline connectivity standard.
- Wi-Fi:Direct cloud synchronization bypasses smartphone dependency for elderly users and clinical settings. German telemedicine platforms and United States skilled nursing facilities specify Wi-Fi for independent operation.
- NFC:Contactless payment and access control integration drives adoption in transit-heavy urban environments. Tokyo and Seoul transit authority partnerships accelerate deployment.
- GPS:Location tracking for outdoor activity mapping and emergency response geofencing. Battery cost concentration in GPS-enabled units reaches 18-22% of bill-of-materials.
Bluetooth dominates shipment volumes, while Wi-Fi gains share fastest among clinical and eldercare applications requiring independent operation.
Application:
Use case specificity determines sensor array configuration and algorithm development investment priorities.
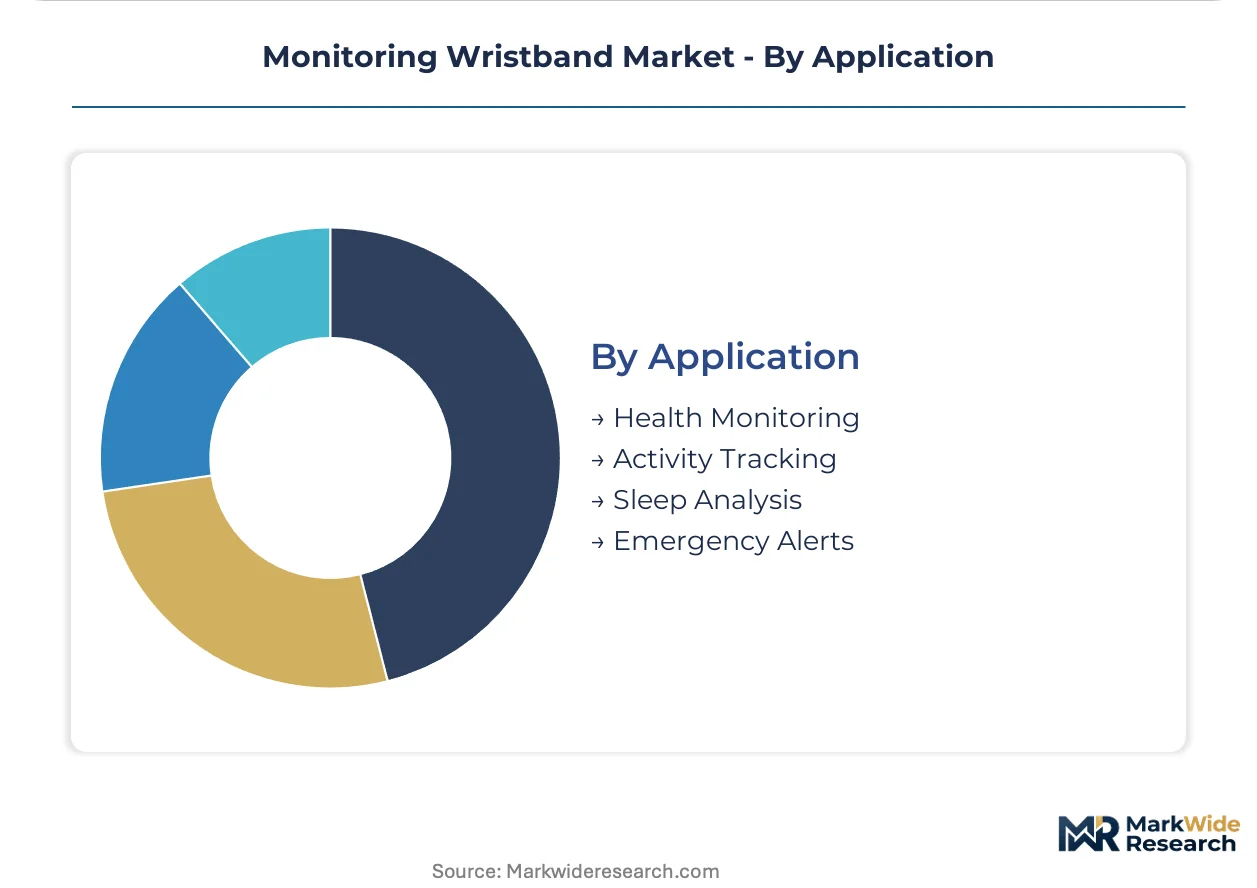
- Health Monitoring:Continuous vital sign surveillance including heart rate variability, SpO2, and blood pressure estimation. Cardiology departments in self-insured employer clinics deploy these for hypertension management programs.
- Activity Tracking:Step counting, calorie expenditure, and workout classification through accelerometry and gyroscope fusion. Baseline functionality now commoditized across sub-premium price tiers.
- Sleep Analysis:Sleep stage classification and respiratory disturbance detection through accelerometry and optical sensors. Behavioral health platforms seek partnerships for depression and anxiety episode correlation.
- Emergency Alerts:Fall detection, arrhythmia notification, and manual SOS triggering. United States senior living facilities and Japanese municipal eldercare programs mandate these features for reimbursed deployment.
Activity Tracking leads in cumulative device-years deployed, with Emergency Alerts showing the steepest expansion trajectory as aging populations drive institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems deploy wristbands through remote patient monitoring programs, while China's tier-one cities integrate wearable data into public hospital EMR networks at scale.
United States
Self-insured employers and cardiology practices drive procurement through benefits administrators and group purchasing organizations. FDA software-as-a-medical-device guidance extends validation timelines for clinical-grade algorithms. Hospital systems in Texas and Florida prioritize ISO 13485-certified suppliers for multi-year service contracts.
China
Shenzhen and Shanghai public health systems source devices through centralized tenders mandating EMR integration. NMPA digital health device pathways accelerate domestic approval but impose data localization requirements. Pearl River Delta contract manufacturers supply both domestic hospital networks and export markets.
Germany
Cardiac rehabilitation centers prescribe reflectance-mode photoplethysmography wristbands for post-myocardial infarction monitoring. EU MDR Class IIa certification creates procurement preference for CE-marked devices over consumer alternatives. Bavaria's medical technology cluster hosts specialized middleware developers for HL7 FHIR integration.
India
Production-linked incentives under the PLI scheme cover manufacturing costs for domestic assembly serving Middle East and African markets. CDSCO medical device rules create compliance pathways for clinical wristband imports. Karnataka and Tamil Nadu electronics manufacturing zones attract contract manufacturers.
Japan
Municipal eldercare programs mandate fall detection and emergency alert features for reimbursed deployment. METI standards for wearable health devices shape sensor accuracy requirements. Tokyo transit authority partnerships accelerate NFC-enabled wristband adoption for contactless payment integration.
Monitoring Wristband Market Competitive Landscape
Top-tier vendors anchor premium clinical and consumer segments, while mid-tier specialists and contract manufacturers populate volume-driven markets. The vendor base stratifies across three tiers: ecosystem-integrated technology conglomerates, specialized health wearable developers, and white-label electronics fabricators. Competitive moves center on regulatory certification acquisition for clinical market entry and strategic partnerships with benefits administrators for corporate wellness channel access.
Within the ecosystem-integrated tier, Apple and Samsung Electronics occupy positions spanning consumer wellness and clinical-adjacent applications. Garmin exemplifies the specialized athletic performance archetype through proprietary training algorithms. Xiaomi anchors the volume-distribution model through direct-to-consumer channels in Asia. These three represent distinct strategic postures: premium ecosystem lock-in, vertical specialization, and cost-optimized scale penetration.
| Leading Market Players |
|---|
| Apple |
| Xiaomi |
| Huawei Technologies |
| Fitbit |
| Garmin |
| Samsung Electronics |
| Polar Electro |
| Withings |
| Sony |
| Others |
Pricing and Supply Chain Analysis
Algorithm engineers with combined signal-processing and regulatory-documentation expertise cluster in Shenzhen, Boston, and Munich, commanding compensation premiums that widen spreads between ISO 13485-certified clinical monitors and consumer-grade fitness trackers.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for Bluetooth-enabled fitness bands while clinical-grade hardware maintains premium positioning through FDA and EU MDR certification barriers. Three-tier pricing structure across premium, standard, and economy levels separates subscription-integrated medical monitors from direct-to-consumer smart bands and white-label fitness trackers. Price differentiation centers on ISO 13485 quality-system certification and photoplethysmography sensor accuracy grades. Cost compression in the economy tier is intensifying because Shenzhen contract manufacturers are absorbing lithium-polymer battery volatility through volume commitments. Corporate wellness programs exhibit highest price sensitivity due to benefits-administrator consolidation, while German cardiac rehabilitation centers show lowest sensitivity given reimbursement code coverage.
Supply Chain Analysis
Regional distribution centers in Hong Kong, Rotterdam, and Los Angeles anchor hub-and-spoke patterns that position finished goods within 72-hour delivery windows of hospital procurement offices and consumer electronics retailers. Manufacturing concentrates in China, Vietnam, and Taiwan for sensor module assembly and final device integration. Raw material dependencies include cobalt and nickel for lithium-polymer cells, indium gallium arsenide for infrared photodetectors, and FR-4 substrates for printed circuit boards. Single-source vulnerability in advanced photoplethysmography optical modules creates chokepoint exposure as only three qualified suppliers serve FDA-cleared device manufacturers. Distribution runs through group purchasing organizations for United States hospital systems and through e-commerce platforms for direct-to-consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in monitoring wristbands rests on photoplethysmography sensor miniaturization cost curves and the shift of clinical-grade devices toward recurring-revenue subscription models.
For Market Incumbents: Anticipate smartphone health-app substitution by deepening ecosystem integration through HL7 FHIR middleware investments that lock hospital systems into multi-year service contracts. Defend against emerging white-label manufacturers from India's PLI scheme by accelerating EU MDR Class IIa certification for core product lines to maintain procurement preference in European hospital tenders.
For New Entrants and Emerging Players: Launch via psychiatric telehealth platform partnerships that seek continuous galvanic skin response data for anxiety and depression episode detection, bypassing saturated fitness-tracker channels. Target behavioral health integration as the most penetrable application segment given limited incumbent specialization and rising employer demand for mental health intervention metrics.
For Investors and Strategic Acquirers: Self-insured employers and benefits administrators are the most active strategic buyers in this space, consolidating vendor relationships to capture pricing power. Long-term viability favors manufacturers with post-market surveillance infrastructure for FDA predetermined change control plans. Watch reimbursement code expansion for remote physiological monitoring as the inflection signal determining whether clinical wristbands achieve billable care delivery status.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Unlocks United States hospital procurement through software-as-a-medical-device clearance. |
| EU MDR Class IIa Certification | Creates defensible margin positions in German and French cardiac rehabilitation markets. |
| Hospital System Partnership | Secures multi-year remote patient monitoring contracts through GPO channel access. |
| Software Companion Development | Enables subscription revenue streams beyond hardware sales through analytics platforms. |
| Reimbursement Strategy | Positions devices as billable care delivery instruments under evolving CMS codes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical signal processing engineers, hospital purchasing committee members, GPO contracts managers, and benefits administrators at self-insured employers with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, NMPA approval registries, and EU MDR notified body certificates. Bottom-up shipment estimates triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Historical reference periods anchored the forecast window to capture replacement cycle compression and regulatory recertification dynamics. Segmentation modeling spanned device category, procurement channel, connectivity protocol, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to unit shipment and average selling price trajectories. Industry-specific inputs included lithium-polymer battery cost indices, photoplethysmography sensor yield rates, and hospital EMR integration project timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software validation timeline extensions or NMPA data localization enforcement shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market