
 South America Feed Probiotics Market | 2026-2036
South America Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Probiotics Market Analytics
Asset-light contract manufacturing and tolling arrangements are reshaping competitive entry in the South America Feed Probiotics Market, allowing regional distributors to launch private-label formulations without captive fermentation capacity. Novus International Inc. leverages its amino acid logistics network to bundle probiotic offerings with existing premix contracts across Brazilian integrators. Lallemand Inc. anchors its position through yeast strain banks maintained at research stations in São Paulo state. Kemin Industries Inc. competes via encapsulated delivery technologies that protect viability during pelleting.
Feed probiotics comprise live microbial cultures, primarily lactic acid bacteria and Saccharomyces cerevisiae, formulated to colonize the gastrointestinal tract of livestock and modulate nutrient absorption, pathogen exclusion, and immune response; viability thresholds typically require minimum colony-forming unit counts per gram at point of consumption. The bacteria segment leads value generation due to strain-specific efficacy claims in poultry gut health, while yeast products sustain faster volume growth in ruminant applications where rumen fermentation modulation commands premium pricing. Powder formulations dominate distribution through feed mill integration, though liquid concentrates are gaining share in aquaculture operations requiring tank-side dosing flexibility.
Brazil's Ministry of Agriculture (MAPA) and Argentina's National Service for Agri-Food Health and Quality (SENASA) enforce registration requirements for direct-fed microbial products, creating compliance barriers that favor established suppliers with in-country stability data. The Mercosur technical regulation harmonization process is reshaping cross-border product approvals, though country-specific strain authorization timelines still fragment market access. Stakeholders must monitor pending updates to microbial feed additive maximum inclusion rates and the divergence between national organic certification standards and conventional probiotic labeling claims.
Market Dynamics
Antibiotic growth promoter bans across Brazil and Argentina are forcing feed formulators to rebuild gut health protocols around live microbial additives, compressing the transition window for probiotic suppliers to prove efficacy under commercial conditions.
Growth Catalysts
- ANVISA veterinary drug restrictions:Brazil's tightening antibiotic residue limits in poultry exports to the European Union are accelerating probiotic substitution in integrated operations across Paraná and Santa Catarina states.
- Saccharomyces cerevisiae fermentation:Yeast strain improvements for rumen pH stabilization are capturing premium positioning in Argentine dairy feedlots facing heat stress productivity losses.
- Southern Brazil soybean belt concentration:Proximity of feed mills to probiotic distribution hubs reduces cold-chain viability losses during last-mile delivery to large integrators.
Market Restraints
- Lyophilization energy costs:Spray-drying and freeze-drying of bacterial cultures ties production economics to Brazilian electricity tariffs and natural gas import volatility.
- Strain authorization fragmentation:Mercosur harmonization delays force suppliers to maintain separate stability dossiers for MAPA and SENASA, duplicating regulatory expenditure.
- Enzyme feed additive substitution:Non-viable fermentation products targeting nutrient digestibility compete for the same gut health budget allocation in cost-sensitive swine operations.
Strategic Opportunities
- Uruguayan beef export channel:Premium grass-fed certification programs create demand for probiotic finishing protocols that differentiate product in EU and Chinese import markets.
- Liquid concentrate aquaculture dosing:Tank-side application systems for tilapia and shrimp ponds in Ecuador and Colombia bypass pelleting viability constraints entirely.
- Organic certification alignment:Divergence between Brazilian MAPA organic standards and EU-equivalent labels creates arbitrage space for dual-certified probiotic formulations.
Industry Challenges
- CFU enumeration technician shortage:Specialized microbiology skills for viability testing at point-of-use remain concentrated in São Paulo and Buenos Aires, constraining quality assurance expansion.
- Legacy ERP integration:Feed mill traceability systems require custom API development to log probiotic lot numbers alongside conventional ingredient certificates of analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Probiotics Market |
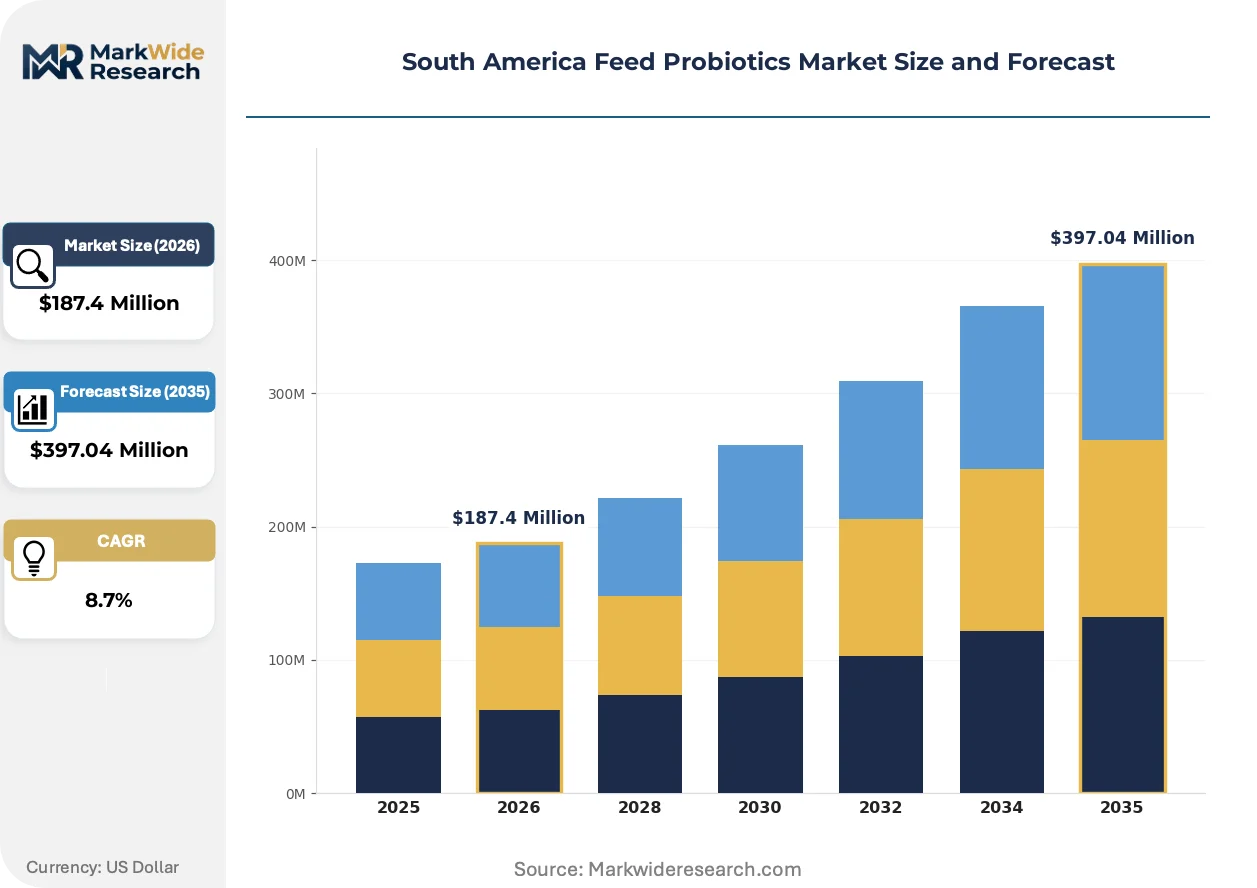
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Yeast, Fungi, Enzymes Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Capsule Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Novus International Inc., Lallemand Inc., Evonik Industries, Kemin Industries Inc., DSM Firmenich, Adisseo, CHR. Hansen A/S, Cargill Inc., IFF (Danisco Animal Nutrition), Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Probiotics Market Evolving Landscape
Live microbial delivery systems are converging with precision fermentation and encapsulation chemistry, reshaping how suppliers protect viability through feed manufacturing thermal stress and gastrointestinal transit.
Microencapsulation via lipid matrix and alginate shell technologies is hybridizing bacterial protection protocols. Brazilian integrators in the southern poultry corridor are piloting these dual-layer systems at commercial scale. The approach compresses viability loss margins that previously forced over-formulation by 30-50 percent to hit label claims post-pelleting.
SENASA's pending updates to direct-fed microbial maximum inclusion rates are tightening strain-specific documentation requirements. Argentine feed compounders must now submit region-specific stability data for each bacterial combination. Poultry premix suppliers are responding by narrowing product portfolios to core Lactobacillus and Bacillus strains with established local dossiers.
Integrated poultry operations are consolidating probiotic procurement under amino acid and vitamin premix umbrella contracts. Large Brazilian integrators now negotiate single-supplier agreements bundling microbial additives with lysine and methionine volumes. This vendor consolidation pattern concentrates most visible in Paraná state, where three protein processors control 60 percent of regional feed mill capacity.
South America Feed Probiotics Market Segmentation
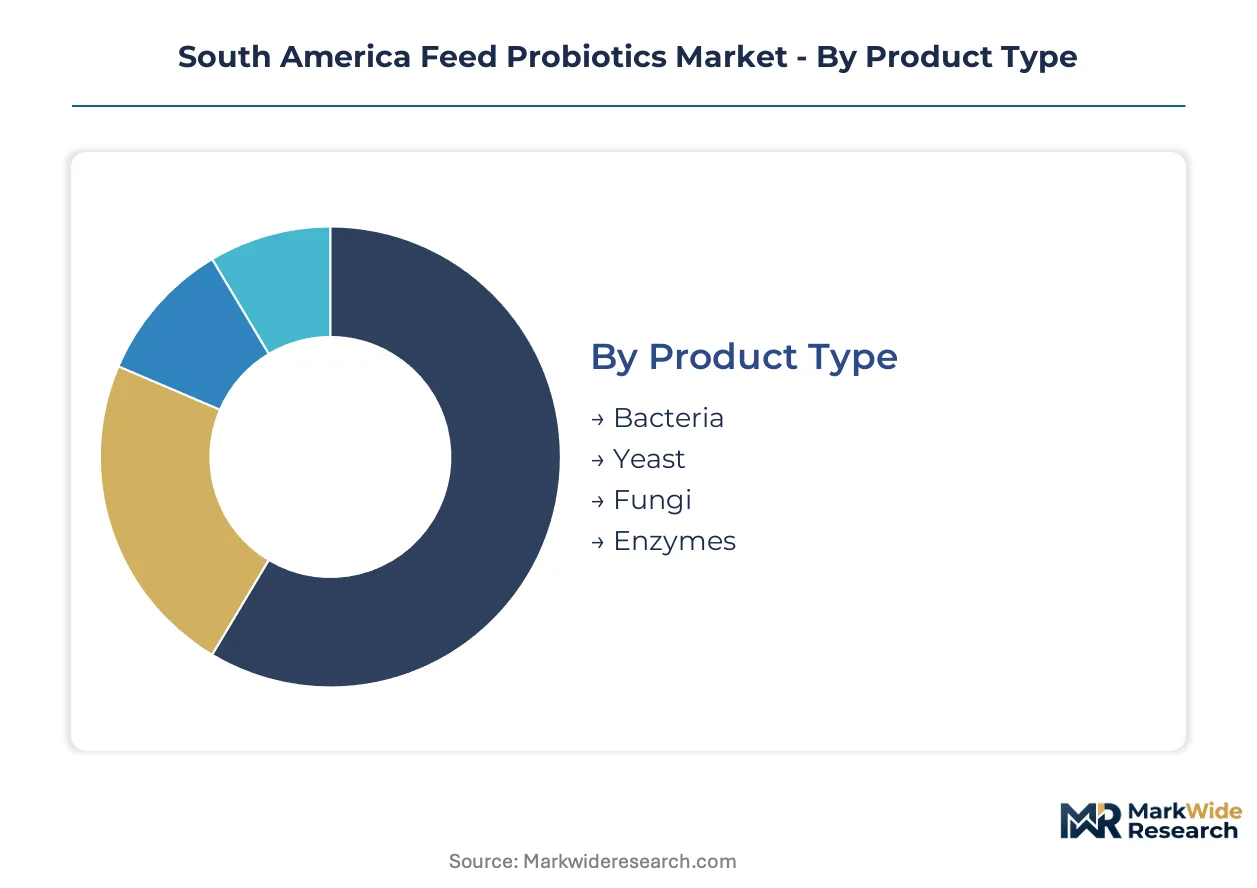
Feed probiotic suppliers in South America structure product portfolios around strain viability requirements, feed manufacturing thermal stress, and species-specific gut colonization protocols. Segmentation choices directly determine cold-chain logistics investment, registration dossier complexity, and pricing power in contract negotiations with integrated protein processors.
Product Type:
Strain classification drives manufacturing capital intensity, with lyophilization capacity and fermentation scale determining competitive positioning across bacterial versus yeast platforms.
- Bacteria:Lactic acid bacteria and Bacillus strains dominate poultry gut health applications, requiring CFU counts above 10^9 per gram at point of consumption. Brazilian integrators in Paraná and Santa Catarina states specify Lactobacillus-based formulations under ANVISA antibiotic restriction compliance protocols.
- Yeast:Saccharomyces cerevisiae products command premium positioning in Argentine dairy feedlots, where rumen pH stabilization during heat stress events justifies higher inclusion rates. SENASA registration requirements for yeast strains remain less burdensome than bacterial authorization timelines.
- Fungi:Aspergillus-based fermentation products target fiber digestibility in ruminant rations across Uruguay's grass-fed beef operations.
- Enzymes:Non-viable fermentation extracts compete for gut health budget allocation in cost-sensitive Brazilian swine operations.
Bacteria holds installed capacity. Yeast is rotating up the share rankings.
Application:
Species-specific digestive physiology dictates strain selection, with poultry driving volume concentration and aquaculture representing the steepest expansion trajectory.
- Poultry:Broiler operations across Brazil's southern soybean belt integrate probiotics into antibiotic-free export protocols targeting European Union residue limits. Integrated processors negotiate bundled premix contracts covering lysine, methionine, and live microbial additives.
- Swine:Nursery phase applications concentrate in Mato Grosso and Rio Grande do Sul states, where weaning stress mitigation commands consistent inclusion rates.
- Ruminants:Argentine dairy feedlots facing heat stress productivity losses specify yeast-based rumen fermentation modulators.
- Aquaculture:Tank-side dosing flexibility for tilapia and shrimp ponds in Ecuador and Colombia bypasses pelleting viability constraints entirely.
Poultry dominates procurement volumes. Aquaculture is climbing the fastest.
Form:
Physical formulation determines thermal protection requirements through feed mill pelleting processes and storage stability under ambient temperature distribution.
- Liquid:Concentrates enable precise dosing in aquaculture operations and automated inclusion systems at large feed mills. Cold-chain requirements constrain distribution radius from production facilities.
- Powder:Standard presentation for feed mill integration, with microencapsulation technologies reducing viability loss margins that previously forced 30-50 percent over-formulation.
- Granular:Flowability advantages in automated handling systems appeal to Brazilian integrators with legacy equipment.
- Capsule:Veterinary prescription formats for therapeutic applications in high-value breeding stock.
Powder commands installed capacity. Liquid is gaining share fastest.
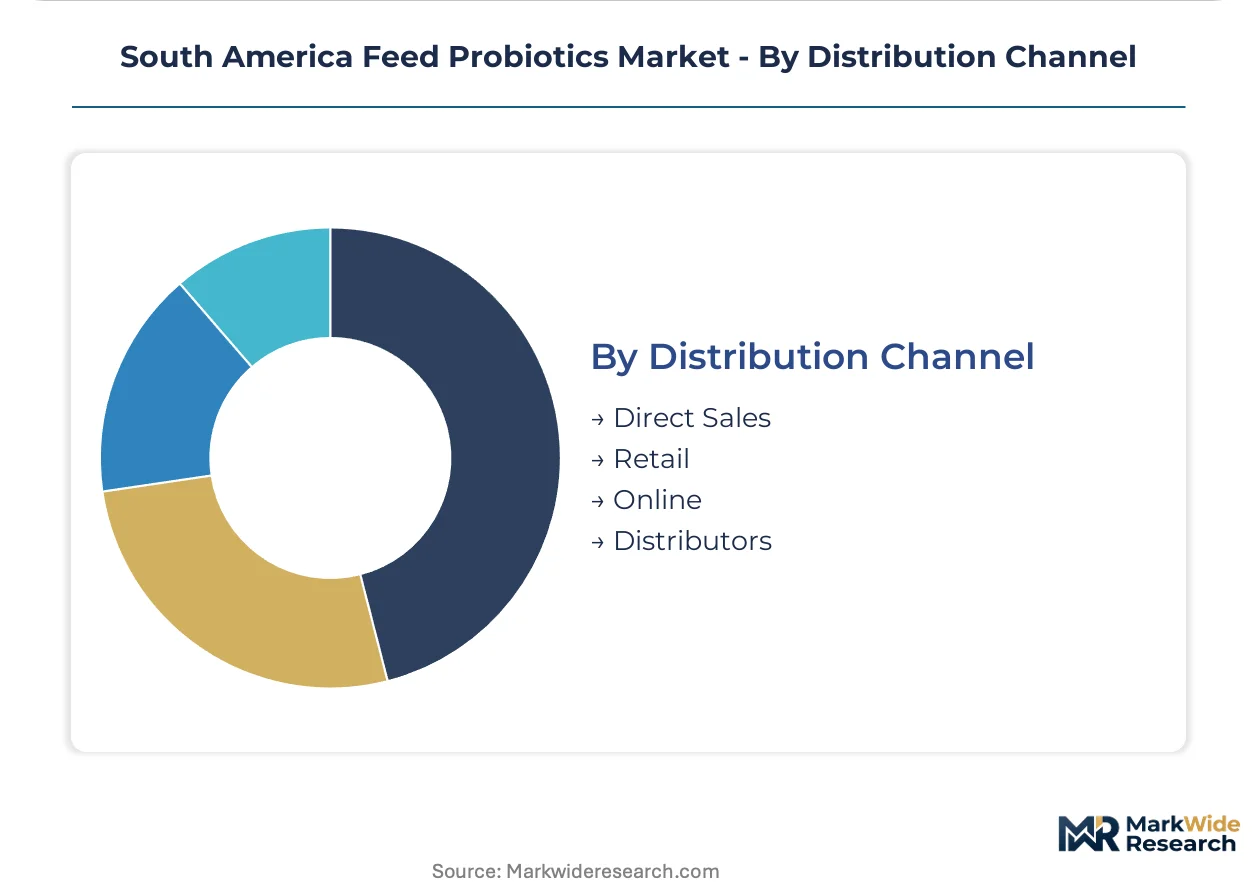
Distribution Channel:
Channel selection reflects customer scale, with direct relationships dominating integrated operations and distributor networks penetrating fragmented farm bases.
- Direct Sales:Large Brazilian protein processors negotiate single-supplier umbrella contracts bundling probiotics with amino acid and vitamin premix volumes. Three processors control 60 percent of Paraná state feed mill capacity.
- Retail:Farm supply cooperatives serve mid-scale independent producers across Argentina's Pampas region.
- Online:Emerging channel for technical documentation access and small-volume orders from specialty producers.
- Distributors:Regional networks with cold-chain capabilities cover last-mile delivery to Santa Catarina and Rio Grande do Sul poultry operations.
Direct sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
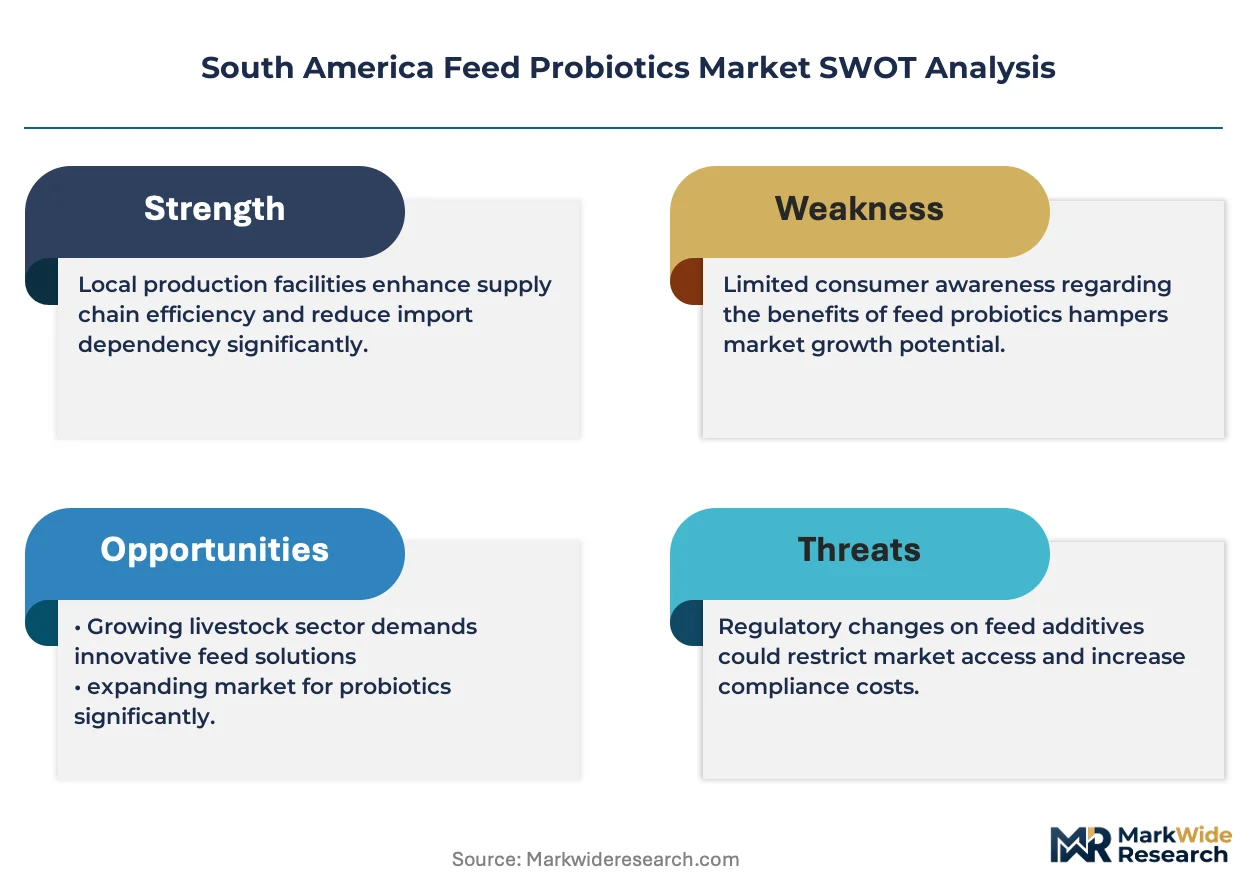
ANVISA veterinary drug restrictions and SENASA feed additive registrations are redrawing procurement corridors across South America, with national regulators enforcing divergent stability documentation that fragments cross-border product flows.
Brazil
Integrated poultry processors in Paraná and Santa Catarina states specify Lactobacillus-based formulations under antibiotic-free export protocols targeting European Union residue limits. MAPA registration requirements for direct-fed microbials demand in-country stability data that favors established suppliers with existing dossiers. Cold-chain distribution hubs in Curitiba and Chapecó concentrate last-mile delivery to feed mills serving three protein processors controlling 60 percent of regional capacity.
Argentina
Dairy feedlots across Buenos Aires and Córdoba provinces specify Saccharomyces cerevisiae products for rumen pH stabilization during heat stress events. SENASA's pending updates to maximum inclusion rates are tightening strain-specific documentation requirements for each bacterial combination. Poultry premix suppliers in Rosario industrial corridor are narrowing portfolios to core strains with established local stability dossiers.
Uruguay
Premium grass-fed beef certification programs create demand for probiotic finishing protocols that differentiate product in EU and Chinese import markets. The country's national agricultural regulator enforces feed additive standards aligned with Mercosur technical regulations. Feed mill operations in Montevideo and Paysandú departments are piloting dual-certified organic formulations bridging MAPA and EU-equivalent label requirements.
Colombia
Aquaculture operations in Antioquia and Valle del Cauca departments are adopting tank-side liquid concentrate dosing systems for tilapia ponds that bypass pelleting viability constraints. The national agricultural institute oversees feed additive registrations with requirements converging toward Brazilian technical standards. Distribution networks from Medellín logistics clusters serve emerging demand from shrimp producers in Pacific coastal zones.
Ecuador
Shrimp aquaculture in Guayas and El Oro provinces drives adoption of liquid probiotic concentrates requiring precise pond-side application. The country's sanitary and phytosanitary regulator maintains feed additive standards focused on export market access for marine products. Processing facilities in Guayaquil metropolitan area integrate probiotic procurement with automated tank dosing infrastructure.
South America Feed Probiotics Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning in South American feed probiotic supply. The market structure reflects consolidation around integrated premix bundling alongside fragmentation among regional distributors launching private-label formulations. Three strategic archetypes dominate: multinational nutrition companies leveraging amino acid logistics networks, specialized microbial suppliers maintaining strain banks at research stations, and regional toll manufacturers enabling asset-light market entry. Competitive moves concentrate on vendor consolidation through umbrella contract negotiations and microencapsulation technology licensing for thermal protection.
Within the multinational nutrition tier, Novus International Inc. and Kemin Industries Inc. exemplify channel-controlling archetypes that bundle probiotic offerings with existing premix contracts across Brazilian integrators. Lallemand Inc. occupies a position among specialized microbial suppliers maintaining technical infrastructure for strain development. These three companies anchor distinct competitive vectors: logistics-integrated bundling, encapsulated delivery technologies, and fermentation strain banking.
| Leading Market Players |
|---|
| Novus International Inc. |
| Lallemand Inc. |
| Evonik Industries |
| Kemin Industries Inc. |
| DSM Firmenich |
| Adisseo |
| CHR. Hansen A/S |
| Cargill Inc. |
| IFF (Danisco Animal Nutrition) |
| Others |
Value Network & Pricing Analysis
Overcapacity in Brazilian lyophilization facilities is compressing contract manufacturing margins and forcing suppliers toward bundled premix pricing models that capture value through amino acid logistics integration rather than standalone microbial premiums.
Pricing Analysis
Certification level (MAPA/SENASA dual-registered versus single-market authorization) creates the primary spread between premium and economy tiers in South American feed probiotics. Contract-based long-term offtake agreements dominate procurement between large Brazilian integrators and multinational nutrition suppliers, with volume scale and cold-chain reliability serving as secondary price differentiation drivers. Cost compression in standard-grade bacterial formulations is intensifying because Argentine toll manufacturers are expanding fermentation capacity without corresponding strain authorization dossiers. Mid-scale independent producers across Argentina's Pampas region exhibit highest price sensitivity, while integrated poultry processors in Paraná state prioritize viability guarantees over per-kilogram unit costs.
Supply Chain Analysis
Regional toll manufacturers in São Paulo state and contract fermentation specialists in Buenos Aires province hold dominant lyophilization capacity for bacterial culture production. Geographic supply concentration centers on Brazil, Argentina, and Uruguay, with Brazilian soybean belt feed mills drawing from Curitiba and Chapecó distribution hubs. Raw material dependencies include pharmaceutical-grade fermentation substrates, specialized cryoprotectants for freeze-drying, and alginate encapsulation polymers. Single-source vulnerability in strain banking infrastructure poses structural risk, as SENASA and MAPA authorization timelines require maintained access to original deposition facilities. Distribution runs through direct sales channels for integrated processors and regional cold-chain distributors for fragmented farm bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic growth promoter bans across Mercosur markets are disrupting legacy gut health protocols and creating a high-growth window for live microbial suppliers that can demonstrate commercial-scale efficacy under compressed transition timelines.
For Market Incumbents: Build regulatory dossier moats by deepening MAPA and SENASA strain authorization archives before harmonization tightens documentation requirements. Incumbent suppliers should consolidate vendor relationships through umbrella contracts bundling probiotics with lysine and methionine volumes, while investing in microencapsulation R&D to protect viability margins against emerging enzyme feed additive substitutes threatening gut health budget allocation. For New Entrants and Emerging Players: Liquid concentrate aquaculture dosing systems in Ecuador and Colombia represent the most penetrable entry point, bypassing pelleting viability constraints that incumbent powder formulations cannot address. Mid-scale Uruguayan beef operations seeking dual-certified organic formulations for EU export channels offer secondary white-space access. New entrants should pursue asset-light toll manufacturing arrangements with established Brazilian fermentation facilities to circumvent captive capacity requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across liquid concentrate production platforms as precision fermentation technologies reduce bioreactor scale requirements. Long-term viability over the next decade hinges on regulatory harmonization completion rather than strain efficacy differentiation alone. Investors should target regional distributors with established cold-chain networks and pending MAPA registration pipelines as acquisition candidates. The critical signal to watch is SENASA's pending maximum inclusion rate updates, which will strain authorization timelines and favor incumbent dossier depth.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Dual-layer lipid-alginate systems reduce over-formulation requirements for Brazilian pelleting operations. |
| Strain Bank Research Station Expansion | São Paulo state yeast strain repositories anchor technical differentiation against commodity bacterial suppliers. |
| Cold-Chain Distribution Partnership | Last-mile viability protection from Curitiba hubs secures Paraná integrator contract renewals. |
| Dual-Certification Organic Alignment | MAPA-EU label bridging captures Uruguayan beef export premium positioning. |
| Liquid Concentrate Aquaculture Launch | Tank-side dosing infrastructure bypasses thermal stress constraints in Ecuadorian shrimp operations. |
Research Methodology
A standing panel of feed mill procurement directors, veterinary microbiology researchers, regulatory affairs specialists at MAPA and SENASA, and cold-chain logistics operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from customs trade databases, ANVISA veterinary drug restriction filings, Mercosur technical regulation harmonization documents, and integrated protein processor annual disclosures. Bottom-up strain-level volume estimates and top-down premix contract value analysis were triangulated to converge on market sizing.
Scenario-bracketing around regulatory harmonization timelines and antibiotic restriction enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include strain classification (bacterial, yeast, fungal), species application (poultry, ruminant, aquaculture), physical formulation (powder, liquid, granular), and distribution channel structure. CAGRs were derived from elasticity-adjusted adoption curves tied to ANVISA enforcement patterns and SENASA authorization completion rates. Industry-specific forecast inputs incorporated lyophilization energy cost trajectories and CFU enumeration technician availability constraints.
Practitioners should monitor MAPA organic standard divergence from EU-equivalent labels, SENASA inclusion rate update timing, and Brazilian electricity tariff volatility for early signals of forecast revision necessity. Quarterly review of strain authorization backlog durations and toll manufacturing capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market