
 Bifidobacterium Probiotics Market | 2026-2036
Bifidobacterium Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Bifidobacterium Probiotics Market Insights
Pharmacy and health food store distribution networks are reconfiguring as probiotic brands bypass traditional wholesale intermediaries. DuPont de Nemours leverages its strain library breadth to dominate pharmaceutical-grade supply. Chr. Hansen Holding anchors its position through culture collection depth and dairy industry partnerships. Lallemand competes via yeast and bacteria integration across human and animal nutrition lines.
Bifidobacterium probiotics comprise live bacterial cultures, predominantly B. longum, B. bifidum, and B. animalis subspecies, typically formulated at colony-forming unit counts exceeding one billion per dose to confer gastrointestinal and immune-modulating benefits. The organisms require cryoprotectant stabilization and controlled-atmosphere packaging to maintain viability through shelf life. Dietary supplements occupy the largest margin pool due to premium positioning and direct-to-consumer accessibility, while functional foods in yogurt format sustain the highest absolute volume throughput. Animal feed applications are accelerating as livestock producers phase out antibiotic growth promoters under regulatory pressure.
EFSA novel food approvals and FDA GRAS notifications govern strain-level market access in Europe and the United States, with dossier requirements intensifying around human intervention study standards. China's NMPA and SAMR enforce dual-layer registration for imported probiotic strains, creating compliance bottlenecks that favor domestic cultivation partnerships. Stakeholders must monitor evolving strain-specific qualification thresholds across these three jurisdictions to preserve formulation pipelines and avoid portfolio obsolescence.
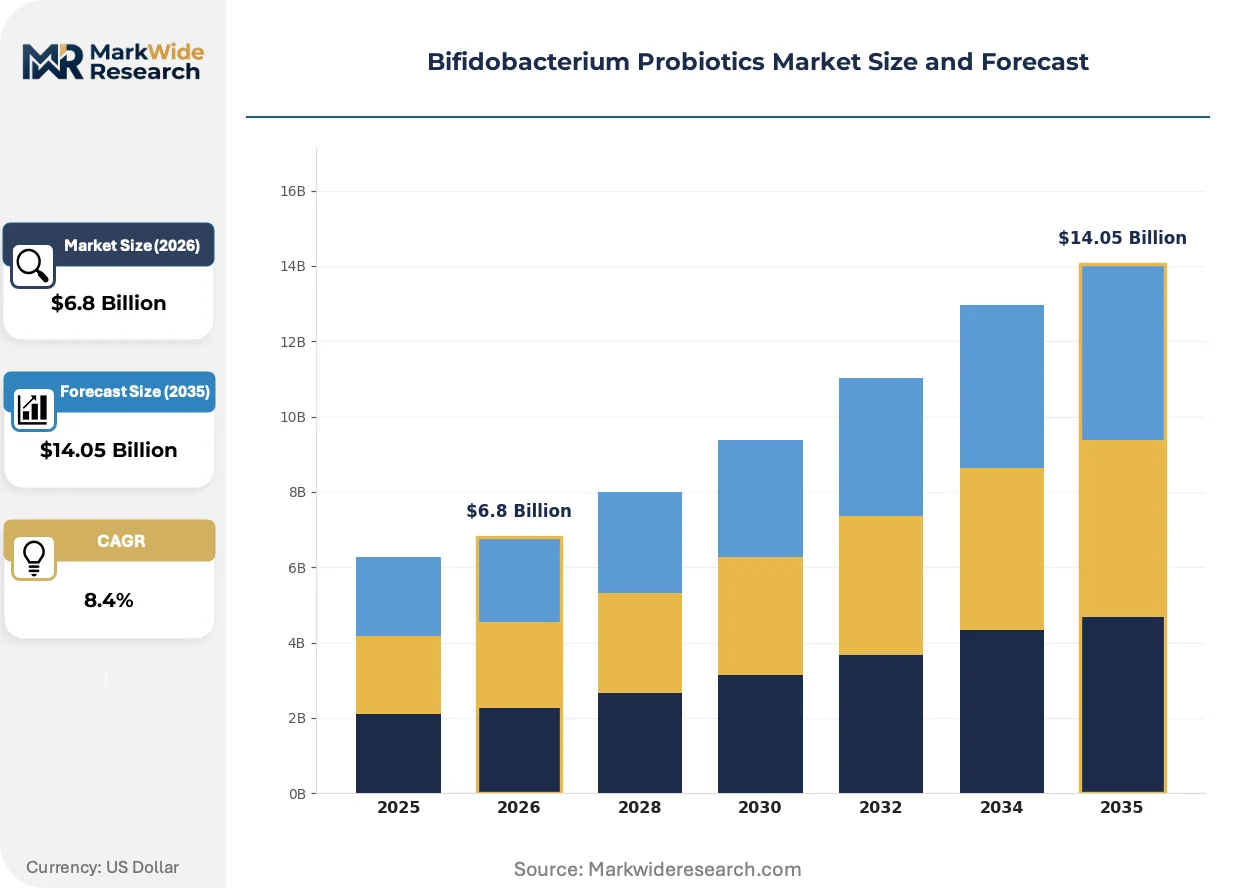
Market Dynamics
Strain-specific regulatory qualification thresholds are fragmenting formulation pipelines as EFSA, FDA, and China's SAMR impose divergent human intervention study standards on Bifidobacterium probiotic developers.
Growth Catalysts
- Infant nutrition prioritization:Parents in China and Germany are prioritizing early-life gut microbiome development, expanding Bifidobacterium applications in pediatric formula and follow-on nutrition products.
- Antibiotic growth promoter phase-out:Livestock producers across Brazil and the European Union are accelerating Bifidobacterium inclusion in animal feed under regulatory pressure from ANVISA and EFSA guidelines.
- Cryoprotectant stabilization advances:Lyophilization technologies incorporating trehalose and skim milk matrices are extending viable shelf life, enabling ambient distribution in pharmacy and direct-to-consumer channels.
Market Restraints
- Dual-layer registration friction:China's NMPA and SAMR enforce separate strain cultivation and import registration, creating compliance bottlenecks that favor domestic partnerships over direct foreign supply.
- Colony-forming unit volatility:Temperature excursions during ambient logistics degrade viable counts, forcing cold-chain investments that compress margins in functional food applications.
- Strain library concentration:Pharmaceutical-grade Bifidobacterium supply concentrates among culture collection holders, creating dependency risks for mid-tier supplement formulators.
Strategic Opportunities
- Senior nutrition underpenetration:Japan's aging demographic presents white space for Bifidobacterium formulations targeting immunosenescence, with METI actively promoting functional food claims for elderly gut health.
- Direct-to-consumer channel expansion:Subscription-based probiotic delivery is bypassing traditional pharmacy wholesale intermediaries, capturing premium positioning through personalized microbiome testing integration.
- Precision fermentation convergence:Recombinant protein production platforms are merging with anaerobic bacterial cultivation, enabling strain-specific metabolite enhancement for next-generation synbiotic products.
Industry Challenges
- Human intervention study capacity:EFSA's tightened substantiation requirements for strain-specific health claims demand placebo-controlled trials that strain developers struggle to resource internally.
- Legacy ERP integration:Quality management systems for live culture tracking require retrofitting into existing pharmaceutical manufacturing execution platforms, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bifidobacterium Probiotics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Chewables, Yogurt Application: Dietary Supplements, Functional Foods, Animal Feed, Clinical Nutrition End User: Adults, Infants, Seniors, Athletes Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | DuPont de Nemours, Chr. Hansen Holding, Lallemand, Nestlé, Danone, Probi AB, Yakult Honsha, Kerry Group, BioGaia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifidobacterium Probiotics Market Trends and Innovations
Live culture stabilization technologies and regulatory claim substantiation protocols are compressing competitive differentiation windows across the Bifidobacterium value chain.
Microencapsulation via alginate-chitosan coacervation is collapsing the viability gap between refrigerated and ambient probiotic products. Infant formula manufacturers in the Netherlands and Denmark are adopting this technology at scale, eliminating cold-chain dependencies that previously constrained pharmacy distribution reach.
EFSA's 2023 updated guidance on gut health claim substantiation is mandating strain-specific human intervention studies with defined primary endpoints. This policy shift is raising dossier preparation costs and timelines, disproportionately affecting mid-sized supplement brands that lack internal clinical affairs capabilities.
Chinese parents are bypassing traditional retail pharmacy channels for infant probiotics, instead purchasing through cross-border e-commerce platforms that offer direct access to European-registered strains. This channel rotation is compressing domestic brand loyalty and forcing reformulation partnerships with SAMR-registered domestic cultivators.
Bifidobacterium Probiotics Market Segmentation
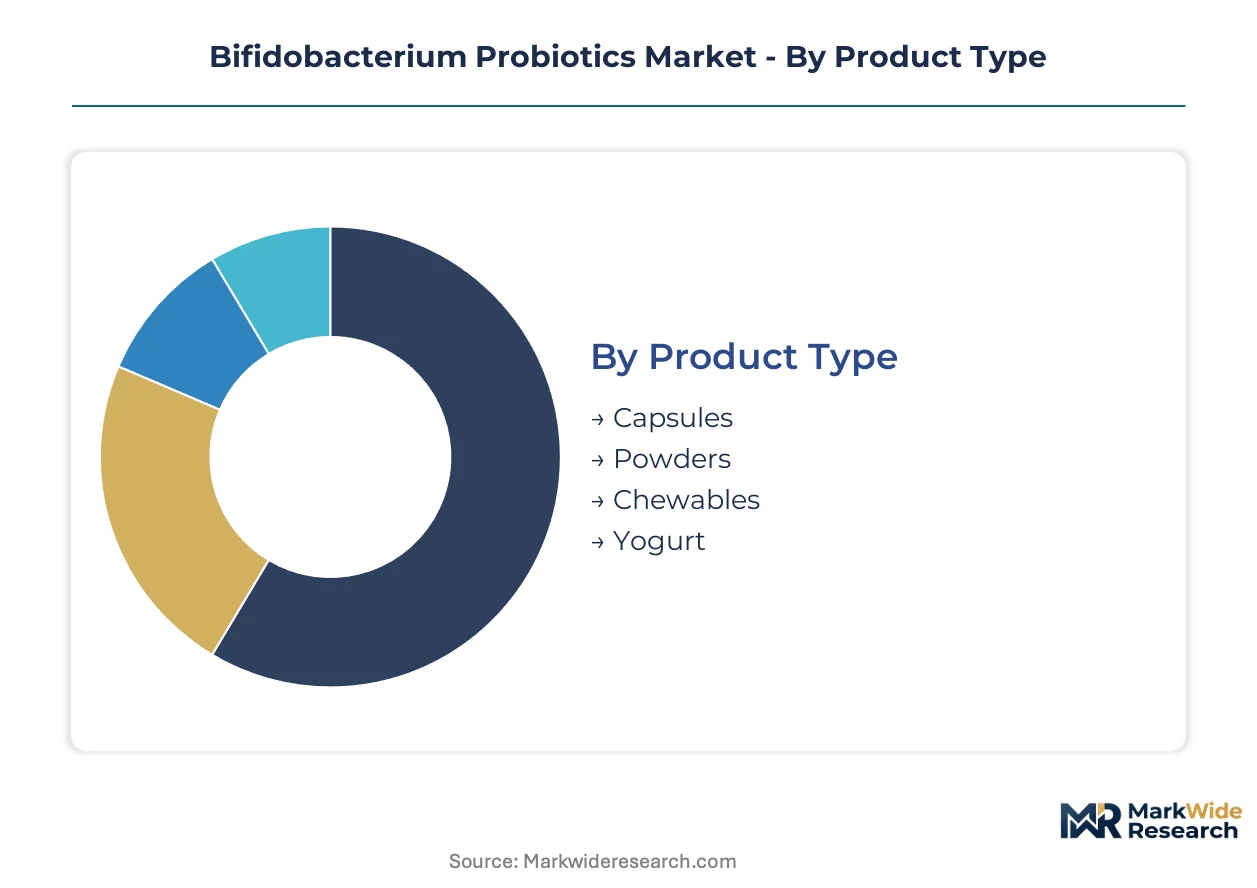
Bifidobacterium probiotics traverse multiple formulation formats and consumption contexts, each imposing distinct stability requirements and margin structures. Strain viability thresholds, regulatory claim pathways, and cold-chain economics fragment addressable opportunity across these dimensions.
Product Type:
Cost tier and manufacturing complexity stratify competitive positioning across delivery formats, with cryoprotectant load and packaging specifications driving unit economics.
- Capsules:Hard-shell gelatin or hypromelsellose enclosures protect lyophilized cultures from gastric acid degradation, enabling enteric-coated release profiles. Adult supplement demand in Germany and the United States concentrates here, with pharmacy chains extracting slotting fees that compress mid-tier brand margins.
- Powders:Sachet-dosed formulations incorporate trehalose-stabilized cultures for ambient shelf stability, supporting infant formula integration and direct-to-consumer subscription models. China’s cross-border e-commerce platforms favor this format for customs efficiency and dosing flexibility.
- Chewables:Compressed tablets with flavor masking compete for pediatric compliance, though moisture sensitivity limits viable strain selection and shelf life.
- Yogurt:Fresh dairy fermentation with live active cultures sustains the highest absolute volume throughput, with cold-chain dependency constraining distribution radius.
Capsules command the established base. The steepest expansion runs through powders.
Application:
Regulatory claim substantiation intensity and margin capture potential diverge sharply across end-use contexts, with pharmaceutical-grade specifications filtering market access.
- Dietary Supplements:Premium-positioned SKUs targeting digestive and immune health claims occupy the largest margin pool, with direct-to-consumer channels bypassing wholesale intermediaries. FDA notification requirements and EFSA health claim substantiation protocols govern strain-specific market access.
- Functional Foods:Yogurt and fermented beverage applications sustain mass-market penetration, though refrigerated distribution compresses operating margins relative to ambient-stable formats. Dutch and Danish manufacturers lead microencapsulation adoption to eliminate cold-chain dependencies.
- Animal Feed:Livestock producers in Brazil and the European Union accelerate inclusion under ANVISA and EFSA antibiotic growth promoter phase-out mandates.
- Clinical Nutrition:Hospital and enteral feeding applications demand pharmaceutical-grade strain documentation and batch-level viability certification, concentrating supply among culture collection holders.
Dietary supplements anchor revenue concentration. Clinical nutrition is climbing the fastest.
End User:
Demographic-specific microbiome development priorities and purchasing authority patterns reshape formulation requirements and channel strategy.
- Adults:General wellness and digestive comfort positioning dominates volume, with subscription models capturing recurring revenue through personalized microbiome testing integration.
- Infants:Early-life gut colonization applications in pediatric formula and follow-on nutrition command premium pricing, with Chinese parents prioritizing European-registered strains through cross-border channels.
- Seniors:Immunosenescence-targeted formulations remain underpenetrated, though Japan’s METI actively promotes functional food claims for elderly gut health.
- Athletes:Exercise-induced gut permeability and recovery positioning represents an emerging niche with specialized endurance nutrition brands.
Adults retain the volume base. Infants drive the steepest premium expansion.
Distribution Channel:
Channel control and customer data capture capabilities increasingly determine brand defensibility as traditional wholesale structures erode.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable strain-specific storytelling and subscription lock-in, with personalized microbiome testing bundling deepening engagement.
- Supermarkets:Mass-market yogurt and functional food placement sustains absolute volume, though private label concentration pressures branded pricing power.
- Health Food Stores:Specialty retailers with trained staff support premium supplement positioning and strain education, defending margin through service differentiation.
- Pharmacies:Professional recommendation channels concentrate infant and clinical nutrition sales, with cold-chain capabilities supporting live culture viability guarantees.
Pharmacies hold the established prescription-adjacent position. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the Netherlands where pharmaceutical-grade strain documentation commands substantial premiums, while Chinese manufacturers absorb margin compression from dual-layer registration requirements imposed by SAMR and NMPA.
China
Cross-border e-commerce platforms are displacing traditional pharmacy channels for infant probiotics as parents prioritize European-registered Bifidobacterium strains. SAMR and NMPA enforce separate cultivation and import registration layers that favor domestic partnerships over direct foreign supply. Shanghai and Guangdong province host the dominant probiotic cultivation facilities serving both local formulation and re-export markets.
Germany
Adult supplement demand concentrates in hard-shell capsule formats with pharmacy chains extracting slotting fees that compress mid-tier brand margins. EFSA gut health claim substantiation protocols mandate strain-specific human intervention studies with defined primary endpoints. Berlin and Frankfurt anchor the pharmaceutical-grade supply chain where culture collection documentation meets hospital and enteral feeding specifications.
United States
Direct-to-consumer subscription models are bypassing traditional wholesale intermediaries through personalized microbiome testing integration. FDA GRAS notifications govern strain-level market access with dossier requirements intensifying around human intervention study standards. Greater Boston and San Diego host precision fermentation convergence platforms merging recombinant protein production with anaerobic bacterial cultivation.
Japan
Senior nutrition formulations targeting immunosenescence remain underpenetrated despite METI actively promoting functional food claims for elderly gut health. PMDA and METI frameworks support health claim substantiation pathways distinct from Western regulatory architectures. Tokyo and Osaka metropolitan areas concentrate the domestic supplement manufacturing base serving aging demographic demand.
Brazil
Livestock producers are accelerating Bifidobacterium inclusion in animal feed under ANVISA antibiotic growth promoter phase-out mandates. ANVISA guidelines align with EFSA regulatory pressure to reduce agricultural antibiotic dependence. São Paulo state anchors both the dairy fermentation industry and the expanding feed additive formulation sector.
Bifidobacterium Probiotics Market Competitive Landscape
Culture collection holders and dairy-integrated multinationals split the market into distinct capability tiers with divergent margin capture mechanisms. Consolidation concentrates pharmaceutical-grade supply among entities with deep strain libraries, while functional food applications sustain a more fragmented tier of regional dairy processors. Two archetypes dominate: proprietary strain developers leveraging regulatory dossier depth, and fermentation-integrated nutrition companies capturing volume through ambient-stable format innovation. Competitive moves center on cryoprotectant stabilization technology licensing and SAMR-registered domestic cultivation partnerships in China.
Within the proprietary strain developer tier, DuPont de Nemours and Chr. Hansen Holding occupy positions defined by culture collection breadth and pharmaceutical-grade documentation capabilities. Lallemand represents the fermentation-integrated archetype spanning human and animal nutrition lines through yeast and bacteria platform convergence. These three entities exemplify how regulatory dossier depth and multi-kingdom fermentation expertise create divergent pathways to margin defense across infant formula, clinical nutrition, and feed additive applications.
| Leading Market Players |
|---|
| DuPont de Nemours |
| Chr. Hansen Holding |
| Lallemand |
| Nestlé |
| Danone |
| Probi AB |
| Yakult Honsha |
| Kerry Group |
| BioGaia |
| Others |
Pricing and Supply Chain Analysis
Shanghai and Guangdong province cultivation clusters dictate downstream pricing power through SAMR-registered strain access, with domestic partnerships commanding premiums over direct import channels. Cold-chain economics and cryoprotectant load stratify margin capture across pharmacy, direct-to-consumer, and mass retail channels.
Pricing Analysis
Customization-premium spreads separate pharmaceutical-grade strain documentation from standard dietary supplement tiers. Three-tier pricing structure across pharmaceutical-grade, premium supplement, and economy mass-market levels tracks certification depth and EFSA/FDA dossier status. Cost compression in economy tiers intensifies as private-label concentration at supermarkets erodes branded pricing power. Mass-market yogurt buyers exhibit highest price sensitivity; clinical nutrition procurement shows lowest sensitivity due to batch-viability certification requirements.
Supply Chain Analysis
Contract-manufacturing concentration rests with culture collection holders in Denmark, France, and the United States for pharmaceutical-grade supply. Raw material dependencies center on trehalose cryoprotectants, skim milk matrices, and anaerobic fermentation feedstocks. Single-source vulnerability concentrates in strain library access, where DuPont de Nemours and Chr. Hansen Holding control documentation depth. Distribution runs through pharmacy wholesale networks for infant and clinical segments, with direct-to-consumer platforms bypassing intermediaries in adult supplement categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EFSA and FDA strain-specific dossier requirements create insurmountable switching costs for mid-tier competitors.
For Market Incumbents: Insulate position through backward integration into cryoprotectant stabilization technology and exclusive SAMR-registered cultivation partnerships in China. Capacity addition in Shanghai province secures strain access against dual-layer registration friction. Channel control via direct-to-consumer microbiome testing platforms defends margin against pharmacy slotting fee compression. For New Entrants and Emerging Players: Build out presence in Japan's senior nutrition white space, where METI-promoted functional food claims for immunosenescence remain underpenetrated. Precision fermentation convergence platforms offer the most penetrable entry vector. Go-to-market through personalized subscription models bypasses entrenched pharmacy wholesale structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors culture collection holders with regulatory dossier depth over format innovators lacking strain documentation capabilities. Long-term viability hinges on strain-specific claim substantiation capabilities. The signal to watch is EFSA guidance tightening on human intervention study standards, which will accelerate consolidation among clinical affairs-capable developers.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR-Registered Cultivation Partnership | Dual-layer registration compliance unlocks direct China market access without domestic intermediary dependency. |
| Cryoprotectant Stabilization Licensing | Trehalose-matrix technology transfers extend ambient shelf life for pharmacy and e-commerce distribution reach. |
| Direct-to-Consumer Platform Launch | Microbiome testing integration captures recurring revenue and bypasses wholesale margin extraction. |
| Precision Fermentation Convergence | Recombinant protein platforms enable strain-specific metabolite enhancement for next-generation synbiotic products. |
| Senior Nutrition Formulation Development | Japan METI functional food claim pathways target underpenetrated immunosenescence applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across probiotic formulation scientists, regulatory affairs directors at culture collection holders, pharmacy chain procurement managers, infant formula brand managers, and precision fermentation platform engineers. Secondary validation drew from EFSA novel food approval databases, FDA GRAS notification filings, SAMR registration records, and customs trade data for cryoprotectant raw materials. Bottom-up strain-level volume estimates triangulated against top-down category spend data.
Calibration anchored segment-level projections to historical regulatory approval velocity and strain commercialization timelines across the analysis window. Modeled dimensions span product type, application, end user, and distribution channel, with regional regulatory cluster as an overlay. CAGRs derived from elasticity-adjusted adoption curves reflecting EFSA substantiation cost inflation and China cross-border e-commerce penetration rates.
Stress conditions across SAMR registration timeline extensions, EFSA human intervention study cost inflation, and cold-chain logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around strain viability thresholds and regulatory claim pathway stability. Quarterly review of EFSA guidance updates, SAMR registration queue depth, and precision fermentation platform capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
North America Oral Health Probiotics Market