
 United Kingdom Probiotics Market | 2026-2036
United Kingdom Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Probiotics Market Analytics
The UK Plastic Packaging Tax is rebalancing formulation priorities toward shelf-stable and ambient probiotic formats that reduce refrigeration dependency. Nestlé SA leverages its dairy infrastructure to sustain distribution scale across British retail channels. Yakult Honsha anchors its position through dedicated cold-chain logistics that competitors struggle to replicate. Protexin Probiotics specializes in practitioner-only lines that command premium positioning in UK pharmacies.
Probiotics comprise live microorganisms, typically Lactobacillus and Bifidobacterium strains at minimum viable counts of 10^6 to 10^9 colony-forming units per serving, administered to confer gastrointestinal or systemic health benefits. These cultures undergo freeze-drying or microencapsulation to preserve viability through manufacturing, storage, and gastric transit. The capsules segment dominates UK value pools due to convenience positioning and extended stability profiles that suit direct-to-consumer subscription models. Yogurts remain the most mature application with compressed margins, while mental health applications represent the fastest-growing category as psychobiotic research gains clinical traction among British consumers.
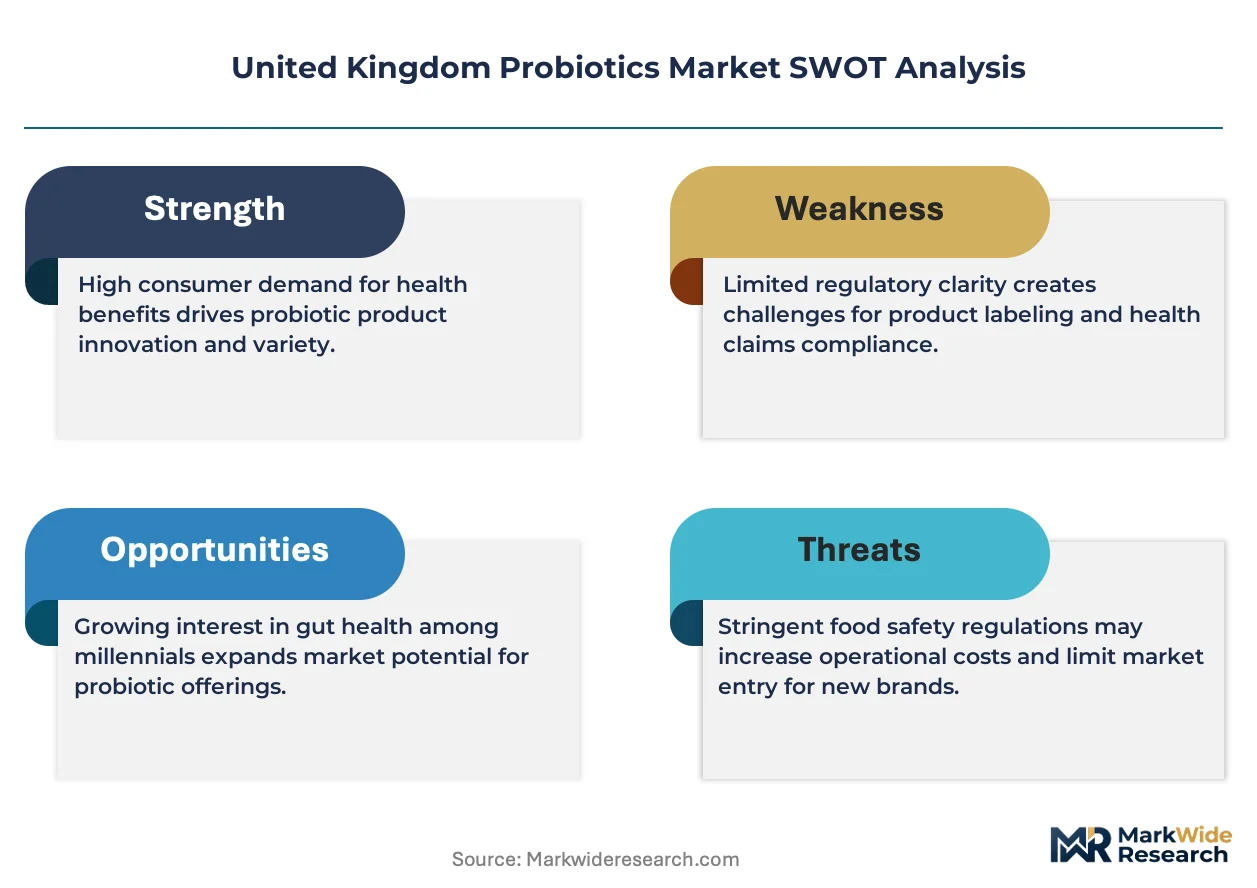
The Food Standards Agency and Advertising Standards Authority jointly govern probiotic health claims, with the FSA's novel food consultation process creating a barrier to entry for innovative strains. MHRA borderline regulations further complicate positioning when products approach medicinal thresholds. Stakeholders must monitor evolving EFSA-style substantiation requirements that the UK may adopt post-Brexit, as these would demand costly clinical validation for existing portfolio claims.
Market Dynamics
The UK Probiotics Market is undergoing structural recalibration as the Food Standards Agency's novel food consultation process elevates entry barriers for innovative strains while psychobiotic research redirects R&D investment toward mental health applications.
Growth Catalysts
- Gut-brain axis research:Clinical validation of psychobiotic mechanisms is expanding addressable indications beyond digestive health into anxiety and cognitive function endpoints.
- England's metropolitan retail concentration:London and Manchester health store networks provide established distribution infrastructure for premium probiotic formats.
- Plastic Packaging Tax incentives:Ambient-stable formulations reduce refrigeration dependency and align with sustainability mandates while lowering logistics costs.
Market Restraints
- Cold-chain infrastructure concentration:Dedicated refrigerated logistics remain concentrated among established dairy distributors, limiting new entrant scale.
- EFSA-style substantiation trajectory:Post-Brexit alignment with European clinical validation standards threatens existing portfolio claim portfolios.
- Freeze-drying input volatility:Specialized cryoprotectant and encapsulation material costs fluctuate with pharmaceutical-grade supply constraints.
Strategic Opportunities
- Practitioner channel expansion:Pharmacy and clinician networks remain underpenetrated relative to direct-to-consumer saturation.
- Subscription model convergence:Direct-to-consumer platforms combined with extended-stability capsule formats enable recurring revenue capture.
- Mental health application white space:Psychobiotic positioning targets stress and sleep endpoints where clinical evidence is accumulating faster than regulatory precedent.
Industry Challenges
- MHRA borderline classification complexity:Products approaching medicinal thresholds face extended review timelines and repositioning costs.
- Strain-specific IP fragmentation:Patent thickets around proprietary Lactobacillus and Bifidobacterium isolates complicate formulation freedom-to-operate.
- Microbiome assay standardization gaps:Inconsistent viability testing protocols create quality assurance friction between manufacturers and retail buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Probiotics Market |
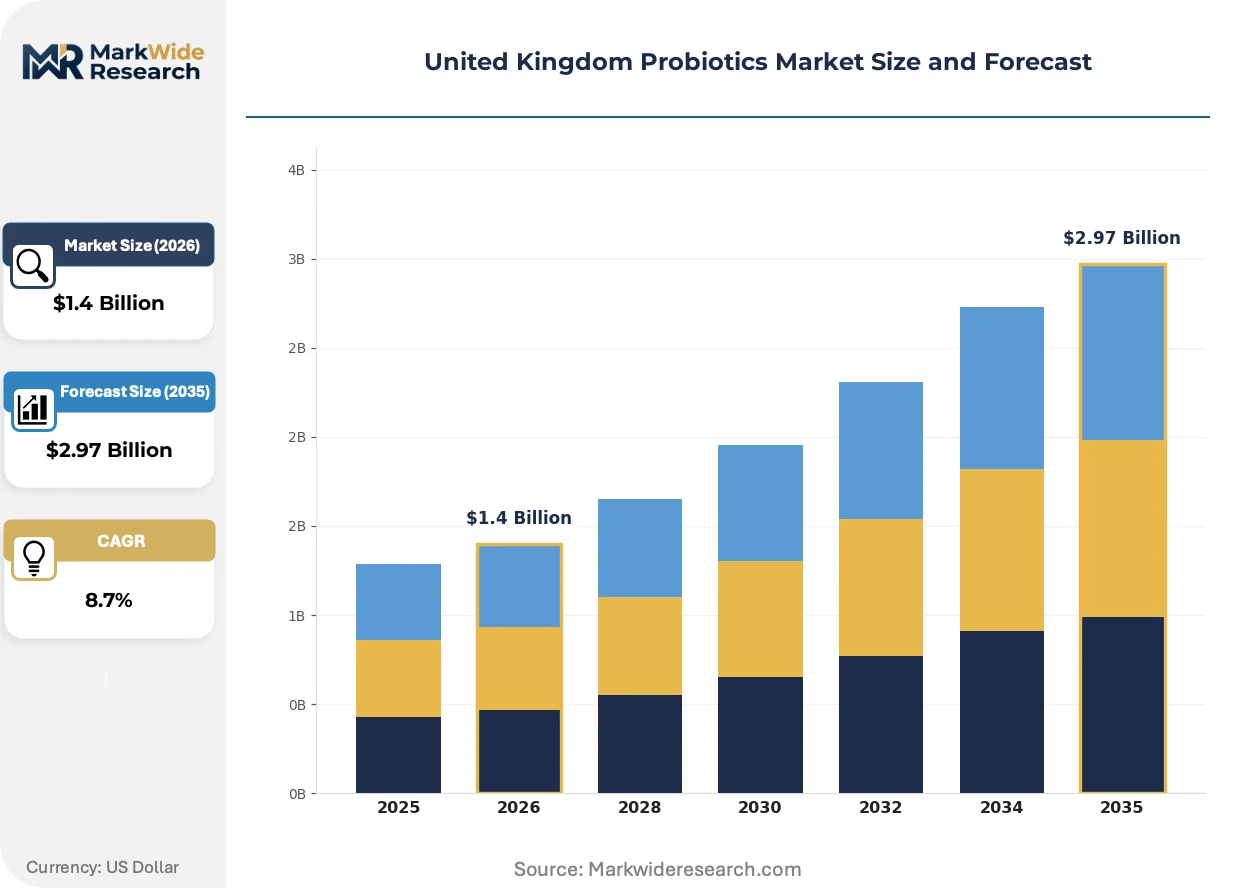
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Yogurts, Beverages End User: Adults, Infants, Elderly, Athletes Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies Application: DigeEstive Health, Immune Support, Weight Management, Mental Health |
| Companies Covered | Nestlé SA, Groupe Danone, Yakult Honsha, OptiBac Probiotics Ltd., BioGaia, PepsiCo Inc., Lifeway Foods, Bio & Me, Protexin Probiotics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Probiotics Market Evolving Landscape
Microencapsulation advances and regulatory claim evolution are compressing traditional format advantages while redirecting competitive investment toward clinically substantiated positioning. Three developments warrant particular attention.
Microencapsulation technology is modularizing probiotic delivery systems by enabling strain-specific coating architectures that protect viability through gastric transit. Functional food manufacturers are adopting these systems at accelerating pace to differentiate ambient-stable formats from conventional refrigerated yogurts. The technology is modularizing supply chain requirements and allowing new entrants to bypass legacy cold-chain dependencies entirely.
Advertising Standards Authority enforcement tightening on health claims is forcing substantiation upgrades across the sector. The FSA's parallel novel food consultations are extending approval timelines for genetically modified or engineered strains. Capsule and supplement segments bear the heaviest compliance burden as they lack the traditional food status that shields yogurt applications.
British consumers are consolidating purchasing decisions around subscription-based direct-to-consumer platforms that bundle personalized microbiome testing with targeted probiotic regimens. Health food retailers in London and Manchester are responding by unbundling after-sales consultation from product margins. This behavioral shift concentrates lifetime value capture among platforms with integrated data infrastructure rather than traditional retail intermediaries.
United Kingdom Probiotics Market Segmentation
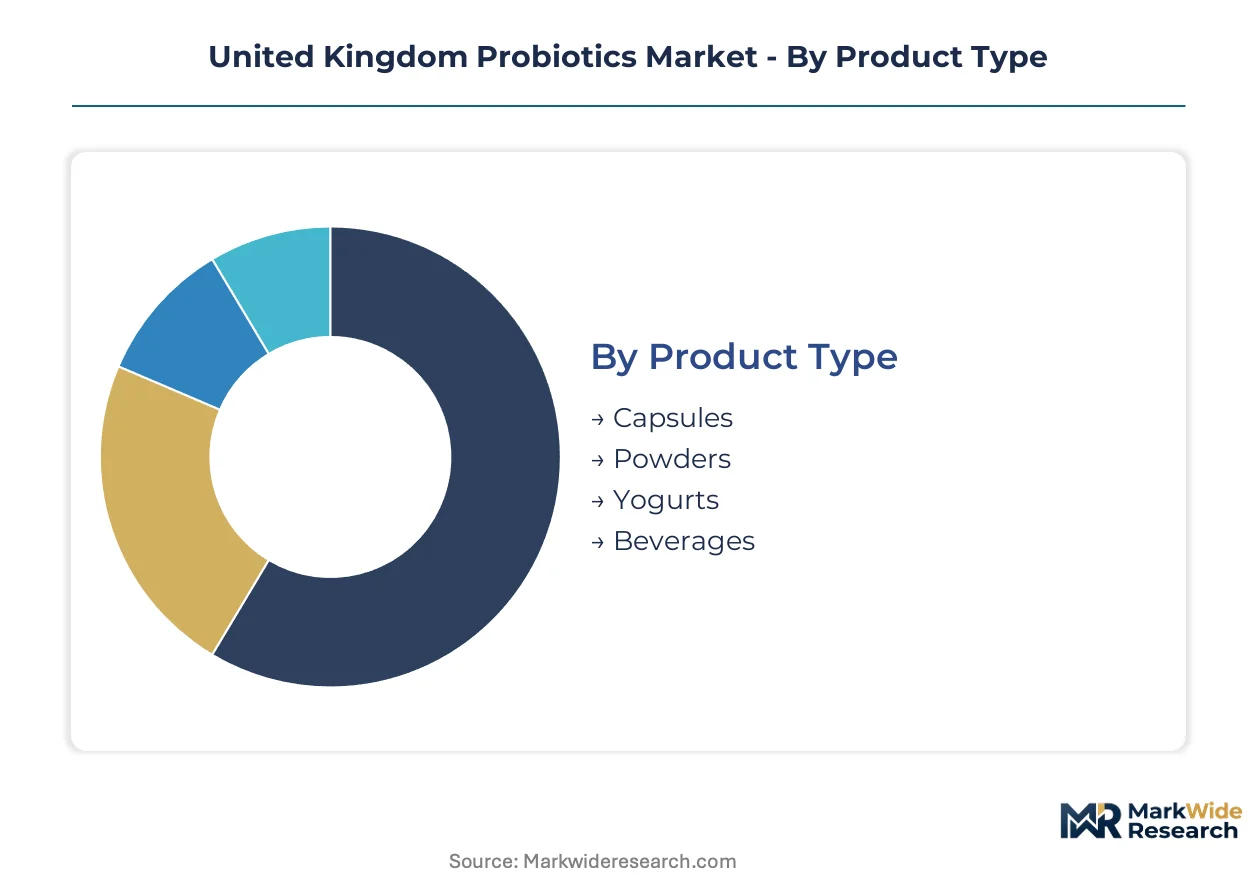
Segmentation in the UK probiotics market reveals how formulation stability, channel economics, and regulatory positioning fragment commercial opportunity. Buyers prioritize convenience, clinical credibility, or price accessibility depending on their wellness sophistication and purchase context.
Product Type:
Adult wellness buyers gravitate toward formats matching their lifestyle integration preferences and storage constraints.
- Capsules:Freeze-dried or microencapsulated cultures in gelatin or vegetable-based shells deliver 10^6 to 10^9 CFU per unit with 18-24 month ambient stability. Direct-to-consumer subscriptions concentrate in London and Manchester, where extended shelf life reduces replenishment friction. The Plastic Packaging Tax accelerates adoption of shelf-stable formats that minimize refrigerated logistics.
- Powders:Bulk lyophilized cultures packaged in sachets or jars allow dose flexibility and blend compatibility with smoothies or foods. Demand clusters among athletes and functional food enthusiasts seeking customizable intake protocols.
- Yogurts:Traditional dairy-based delivery with live cultures at point of manufacture, though viability degrades through cold-chain distribution. Margins compress as ambient alternatives capture convenience-seeking buyers.
- Beverages:Ready-to-drink formulations requiring continuous refrigeration, constraining distribution to established dairy networks and premium convenience retail.
Volume sits with Yogurts; growth tilts toward Capsules.
End User:
Life stage and activity level determine strain specificity, dosage requirements, and channel access for probiotic procurement.
- Adults:The broadest addressable base spanning preventive wellness and symptomatic management, with psychobiotic applications expanding fastest among urban professionals. Mental health positioning targets stress and sleep endpoints where clinical evidence accumulates ahead of regulatory precedent.
- Infants:Formulations emphasize Bifidobacterium strains for early microbiome establishment, with practitioner endorsement required for parental confidence. The FSA novel food consultation process creates particular barriers for innovative strains in this vulnerable population.
- Elderly:Immune support and digestive regularity drive demand, with swallowing-friendly formats preferred. Pharmacy and clinician networks remain underpenetrated relative to direct-to-consumer saturation.
- Athletes:Performance-oriented strains targeting gut permeability and recovery, with powder formats dominating for integration with nutrition protocols.
Adults command current volume; Athletes and Mental Health applications within this segment climb fastest.
Distribution Channel:
Channel selection determines margin structure, claim substantiation burden, and customer relationship depth.
- Online:Direct-to-consumer platforms bundle personalized microbiome testing with subscription-based regimens, capturing lifetime value through data infrastructure. British consumers consolidate purchasing decisions here, forcing traditional retailers to unbundle consultation from product margins.
- Supermarkets:Mass-market yogurt and beverage placement with compressed margins and limited strain differentiation. Ambient-stable capsule introductions are expanding shelf presence beyond traditional dairy cases.
- Health Stores:Concentrated in London and Manchester corridors, these networks provide premium positioning for specialized strains and practitioner-grade lines. Staff consultation justifies price premiums over supermarket alternatives.
- Pharmacies:Protexin Probiotics and similar specialists command premium positioning here, with MHRA borderline regulations complicating products approaching medicinal thresholds.
Supermarkets move the most units; Online captures the steepest expansion trajectory.
Application:
Clinical validation breadth and regulatory claim permissibility segment opportunity by therapeutic endpoint.
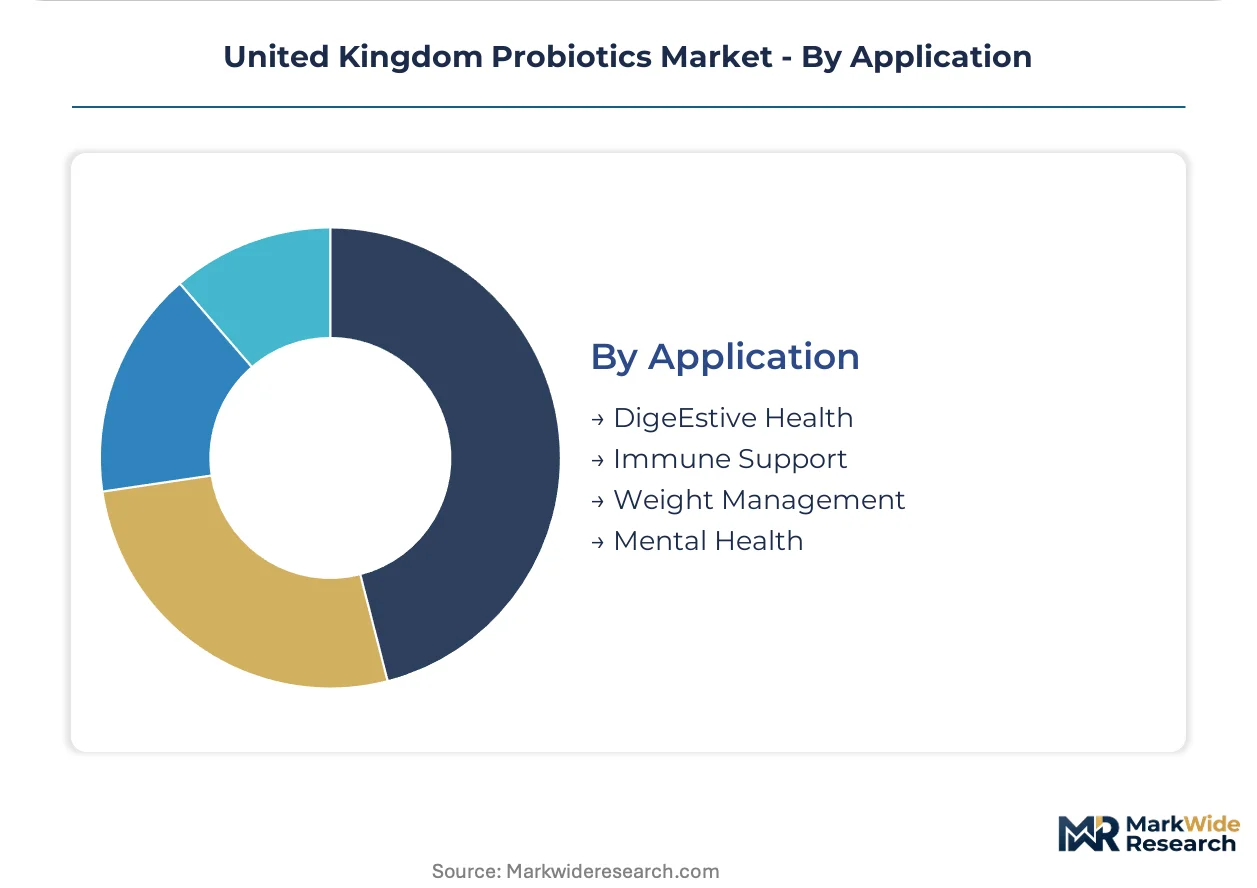
- Digestive Health:The most mature indication with established EFSA-style substantiation pathways, though commoditization pressures mount as strain differentiation narrows. Yogurt applications retain traditional food status that shields them from heaviest supplement compliance burdens.
- Immune Support:Seasonal demand patterns and pediatric positioning drive volume, with strain-specific mechanistic claims requiring costly clinical validation under tightening Advertising Standards Authority enforcement.
- Weight Management:Emerging evidence on microbiome-metabolic interactions attracts R&D investment, though regulatory precedent lags commercial positioning.
- Mental Health:Psychobiotic research redirects competitive investment fastest, with gut-brain axis mechanisms expanding addressable indications into anxiety and cognitive function. Clinical validation accumulates faster than FSA novel food approvals can accommodate.
Digestive Health anchors current revenue; Mental Health applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom consumes probiotics at levels exceeding domestic fermentation capacity, creating import dependency on Irish dairy processing and continental European strain suppliers. English metropolitan corridors absorb disproportionate volume while Scottish and Welsh markets develop distinct regulatory positioning under devolved health frameworks.
London and the Southeast
Health-conscious professionals drive psychobiotic demand for stress and sleep applications in the capital's subscription-based direct-to-consumer channels. The Advertising Standards Authority maintains its headquarters here, tightening enforcement on unsubstantiated gut-brain axis claims. Canary Wharf and Shoreditch host the densest concentration of microbiome testing startups bundling personalized regimens with probiotic subscriptions.
Midlands
Manufacturing heritage supports contract fermentation facilities serving pan-European probiotic ingredient supply. The Food Standards Agency's novel food consultation process creates particular friction for engineered strains developed at Birmingham and Nottingham university research parks. Leicester's halal-certified production lines capture British Muslim demographic demand for religiously compliant formulations.
North England
Manchester health store networks rival London's for premium probiotic SKU density per capita. Cold-chain infrastructure gaps disadvantage refrigerated beverage formats against shelf-stable capsules in Leeds and Sheffield distribution catchments. The Northern Powerhouse investment agenda has yet to materialize dedicated microbiome manufacturing capacity.
Scotland
Devolved health policy under NHS Scotland creates divergent procurement pathways for practitioner-grade lines in Edinburgh and Glasgow pharmacy networks. Traditional fermented dairy consumption patterns sustain yogurt demand despite ambient format encroachment. Strain research at Scottish universities feeds into local startup formation around psychobiotic applications.
Wales
Rural pharmacy access limitations push Welsh consumers toward online subscription platforms over health store consultation models. Cardiff's emerging biotech cluster explores microencapsulation applications for extended-stability formulations targeting export markets. Welsh Government food innovation grants support dairy-alternative probiotic development leveraging oat and hemp substrates.
United Kingdom Probiotics Market Competitive Landscape
The competitive structure tilts toward diversified food conglomerates with legacy dairy infrastructure. Nestlé SA and Groupe Danone leverage refrigerated distribution scale that specialist supplement manufacturers cannot replicate, while Yakult Honsha's dedicated cold-chain logistics anchor a defensible position in daily-consumption formats. Three archetypes dominate: multinational food corporations with probiotic line extensions, dedicated fermentation specialists with strain IP libraries, and direct-to-consumer platforms integrating microbiome testing. Consolidation pressure intensifies as ambient-stable microencapsulation technologies erode traditional format advantages and subscription models capture lifetime value from retail intermediaries.
Among diversified food conglomerates, Nestlé SA and Groupe Danone represent the infrastructure-heavy archetype, their UK dairy networks sustaining supermarket penetration that pure-play competitors cannot match. Yakult Honsha occupies a distinct position as a fermentation specialist with decades of daily-delivery logistics investment. Protexin Probiotics exemplifies the practitioner-channel strategy, commanding pharmacy premium positioning through clinician endorsement rather than mass-market advertising. OptiBac Probiotics Ltd. and BioGaia sit within the science-forward tier, their strain-specific clinical substantiation attempting to differentiate against commodity live-culture yogurts. PepsiCo Inc.'s presence signals beverage-format experimentation, while Lifeway Foods and Bio & Me represent challenger positioning in kefir and gut-health-focused segments respectively.
| Leading Market Players |
|---|
| Nestlé SA |
| Groupe Danone |
| Yakult Honsha |
| OptiBac Probiotics Ltd. |
| BioGaia |
| PepsiCo Inc. |
| Lifeway Foods |
| Bio & Me |
| Protexin Probiotics |
| Others |
Value Network & Pricing Analysis
Metropolitan health-conscious professionals in London and Manchester subscription channels anchor pricing power toward recurring revenue models that reward cold-chain bypass through microencapsulation investment. The Food Standards Agency's novel food consultation timeline extends payback periods for strain innovation, compressing returns on premium positioning.
Pricing Analysis
Margin tightening in practitioner-grade lines reflects MHRA borderline review costs and extended substantiation timelines. Three-tier pricing structure across premium pharmacy, standard health store, and economy supermarket tiers separates clinician-endorsed strains from mass-market yogurts. Cost-down pressure on ambient-stable capsules accelerates because Plastic Packaging Tax incentives reward refrigeration reduction. Direct-to-consumer subscribers show lowest price sensitivity; supermarket yogurt buyers exhibit highest.
Supply Chain Analysis
Regional distribution centers in the Midlands feed London and Manchester health store networks through hub-and-spoke patterns that disadvantage refrigerated beverages. Strain supply concentrates in Ireland, France, and the Netherlands; cryoprotectant inputs draw from German and Swiss pharmaceutical-grade suppliers. Single-source vulnerability sits with dedicated cold-chain logistics that Yakult Honsha controls. Distribution runs through supermarket dairy cases, pharmacy networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain-specific IP fragmentation and Food Standards Agency approval bottlenecks constrain capacity expansion, sustaining premium pricing for validated psychobiotic positioning.
For Market Incumbents: To counter ambient-stable capsule entrants eroding refrigerated yogurt advantages, Nestlé SA and Groupe Danone should deepen backward integration into microencapsulation capacity and secure exclusive pharmacy distribution through clinician education programs. For New Entrants and Emerging Players: Microbiome testing bundling offers the clearest technology-first wedge, targeting underpenetrated mental health applications in Welsh and Scottish online channels where health store access remains limited. For Investors and Strategic Acquirers: Distressed-cycle entries favor practitioner-channel specialists with FSA novel food approvals already in hand, particularly those anchored in Edinburgh and Glasgow pharmacy networks under NHS Scotland procurement pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Divestment | Plastic Packaging Tax alignment accelerates ambient format adoption across English retail corridors. |
| Psychobiotic Clinical Trial Investment | Gut-brain axis substantiation opens MHRA borderline positioning for anxiety and sleep endpoints. |
| Practitioner Channel Acquisition | Pharmacy network control captures premium pricing unavailable through supermarket penetration. |
| Microbiome Testing Platform Integration | Subscription bundling concentrates lifetime value capture away from traditional health store intermediaries. |
| Halal-Certified Production Line Expansion | Leicester facility capacity captures British Muslim demographic demand for religiously compliant formulations. |
Research Methodology
Independent corroboration across fermentation facility operators, pharmacy procurement managers, and Advertising Standards Authority enforcement officers underwrites the qualitative findings. Primary fieldwork with health store category buyers in London and Manchester combined with secondary validation from FSA novel food consultation records, MHRA borderline classification databases, and Nielsen retail audit data. Bottom-up strain volume estimates and top-down market sizing triangulate through cross-reference.
Rate-of-change decomposition separates volume growth from mix shift and pricing evolution across the analysis window. Segmentation dimensions modeled include product format stability tier, end-user life stage, distribution channel margin structure, and application endpoint regulatory permissibility. CAGRs derive from historical trajectory analysis adjusted for Food Standards Agency consultation timeline impacts and psychobiotic clinical validation velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA-style substantiation adoption or cold-chain infrastructure disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market