
 Synbiotic Product Market | 2026-2036
Synbiotic Product Market Size, Share, and Industry Trends Forecast 2026-2036
Synbiotic Product Market Intelligence
China is reshaping synbiotic manufacturing capacity through state-backed biotech parks in Jiangsu and Zhejiang provinces. Pfizer Inc. leverages its pharmaceutical distribution network to position synbiotic capsules within clinician-recommended channels. Danone S.A. anchors its competitive stance through fermented dairy integration with live culture supply chains. Kerry Group plc specializes in customized synbiotic blends for functional food and beverage clients across Asia-Pacific.
Synbiotic products combine live probiotic microorganisms with prebiotic substrates that selectively nourish beneficial gut flora, typically formulated to deliver colony-forming units alongside fermentable fibers such as inulin or galactooligosaccharides. The primary commercial purpose centers on modulating host microbiome composition to support digestive function, immune response, and nutrient bioavailability. Capsules and powders command the formulation landscape due to shelf stability and dosing precision, while combined probiotic and prebiotic formulations capture expanding margin pools as consumers seek single-product convenience. Health-conscious consumers and seniors represent the most structurally important end-user clusters, with pharmacies and online retail channels distributing the bulk of volume.
EFSA novel food assessments and EMA borderline classification discussions determine whether synbiotic products register as foods, supplements, or medicinal items across European markets. China's NMPA and SAMR enforce GB standards for probiotic strain identification and prebiotic purity thresholds, while the FDA in the United States exercises jurisdiction through dietary supplement GMPs and GRAS notifications for new prebiotic ingredients. Stakeholders must monitor evolving strain-specific health claim authorization pathways, as regulatory clarity on microbiome-targeted benefits will determine which product categories achieve premium positioning versus commodity status.
Market Dynamics
Strain-specific health claim authorization pathways are fragmenting competitive positioning across developed markets, as regulators in Europe and Asia-Pacific impose divergent evidentiary standards for microbiome-targeted benefits.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined safety assessments for synbiotic ingredients are accelerating product registration timelines for infant nutrition applications across EU member states.
- Geriatric Gut Health Demand:Aging populations in Japan and Germany are driving clinician-recommended synbiotic adoption for immune modulation and nutrient absorption support.
- Fermentation Infrastructure Expansion:State-backed biotech parks in Jiangsu province are concentrating live culture manufacturing capacity with integrated prebiotic substrate supply.
Market Restraints
- Prebiotic Input Volatility:Inulin and galactooligosaccharide prices fluctuate with chicory root harvest cycles and dairy whey availability, compressing margin predictability for blend manufacturers.
- Strain Banking Concentration:Commercial probiotic strain deposits cluster within three European culture collections, creating licensing bottleneck risks for new market entrants.
- Stability-Temperature Tradeoffs:Viability loss in ambient distribution chains limits capsule formulation shelf life, constraining pharmacy channel penetration in tropical climates.
Strategic Opportunities
- Pediatric Formulation White Space:Dropper-delivery synbiotics for infants remain underdeveloped in North American markets, presenting first-mover potential beyond powder and capsule formats.
- China SAMR Strain Approval:Expanded GB standards recognition for imported probiotic strains is opening distribution pathways through cross-border e-commerce channels.
- Personalized Microbiome Testing Integration:At-home gut health diagnostics are converging with subscription-based synbiotic regimens, enabling outcome-linked retention models in direct-to-consumer segments.
Industry Challenges
- Multi-Jurisdiction Labeling Complexity:Divergent prebiotic fiber definitions between FDA dietary supplement rules and EFSA novel food categories force SKU proliferation for international brands.
- Live Culture Cold Chain Integrity:Temperature excursion monitoring and last-mile refrigeration requirements inflate logistics costs for pharmacy and clinic distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synbiotic Product Market |
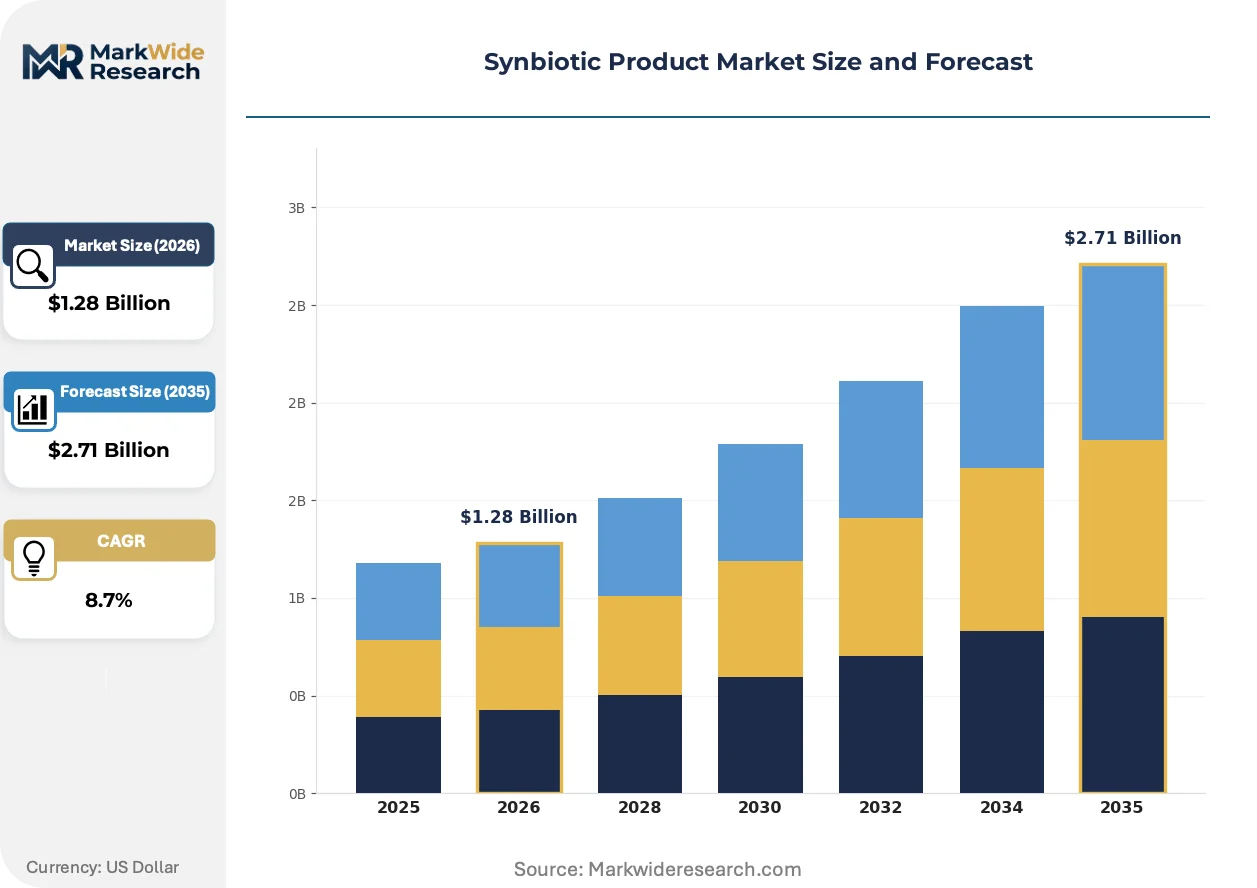
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.71 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquids End User: Health-Conscious Consumers, Athletes, Seniors, Children Formulation: Probiotic-Only, Prebiotic-Only, Combined Probiotic & Prebiotic, Customized Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Pfizer Inc., Probiotical S.p.A., Danone S.A., Probi AB, Lallemand Inc., Yakult Honsha Co. Ltd., Sabinsa Corporation, Kerry Group plc, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synbiotic Product Market Strategic Shifts & Innovations
Digital strain characterization and AI-guided formulation design are compressing development cycles, while regulatory science investments reshape how manufacturers validate microbiome-targeted claims.
Next-generation sequencing platforms are virtualizing traditional culture-based strain identification workflows. Contract research organizations in Denmark and Singapore are adopting metagenomic screening to accelerate safety dossier compilation for novel probiotic candidates. This technology is virtualizing the multi-year strain validation timelines that previously constrained product pipeline velocity.
EFSA's evolving guidance on microbiome health claims is forcing evidentiary upgrades across European synbiotic portfolios. Manufacturers must now submit human intervention trial data for digestive and immune benefit assertions, displacing in vitro and animal model submissions. Powder formulations targeting German and French pharmacy channels face the steepest compliance cost adjustments.
Clinician-recommended dispensing is displacing self-directed retail purchasing in premium synbiotic segments. Pediatricians and gastroenterologists in Japan and South Korea are anchoring prescription-adjacent recommendation protocols, shifting volume toward medical channel distributors. This behavioral pivot is most visible in fermented dairy-integrated formats positioned for post-antibiotic recovery applications.
Synbiotic Product Market Segmentation
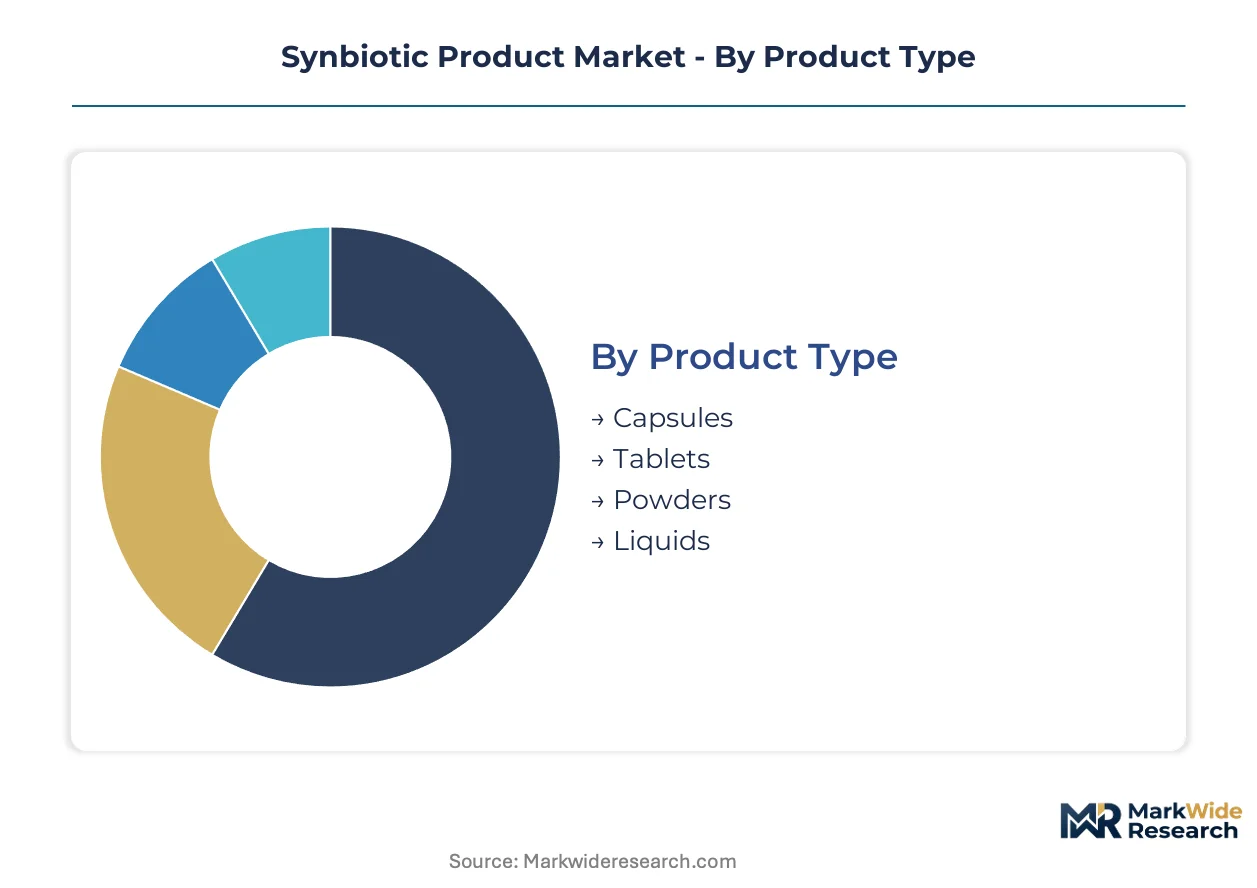
Segmentation in synbiotic products determines formulation stability requirements, cold chain infrastructure investments, and regulatory pathway selection. Manufacturers align production configurations with specific delivery formats and end-user microbiome needs rather than pursuing undifferentiated scale.
Product Type:
After-sales service intensity varies sharply across delivery formats, with powders requiring formulation guidance and capsules demanding stability troubleshooting through distribution partners.
- Powders:Bulk formulations combine live cultures with prebiotic substrates in sachet or jar formats, enabling flexible dosing and beverage integration. Demand concentrates in China where domestic dairy brands reformulate gut-health lines, driven by state-backed biotech park capacity expansion in Jiangsu and Zhejiang provinces.
- Capsules:Hard-shell and enteric-coated variants protect probiotic viability through gastric transit, typically standardized to deliver precise colony-forming units per dose. German infant nutrition manufacturers expand procurement under EFSA novel food guidelines, prioritizing shelf-stable formats for pharmacy channel penetration.
- Tablets:Compressed formulations with binders and disintegrants suit cost-sensitive retail segments requiring ambient distribution.
- Liquids:Ready-to-drink suspensions and dropper formats target pediatric and geriatric consumers with swallowing difficulties.
By volume, powders lead. By growth pace, capsules are ahead.
End User:
Cost tier stratification separates premium clinician-recommended regimens from mass-market self-directed purchasing across user categories.
- Seniors:Aging populations in Japan and Germany drive clinician-recommended adoption for immune modulation and nutrient absorption support, with gastroenterologists anchoring prescription-adjacent protocols.
- Health-Conscious Consumers:Self-directed purchasers seeking single-product convenience favor combined probiotic-prebiotic formats through online retail and specialty store channels.
- Children:Pediatric applications remain underdeveloped in North American markets, with dropper-delivery formats presenting first-mover potential beyond established powder and capsule presentations.
- Athletes:Performance-oriented microbiome modulation targets gut permeability and nutrient timing for training recovery applications.
Health-conscious consumers dominate transaction volume. Seniors exhibit steepest expansion trajectory as healthcare systems integrate microbiome interventions.
Formulation:
Application specificity determines whether manufacturers pursue commodity prebiotic blending or strain-customized premium positioning.
- Combined Probiotic & Prebiotic:Single-product formats capture expanding margin pools as consumers seek convenience, with Kerry Group specializing in customized blends for Asia-Pacific functional food and beverage clients.
- Customized:Strain-specific and substrate-matched formulations respond to at-home microbiome testing integration, enabling subscription-based retention models.
- Probiotic-Only:Live culture concentrates require refrigerated distribution and shorter shelf life management.
- Prebiotic-Only:Fermentable fiber isolates such as inulin or galactooligosaccharides face input volatility tied to chicory root harvest cycles.
Combined formulations command premium positioning. Customized blends are expanding most quickly through direct-to-consumer diagnostic integration.
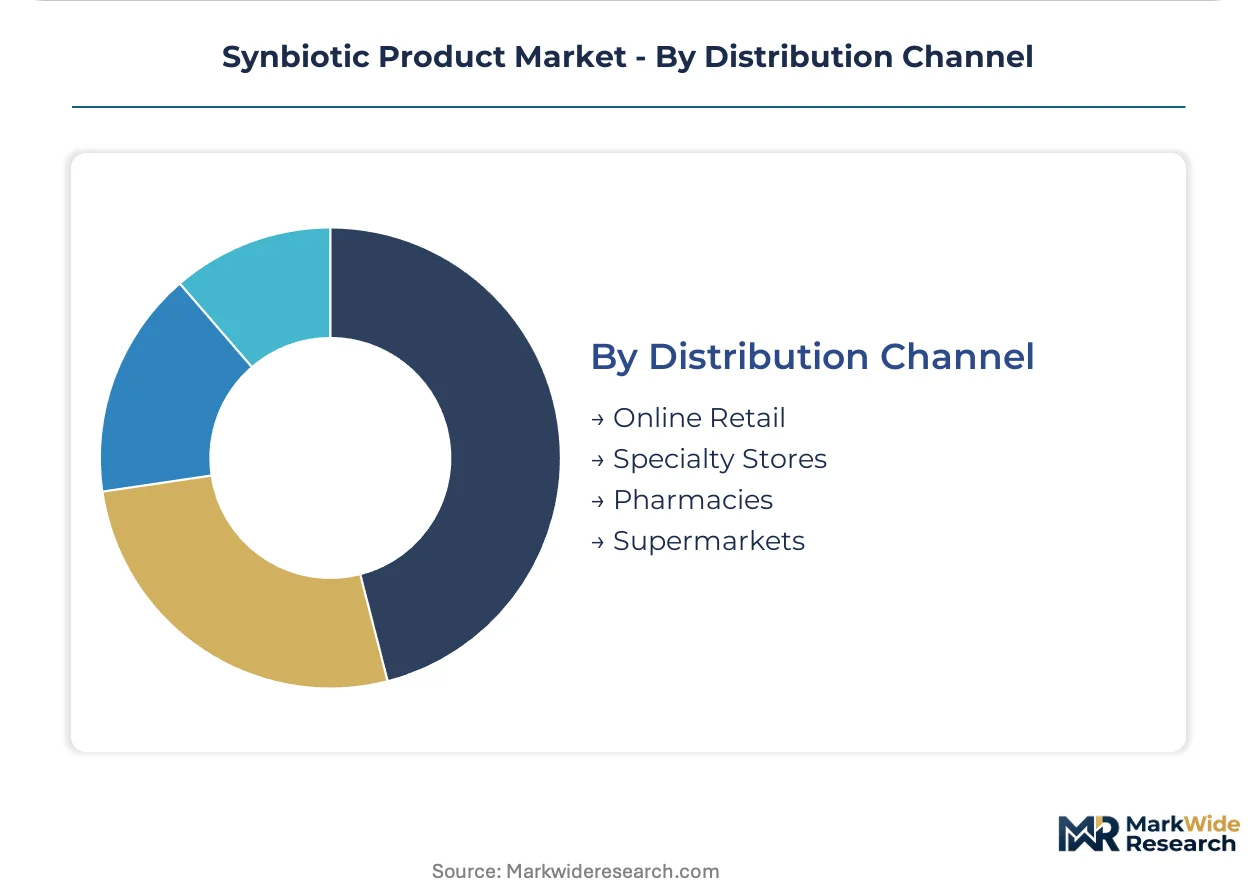
Distribution Channel:
Volume concentration in pharmacy and online channels reflects divergent cold chain requirements and consumer education needs.
- Pharmacies:Clinician-recommended dispensing displaces self-directed purchasing in premium segments, with medical channel distributors capturing volume in Japan and South Korea through fermented dairy-integrated formats.
- Online Retail:Cross-border e-commerce channels open distribution pathways as China's SAMR expands GB standards recognition for imported probiotic strains.
- Specialty Stores:Health food and nutrition retailers provide formulation guidance for complex multi-strain products.
- Supermarkets:Mass retail placement suits shelf-stable formats with simplified health positioning and lower price points.
Online retail leads by transaction volume. Pharmacies gain share fastest through medical channel integration and post-antibiotic recovery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments anchor European synbiotic registration pathways, while China's SAMR and NMPA enforce GB standards that determine strain-specific market access. National regulators across Germany, China, Japan, the United States, and South Korea shape divergent compliance costs and distribution channel structures.
Germany
Infant nutrition manufacturers expand synbiotic procurement under EFSA streamlined safety assessments for novel food ingredients. German regulators prioritize human intervention trial data for digestive and immune benefit assertions, displacing older in vitro submissions. Bavaria-based pharmaceutical distributors leverage clinician-recommended channels to position pharmacy-grade capsules for post-antibiotic recovery applications.
China
Domestic dairy brands reformulate gut-health product lines as state-backed biotech parks in Jiangsu and Zhejiang provinces concentrate live culture manufacturing capacity. SAMR expanded GB standards recognition for imported probiotic strains, opening cross-border e-commerce distribution pathways. Powder formulations dominate consumer demand through integrated prebiotic substrate supply chains.
Japan
Aging populations drive clinician-recommended synbiotic adoption for immune modulation and nutrient absorption support. METI guidelines influence fermented dairy-integrated format positioning through medical channel distributors. Pediatricians and gastroenterologists in Tokyo-Osaka corridors anchor prescription-adjacent recommendation protocols.
United States
FDA dietary supplement GMPs and GRAS notifications govern new prebiotic ingredient market entry, creating evidentiary requirements distinct from European novel food pathways. Health-conscious consumers favor combined probiotic-prebiotic formats through online retail channels. Direct-to-consumer segments experiment with subscription-based regimens linked to at-home microbiome testing.
South Korea
MFDS regulations shape strain-specific health claim authorization for fermented dairy-integrated synbiotics positioned for digestive health. Seoul-based medical channel distributors capture volume through clinician-recommended dispensing models. Pharmacy networks in the capital region prioritize shelf-stable capsule formulations with enteric-coated protection.
Synbiotic Product Market Key Industry Players
Pharmaceutical-origin multinationals and specialized fermentation houses split the market into divergent capability tiers. Consolidation concentrates around strain banking assets and cold chain distribution infrastructure. Three archetypes dominate: diversified healthcare conglomerates with pharmacy channel access, dedicated probiotic culture suppliers with strain collection depth, and functional ingredient blenders serving food and beverage clients. Competitive moves center on regulatory science investments for health claim authorization and backward integration into live culture manufacturing capacity.
Among diversified healthcare conglomerates, Pfizer Inc. and Danone S.A. exemplify the pharmaceutical-dairy hybrid model that leverages clinician networks and fermented product integration. Kerry Group plc occupies a position within the functional ingredient blending tier, supplying customized synbiotic formulations to Asia-Pacific food and beverage manufacturers. These three entities represent distinct strategic postures: pharmacy-channel pharmaceutical distribution, fermented dairy live culture supply chains, and customized blend manufacturing for industrial clients.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Probiotical S.p.A. |
| Danone S.A. |
| Probi AB |
| Lallemand Inc. |
| Yakult Honsha Co. Ltd. |
| Sabinsa Corporation |
| Kerry Group plc |
| Nestlé S.A. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Jiangsu province biotech parks is compressing live culture manufacturing margins while simultaneously enabling aggressive pricing postures among domestic Chinese suppliers seeking export market share.
Pricing Analysis
Geographic price spreads between German pharmacy-grade capsules and Chinese domestic powders reflect divergent regulatory compliance burdens and cold chain infrastructure investments. Three-tier pricing structure across premium clinician-recommended, standard retail, and economy bulk segments anchors the market. Pricing pressure stems from inulin and galactooligosaccharide input volatility tied to chicory root harvest cycles. Health-conscious consumers through online channels exhibit highest price sensitivity, while geriatric segments in Japan and Germany show lowest elasticity due to clinician endorsement.
Supply Chain Analysis
Export control regimes on precision fermentation equipment from EU member states and the United States constrain live culture manufacturing capacity expansion in emerging markets. Supply concentrates in China, Germany, and Denmark, with Jiangsu province biotech parks, Bavarian pharmaceutical distributors, and Danish contract research organizations anchoring regional networks. Raw material dependencies center on chicory root inulin, dairy-derived galactooligosaccharides, and cryopreserved strain deposits from European culture collections. Single-source vulnerability around strain banking licensing creates bottleneck risk. Distribution runs through pharmacy networks requiring cold chain integrity, online retail platforms, and medical channel distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
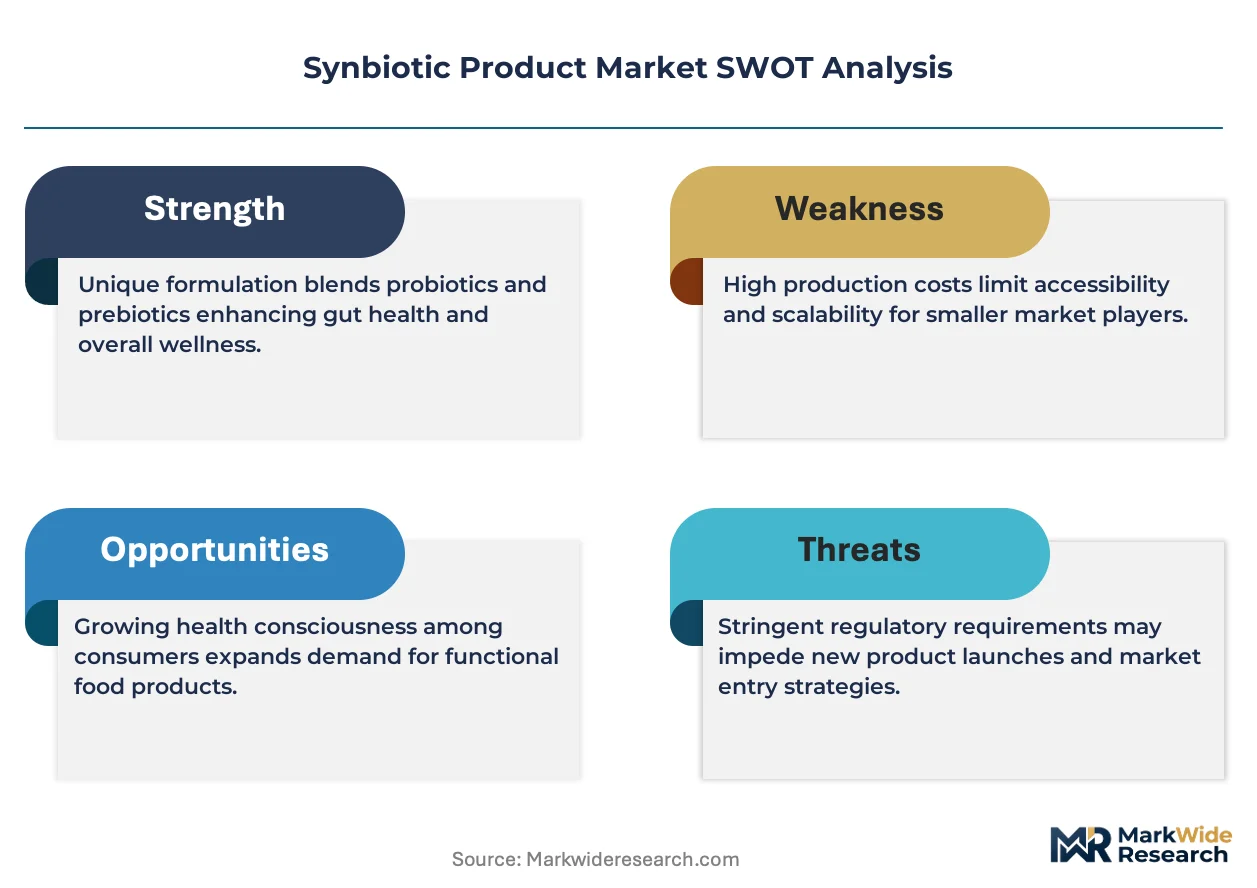
Live culture strain banking assets and regulatory science capabilities for microbiome health claim authorization represent the scarcest competitive resources in this market, separating consolidated players from commodity blenders.
For Market Incumbents: Entrench position through backward integration into captive strain collection assets and expanded GB standards recognition investment for China SAMR pathway access. Emerging Asian fermentation houses threaten licensing revenue streams; priority lever rests on cold chain distribution infrastructure lock-in with pharmacy networks. For New Entrants and Emerging Players: Dropper-delivery pediatric formulations for North American markets represent the most penetrable entry point given underdeveloped competitive presence beyond powder and capsule formats. Target subscription-based personalized microbiome testing integration as go-to-market anchor for direct-to-consumer retention models. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory moat play because strain-specific health claim authorization pathways determine premium positioning versus commodity status. Acquisition targets should exhibit demonstrated EFSA novel food dossier success or SAMR GB standards approval track records. Signal to watch is clinician recommendation protocol adoption rates in Japan and South Korea medical channels.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Science Investment | Human intervention trial data for EFSA microbiome claims displaces older in vitro submissions. |
| Strain Banking Acquisition | Commercial probiotic deposits cluster within three European culture collections. |
| Cold Chain Infrastructure Expansion | Temperature excursion monitoring requirements inflate pharmacy distribution costs. |
| Pediatric Formulation Development | Dropper-delivery formats remain underdeveloped in North American markets. |
| Personalized Testing Integration | At-home gut health diagnostics converge with subscription synbiotic regimens. |
Research Approach
Desk research of EFSA novel food guidance documents, SAMR GB standards filings, and fermentation industry trade publications preceded structured interviews with regulatory affairs directors at probiotic manufacturers, strain collection curators at European culture banks, pharmacy channel distributors in Germany and Japan, and functional food R&D heads at Asia-Pacific ingredient suppliers. Secondary validation drew from NMPA strain approval databases, customs import records for prebiotic substrates, and hospital procurement data for clinician-recommended products. Bottom-up volume estimates triangulated against top-down market sizing.
Assumptions held fixed include EFSA's evidentiary standards trajectory for microbiome health claims and SAMR's GB standards recognition pace for imported strains, while variables included chicory root harvest yields and cold chain infrastructure investment rates across tropical markets. Segmentation modeling spanned delivery format, end-user demographic, formulation type, and distribution channel dimensions. CAGRs derived from growth driver elasticity analysis against baseline penetration rates, with strain approval timelines and pharmacy channel expansion rates as key forecast inputs.
Stress conditions across prebiotic input price volatility bands, regulatory pathway delay scenarios, and cold chain failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; accelerated EFSA guidance revision or SAMR policy shifts could materially revise projections. Cross-checking against hospital procurement database trends and pharmacy inventory turnover metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Global Liquid Feed Supplements Market