
 Single-Strain Probiotics Market | 2026-2036
Single-Strain Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Strain Probiotics Market Analytics
European fermentation capacity is restructuring as dedicated probiotic facilities replace multi-purpose dairy plants. Chr. Hansen leverages its culture collection depth to dominate high-potency medical probiotic supply. Danone sustains brand loyalty through refrigerated distribution networks that protect live-cell viability. Novonesis anchors industrial-scale production with precision fermentation platforms optimized for Lactobacillus and Bifidobacterium strains.
Single-strain probiotics contain isolated, taxonomically defined microbial cultures—typically 10^8 to 10^11 colony-forming units per dose—formulated without competing strains to enable targeted mechanistic claims and reproducible clinical outcomes. These products serve therapeutic, preventive, and performance-enhancement purposes across human and animal health sectors. Capsule formats command the largest margin pool due to stability advantages and physician channel preference, while gummies represent the fastest-growing delivery format as adult consumers reject pill fatigue. Gut health applications retain volume leadership, though immune support positioning is displacing general wellness claims as the primary purchase trigger.
FDA GRAS notifications and EFSA health claim authorizations shape market access by determining which strain-specific benefits manufacturers may communicate to consumers. The EU F-Gas Regulation and REACH frameworks constrain solvent use in downstream extraction processes, elevating compliance costs for European producers. Stakeholders must monitor evolving strain-level QPS list updates from EFSA and novel food consultation pathways, as these regulatory gatekeepers increasingly demand whole-genome sequencing data before market clearance.
Market Dynamics
Strain-specific genomic screening is compressing product development timelines from years to months, forcing manufacturers to rebuild R&D workflows around rapid phenotyping and whole-genome sequencing validation pipelines.
Growth Catalysts
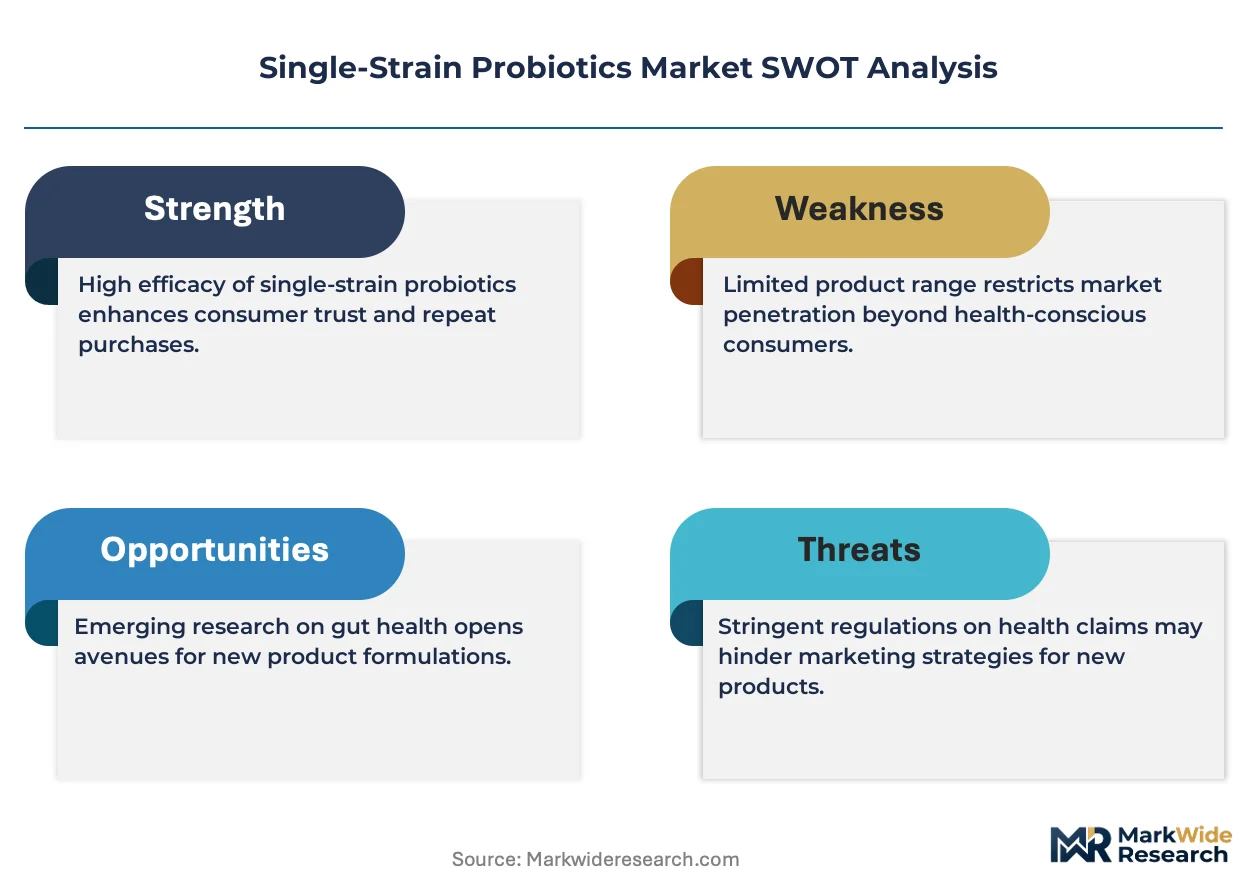
- EFSA QPS List Expansion:The European Food Safety Authority's quarterly updates to the Qualified Presumption of Safety list accelerate strain clearance for novel Lactobacillus and Bifidobacterium isolates, reducing regulatory uncertainty for European launch timelines.
- Direct-to-Consumer Channel Maturation:Subscription-based probiotic brands in the United States bypass traditional retail slotting fees, capturing higher margins while building longitudinal consumer health data repositories that inform formulation iterations.
- Precision Fermentation Infrastructure:Dedicated bioreactor facilities optimized for single-strain anaerobic culture achieve cell densities exceeding 10^11 CFU per milliliter, enabling medical-grade potency at industrial scale.
Market Restraints
- Live-Cell Cold Chain Dependency:Refrigerated distribution from fermentation facility to retail shelf adds 15-25% to logistics costs compared to shelf-stable alternatives, compressing margin pools for mid-tier brands.
- Strain Patent Thickets:Dense intellectual property landscapes around well-characterized probiotic genomes limit freedom to operate for new entrants, particularly for Bifidobacterium longum and Lactobacillus rhamnosus lineages.
- EU F-Gas Solvent Constraints:The EU F-Gas Regulation restricts hydrofluorocarbon use in downstream extraction and drying processes, elevating capital expenditure requirements for European manufacturing sites.
Strategic Opportunities
- Companion Animal Microbiome:Veterinary applications for single-strain formulations in canine and feline digestive health remain underdeveloped relative to human markets, with pet insurance reimbursement creating pull-through demand.
- India PLI Scheme Alignment:India's Production Linked Incentive scheme for pharmaceutical and biotechnology manufacturing offers cost offsets for fermentation capacity investments serving domestic and export markets.
- Metabolomics-Enabled Claims:Integration of untargeted metabolomics with clinical trial design enables mechanistic benefit attribution to specific strain-secreted compounds, differentiating premium positioning from commodity probiotics.
Industry Challenges
- Genomic Taxonomist Shortage:The intersection of microbial genomics, bioinformatics pipeline management, and regulatory documentation requires hybrid skill sets that command premium compensation and extend hiring timelines.
- Multi-Site cGMP Harmonization:Manufacturers operating fermentation facilities across jurisdictions must reconcile divergent FDA, EMA, and national inspectorate expectations for environmental monitoring and batch release protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Strain Probiotics Market |
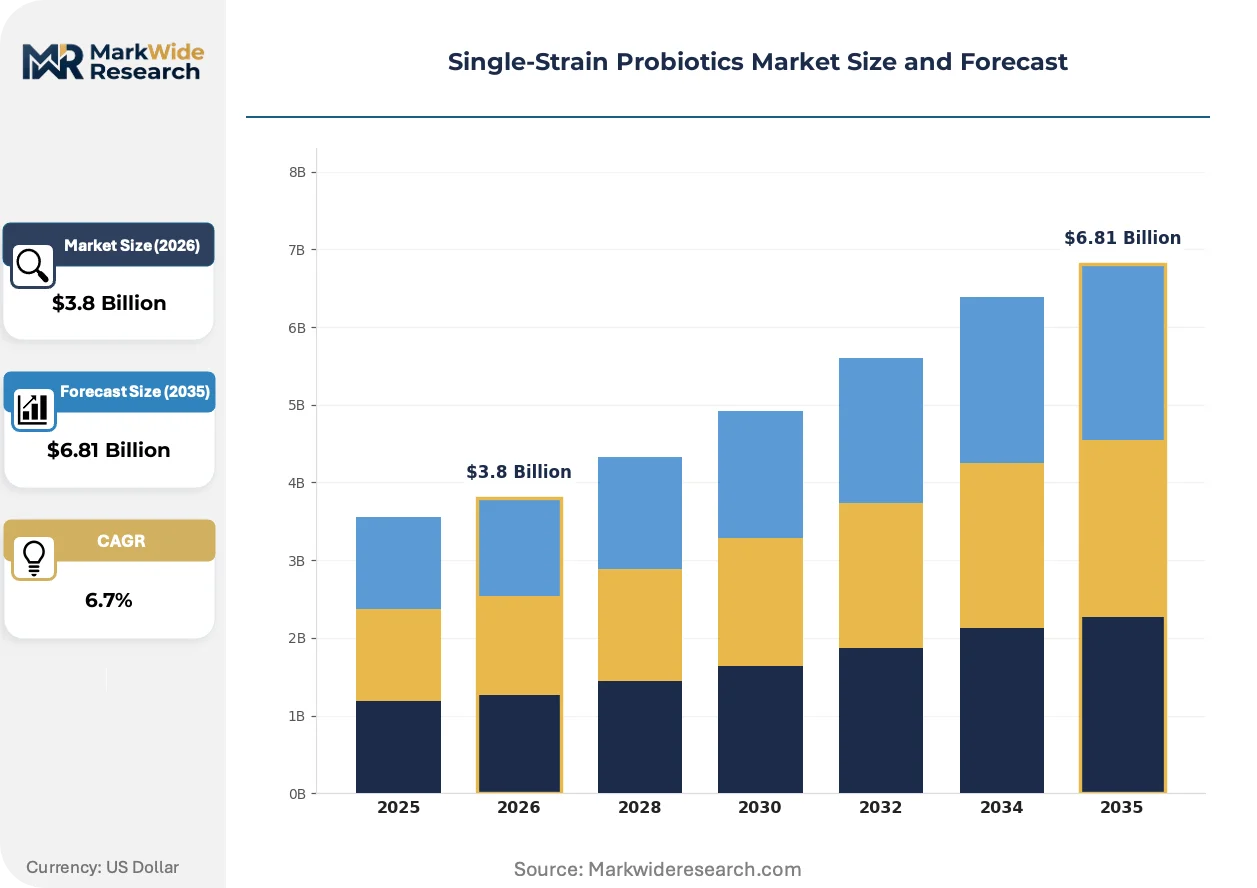
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquids, Gummies Application: Gut Health, Immune Support, Skin Care, Mood Enhancement End User: Adults, Children, Seniors, Pets Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Chr. Hansen, Danone, Nestlé Health Science, Yakult Honsha, BioGaia, DuPont, Novonesis, Lallemand, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Strain Probiotics Market Evolving Landscape
Automation and analytical depth are converging to transform how single-strain probiotics are characterized, manufactured, and brought to market, with regulatory frameworks racing to keep pace with technical capabilities.
Whole-genome sequencing paired with artificial intelligence-driven phenotype prediction is automating strain selection workflows that previously required months of empirical screening. Contract research organizations serving functional food manufacturers now deploy automated colony pickers and high-throughput fermentation mini-bioreactors that compress lead identification from 90 days to under three weeks. This acceleration is compressing competitive moats for incumbents with legacy culture collections, as smaller entrants access equivalent screening velocity through platform partnerships.
EFSA's novel food consultation pathway now mandates whole-genome sequencing data for all new probiotic strain submissions, creating a documentation burden that favors well-capitalized players with in-house sequencing infrastructure. The industrial consequence is a bifurcation between European manufacturers who have integrated sequencing into quality control workflows and those reliant on third-party providers facing extended turnaround times. Medical probiotic applications face the steepest compliance escalation, as strain-level safety dossiers must now address horizontal gene transfer risks and antimicrobial resistance profiling.
Physician channel preference for capsule formats with documented live-cell stability through expiration is displacing general wellness positioning as the primary purchase trigger among educated consumers. Functional food manufacturers respond by commissioning accelerated stability studies at 25°C and 40°C conditions, publishing results in peer-reviewed journals to support clinical credibility claims. This certification-driven preference shift is most visible in the United States, where direct-to-consumer brands now compete for formulary inclusion with medical food distributors serving gastroenterology practices.
Single-Strain Probiotics Market Segmentation
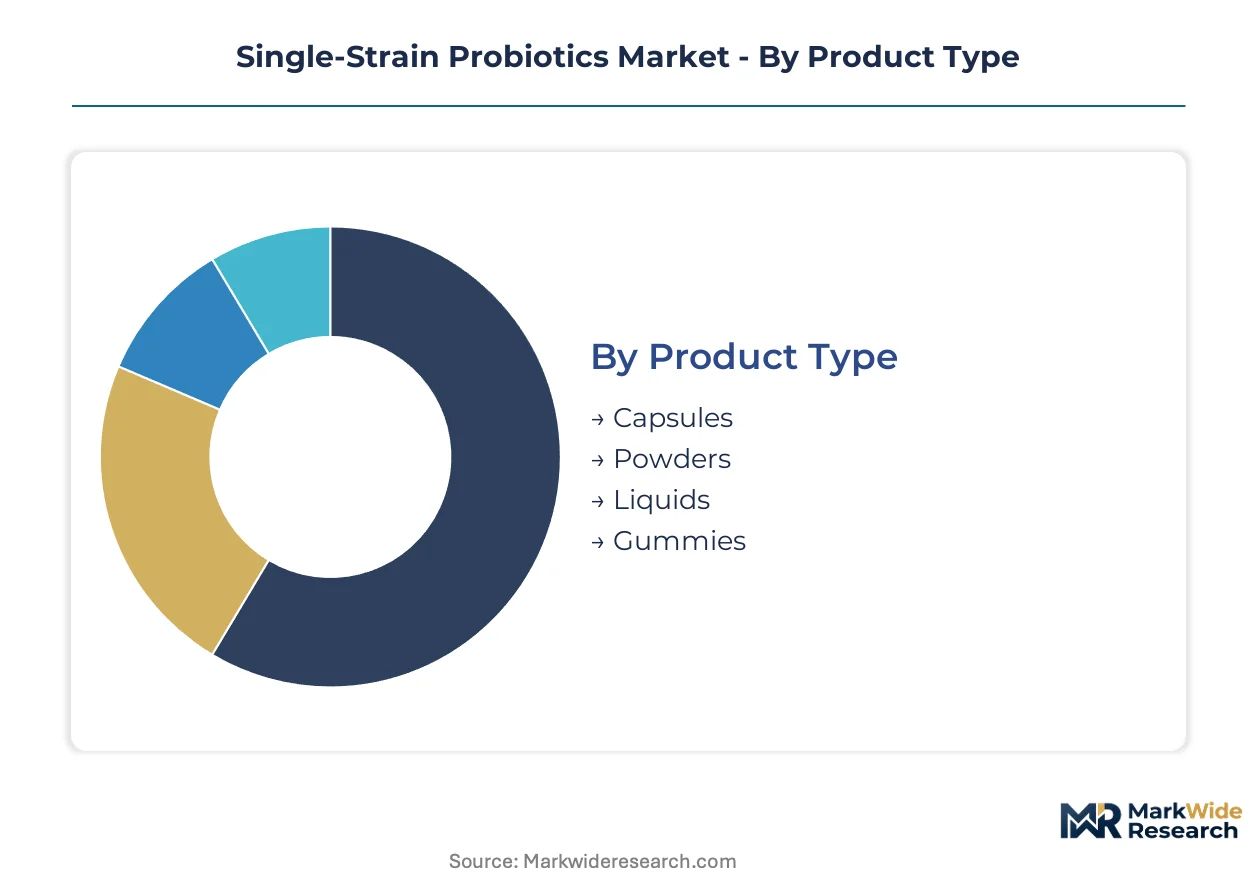
Strain-specific formulation requirements and cold-chain logistics create distinct competitive arenas across delivery formats and consumer segments. Manufacturers align R&D investments with channel-specific margin structures and regulatory pathway complexity.
Product Type:
Purchase decisions pivot on shelf-stability requirements and physician channel credibility rather than price alone.
- Capsules:Enteric-coated gelatin or vegetable cellulose shells protect Lactobacillus and Bifidobacterium strains from gastric acid degradation. Physician formulary preference in the United States concentrates demand here, with brands commissioning accelerated stability studies at 25°C and 40°C to support clinical credibility claims.
- Gummies:Pectin-based matrices with low water activity enable ambient distribution while masking microbial fermentation notes with fruit flavors. Adult consumers rejecting pill fatigue in direct-to-consumer channels are expanding this segment most quickly, though heat-sensitive strain viability limits potency claims.
- Powders:Lyophilized cultures in sachet or bulk formats suit functional food integration and infant formula applications. The format sacrifices convenience for dosing flexibility and cost efficiency in institutional channels.
- Liquids:Aqueous suspensions with cryoprotectant additives serve veterinary and pediatric niches where swallowing capacity is constrained. Refrigerated distribution dependency compresses margin pools outside cold-chain infrastructure dense regions.
Volume sits with capsules; growth tilts toward gummies.
Application:
Mechanistic claim substantiation costs determine which benefit areas attract venture-backed entrants versus legacy nutrition players.
- Gut Health:Irritable bowel syndrome and antibiotic-associated diarrhea indications command the largest clinical trial investment, with EFSA health claim authorizations and FDA medical food designations shaping market access. Strain-specific mechanistic dossiers for L. rhamnosus GG and B. animalis subsp. lactis BB-12 anchor premium positioning.
- Immune Support:Respiratory infection risk reduction claims require seasonal trial design and pediatric cohort recruitment. The application is gaining share fastest as post-pandemic consumers prioritize preventive positioning over general wellness.
- Skin Care:Topical and oral probiotic formulations targeting atopic dermatitis and acne vulgaris leverage gut-skin axis research, though cosmetic regulation pathways differ sharply from food supplement frameworks.
- Mood Enhancement:Psychobiotic claims linking specific strains to cortisol modulation and anxiety scores remain preliminary, with most products positioned as wellness rather than therapeutic.
Revenue concentrates in gut health; immune support climbs the fastest.
End User:
Age-stratified microbiome development stages and reimbursement access create divergent go-to-market economics.
- Adults:Working-age consumers with discretionary health spending drive subscription model adoption and premium strain positioning. Direct-to-consumer brands in the United States capture longitudinal health data to inform formulation iterations.
- Seniors:Immunosenescence and polypharmacy interactions elevate medical-grade potency requirements and physician channel dependency. Medicare Advantage supplemental benefit coverage is expanding access.
- Children:Pediatric indication trials face ethical review complexity and placebo response variability, limiting strain-specific claims to established isolates with multi-year safety records.
- Pets:Canine and feline digestive health applications remain underdeveloped relative to human markets, with pet insurance reimbursement creating pull-through demand for veterinary-exclusive formulations.
Adults anchor volume; seniors offer steepest expansion trajectory.
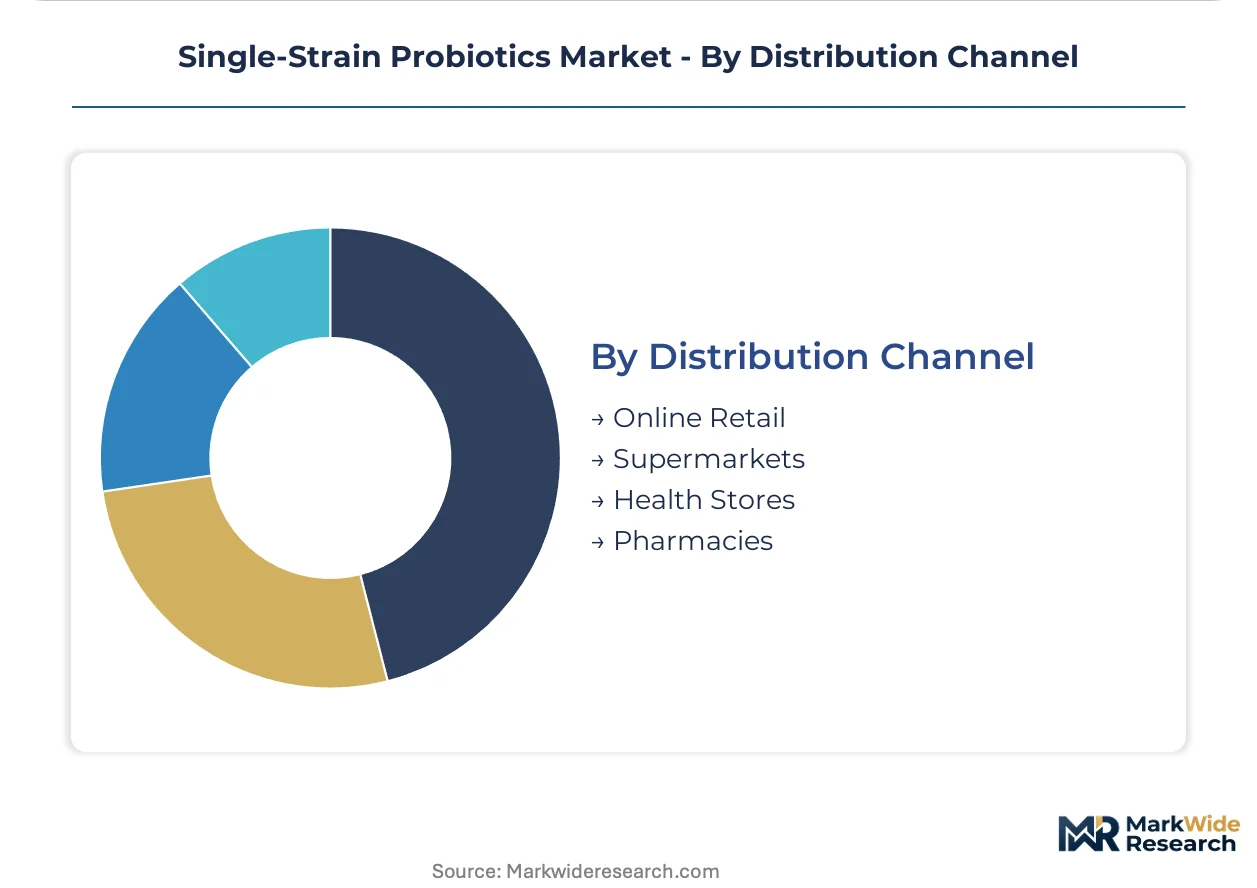
Distribution Channel:
Cold-chain capability and slotting fee structures determine which channels sustain live-cell viability claims.
- Online Retail:Subscription-based brands bypass traditional retail slotting fees, capturing higher margins while building consumer health data repositories. Refrigerated last-mile logistics partnerships protect viability claims.
- Pharmacies:Behind-the-counter positioning and pharmacist recommendation dependence suit medical-grade potency products with documented stability through expiration. Chain formulary inclusion requires accelerated stability certification.
- Supermarkets:Mass-market refrigerated sets face temperature excursion risks and shorter shelf turnover, favoring shelf-stable or lower-potency formulations with extended dating.
- Health Stores:Educated consumer base and trained staff enable premium strain storytelling, though limited cold-chain infrastructure constrains live-cell product assortment depth.
Pharmacies dominate medical-grade volume; online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation feedstock supply chains anchor geographic production concentration for single-strain probiotics, with dairy-derived substrates and precision fermentation media sourcing dictating facility siting decisions across major manufacturing clusters.
United States
Direct-to-consumer subscription brands and refrigerated pharmacy distribution networks drive strain-specific demand. FDA GRAS notification pathways and medical food designations shape regulatory access for high-potency formulations. The Greater Boston corridor hosts contract research organizations deploying automated colony pickers and mini-bioreactors that compress strain screening timelines.
Germany
Industrial biotechnology infrastructure and dedicated anaerobic fermentation facilities support medical-grade probiotic supply. EFSA QPS list compliance and REACH solvent constraints elevate documentation burdens for European market entry. The Baden-Württemberg cluster concentrates precision fermentation platforms optimized for Lactobacillus and Bifidobacterium strain production.
India
Domestic pharmaceutical fermentation capacity and export-oriented manufacturing investments expand strain production scale. The Production Linked Incentive scheme for biotechnology manufacturing offers cost offsets for fermentation infrastructure investments. Maharashtra and Gujarat host contract manufacturing organizations building cGMP-compliant facilities serving European and North American markets.
Japan
Long-established fermented food consumption patterns and aging demographics sustain medical probiotic demand. PMDA consultation pathways and FOSHU health claim frameworks require extensive clinical dossiers for strain-specific benefits. The Kanto region maintains culture collection depth and automated quality control workflows for pharmaceutical-grade supply.
Denmark
Industrial-scale culture collection management and genomic screening capabilities anchor strain development pipelines. EFSA novel food consultation mandates for whole-genome sequencing data favor manufacturers with integrated bioinformatics infrastructure. The Copenhagen region concentrates fermentation science expertise and regulatory affairs specialization for European market navigation.
Single-Strain Probiotics Market Competitive Landscape
Global majors compete with regional champions across strain development depth and cold-chain distribution reach, producing a tiered structure where culture collection heritage separates premium-positioned players from commodity suppliers. Market concentration reflects patent-protected strain lineages and fermentation scale economies rather than manufacturing technology alone. Three archetypes dominate: legacy culture houses with century-long strain banks, diversified nutrition conglomerates leveraging refrigerated retail networks, and precision fermentation specialists optimizing single-strain anaerobic production. Competitive moves center on genomic screening platform partnerships and accelerated stability certification investments that secure pharmacy formulary inclusion.
Within the legacy culture house tier, Chr. Hansen and Lallemand exemplify players whose strain collection depth anchors medical-grade supply positioning. Among diversified nutrition conglomerates, Danone and Nestlé Health Science occupy positions where refrigerated distribution infrastructure protects live-cell viability claims through retail and pharmacy channels. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Chr. Hansen |
| Danone |
| Nestlé Health Science |
| Yakult Honsha |
| BioGaia |
| DuPont |
| Novonesis |
| Lallemand |
| ADM |
| Others |
Value Network & Pricing Analysis
Medical-grade certification tiers bifurcate the market into pharmacy-distributed clinical products and ambient-stable consumer formats, with cold-chain warranty terms and live-cell stability guarantees separating premium positioning from commodity alternatives. This tier divergence manifests in supply chain configurations through dedicated anaerobic fermentation facilities versus multi-purpose dairy plant retrofits, and in pricing through subscription bundling versus transactional retail.
Pricing Analysis
Live-cell stability warranties bundled with refrigerated last-mile logistics anchor premium subscription pricing for direct-to-consumer brands, while unbundled commodity powders compete on per-CFU unit economics. Three-tier pricing structure across medical-grade, professional-grade, and mass-market levels reflects certification depth and cold-chain investment. Pricing pressure stems from precision fermentation scale economies as industrial bioreactors achieve 10^11 CFU per milliliter densities. Hospital procurement committees exhibit lowest price sensitivity; mass-market supermarket buyers show highest.
Supply Chain Analysis
Dairy-derived growth media and cryoprotectant feedstocks rest on Danish and German specialty fermentation suppliers, with precision fermentation platforms drawing from US and Indian contract manufacturing expansion. Lyophilized culture concentrates, enteric coating materials, and anaerobic bioreactor hardware constitute critical input dependencies. Single-source vulnerability concentrates in European EFSA QPS-compliant strain banks. Distribution runs through cold-chain logistics partnerships for live-cell products and ambient networks for stabilized formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is transitioning from empirical strain screening to AI-driven phenotype prediction, with whole-genome sequencing validation replacing legacy culture collection depth as the primary competitive moat.
For Market Incumbents: Lock in genomic screening platform partnerships to defend against precision fermentation specialists eroding culture collection advantages. Invest in accelerated stability certification at 25°C and 40°C conditions to secure pharmacy formulary inclusion before subscription brands capture physician channel preference. For New Entrants and Emerging Players: Begin with veterinary microbiome applications in canine digestive health, where pet insurance reimbursement creates pull-through demand and strain patent thickets are less dense. Target India's PLI scheme-aligned fermentation capacity for cost-competitive export supply to European and North American markets. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given EFSA novel food consultation mandates for whole-genome sequencing data favoring integrated bioinformatics infrastructure. Long-term viability hinges on strain-level IP freedom-to-operate in Bifidobacterium and Lactobacillus lineages. Watch EFSA QPS list expansion velocity as inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Whole-Genome Sequencing Integration | EFSA novel food mandates favor manufacturers with in-house bioinformatics pipelines over third-party dependencies. |
| Precision Fermentation Scale-Up | Dedicated anaerobic bioreactors achieve medical-grade potency at industrial scale, compressing cost curves for high-CFU formulations. |
| Accelerated Stability Certification | Physician formulary inclusion requires documented live-cell viability through expiration at elevated temperature conditions. |
| Veterinary Microbiome Expansion | Pet insurance reimbursement creates pull-through demand for canine and feline digestive health formulations. |
| Direct-to-Consumer Subscription Model | Bypassing retail slotting fees captures higher margins while building longitudinal health data repositories. |
Research Methodology
Independent corroboration across fermentation science executives, regulatory affairs specialists at EFSA and FDA, pharmacy formulary directors, and precision fermentation platform engineers underwrites the qualitative findings. Secondary validation draws from EFSA QPS list updates, FDA GRAS notifications, clinical trial registries, and customs data on fermentation equipment imports. Bottom-up strain-level demand modeling triangulates with top-down market sizing across delivery formats.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs derive from strain-specific adoption curves and pricing trajectory assumptions. Forecast inputs incorporate EFSA regulatory pathway timelines and precision fermentation capacity buildout announcements.
Underlying measurement precision varies by segment; medical-grade formulations with pharmacy distribution carry tighter precision than direct-to-consumer wellness products. Forecasts reflect documented assumptions on regulatory clearance velocity and cold-chain infrastructure expansion. EFSA QPS list update frequency, FDA medical food designation velocity, and precision fermentation yield improvements warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
South America Probiotics Market