
 United States Feed Probiotics Market | 2026-2036
United States Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Feed Probiotics Market Outlook
Direct-to-farm distribution networks is rewriting how probiotic formulations reach livestock operations across the Midwest and Southeast. Cargill Inc. leverages its vertically integrated animal nutrition platform to control formulation-to-farm delivery. Lallemand Inc. specializes in yeast and bacterial strain development for species-specific applications. Kemin Industries anchors its position through shelf-stable encapsulation technologies that protect viability through feed processing.
Feed probiotics are live microbial preparations, typically containing bacteria such as Lactobacillus, Bacillus, or Enterococcus strains at concentrations measured in colony-forming units per gram, that colonize the gastrointestinal tract to improve nutrient absorption and outcompete pathogenic organisms. Their primary commercial purpose is to replace or reduce antibiotic growth promoters while maintaining feed conversion efficiency in intensive animal production systems. Powder formulations dominate volume shipments due to blending compatibility with existing feed mill infrastructure, while liquid applications are gaining traction in automated drinking water systems for swine and poultry operations. Gut health applications command the largest share of current demand, though disease prevention segments are expanding as veterinarians integrate probiotics into reduction protocols for enteric pathogens like Salmonella and Clostridium.
The FDA's Veterinary Feed Directive framework and USDA organic certification standards shape product development pathways, with the former restricting antibiotic use and the latter prohibiting synthetic alternatives altogether. State-level feed regulatory programs in Iowa, North Carolina, and Texas add compliance layers that favor suppliers with documented strain efficacy and stability data. Stakeholders must monitor evolving EPA guidelines on microbial manufacturing emissions and the potential for federal procurement standards that would require probiotic inclusion in supplier contracts for institutional meat purchasing.
Market Dynamics
The FDA's Veterinary Feed Directive has eliminated routine antibiotic use in livestock feed, forcing integrators to rebuild gut health protocols around live microbial additives. This regulatory compression has concentrated purchasing power among the largest poultry and swine operations while fragmenting supplier tiers.
Growth Catalysts
- Regulatory displacement:The Veterinary Feed Directive mandates veterinary oversight for antibiotic use, accelerating probiotic adoption as growth promoter substitutes in Iowa and North Carolina feedlots.
- Precision fermentation:Bioreactor-based strain cultivation is lowering production costs for Bacillus and Lactobacillus concentrates, expanding formulation access to mid-size dairy operations.
- Consolidated livestock operations:Vertical integration across Georgia and Arkansas poultry chains creates volume contracts for customized multi-strain blends with documented efficacy data.
Market Restraints
- Strain stability costs:Encapsulation technologies required to protect viability through pelleting temperatures above 85°C add 15-25% to raw material costs versus unprotected alternatives.
- Midwest supply concentration:Three-quarters of domestic fermentation capacity sits within 200 miles of Des Moines, creating weather and logistics vulnerability for just-in-time delivery to Southeast poultry integrators.
- Enzyme substitution:Direct-fed microbial enzymes from fungal sources compete for the same gut health budget in ruminant operations, particularly in Texas cattle feedyards.
Strategic Opportunities
- USDA organic certification:The National Organic Program's prohibition on synthetic growth promoters creates a captive market for documented probiotic protocols in pasture-based dairy and poultry systems.
- Automated drinking water delivery:Liquid probiotic dosing systems in tunnel-ventilated hog barns bypass feed mill infrastructure entirely, opening direct supplier relationships with swine operations over 5,000 head.
- Salmonella reduction protocols:FSIS performance standards for poultry processing plants are driving preventive probiotic programs in breeder and layer operations to reduce downstream contamination risk.
Industry Challenges
- Microbiome analytical talent:Commercial feed mills lack in-house capability to interpret 16S rRNA sequencing data for strain-specific efficacy validation, creating dependency on third-party testing labs with 6-8 week turnaround times.
- Legacy feed mill retrofit costs:Separated liquid handling and temperature-controlled storage for live cultures requires capital investment that smaller independent mills in the Corn Belt cannot absorb without cooperative purchasing agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Feed Probiotics Market |
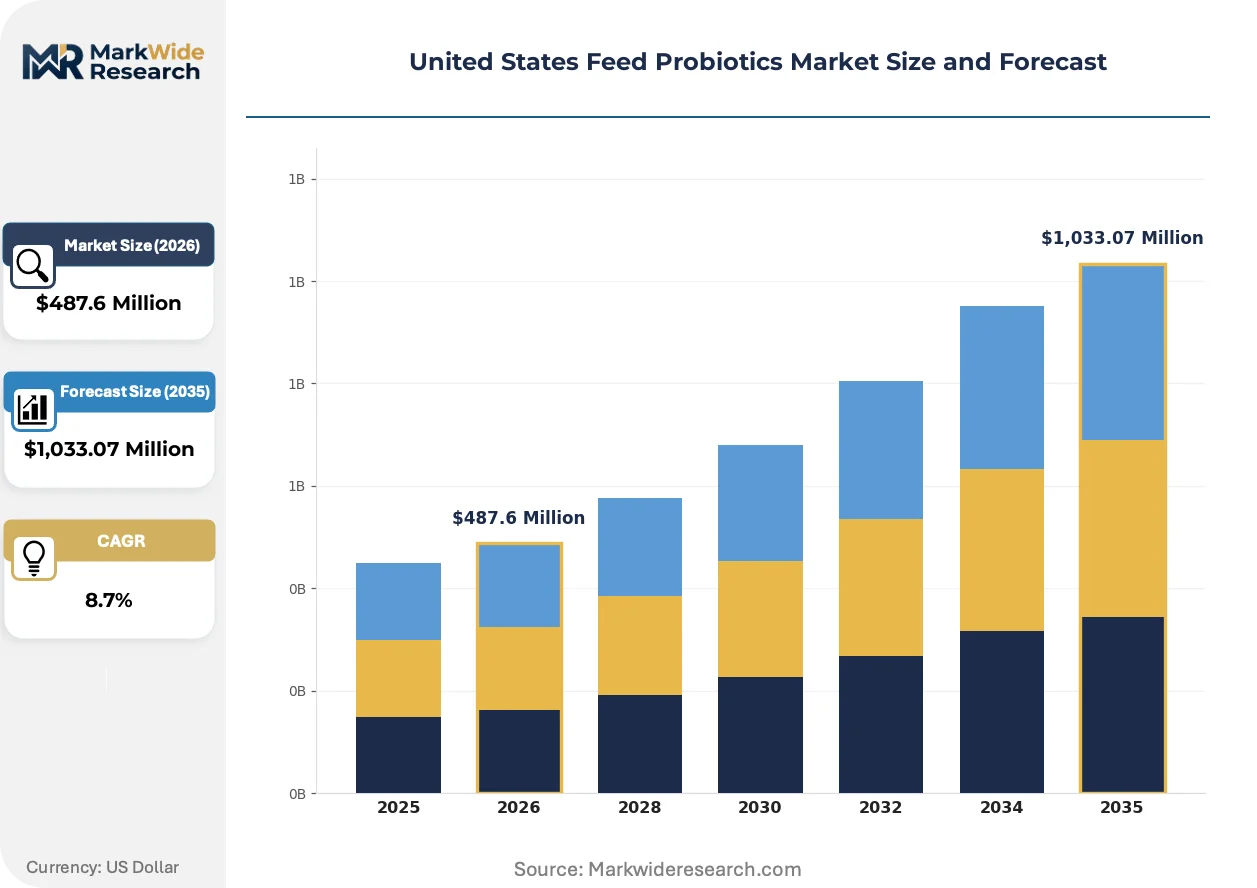
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Swine, Ruminants, Aquaculture Application: Animal Nutrition, Gut Health, Growth Promotion, Disease Prevention Form: Powder, Liquid, Granules, Capsules End User: Farmers, Feed Manufacturers, Veterinarians, Livestock Producers |
| Companies Covered | Cargill Inc., DSM Nutritional Products AG, Evonik Industries AG, International Flavors and Fragrances Inc., Kerry Group PLC, Kemin Industries, Lallemand Inc., Adisseo, CHR. Hansen A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Feed Probiotics Market Strategic Shifts
Livestock nutrition is digitizing rapidly as sensor networks and biological monitoring converge with microbial science. Three developments are compressing product development cycles and rewiring supplier-buyer relationships.
Multi-omics strain screening is virtualizing the traditional isolation-and-test pipeline for probiotic candidates. Genomic sequencing combined with metabolomic profiling allows researchers to predict colonization efficacy before animal trials. Large integrators in the Southeast are adopting these platforms to co-develop proprietary strain combinations with input suppliers, collapsing 18-month development timelines.
The EPA's emerging guidelines on microbial manufacturing emissions are tightening effluent standards for fermentation facilities. Plants discharging high-biomass waste streams face pretreatment requirements that favor consolidated production sites with dedicated wastewater infrastructure. Iowa and Minnesota facilities with anaerobic digestion capacity are capturing biogas credits while smaller operators face compliance-driven consolidation pressure.
Direct contracting between strain developers and livestock operations is displacing traditional distributor networks in the upper Midwest. Volume buyers with internal nutrition teams now negotiate formulation exclusivity in exchange for field trial data sharing. This pattern concentrates in Nebraska and Kansas cattle feedyards where three operators control sufficient tonnage to justify dedicated production runs.
United States Feed Probiotics Market Segmentation
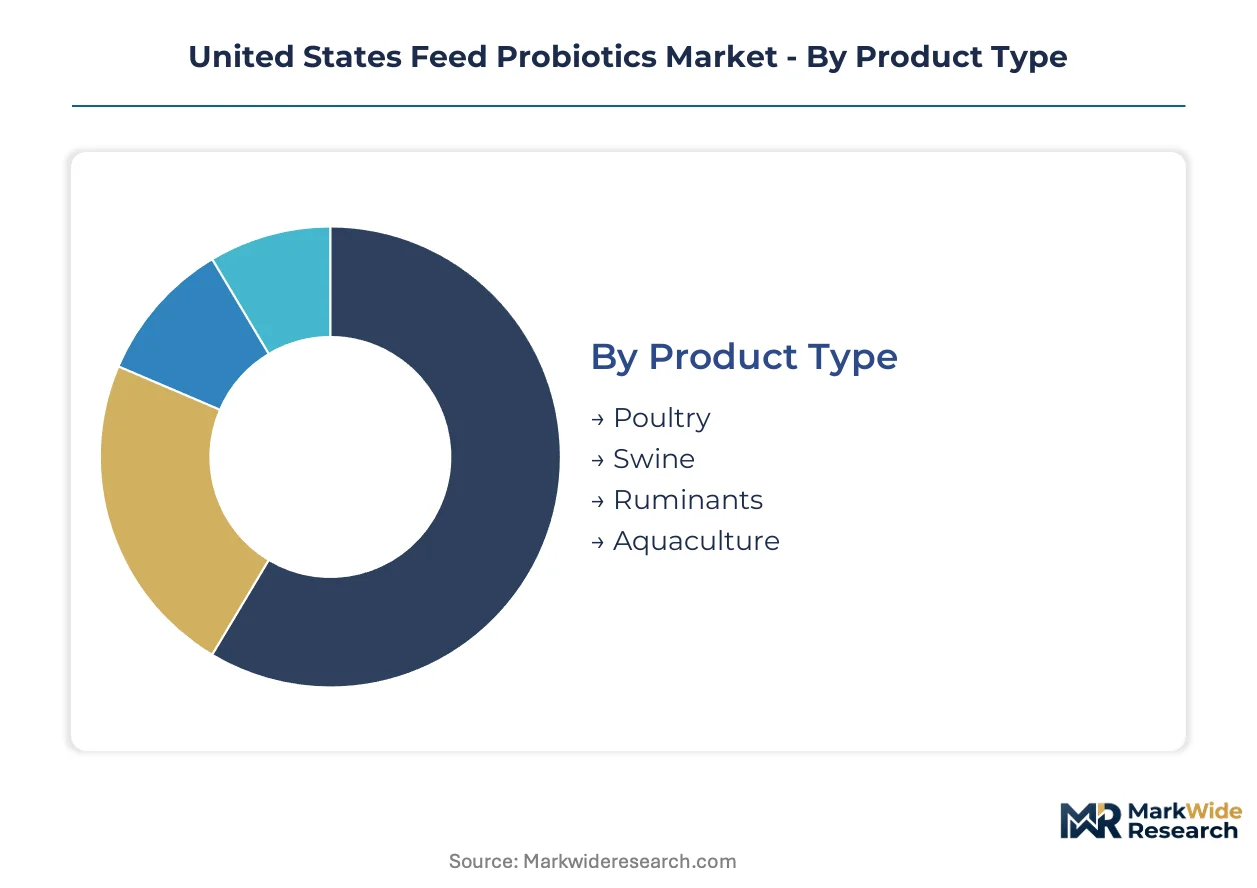
Feed probiotic suppliers configure service intensity around formulation stability and delivery timing. Live microbial products demand cold-chain monitoring, viability testing, and rapid response protocols that vary sharply across livestock categories and application settings.
Product Type:
After-sales-service intensity peaks with species requiring customized multi-strain protocols and real-time gut health monitoring.
- Poultry:Broiler and layer operations in Georgia and Arkansas drive demand for heat-stable Bacillus formulations that survive pelleting temperatures. Vertical integrators negotiate dedicated technical service teams for flock-level protocol adjustments. Contract volumes concentrate with integrators controlling breeder through processing operations.
- Swine:Sow farms and nursery operations in Iowa and North Carolina require liquid delivery systems with automated dosing calibration. Service technicians visit weekly during diet transitions to adjust Lactobacillus concentrations. Disease pressure from porcine epidemic diarrhea virus elevates microbiome monitoring frequency.
- Ruminants:Dairy operations in Wisconsin and California prioritize yeast-based rumen modifiers with on-farm mixing support.
- Aquaculture:Catfish ponds in Mississippi and salmonid facilities in Idaho need species-specific strain validation with water quality correlation.
By volume, Poultry leads. By growth pace, Aquaculture is ahead.
Application:
Cost tier stratification separates premium validated protocols from commodity growth promoter substitutes.
- Animal Nutrition:Broad-spectrum formulations targeting feed conversion efficiency dominate volume shipments to Corn Belt feed mills. These applications require minimal technical support beyond blending instructions. Price competition intensifies among suppliers with undifferentiated Bacillus subtilis concentrates.
- Gut Health:Microbiome modulation protocols command premium pricing in weaning piglets and transition dairy cows. Veterinary oversight requirements under FDA guidelines elevate documentation burdens. Suppliers invest in sequencing partnerships to validate colonization claims.
- Growth Promotion:Post-antibiotic alternatives face margin compression from enzyme competitors in Texas cattle feedyards.
- Disease Prevention:Salmonella reduction programs in breeder operations carry liability exposure requiring indemnification clauses.
Nutrition applications capture the largest tonnage. Disease prevention commands the steepest expansion trajectory.
Form:
Volume concentration favors formats compatible with existing feed mill infrastructure and automated delivery systems.
- Powder:Standardized particle sizes between 100-500 microns enable homogeneous blending with vitamin premixes and trace minerals. Thermal protection through spray-dried encapsulation extends shelf stability to 18 months. Midwest feed mills process powder formulations through existing batching systems without capital retrofit.
- Liquid:Concentrated suspensions with 10^10 CFU/ml potency integrate into swine nursery drinking water systems. Metering pumps require weekly calibration service visits. Nebraska and Kansas operations over 5,000 head justify direct supplier relationships bypassing distributor markups.
- Granules:Fluidized bed coating protects viability through extrusion temperatures for aquaculture feeds.
- Capsules:Unit-dose packaging serves small ruminant producers and veterinary prescription channels.
Powder dominates current volume. Liquid is gaining share fastest in automated facilities.
End User:
Customer type determines purchasing sophistication, contract structure, and technical service allocation.
- Feed Manufacturers:Commercial mills in Iowa, Minnesota, and Texas negotiate volume contracts with strain exclusivity provisions. Quality control protocols demand certificate of analysis for every lot with third-party viability verification. Just-in-time delivery requirements strain logistics networks concentrated near Des Moines.
- Livestock Producers:Large integrators in Georgia and Arkansas employ internal nutritionists who co-develop proprietary formulations with input suppliers. Data sharing agreements exchange field trial results for preferred pricing tiers. Direct contracting displaces traditional distributor relationships.
- Farmers:Independent operators under 500 head rely on cooperative purchasing for price leverage.
- Veterinarians:Prescription channels expand under Veterinary Feed Directive oversight requirements.
Feed manufacturers move the most tonnage. Livestock producers are expanding procurement autonomy fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Interstate 35 corridor link fermentation capacity in Iowa to poultry processing clusters in the Southeast, creating a dual-hub supply architecture for live microbial feed additives.
Iowa
Precision fermentation facilities near Des Moines supply Bacillus and Lactobacillus concentrates to Corn Belt feed mills. EPA pretreatment requirements for high-biomass effluent favor plants with anaerobic digestion capacity. Three operators control three-quarters of domestic fermentation tonnage within 200 miles of the state capital.
Georgia
Broiler integrators in Gainesville and Athens negotiate dedicated technical service teams for heat-stable formulation protocols. The FDA's Veterinary Feed Directive has eliminated routine antibiotic use, forcing flock-level gut health rebuilds. Vertical integration from breeder farms through processing plants creates volume contracts for customized multi-strain blends.
Arkansas
Tyson Foods and Pilgrim's Pride operations in Springdale and Russellville drive demand for encapsulated yeast and bacterial preparations. State environmental permits for concentrated animal feeding operations require documented pathogen reduction strategies. Direct supplier relationships bypass traditional distributor networks for operations over 5,000 head.
North Carolina
Sow farms and nursery operations in Duplin and Sampson counties require liquid probiotic delivery systems with automated dosing calibration. The state's veterinary oversight requirements under FDA guidelines elevate documentation burdens for live microbial protocols. Weekly service visits during diet transitions adjust Lactobacillus concentrations for porcine epidemic diarrhea virus pressure.
California
Dairy operations in the Central Valley prioritize yeast-based rumen modifiers with on-farm mixing support. State air quality regulations for dairy digesters create compliance-driven demand for documented microbial protocols. Cooperative purchasing agreements among mid-size herds aggregate sufficient volume for preferred pricing tiers.
United States Feed Probiotics Market Competitive Environment
On the supply side, the industry is bifurcated between integrated nutrition platforms and specialized strain developers. Large-scale compounders control distribution infrastructure through captive feed mill relationships. Independent fermentation houses compete on strain specificity and thermal stability documentation. Consolidation pressure is mounting as EPA effluent standards favor capital-intensive production sites with dedicated wastewater infrastructure.
Within the integrated nutrition tier, Cargill Inc. anchors market presence through vertically controlled formulation-to-farm delivery. Lallemand Inc. exemplifies the specialized fermentation archetype with concentrated expertise in yeast and bacterial strain development. Kemin Industries occupies a position defined by encapsulation technology differentiation for pelleting temperature protection. These three entities represent the dominant competitive vectors: captive supply chain control, biological specialization, and process technology barriers.
| Leading Market Players |
|---|
| Cargill Inc. |
| DSM Nutritional Products AG |
| Evonik Industries AG |
| International Flavors and Fragrances Inc. |
| Kerry Group PLC |
| Kemin Industries |
| Lallemand Inc. |
| Adisseo |
| CHR. Hansen A/S |
| Others |
Value Chain & Pricing Dynamics
Des Moines-area fermentation capacity concentration grants three operators outsized leverage in contract negotiations with Corn Belt feed mills and Southeast poultry integrators. This geographic chokepoint translates into pricing power for heat-stable Bacillus concentrates, while downstream buyers absorb logistics premiums for just-in-time delivery to Arkansas and Georgia operations.
Pricing Analysis
Volume-discount tiering structures separate integrators above 5,000 head from cooperative-purchasing independents and small ruminant operators. Price differentiation rests on thermal stability documentation and strain-specific efficacy data, with USDA organic certification commanding premium positioning. Pricing pressure intensifies in commodity Bacillus subtilis concentrates as enzyme competitors from fungal sources capture gut health budgets in Texas cattle feedyards. Feed manufacturers represent the most price-sensitive segment due to undifferentiated blending requirements, while vertically integrated poultry chains with internal nutrition teams demonstrate lowest sensitivity through co-development arrangements.
Supply Chain Analysis
Contract-manufacturing concentration sits with Cargill Inc., Lallemand Inc., and Kemin Industries controlling formulation-to-farm infrastructure across Iowa, Minnesota, and Texas. Raw material dependencies include glucose feedstocks for fermentation, specialized encapsulation polymers for thermal protection, and cold-chain logistics capacity for viability maintenance. Supply chain risk centers on Des Moines-cluster weather vulnerability disrupting just-in-time delivery to Southeast poultry integrators. Distribution runs through vertically integrated nutrition platforms for large integrators, while independent feed mills rely on cooperative purchasing agreements for price leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Veterinary Feed Directive has transformed feed probiotics from additive inputs into platform-anchored health protocols, with interoperability between strain developers and livestock sensor networks emerging as the decisive ecosystem battleground.
For Market Incumbents: Insulate proprietary strain libraries through exclusive data-sharing agreements with large integrators in Georgia and Arkansas. Deepen backward integration into precision fermentation capacity near Des Moines to secure EPA-compliant effluent handling. The priority defensive lever is capturing field trial data pipelines that validate colonization claims before generic competitors reach veterinary channels. For New Entrants and Emerging Players: Build out liquid delivery system expertise for automated swine nursery operations in Iowa and North Carolina, the most penetrable white-space segment. Target mid-size dairy cooperatives in Wisconsin and California seeking yeast-based rumen modifiers with on-farm mixing support. The optimal go-to-market angle is direct technical service relationships bypassing traditional distributor markups for operations between 500 and 5,000 head. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fermentation houses with documented thermal stability IP and EPA-compliant wastewater infrastructure. Long-term viability hinges on multi-omics strain screening capabilities that collapse development timelines. The signal to watch is direct contracting velocity between strain developers and livestock operations with internal nutrition teams.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | EPA pretreatment compliance secures Des Moines-cluster positioning against consolidation pressure. |
| Multi-Strain Co-Development Partnerships | Data-sharing agreements with Georgia integrators lock in proprietary formulation exclusivity. |
| Liquid Delivery System Integration | Automated dosing calibration penetrates Iowa and North Carolina swine nursery operations. |
| Thermal Stability IP Acquisition | Encapsulation technology barriers protect viability through feed mill pelleting temperatures. |
| USDA Organic Certification Pathway | National Organic Program compliance opens captive pasture-based dairy and poultry segments. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation plant managers, poultry nutrition directors at Georgia integrators, swine veterinary specialists in Iowa, and feed mill procurement leads, then refined through secondary validation. Primary intelligence drew from FDA Veterinary Feed Directive implementation assessments, EPA effluent standard filings, USDA organic certification databases, and Corn Belt logistics operator interviews. Secondary sources included SEC 10-K disclosures from publicly traded nutrition platforms, American Feed Industry Association regulatory commentaries, and Iowa State University extension service technical bulletins. Bottom-up strain-level volume estimates and top-down feed additive market allocations were triangulated for convergence.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included livestock species, application purpose, formulation format, and end-user procurement sophistication. CAGRs were derived from probiotic inclusion rate trajectories in post-antibiotic protocols, cross-referenced against livestock inventory projections and feed tonnage forecasts. Industry-specific inputs incorporated Veterinary Feed Directive compliance timelines and EPA pretreatment cost pass-through assumptions for fermentation capacity.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by enzyme competitors or rapid EPA effluent standard tightening would shift outcomes beyond modeled ranges. Quarterly review of direct contracting announcements, 16S rRNA sequencing partnership formations, and Iowa fermentation capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Shelf Stable Probiotics Market