
 Global Probiotics Food and Cosmetics Market | 2026-2036
Global Probiotics Food and Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Probiotics Food and Cosmetics Market Outlook
Buyer concentration in the probiotics space is consolidating as large retail pharmacy chains and direct-to-consumer wellness platforms capture growing share of end-user spending. Danone S.A. leverages its fermented dairy heritage to anchor European refrigerated probiotic distribution. Nestlé S.A. sustains multi-category presence spanning infant nutrition through adult gut health portfolios. L'Oréal S.A. competes in skin microbiome science through dedicated research programs and dermatological brand extensions.
Probiotics food and cosmetics comprise live microbial cultures formulated into ingestible products or topical preparations, typically requiring minimum viable cell counts at consumption or application to confer claimed benefits. Industrial production employs freeze-drying, microencapsulation, and controlled fermentation to preserve strain viability through shelf life and gastric transit. Dairy formulations dominate current revenue owing to established consumer habits and cold-chain infrastructure, while skin care applications attract accelerating investment as microbiome science validates topical live culture efficacy. Adult consumers represent the largest addressable end-user pool, though athlete-targeted probiotic positioning is gaining traction as exercise-associated gut permeability research advances.
The US FDA oversees probiotic dietary supplement labeling under DSHEA, while EFSA evaluates health claim substantiation for European food applications, creating divergent evidentiary thresholds that fragment product development roadmaps. Health Canada's Natural and Non-prescription Health Products Directorate imposes additional strain-specific efficacy requirements for market entry. Stakeholders must monitor evolving strain-level qualification standards across jurisdictions to avoid reformulation costs and access delays.
Market Dynamics
Strain-level qualification standards across the US, EU, and China are fragmenting product development roadmaps and forcing manufacturers to maintain parallel regulatory dossiers for identical formulations.
Growth Catalysts
- EFSA health claims framework:Validated substantiation pathways enable premium positioning for clinically documented strains in European dairy and supplement applications.
- China tier-one city consumption:Domestic probiotic food demand concentrates in Shanghai, Beijing, and Shenzhen as cold-chain infrastructure penetrates urban retail.
- Microencapsulation technology:Advanced coating systems extend shelf stability and gastric survival rates for non-refrigerated delivery formats.
Market Restraints
- Strain-specific efficacy requirements:Health Canada's Natural and Non-prescription Health Products Directorate mandates individualized dossiers that extend approval timelines.
- Live culture supply concentration:Freeze-drying capacity clusters in Denmark, Germany, and France, creating geographic vulnerability for non-European formulators.
- Fermented dairy substitution:Plant-based alternatives displace traditional yogurt carriers in European and North American retail channels.
Strategic Opportunities
- India functional food penetration:FSSAI regulatory clarity and PLI scheme incentives attract manufacturing investment for domestic and export supply.
- Skin microbiome topical delivery:Cosmetic applications leverage live culture stabilization advances to enter premium dermatological channels.
- Direct-to-consumer wellness platforms:Subscription models bypass traditional pharmacy and grocery intermediaries in the US and UK markets.
Industry Challenges
- Strain banking and IP licensing:Exclusive access agreements with culture collections create barriers for new market entrants.
- Clinical trial standardization:Divergent endpoints across FDA, EFSA, and NMPA guidelines multiply development costs for global launches.
- Legacy cold-chain integration:Refrigerated distribution networks require capital-intensive retrofitting for ambient-stable probiotic formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Probiotics Food and Cosmetics Market |
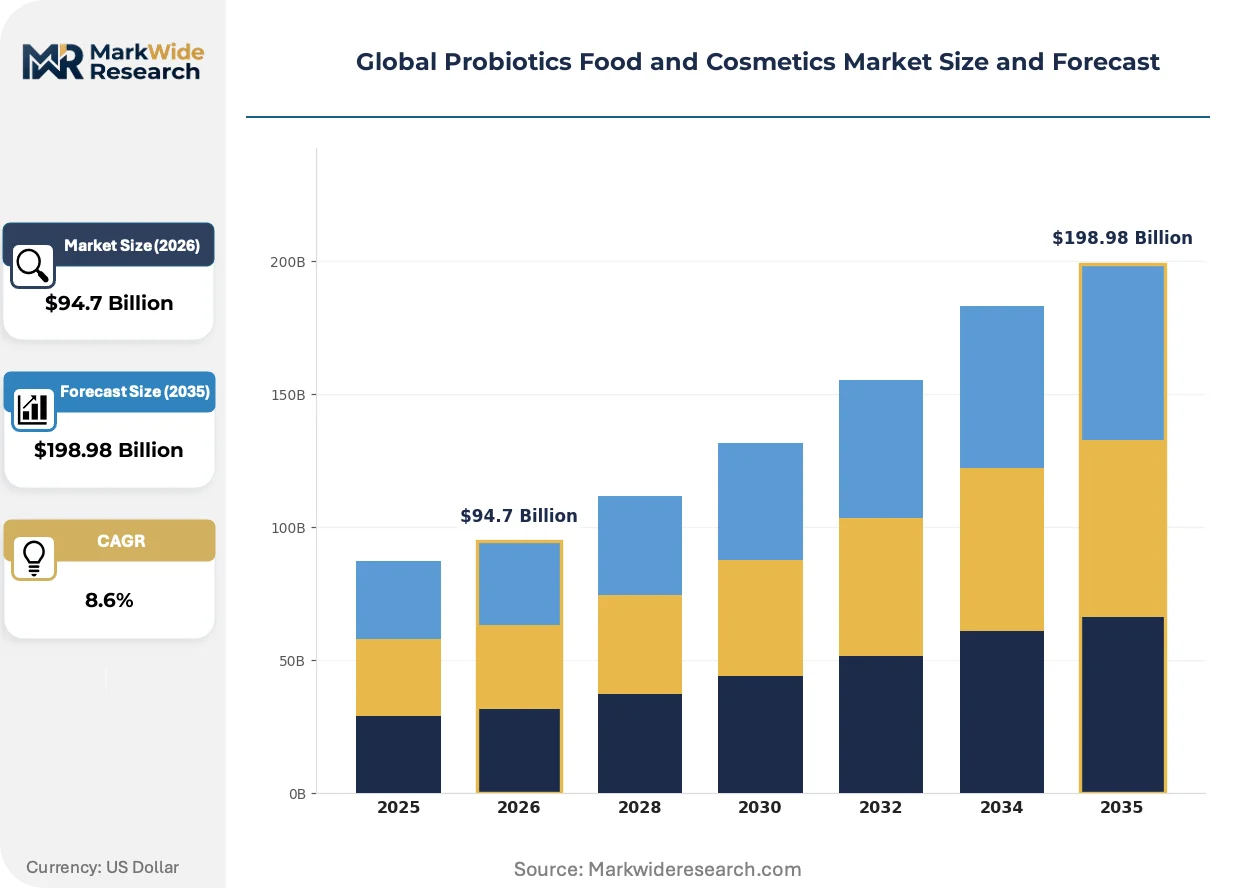
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy, Dietary Supplements, Snack Bars, Beverages End User: Adults, Children, Pregnant Women, Athletes Application: Digestive Health, Skin Care, Immune Support, Weight Management Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Danone S.A., Nestlé S.A., L'Oréal S.A., DuPont, Yakult Honsha Co., Ltd., ADM, The Estée Lauder Companies Inc., Esse Skincare, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Probiotics Food and Cosmetics Market Strategic Shifts
Live microbial delivery systems are converging with precision fermentation and synthetic biology to expand viable applications beyond traditional dairy matrices.
Microencapsulation via spray-dried alginate-chitosan complexes is overtaking conventional freeze-drying for ambient-stable probiotic powders. Sports nutrition and travel-health supplement brands adopt these formats for convenience positioning. The technology compresses manufacturing costs and enables direct-to-consumer channels previously blocked by refrigeration requirements.
China's NMPA and SAMR are tightening strain registration protocols for imported probiotic cosmetics and functional foods. Manufacturers must submit whole-genome sequencing and safety documentation that exceeds prior notification thresholds. European exporters to China face extended qualification timelines and are restructuring local partnerships to secure domestic strain libraries.
Athlete-targeted positioning is gaining traction as exercise-associated gut permeability research validates strain-specific formulations. Performance nutrition brands and professional sports teams in Australia and the US incorporate clinically documented cultures into recovery protocols. This segment shifts procurement toward evidence-based specifications and away from generic colony-forming unit claims.
Global Probiotics Food and Cosmetics Market Segmentation
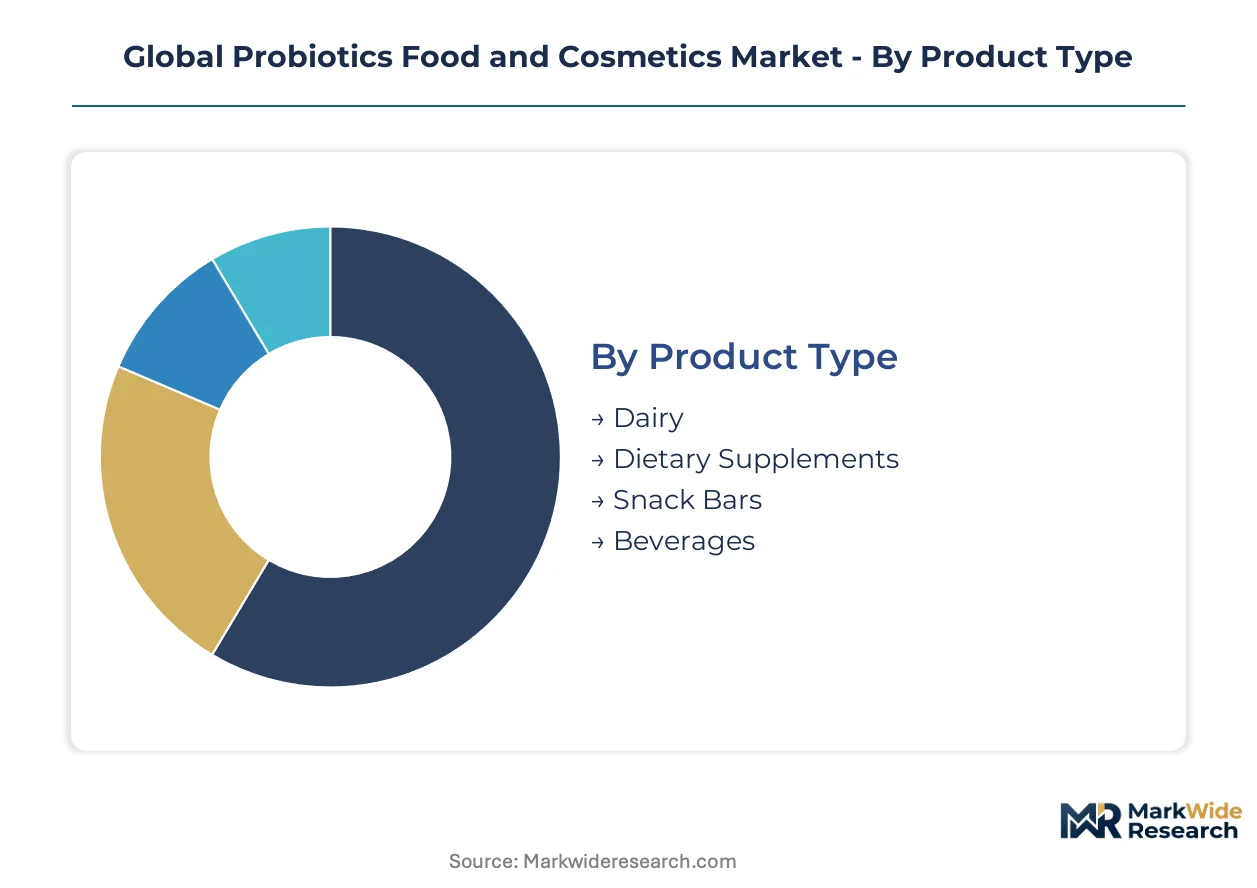
Strain viability requirements and cold-chain dependencies create divergent upgrade cycles across product formats. Consumer migration from refrigerated dairy to ambient-stable supplements and topicals is redrawing competitive boundaries.
Product Type:
Replacement cycles accelerate as microencapsulation technology extends shelf stability beyond traditional freeze-dried formats.
- Dairy:Fermented milk and yogurt carriers deliver live cultures through established cold-chain infrastructure. European refrigerated retail and Chinese tier-one city supermarkets anchor volume, though plant-based substitution pressures conventional dairy positioning.
- Dietary Supplements:Capsule, tablet, and powder formats employ alginate-chitosan microencapsulation to achieve ambient stability. Direct-to-consumer wellness platforms in the US and UK drive fastest expansion as subscription models bypass pharmacy intermediaries.
- Snack Bars:Ambient-stable probiotic incorporation into cereal and protein bars targets convenience-oriented consumers. Manufacturing challenges around moisture control and thermal processing limit strain viability.
- Beverages:Ready-to-drink kombucha and water kefir occupy niche premium positioning. Shelf-life constraints and refrigeration requirements restrict mass-market penetration outside urban cold-chain clusters.
Dairy sits at the top of the volume ranking, with Dietary Supplements climbing the fastest.
End User:
Customer lifetime value concentrates in segments with recurring purchase behavior and clinical validation requirements.
- Adults:Working-age consumers seeking gut health maintenance and immune support represent the broadest addressable base. Chinese urban professionals and European aging populations sustain premium pricing for clinically documented strains.
- Children:Pediatric formulations emphasize strain safety profiles and palatability in gummy or powder formats. Parental purchasing decisions prioritize EFSA-substantiated health claims and allergen-free certifications.
- Pregnant Women:Specialized prenatal probiotics target gestational microbiome modulation. Regulatory scrutiny from FDA and EFSA elevates substantiation thresholds above general adult formulations.
- Athletes:Exercise-associated gut permeability research validates strain-specific recovery protocols. Australian and US professional sports teams incorporate documented cultures into nutrition programs, shifting procurement toward evidence-based specifications.
Adults command the largest revenue share, while Athletes gain share fastest through performance nutrition channel expansion.
Application:
Margin structures diverge between commoditized digestive positioning and premium dermatological claims.
- Digestive Health:Core gut microbiome modulation applications dominate current revenue. Generic colony-forming unit claims face pressure from strain-specific efficacy requirements in Canada and China.
- Skin Care:Topical live culture delivery leverages microencapsulation advances for dermatological channel entry. L'Oréal's dedicated research programs and European cosmetic science validate premium pricing.
- Immune Support:Respiratory and systemic immune claims require rigorous clinical substantiation under EFSA and NMPA frameworks. Approved strains command significant formulation premiums.
- Weight Management:Metabolic health positioning remains contested territory with inconsistent regulatory acceptance. Strain-specific satiety and adiposity studies multiply development costs.
Digestive Health maintains volume leadership, with Skin Care expanding most quickly through microbiome science validation.
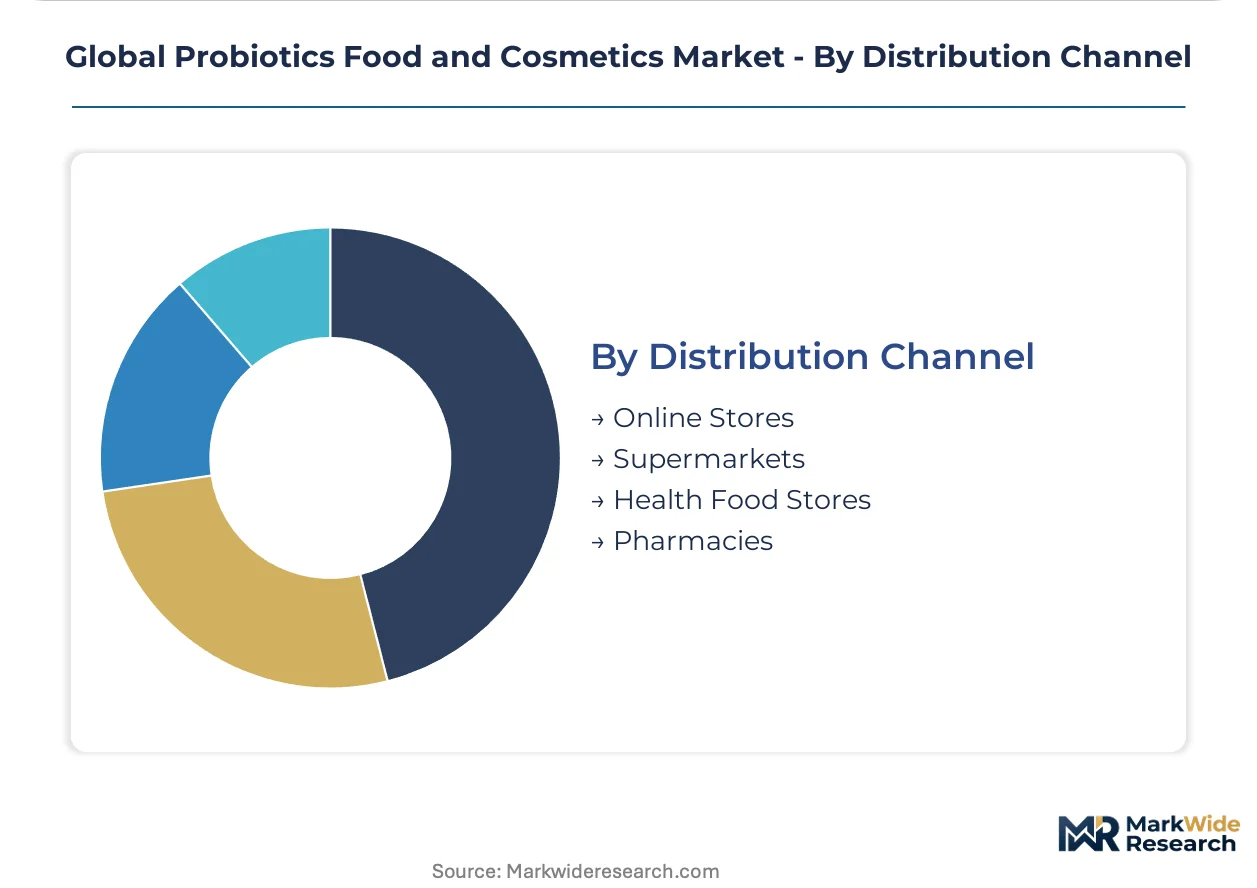
Distribution Channel:
Channel control is consolidating as vertical integration between manufacturers and direct platforms bypasses traditional retail intermediaries.
- Online Stores:Subscription-based wellness platforms capture recurring revenue with personalized strain recommendations. UK and US direct-to-consumer brands leverage first-party data to optimize retention.
- Supermarkets:Mass-market refrigerated dairy placement depends on cold-chain infrastructure penetration. Chinese tier-one city retail expansion and European discount channel competition pressure margin structures.
- Health Food Stores:Specialty retailers emphasize artisanal and organic probiotic positioning. Knowledgeable staff drive higher-margin supplement sales through consultation-based selling.
- Pharmacies:Clinical channel credibility supports premium pricing for medically positioned strains. Health Canada and EFSA-approved indications differentiate pharmacy-grade from general wellness formulations.
Supermarkets retain volume dominance, with Online Stores capturing share fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microbiome research talent clusters in Copenhagen, Paris, and Shanghai anchor the geographic distribution of probiotic innovation. Strain development laboratories and fermentation engineering expertise concentrate in these cities, shaping regional competitive advantages.
United States
Athlete-targeted formulations and direct-to-consumer wellness platforms drive demand expansion. The FDA's DSHEA framework governs dietary supplement labeling, creating distinct substantiation requirements from food applications. Greater Boston hosts biotechnology firms advancing precision fermentation for next-generation strain development.
China
Tier-one urban professionals in Shanghai, Beijing, and Shenzhen sustain premium consumption of imported probiotic dairy and supplements. NMPA and SAMR strain registration protocols now mandate whole-genome sequencing documentation. Yangtze River Delta manufacturing clusters are integrating domestic strain libraries to bypass import qualification delays.
Germany
Freeze-drying equipment manufacturers and industrial fermentation specialists anchor European supply capacity. EFSA health claim substantiation pathways enable premium positioning for clinically documented strains. Bavaria's biotechnology corridor houses contract manufacturing organizations serving global brand portfolios.
France
Dermatological channel penetration for skin microbiome products accelerates through Paris-based cosmetic science institutions. ANSM oversees cosmetic safety assessments alongside EU-wide EFSA coordination. The Île-de-France region concentrates formulation laboratories bridging pharmaceutical and cosmetic applications.
India
FSSAI regulatory clarity and PLI scheme incentives attract manufacturing investment for domestic functional food production. Maharashtra and Gujarat industrial zones develop ambient-stable probiotic formats suited to limited cold-chain infrastructure. Domestic strain isolation programs reduce licensing costs for regional formulators.
Global Probiotics Food and Cosmetics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across strain development, formulation, and distribution tiers. The market structure consolidates around three to four dominant players with integrated fermentation-to-retail capabilities, while mid-tier specialists occupy niche dermatological and sports nutrition positions. Strategic archetypes include dairy heritage conglomerates leveraging refrigerated distribution, cosmetic science multinationals advancing topical delivery, and ingredient technology suppliers licensing strain IP. Competitive moves center on exclusive culture collection agreements and microencapsulation technology licensing to secure ambient-stable formulation advantages.
Within the diversified conglomerate tier, Danone S.A. and Nestlé S.A. exemplify integrated food and nutrition positioning, while L'Oréal S.A. occupies a distinct cosmetic science archetype. These three entities anchor different competitive vectors—fermented dairy heritage, multi-category nutrition portfolios, and dermatological brand extension—without overlapping core capabilities. Specialist positioning in skin microbiome applications is represented by Esse Skincare, a focused entity exemplifying pure-play topical delivery development.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| L'Oréal S.A. |
| DuPont |
| Yakult Honsha Co., Ltd. |
| ADM |
| The Estée Lauder Companies Inc. |
| Esse Skincare |
| Kerry Group plc |
| Others |
Value Chain & Pricing Dynamics
Freeze-drying energy costs in Denmark and Germany propagate through three pricing tiers as manufacturers pass efficiency differentials to pharmacy-grade, mass-market dairy, and direct-to-consumer supplement channels. Cold-chain logistics expenditure separates refrigerated probiotic positioning from ambient-stable microencapsulated formats.
Pricing Analysis
Unbundled strain-specific efficacy documentation commands premium positioning against bundled generic colony-forming unit claims. EFSA-substantiated indications and Health Canada strain-specific approvals drive price differentiation between clinically validated and commodity-tier formulations. Pricing pressure intensifies in European dairy as plant-based alternatives displace conventional yogurt carriers. Mass-market supermarket segments exhibit highest price sensitivity, while pharmacy and dermatological channels sustain premium tolerance for documented strains.
Supply Chain Analysis
Single-source vulnerability sits with freeze-drying capacity concentration in Denmark, Germany, and France. Live culture production draws from specialized fermentation feedstocks, alginate-chitosan encapsulation polymers, and pharmaceutical-grade packaging materials. Tariff exposure on imported strains into China amplifies supply chain risk as NMPA registration timelines extend. Distribution runs through cold-chain refrigerated networks for dairy, direct-to-consumer platforms for supplements, and dermatological specialty channels for topical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in probiotics food and cosmetics rests on microencapsulation cost compression enabling ambient-stable formats to capture pharmacy and travel-health premiums.
For Market Incumbents: Lock in exclusive access agreements with culture collections to defend against strain banking IP fragmentation. Secure backward integration into alginate-chitosan microencapsulation capacity to capture cost advantages as ambient-stable formats displace refrigerated dairy. Plant-based substitution in European retail threatens traditional yogurt positioning; counter with clinically documented strain portfolios that justify premium pharmacy placement. For New Entrants and Emerging Players: Direct-to-consumer wellness platforms offer the lowest barrier to entry for subscription-based probiotic brands in the US and UK. Target athlete-targeted performance nutrition as the most penetrable white-space segment, where exercise-associated gut permeability research validates strain-specific procurement. Lead with evidence-based formulations and third-party certification to bypass entrenched retail pharmacy intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where strain-level qualification standards fragment product development roadmaps across FDA, EFSA, and NMPA jurisdictions. Acquire mid-tier specialists with ambient-stable formulation capabilities and existing culture collection licensing agreements. Watch NMPA strain registration protocol evolution as the inflection signal for China market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Partnership | Exclusive culture collection agreements with DSMZ or ATCC secure differentiated IP for global launches. |
| Microencapsulation Scale-Up | Spray-dried alginate-chitosan capacity expansion enables ambient-stable formats for direct-to-consumer channels. |
| EFSA Health Claim Submission | Validated substantiation pathways unlock premium positioning in European dairy and supplement applications. |
| China Domestic Strain Library | Yangtze River Delta manufacturing partnerships bypass NMPA import qualification delays and whole-genome sequencing requirements. |
| Dermatological Channel Entry | Paris-based cosmetic science institutions validate topical live culture efficacy for premium skin microbiome positioning. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down strain production tracking forms the analytical core of this study. Primary interviews with fermentation engineering directors, regulatory affairs specialists at culture collection licensors, pharmacy category buyers, and direct-to-consumer brand operators combined with secondary validation from EFSA health claim registers, NMPA strain approval databases, FSSAI functional food notifications, and customs trade data on freeze-drying equipment imports. Triangulation between manufacturer production disclosures and retail channel shipment data ensures consistency across supply-side and demand-side estimates.
Historical trendline analysis of refrigerated dairy, ambient-stable supplement, and topical cosmetic growth patterns informed the projection framework. Segmentation modeling spans product type, end-user demographic, application claim, and distribution channel dimensions, with additional disaggregation by regulatory jurisdiction cluster. CAGRs derive from fitted growth curves adjusted for strain registration timeline variability and cold-chain infrastructure penetration rates. Microencapsulation technology adoption curves and athlete-targeted positioning momentum served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-derived next-generation strains would alter the outlook. Forecasts reflect assumptions regarding EFSA substantiation efficiency, NMPA registration streamlining, and cold-chain infrastructure buildout in target geographies. Strain-specific efficacy requirement divergence, trade policy friction on culture imports, and plant-based substitution acceleration represent primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Herbal Yeast Market