
 Herbal Yeast Market | 2026-2036
Herbal Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Yeast Market Analytics
The gap between certified organic herbal yeast strains and commodity-grade feedstock is broadening in concrete terms. Lesaffre Group leverages its vertically integrated fermentation network to secure premium positioning in specialty yeast derivatives. Angel Yeast Co., Ltd. anchors volume supply across Asian baking and brewing channels through concentrated production bases. Lallemand Inc. differentiates via probiotic-compatible strain libraries that serve pharmaceutical contract manufacturers.
Herbal yeast comprises Saccharomyces and non-Saccharomyces species cultivated on botanical substrates, typically yielding 40-60% protein by dry weight with intact beta-glucan cell walls. Its primary commercial purpose centers on delivering fermentation activity, nutritional fortification, and bioactive metabolite extraction across food and health applications. Nutritional yeast and specialty yeast command the deepest margin pools as clean-label demand from nutraceutical end users intensifies. Baker's yeast retains volume leadership but faces pricing compression from commoditized supply in mature baking markets.
EFSA evaluates novel food and health claim petitions for yeast-derived ingredients entering European commerce, while the FDA oversees GRAS self-affirmation pathways for US-bound specialty yeast products. The EU F-Gas Regulation and REACH chemical registration requirements constrain solvent-based extraction processes, redirecting capital toward aqueous and enzymatic purification technologies. Stakeholders must monitor evolving strain intellectual property landscapes and fermentation substrate traceability standards as supply chain scrutiny intensifies.
Market Dynamics
Clean-label fermentation inputs are compressing supply chains as Western European nutraceutical formulators demand substrate traceability and organic certification for beta-glucan extracts. This pressure is forcing upstream consolidation around vertically integrated strain libraries and aqueous extraction capabilities.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:The substantiation framework is redirecting R&D investment toward clinically validated yeast-derived immune modulators, accelerating premium product development.
- Botanical substrate diversification:Fermentation on spent grain and olive pomace is lowering input costs while delivering novel metabolite profiles for functional food applications.
- German procurement concentration:Nutraceutical contract manufacturers in Bavaria and Baden-Württemberg are consolidating supplier relationships around certified organic strains.
Market Restraints
- Molasses price volatility:Sugar beet harvest fluctuations in France and Germany are squeezing margins for commodity baker's yeast production.
- REACH solvent restrictions:The EU F-Gas Regulation and chemical registration requirements are blocking legacy hexane extraction infrastructure from expansion.
- Plant-based protein substitution:Pea and fava protein isolates are capturing clean-label positioning in bakery fortification segments.
Strategic Opportunities
- Spanish organic conversion:Andalusian olive processors are developing captive yeast cultivation on pomace waste streams for export to Northern European supplement markets.
- Probiotic strain convergence:Co-fermentation with Lactobacillus species is opening pharmaceutical-grade applications previously closed to single-strain products.
- Direct-to-manufacturer platforms:Digital procurement channels are disintermediating traditional ingredient distributors for mid-volume nutraceutical buyers.
Industry Challenges
- Strain IP fragmentation:Patent thickets around CRISPR-edited Saccharomyces variants are complicating licensing negotiations for smaller fermentation houses.
- Organic certification timelines:EC 834/2007 compliance audits are extending new strain qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Yeast Market |
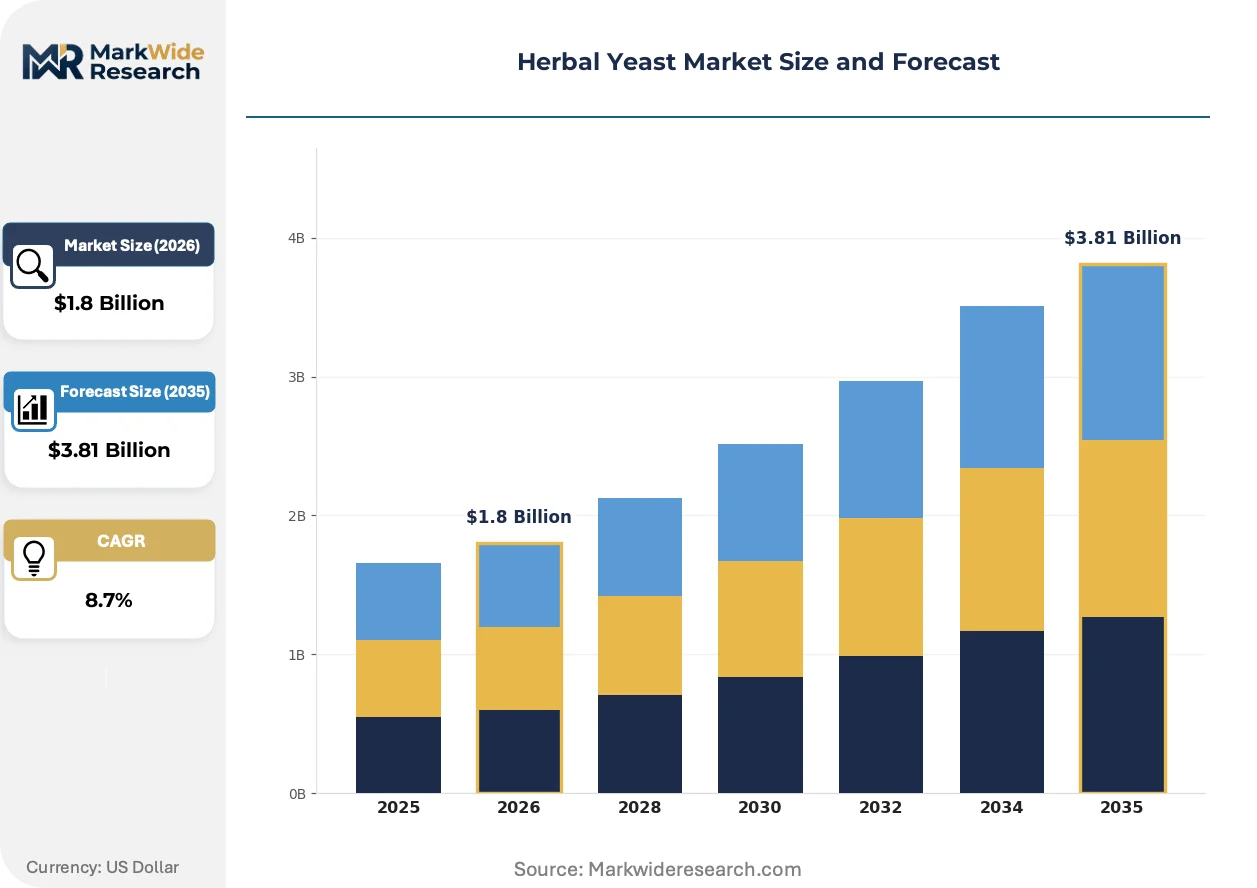
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Nutritional Yeast, Brewer's Yeast, Specialty Yeast End User: Food & Beverage Industry, Pharmaceuticals, Nutraceuticals, Animal Feed Application: Baking, Brewing, Fermentation, Dietary Supplements Form: Powder, Granules, Liquid, Tablets |
| Companies Covered | Lesaffre Group, Angel Yeast Co., Ltd., Lallemand Inc., Associated British Foods plc, DSM-Firmenich, Biospringer, Titan Biotech Ltd., Biorigin, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Yeast Market Evolving Landscape
Enzymatic cell wall disruption and precision fermentation are converging to reshape how bioactive metabolites are extracted and standardized. These advances are compressing the gap between pharmaceutical-grade and food-grade supply.
Subcritical water extraction is unifying purification efficiency with clean-label positioning by eliminating organic solvent residues. German and Dutch nutraceutical manufacturers are adopting these systems at pilot scale. The technology is unifying aqueous processing with beta-glucan yield parity previously achievable only through hexane-based methods.
EFSA's evolving novel food guidance on genetically edited microorganisms is tightening pre-market safety data requirements for engineered yeast strains. Fermentation houses are redirecting development budgets toward extensive toxicology dossiers. The regulation is compressing innovation cycles for synthetic biology startups while favoring established players with regulatory affairs infrastructure.
Buyer concentration among European contract manufacturers is shortening supplier qualification timelines and demanding real-time substrate traceability data. Traditional spot-market purchasing is giving way to multi-year offtake agreements with embedded quality audits. This shift is most visible in the German Rhineland corridor where bakery and supplement manufacturers have consolidated procurement functions.
Herbal Yeast Market Segmentation
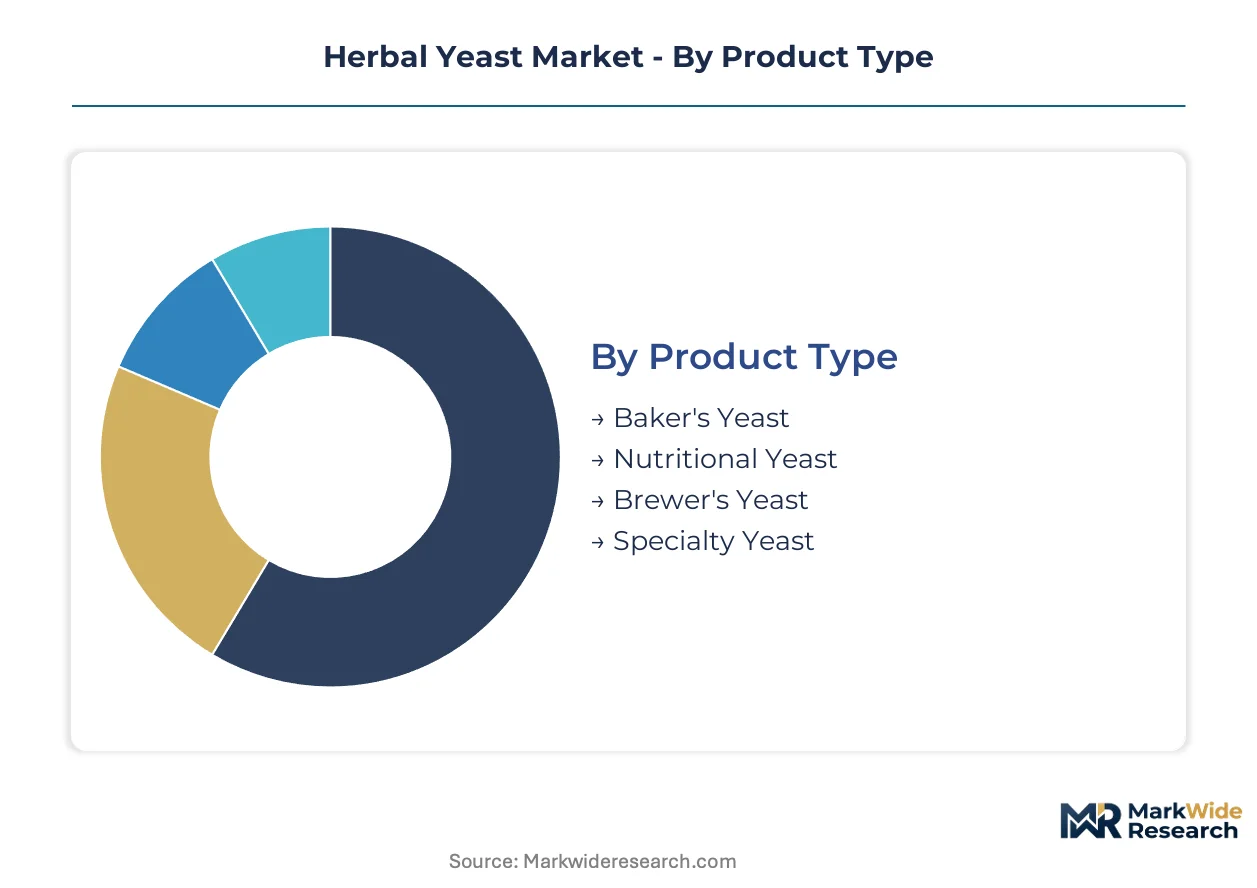
Herbal yeast segmentation reflects divergent margin structures across commodity fermentation and premium bioactive extraction. Product form and end-use specifications determine whether supply flows toward cost-sensitive baking operations or high-value nutraceutical contract manufacturers.
Product Type:
Upgrade cycles from commodity baker's yeast toward certified organic and beta-glucan-enriched variants are accelerating as clean-label requirements harden across European procurement specifications.
- Baker's Yeast:Standard Saccharomyces cerevisiae strains cultivated on molasses substrates dominate volume throughput in commercial baking operations. French and German industrial bakeries anchor procurement despite margin compression from sugar beet price volatility.
- Nutritional Yeast:Inactivated whole-cell preparations delivering 40-60% protein with intact B-vitamin complexes command premium positioning in vegan fortification and clean-label seasoning. Bavarian and Baden-Württemberg supplement manufacturers are consolidating supply relationships around certified organic strains with substrate traceability documentation.
- Brewer's Yeast:Spent brewing biomass repurposed for feed and lower-grade supplement applications faces displacement by purpose-cultivated alternatives with standardized metabolite profiles.
- Specialty Yeast:Beta-glucan extracts and probiotic-compatible strains serve pharmaceutical contract manufacturing with aqueous purification methods replacing restricted solvent-based processes.
Volume placements concentrate in Baker's Yeast; the faster expansion belongs to Specialty Yeast.
End User:
Customer-type stratification separates price-tolerant pharmaceutical buyers from cost-pressured feed compounders, with nutraceutical formulators occupying the contested middle ground demanding both certification and scale.
- Food & Beverage Industry:Industrial bakeries and fermentation-based food manufacturers procure standard-grade yeast for leavening and flavor development. German Rhineland corridor manufacturers have consolidated procurement functions around multi-year offtake agreements.
- Pharmaceuticals:CRISPR-edited strain libraries and co-fermentation capabilities with Lactobacillus species open parenteral and probiotic drug delivery applications. EFSA novel food guidance and extensive toxicology dossier requirements favor established players with regulatory infrastructure over synthetic biology startups.
- Nutraceuticals:Immune-modulating beta-glucan extracts and whole-cell nutritional supplements drive demand for organic-certified substrates. Procurement is shifting from spot-market purchasing toward embedded quality audit contracts.
- Animal Feed:Protein fortification and gut health applications in poultry and aquaculture operations compete with pea and fava protein isolates for clean-label positioning.
Revenue margins peak in Pharmaceuticals; the steepest volume climb is occurring in Nutraceuticals.
Application:
Application maturity varies from centuries-old baking traditions to emerging precision fermentation platforms, with extraction technology advances compressing the gap between food-grade and pharmaceutical-grade supply.
- Baking:Leavening applications in artisanal and industrial bread production retain volume leadership but face substitution risk from chemical raising agents in cost-sensitive markets.
- Brewing:Ethanol fermentation for beverage production and biofuel applications depends on sugar feedstock economics and molasses supply stability.
- Fermentation:Precision platforms for metabolite production and enzyme generation are gaining share fastest as subcritical water extraction and enzymatic cell wall disruption mature at pilot scale.
- Dietary Supplements:Capsule and tablet formulations of beta-glucan extracts and whole-cell nutritional yeast serve immune health positioning. German and Dutch manufacturers are adopting aqueous processing systems to eliminate solvent residues.
Established throughput centers on Baking; the frontier of value creation is shifting toward Fermentation.
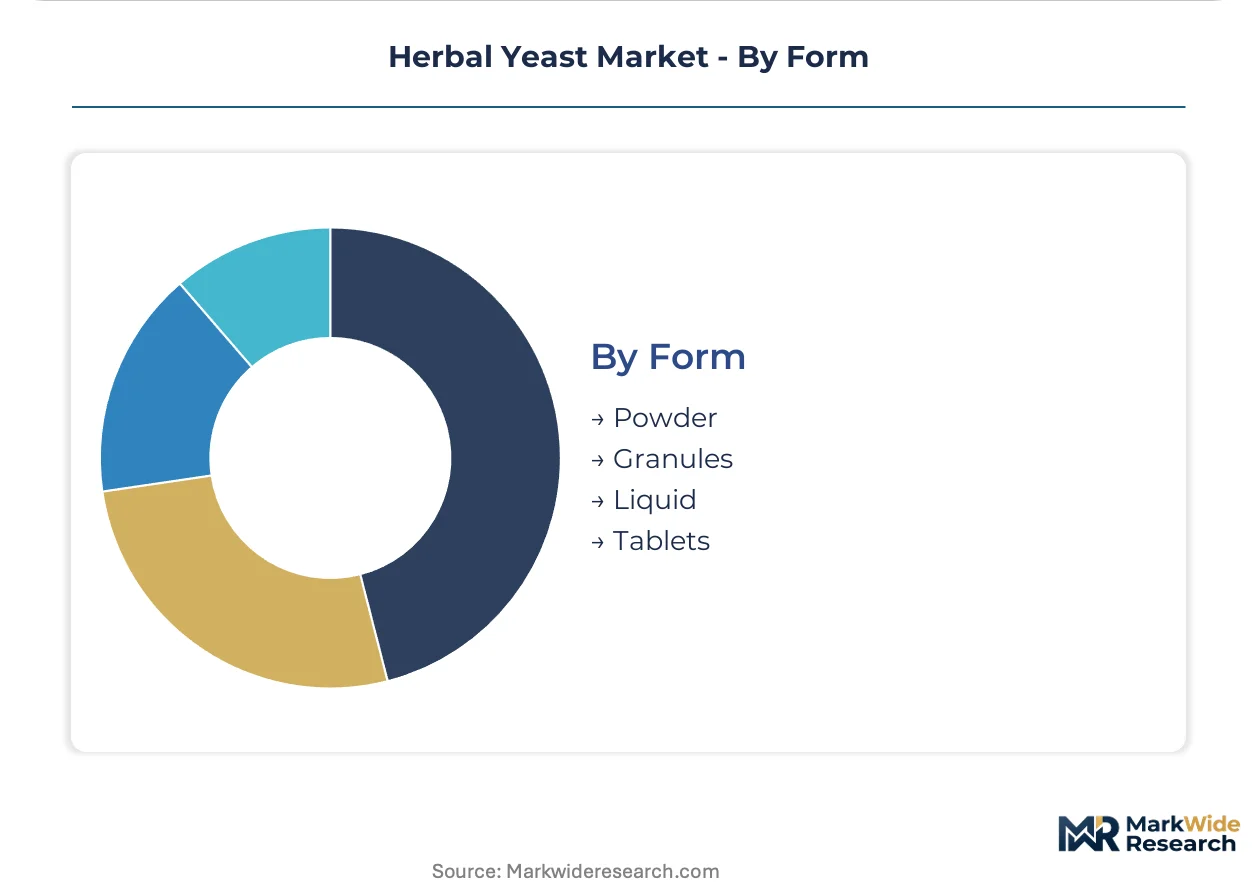
Form:
Physical format selection traces directly to downstream processing requirements and shelf-stability specifications across divergent supply chain temperature controls.
- Powder:Spray-dried preparations dominate bulk ingredient handling and reconstitution flexibility in industrial food manufacturing.
- Granules:Free-flowing agglomerated forms improve dispersibility in beverage applications and reduce dust exposure in handling operations.
- Liquid:Cream yeast and live culture suspensions serve regional bakery distribution with constrained shelf life and cold chain requirements.
- Tablets:Compressed dosage forms for direct-to-consumer supplement channels command finished goods margins but require additional excipient and coating processing.
Industrial procurement favors Powder; the premium conversion rate is highest in Tablets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German Rhineland corridor anchors procurement concentration for herbal yeast derivatives, with Bavarian supplement manufacturers driving certified organic demand across Northern Europe.
Germany
Baden-Württemberg nutraceutical formulators consolidate supply relationships around substrate-traceable beta-glucan extracts. The EU Nutrition and Health Claims Regulation redirects R&D toward clinically validated immune modulators. Bavarian contract manufacturers embed multi-year offtake agreements with real-time quality audit requirements.
France
Sugar beet harvest volatility in northern growing regions squeezes commodity baker's yeast margins while driving specialty yeast investment. REACH and the F-Gas Regulation block hexane extraction expansion, redirecting capital toward aqueous purification. Lesaffre Group leverages vertically integrated fermentation networks from its French base to secure premium positioning.
Spain
Andalusian olive processors develop captive yeast cultivation on pomace waste streams for export to Northern European supplement markets. EC 834/2007 organic certification timelines extend new strain qualification cycles. The region's biomass conversion infrastructure concentrates near Seville and Córdoba.
Netherlands
Dutch nutraceutical manufacturers pilot subcritical water extraction systems to eliminate solvent residues from beta-glucan purification. EFSA novel food guidance tightens pre-market safety data requirements for engineered strains. Rotterdam-area logistics hubs facilitate just-in-time delivery to German Rhineland buyers.
United States
FDA GRAS self-affirmation pathways attract specialty yeast products seeking faster market entry than European novel food routes. Precision fermentation startups face compressed innovation cycles from extensive toxicology dossier requirements. California and Northeast corridor nutraceutical buyers demand clean-label substrate documentation.
Herbal Yeast Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and extraction technology tiers. The vendor base stratifies between vertically integrated fermentation houses with captive strain libraries and regional distributors dependent on spot-market feedstock. Three archetypes dominate: legacy yeast multinationals with pharmaceutical-grade infrastructure, Asian scale producers anchoring baking and brewing volume, and biotechnology specialists pursuing CRISPR-edited strain IP. Consolidation pressures favor backward integration into substrate supply and aqueous extraction capacity expansion.
Within the legacy multinational tier, Lesaffre Group and DSM-Firmenich occupy positions defined by regulatory affairs infrastructure and vertically controlled supply networks. Angel Yeast Co., Ltd. represents the scale-driven Asian archetype, while Lallemand Inc. exemplifies the specialty biotechnology positioning. These three anchors illustrate how competitive differentiation traces to certification depth, extraction method, and strain library breadth rather than volume alone.
| Leading Market Players |
|---|
| Lesaffre Group |
| Angel Yeast Co., Ltd. |
| Lallemand Inc. |
| Associated British Foods plc |
| DSM-Firmenich |
| Biospringer |
| Titan Biotech Ltd. |
| Biorigin |
| Kerry Group plc |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as aqueous extraction infrastructure investments separate certified organic strains from commodity-grade alternatives. German nutraceutical buyers now demand substrate traceability documentation as a non-negotiable entry ticket to contract negotiations, compressing spot-market participation to uncertified feedstock tiers.
Pricing Analysis
Yield-locked value-based pricing anchors beta-glucan extract quotations to immune-modulation efficacy benchmarks rather than input weight. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels reflects extraction method and organic compliance depth. Cost compression in commodity baker's yeast intensifies because molasses supply volatility from French sugar beet harvests squeezes standard-tier margins. Industrial bakeries exhibit highest price sensitivity; pharmaceutical contract manufacturers tolerate premium positioning for strain-documented supply.
Supply Chain Analysis
Refrigerated freight cost premiums from Spanish olive processing clusters to Northern European supplement manufacturers compress margin capture for pomace-derived yeast biomass. Supply concentrates in France, Germany, and China, with fermentation capacity anchored in the Rhineland corridor and Angel Yeast's concentrated Asian production bases. Raw material dependencies center on molasses substrates, botanical waste streams, and enzymatic processing reagents. Single-source vulnerability runs through CRISPR-edited strain IP controlled by legacy multinationals. Distribution runs through just-in-time logistics hubs serving Bavarian contract manufacturers with embedded quality audit requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification audit capacity serves as the binding constraint propping premium-tier pricing, as EC 834/2007 compliance timelines extend strain qualification cycles beyond competitor replication speed.
For Market Incumbents: Acquire aqueous extraction technology assets to replace hexane-dependent infrastructure blocked by REACH restrictions. Consolidate backward integration into olive pomace and spent grain substrate supply in Andalusia. Defend against precision fermentation startups by accelerating toxicology dossier submissions ahead of EFSA novel food guidance tightening. For New Entrants and Emerging Players: Enter via direct-to-manufacturer digital procurement platforms disintermediating traditional ingredient distributors. Target mid-volume nutraceutical buyers in the German Rhineland corridor seeking certified organic alternatives to Lesaffre and DSM-Firmenich supply. Exploit white-space in co-fermentation strain development for probiotic-compatible applications. For Investors and Strategic Acquirers: Multi-year offtake agreement announcements from Bavarian contract manufacturers are the leading indicator that premium-tier capacity is achieving revenue visibility. Long-term viability favors vertically integrated fermentation houses with captive strain libraries and regulatory affairs infrastructure over synthetic biology startups facing compressed innovation cycles. Monitor EFSA novel food petition submission volumes as inflection signal for engineered strain commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive olive pomace and spent grain access secures cost-advantaged organic certification pathways for Northern European buyers. |
| Aqueous Extraction Capacity Expansion | Subcritical water systems bypass F-Gas Regulation constraints while delivering pharmaceutical-grade beta-glancan purity. |
| Probiotic Strain Co-Fermentation Development | Lactobacillus-compatible libraries open parenteral applications previously closed to single-strain Saccharomyces products. |
| Direct-to-Manufacturer Platform Launch | Digital procurement channels capture margin from disintermediated distributor relationships in mid-volume supplement segments. |
| Organic Certification Fast-Track Investment | EC 834/2007 audit infrastructure compresses 18-24 month qualification cycles to secure first-mover supply contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fermentation plant managers, nutraceutical procurement leads, regulatory affairs directors at EFSA and FDA, and distribution channel partners. FDA GRAS affirmation petitions, EFSA novel food submissions, EU organic certification databases, and molasses import customs records provided validation benchmarks. Bottom-up strain-level production estimates triangulated against top-down regional consumption models.
Segmentation granularity modeled product type at the strain-certification tier, end user at the procurement function consolidation level, application at the extraction technology generation, and form at the cold chain requirement band. CAGRs derived from logistic curve fitting to certified organic penetration rates and aqueous extraction adoption slopes across the projection horizon. Molasses price volatility indices and EFSA petition approval timelines served as industry-specific forecast modifiers.
Revisions become necessary when REACH solvent restrictions tighten beyond current aqueous processing parity, EFSA novel food guidance shifts genetically edited microorganism requirements, or organic certification audit capacity fails to match strain development velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market