
 Probiotic for Men Market | 2026-2036
Probiotic for Men Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic for Men Market Insights
North American contract manufacturing capacity for men's probiotics is hardening as specialized fermentation facilities expand output. Seed Health leverages vertically integrated strain development to control quality from culture bank to capsule. BioGaia anchors its position through patented Lactobacillus reuteri strains with documented male-targeted clinical endpoints. NOW Foods competes on manufacturing scale, sustaining broad distribution across mass-market retail and practitioner channels.
Probiotic for men denotes live microbial formulations containing defined CFU counts of bacterial strains selected for male physiology, typically delivered in gastric-resistant capsules or sachets to ensure colonization of the lower gastrointestinal tract; these products modulate gut microbiota composition to support digestive efficiency, immune modulation, and androgen-influenced metabolic pathways. Capsule formats dominate current revenue due to convenience and moisture-stable packaging, while powders gain traction among fitness-oriented consumers blending into protein shakes. Digestive health applications retain the largest volume base, though immune support and urinary tract health segments show faster expansion as urogenital-specific strains enter commercialization.
FDA's New Dietary Ingredient notification framework and EFSA's health claims substantiation requirements shape formulation strategies and market access timelines for cross-border brands. The EU's Nutrition and Health Claims Regulation constrains marketing language, pushing companies toward investment in human intervention studies for strain-specific dossiers. Stakeholders must monitor evolving strain-level regulatory classifications and build clinical evidence portfolios before entering jurisdictions with active pre-market approval regimes.
Market Dynamics
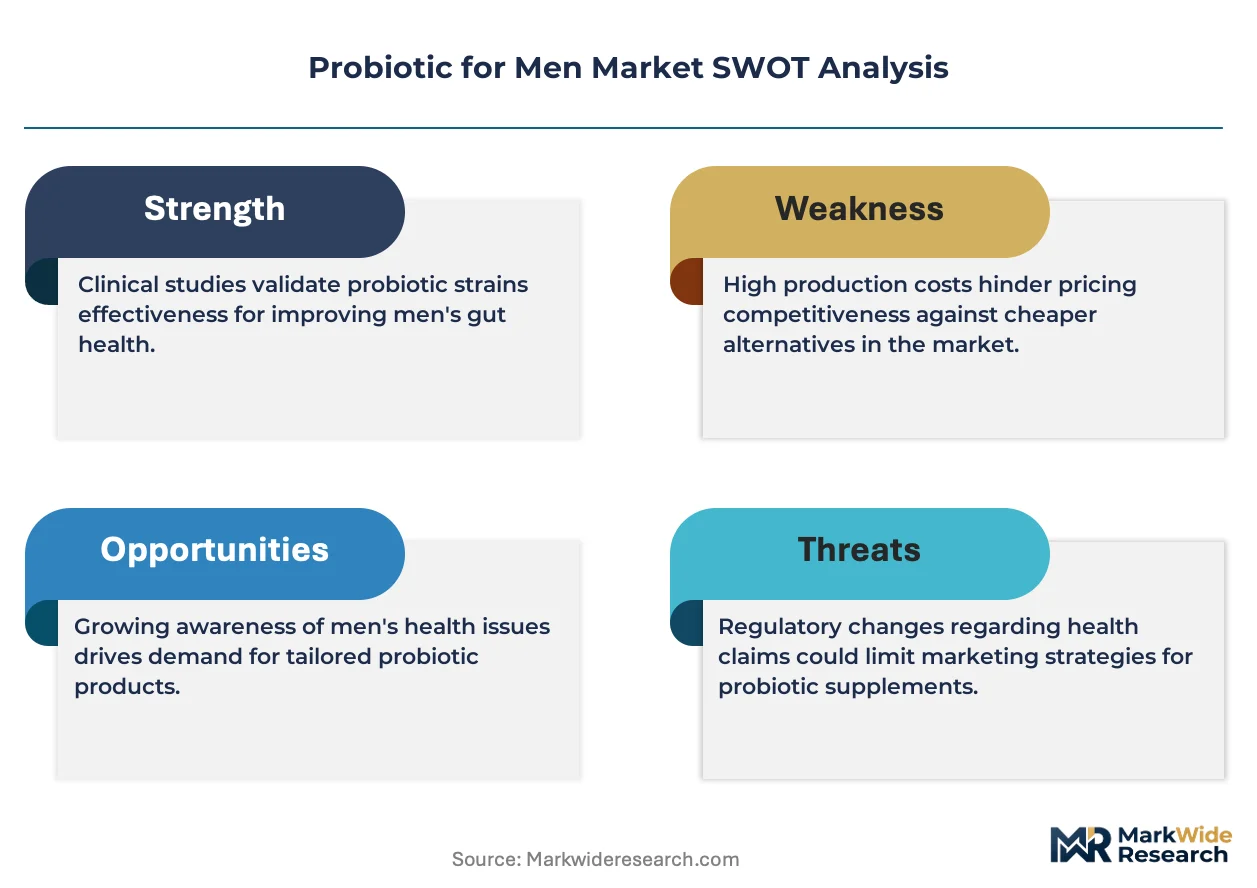
Strain-specific clinical documentation requirements from FDA and EFSA are forcing manufacturers to abandon generic formulations and invest in human intervention studies for male-targeted endpoints. This regulatory pivot concentrates competitive advantage among firms with captive fermentation capacity and in-house research infrastructure.
Growth Catalysts
- EFSA Health Claims Substantiation:Strain-level dossier requirements push manufacturers toward clinically validated formulations with documented male physiological endpoints, elevating product credibility and pricing power.
- Sports Nutrition Channel Expansion:Dedicated men's probiotic SKUs now occupy standard shelf positions in North American retail chains, normalizing consumption among fitness-oriented demographics.
- Direct-to-Consumer Subscription Models:Automated replenishment platforms in the United States reduce customer acquisition costs and improve lifetime value metrics for gut health brands.
Market Restraints
- Specialized Fermentation Capacity Scarcity:Contract manufacturing for clinically documented strains concentrates among a limited number of facilities with GMP-compliant culture banks, creating supply bottlenecks.
- Live Culture Stability Constraints:Moisture and temperature sensitivity during distribution limits shelf life and complicates logistics for products requiring cold chain integrity.
- FDA New Dietary Ingredient Notification Burden:Pre-market safety documentation requirements delay product launches and inflate regulatory compliance costs for novel strain introductions.
Strategic Opportunities
- Urogenital Health Applications:Commercialization of strains targeting urinary tract and prostate-specific endpoints opens underserved therapeutic categories beyond digestive positioning.
- Powder Format Penetration:Fitness consumers blending probiotics into protein shakes create demand for sachet and bulk powder delivery systems with flavor-masking technologies.
- Practitioner Channel Development:Functional medicine and urology clinics represent high-trust distribution pathways for premium formulations with clinical documentation.
Industry Challenges
- Strain Characterization Expertise Gap:Manufacturers lack sufficient microbiologists and bioinformaticians to execute whole-genome sequencing and phenotypic profiling required for regulatory dossiers.
- Cross-Jurisdictional Labeling Complexity:Divergent CFU count disclosure standards and health claim permissible language between FDA and EFSA frameworks complicate global SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic for Men Market |
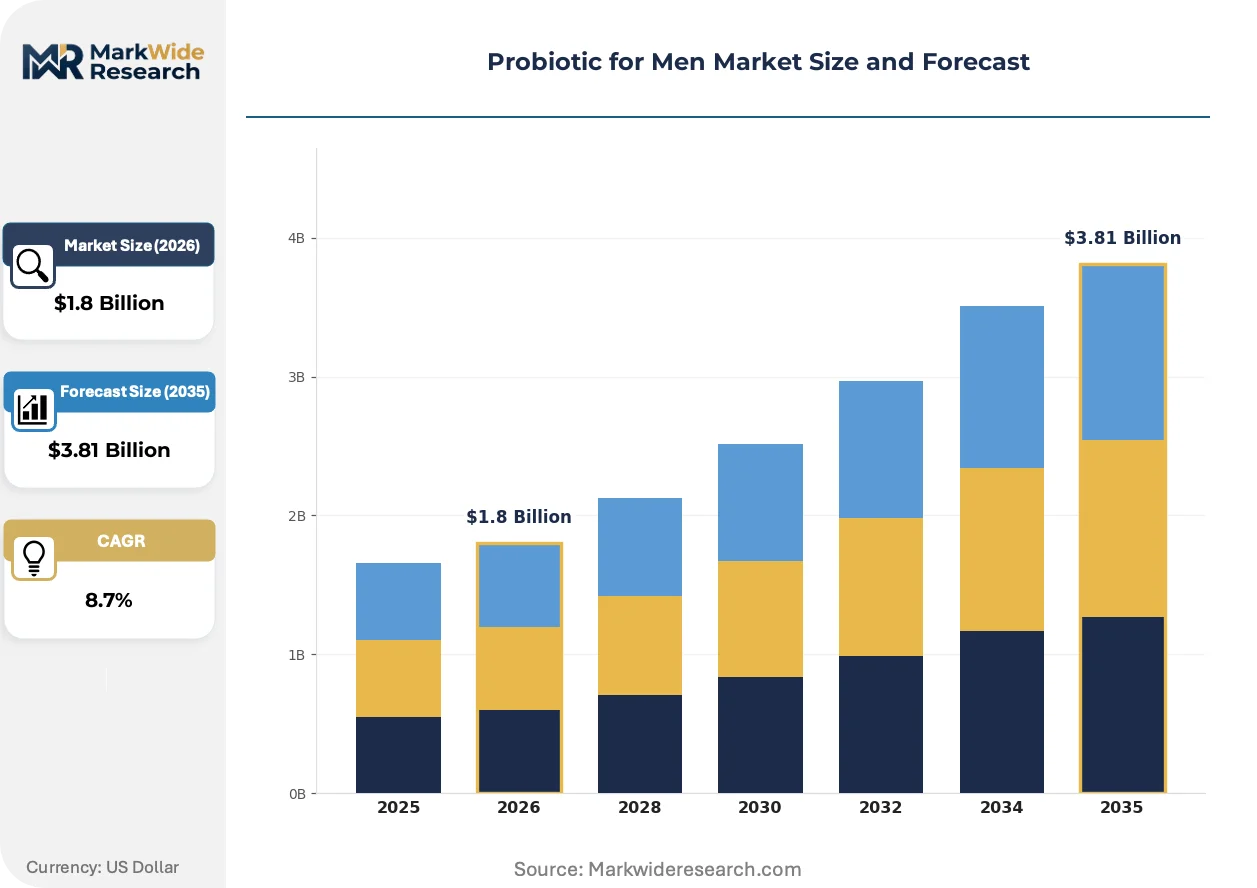
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquids, Chewables, Tablets Application: Digestive Health, Immune Support, Urinary Tract Health, Mental Wellness, Skin Care End User: Gyms & Fitness Centers, Pharmacies, Nutritionists, Sports Clubs Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Seed Health, Ritual, BioGaia, Yakult Honsha, Nestlé, Reckitt Benckiser Group, Church and Dwight, NOW Foods, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic for Men Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how male-targeted probiotics reach consumers. Three developments dominate current competitive maneuvering.
Multi-strain synbiotic formulations combining probiotics with targeted prebiotic substrates are overtaking single-strain legacy products in premium positioning. Sports nutrition brands and functional medicine practitioners are accelerating adoption of these advanced combinations. The shift is compressing margins for basic CFU-count marketing and rewarding integrated microbiome modulation claims.
EFSA's tightening enforcement of the Nutrition and Health Claims Regulation is elevating investment thresholds for European market access. Manufacturers now commission human intervention studies before commercial launch rather than retrofitting claims post-entry. Powder formats and practitioner-exclusive lines bear the heaviest compliance burden as direct-to-consumer marketing faces stricter substantiation scrutiny.
Subscription-based replenishment models are displacing traditional retail replenishment cycles among United States consumers. Fitness-oriented buyers and chronic condition managers favor automated delivery with microbiome testing integration. This behavioral shift concentrates customer lifetime value metrics with brands owning direct relationships rather than retail intermediaries.
Probiotic for Men Market Segmentation
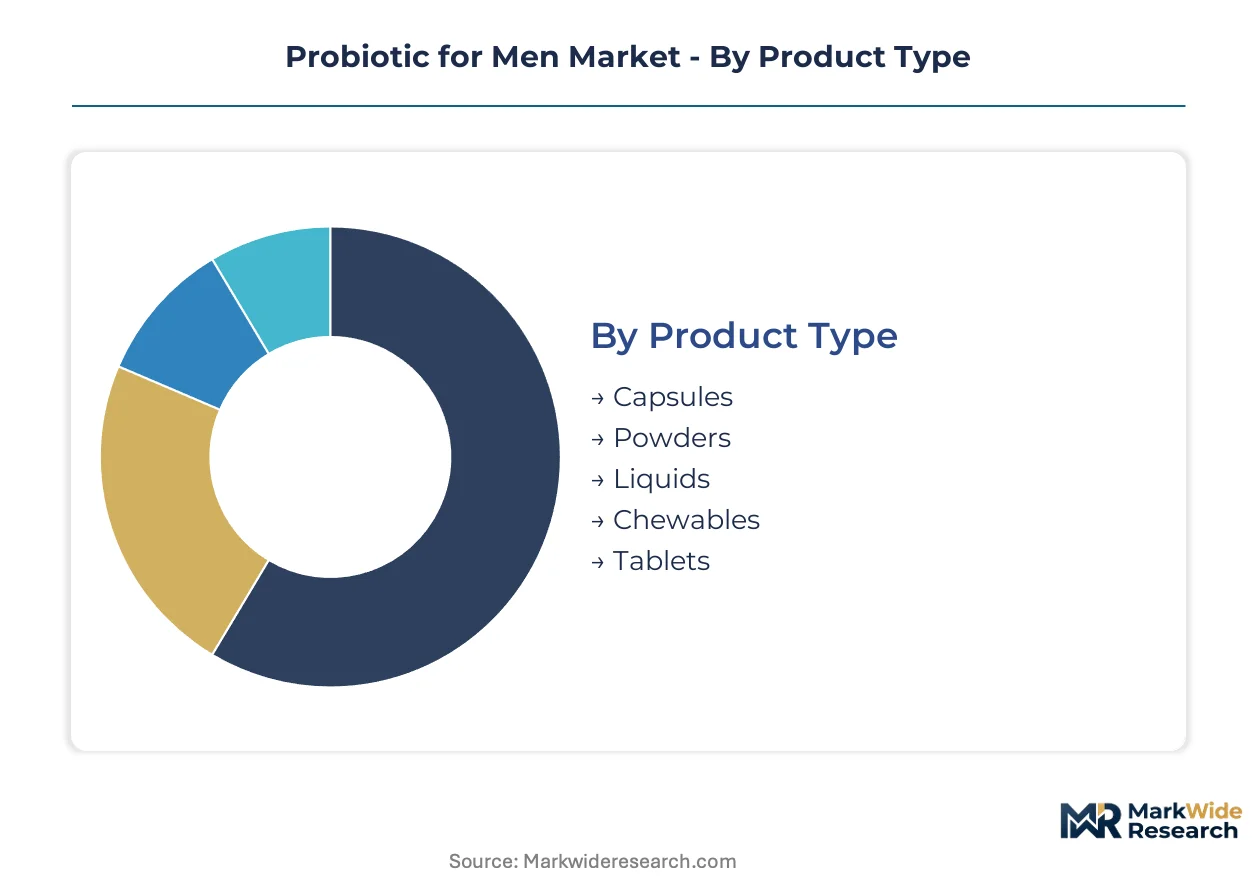
Segmentation in the men's probiotic market reveals divergent capital requirements and margin structures across delivery formats and therapeutic positioning. Manufacturers must align fermentation capacity investments with the stability demands and clinical substantiation burdens of each product category.
Product Type:
Capsule manufacturing demands the heaviest upfront investment in moisture-barrier packaging lines and gastric-resistant coating technology, while powder production requires specialized flavor-masking and cold-chain infrastructure.
- Capsules:Gastric-resistant shell technology protects live cultures through stomach acid to ensure colonization of the lower gastrointestinal tract. United States direct-to-consumer brands concentrate demand here, driven by convenience preferences and moisture-stable shelf positioning. Capsule formats absorb the bulk of installed capacity; powders are expanding most quickly.
- Powders:Sachet and bulk formats enable blending into protein shakes for fitness-oriented consumers, requiring flavor-masking investments and cold-chain integrity. North American sports nutrition aisles now stock dedicated SKUs targeting this behavior.
- Liquids:Refrigerated distribution requirements and shorter shelf lives limit commercial penetration to practitioner channels with controlled storage.
- Chewables:Palatability engineering and moisture sensitivity constraints concentrate production among specialized contract manufacturers.
- Tablets:Compression heat during manufacturing reduces viable CFU counts, restricting adoption to lower-potency mass-market positioning.
Capsule lines dominate current manufacturing footprints; powder capacity is scaling fastest to serve fitness channel expansion.
Application:
Clinical substantiation costs vary sharply across therapeutic endpoints, with urogenital health applications requiring the most extensive human intervention studies for regulatory approval.
- Digestive Health:Established strain libraries and well-documented mechanisms reduce R&D burden for basic gut microbiota modulation. This foundational positioning commands the largest volume base across retail and practitioner channels.
- Immune Support:Strain-specific immunomodulatory claims require EFSA health claims substantiation dossiers, elevating investment thresholds for European market access.
- Urinary Tract Health:Urogenital-specific strains with documented male physiological endpoints open underserved therapeutic categories beyond digestive positioning. EFSA and FDA strain-level documentation requirements concentrate competitive advantage among firms with captive research infrastructure.
- Mental Wellness:Gut-brain axis claims face heightened regulatory scrutiny, delaying commercialization timelines for novel strain introductions.
- Skin Care:Dermatological endpoints remain niche, with demand concentrated among premium positioning in specialty retail.
Digestive applications anchor current revenue; urinary tract health is climbing the fastest as urogenital-specific strains enter commercialization.
End User:
Channel-specific compliance requirements and trust dynamics shape customer acquisition costs, with practitioner channels demanding the most extensive clinical documentation.
- Gyms & Fitness Centers:Sports nutrition integration drives powder format adoption, with automated replenishment platforms reducing customer acquisition costs.
- Pharmacies:Mass-market retail requires broad distribution infrastructure and competes on manufacturing scale across standard shelf positions.
- Nutritionists:Functional medicine practitioners represent high-trust distribution pathways for premium formulations with clinical documentation.
- Sports Clubs:Team-based procurement concentrates volume among specialized suppliers with bulk powder capabilities.
Pharmacy channels absorb the bulk of volume throughput; nutritionist-directed sales are gaining share fastest.
Distribution Channel:
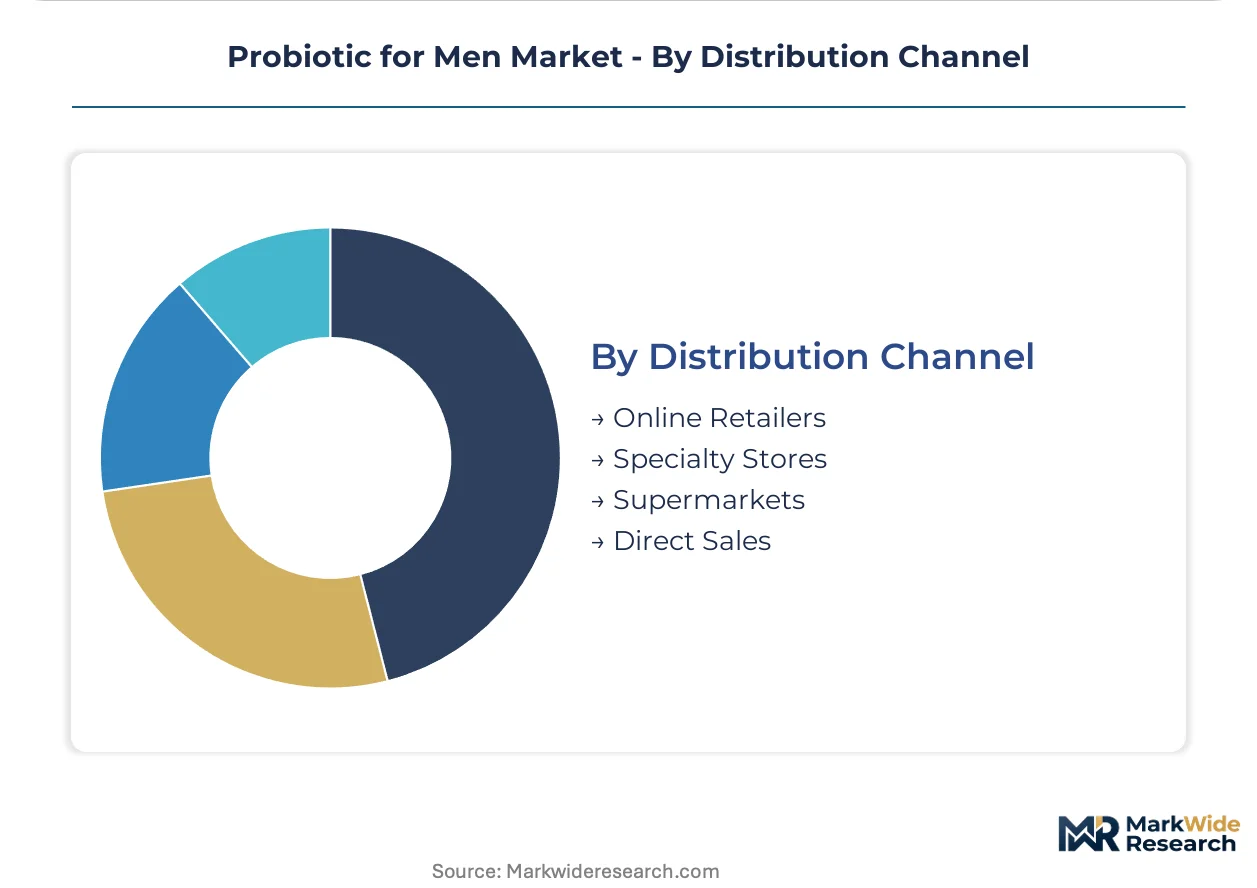
Fulfillment infrastructure requirements diverge sharply, with direct-to-consumer models demanding the most sophisticated subscription platform investment.
- Online Retailers:Automated replenishment platforms concentrate customer lifetime value metrics with brands owning direct relationships rather than retail intermediaries.
- Specialty Stores:Curated positioning supports premium pricing for clinically documented formulations with strain-specific labeling.
- Supermarkets:Mass-market penetration competes on manufacturing scale and moisture-stable packaging for standard shelf placement.
- Direct Sales:Practitioner-exclusive lines bear the heaviest compliance burden as EFSA tightens enforcement of health claims substantiation requirements.
Online retail absorbs the bulk of growth investment; specialty stores are expanding most quickly for premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-grade dextrose and specialized culture media production concentrates in the United States Midwest and German Rhineland, anchoring upstream supply for men's probiotic manufacturing. Clinical documentation requirements from FDA and EFSA are redrawing competitive maps as brands prioritize jurisdictions with established regulatory pathways.
United States
Direct-to-consumer subscription platforms for men's gut health have achieved mainstream penetration, with automated replenishment models concentrating customer lifetime value. FDA's New Dietary Ingredient notification framework shapes pre-market timelines and compliance investment. Chicago and Minneapolis host specialized contract fermentation facilities expanding GMP-compliant capacity for clinically documented strains.
Germany
EFSA's Nutrition and Health Claims Regulation enforcement elevates investment thresholds for strain-specific dossiers with male physiological endpoints. The country's central pharmaceutical regulator demands human intervention studies before commercial launch rather than post-entry retrofitting. Frankfurt and Mannheim industrial clusters concentrate captive fermentation infrastructure for premium practitioner-channel formulations.
Japan
Functional food traditions normalize daily probiotic consumption among male demographics, with Yakult-style delivery systems penetrating workplace and retail channels. METI standards for functional food claims require documented safety and efficacy profiles. Tokyo-Osaka corridor manufacturing bases supply both domestic demand and export markets across Asia-Pacific.
Canada
Health Canada's Natural Health Product Directorate imposes strain-level identification and stability testing requirements that parallel FDA frameworks. Cross-border regulatory alignment facilitates US brand expansion through Health Canada site licensing. Toronto and Vancouver serve as distribution hubs for North American mass-market and practitioner channels.
Australia
TGA's Listed Medicine framework permits probiotic indications while requiring evidence of quality and safety for male-targeted positioning. Sports nutrition integration drives powder format adoption among fitness-oriented consumers. Sydney and Melbourne host specialized logistics infrastructure for cold-chain probiotic distribution across domestic retail networks.
Probiotic for Men Market Competitive Landscape
Global majors compete with regional champions across clinical documentation infrastructure and captive fermentation capacity. Market structure shows moderate consolidation among vertically integrated strain developers, with tiered competition separating premium clinically documented formulations from mass-market CFU-count positioning. Strategic archetypes include integrated microbiome biotechnology firms, scale-driven contract manufacturers, and direct-to-consumer wellness platforms. Dominant competitive moves center on backward integration into strain banking and geographic licensing partnerships for regulatory dossier sharing.
Within the integrated biotechnology tier, Seed Health and BioGaia exemplify archetypes built on captive strain development and proprietary culture collections. NOW Foods occupies a position representing scale-driven manufacturing across mass-market retail and practitioner channels. Ritual and Ritual anchor the direct-to-consumer vector with subscription-first distribution models. These named entities sit within broader competitive dynamics where clinical evidence portfolios and fermentation capacity determine market access rather than marketing expenditure alone.
| Leading Market Players |
|---|
| Seed Health |
| Ritual |
| BioGaia |
| Yakult Honsha |
| Nestlé |
| Reckitt Benckiser Group |
| Church and Dwight |
| NOW Foods |
| Herbalife Nutrition |
| Others |
Pricing and Supply Chain Analysis
Fermentation-grade dextrose spot prices in the United States Midwest cascade through men's probiotic manufacturing into three-tier pricing structure across premium, standard, and economy levels. Chicago and Minneapolis culture bank facilities transmit cost volatility downstream, compressing margins at mass-market tiers while practitioner-channel premiums absorb input fluctuations through subscription lock-in.
Pricing Analysis
Extended stability warranties and cold-chain integrity guarantees bundle into practitioner-channel subscriptions, while mass-market SKUs strip these services to hit retail price points. Three-tier pricing structure across premium, standard, and economy levels separates strain-documented formulations from basic CFU-count positioning. Cost compression in economy tiers intensifies because generic strain suppliers compete on manufacturing scale. Fitness-oriented direct-to-consumer buyers show lowest price sensitivity; supermarket mass-market segments demand per-capsule cost minimization.
Supply Chain Analysis
Expired culture returns and fermentation media recycling flows concentrate at specialized Midwest facilities, creating reverse-logistics infrastructure that standard probiotic manufacturers lack. Live culture production draws from United States, Germany, and Japan fermentation clusters. Raw material dependencies include pharmaceutical-grade dextrose, specialized nitrogen sources, and gastric-resistant capsule polymers. Single-source vulnerability concentrates at GMP-compliant culture banks with documented male-targeted strain libraries. Distribution runs through direct-to-consumer subscription platforms, practitioner-exclusive lines, and mass-market retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Men's probiotic manufacturing is transitioning from generic CFU-count formulations to strain-specific clinical documentation, with multi-strain synbiotic technologies displacing legacy single-strain products. This shift elevates investment thresholds and concentrates competitive advantage among firms with captive research infrastructure.
For Market Incumbents: Acquire specialized fermentation facilities with GMP-compliant culture banks and documented male physiological endpoints. Seed Health's vertically integrated model demonstrates how strain development control insulates against FDA New Dietary Ingredient notification delays. Incumbents must consolidate practitioner-channel relationships before EFSA health claims substantiation requirements harden further. For New Entrants and Emerging Players: Launch via automated replenishment platforms targeting fitness-oriented demographics with powder-format synbiotic positioning. Urinary tract health applications remain underpenetrated relative to digestive positioning, offering white-space entry with lower clinical documentation burdens than immune or gut-brain axis claims. Direct microbiome testing integration creates differentiated subscription stickiness. For Investors and Strategic Acquirers: The window for entry favors vertically integrated microbiome biotechnology firms with proprietary strain collections and in-house bioinformatics capabilities. Long-term viability hinges on regulatory dossier depth rather than marketing expenditure. Watch EFSA enforcement patterns and FDA strain-level classification updates as inflection indicators for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Acquisition | Captive Lactobacillus reuteri and male-targeted strain libraries secure regulatory dossier control against FDA notification delays. |
| Synbiotic Formulation Launch | Prebiotic-probiotic combinations command premium positioning as EFSA tightens single-strain health claims enforcement. |
| Direct-to-Consumer Platform Buildout | Subscription models with microbiome testing integration concentrate customer lifetime value away from retail intermediaries. |
| Practitioner Channel Partnership | Functional medicine and urology clinic relationships provide high-trust distribution for clinically documented formulations. |
| Powder Format Capacity Expansion | Fitness channel penetration demands flavor-masking technology and cold-chain infrastructure for protein shake integration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving fermentation facility operators, regulatory affairs specialists at probiotic manufacturers, functional medicine practitioners, sports nutrition buyers, and direct-to-consumer brand executives. FDA New Dietary Ingredient notifications, EFSA health claims substantiation dossiers, and Health Canada Natural Health Product registrations provided strain-level commercialization timelines. Bottom-up capacity modeling at individual fermentation facilities combined with top-down retail audit data across United States, German, and Japanese distribution channels.
Segmentation granularity extended to delivery format stability requirements, therapeutic application clinical substantiation burdens, and channel-specific compliance frameworks across the projection horizon. Strain-specific versus generic formulation splits, subscription versus transactional revenue mixes, and practitioner versus mass-market channel shares were modeled at country level. CAGRs derived from triangulated capacity expansion announcements, retail SKU velocity indicators, and regulatory approval pipeline tracking. Human intervention study investment flows and culture bank certification timelines served as industry-specific forecast inputs.
Strain characterization expertise shortages, divergent CFU disclosure standards between FDA and EFSA frameworks, and live culture stability failures during distribution are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory enforcement continuity and fermentation capacity scaling timelines. Practitioners should monitor EFSA health claims substantiation precedent cases and FDA strain-level classification updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
United States Probiotics Market