
 South America Probiotics Market | 2026-2036
South America Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Probiotics Market Analytics
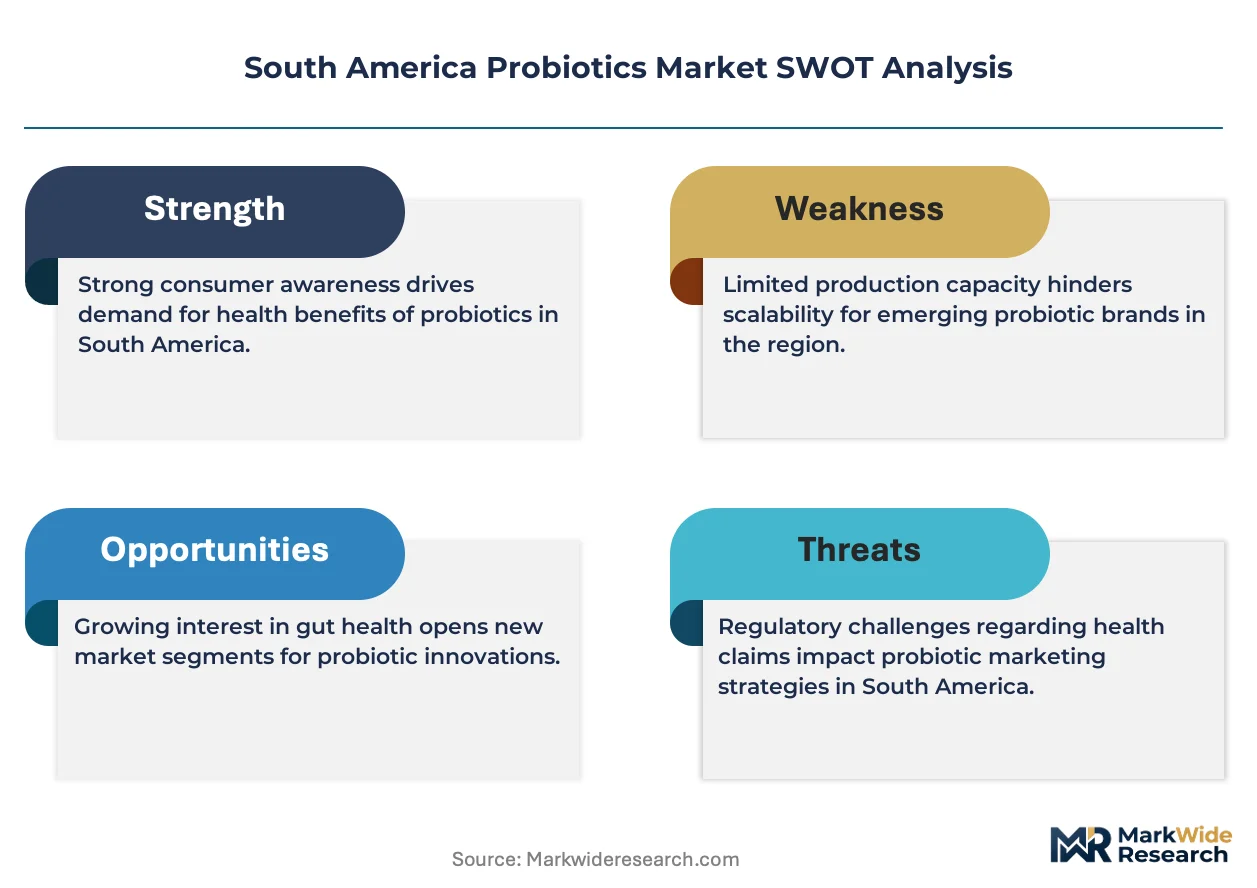
Pharmacy and health store distribution networks across South America are reshaping how probiotic products reach consumers. Nestle SA leverages its dairy processing infrastructure to sustain shelf-stable probiotic yogurt lines across Brazilian retail. Groupe Danone anchors premium positioning through specialized fermentation capabilities in Argentina. Chr. Hansen competes via strain development partnerships with regional dairy cooperatives.
Probiotics comprise live microorganisms, typically Lactobacillus and Bifidobacterium species at minimum viable counts of 10^6 to 10^9 colony-forming units per serving, delivered through fermented foods, capsules, or powders to confer defined health benefits on the host. Food and beverages occupies the dominant volume position given entrenched yogurt and fermented milk consumption patterns across the region. Dietary supplements represents the fastest-expanding category as Brazilian and Colombian consumers shift toward capsule and sachet formats for targeted gut health and immune support applications.
ANVISA governs novel food and ingredient approvals in Brazil, while Argentina's national food safety authority enforces labeling standards for live culture claims across dairy and supplement products. Both frameworks elevate compliance costs for new market entrants but simultaneously validate clinical efficacy requirements that protect established strain suppliers. Stakeholders must monitor pending harmonization discussions between Mercosur member states regarding mutual recognition of probiotic health claims.
Market Dynamics
ANVISA's 2023 novel food guideline revision compresses strain registration timelines from 24 months to 14 months, accelerating domestic and imported live culture approvals while intensifying competitive pressure on established Brazilian suppliers.
Growth Catalysts
- Strain-specific health claims:ANVISA's updated framework validates clinical efficacy requirements for digestive and immune benefits, enabling premium positioning for validated Lactobacillus and Bifidobacterium formulations.
- Fermented dairy infrastructure:Brazil's southeastern urban corridor spanning São Paulo, Rio de Janeiro, and Belo Horizonte concentrates cold chain distribution capacity and retail pharmacy networks.
- Dietary supplement format expansion:Capsule and sachet delivery systems attract Brazilian and Colombian consumers seeking targeted gut health applications beyond traditional yogurt consumption.
Market Restraints
- Live culture stability costs:Refrigerated transport requirements across Brazil's vast interior elevate last-mile logistics expenses for probiotic beverages and fresh fermented products.
- Strain supplier concentration:European and North American culture houses control premium validated strains, creating import dependency for Argentine and Colombian manufacturers.
- Mercosur claim harmonization delays:Pending mutual recognition discussions between Brazil, Argentina, Paraguay, and Uruguay fragment health claim standards across the customs union.
Strategic Opportunities
- Colombian pharmacy channel expansion:Health store networks in Bogotá and Medellín remain underdeveloped for probiotic supplements relative to Brazilian retail density.
- Shelf-stable formulation innovation:Spore-forming Bacillus strains and microencapsulation technologies enable ambient distribution without cold chain infrastructure.
- Argentine dairy cooperative partnerships:Regional fermentation facilities seek strain development alliances to reduce reliance on imported live cultures.
Industry Challenges
- Microbiome research talent scarcity:Clinical trial design and strain characterization expertise concentrates in São Paulo and Buenos Aires, creating recruitment bottlenecks for expansion programs.
- Multi-jurisdiction compliance complexity:Divergent labeling standards between ANVISA and Argentina's national food safety authority force duplicate testing protocols for cross-border products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Probiotics Market |
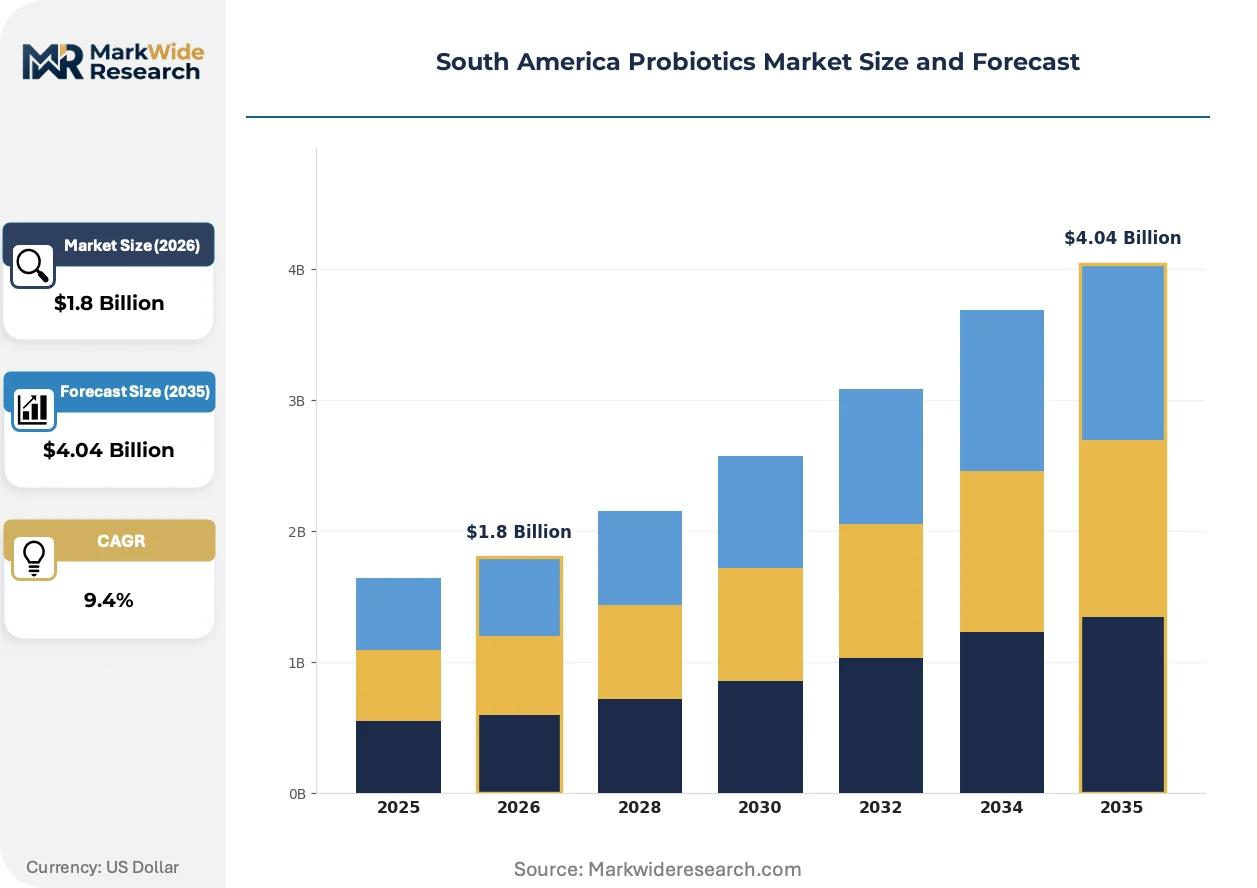
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food & Beverages, Dietary Supplements, Infant Formula, Animal Feed Application: Gut Health, Immune Support, Mental Health, Skin Health End User: Adults, Infants, Seniors, Athletes Distribution Channel: Supermarkets, Online Retail, Pharmacies, Health Stores |
| Companies Covered | Nestle SA, Groupe Danone, Yakult Honsha Co Ltd., Chr. Hansen, PepsiCo Inc., Fonterra Cooperative Group, Kerry Group plc, Beneo GmbH, Mastellone Hnos SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Probiotics Market Evolving Landscape
Digital traceability systems and next-generation sequencing are compressing product development cycles while reshaping how manufacturers validate strain efficacy and communicate provenance to health-conscious consumers.
Next-generation sequencing is digitizing strain identification and characterization workflows across Brazilian quality control laboratories. Mid-sized dairy processors in São Paulo and Minas Gerais adopt rapid metagenomic screening to verify live culture counts and detect contamination. This technology is digitizing compliance documentation, reducing batch release timelines from weeks to days while elevating competitive barriers for facilities lacking sequencing capacity.
ANVISA's streamlined novel food pathway is accelerating the transition from research strains to commercial ingredients. Argentine regulators are observing this framework for potential adoption, creating anticipatory investment in clinical trial infrastructure. Supplement manufacturers targeting cross-border Mercosur distribution must now design studies meeting Brazil's efficacy thresholds from inception.
Direct-to-consumer subscription models are displacing traditional pharmacy replenishment cycles among urban Brazilian professionals. São Paulo-based wellness platforms bundle personalized microbiome testing with curated probiotic regimens, bypassing retail markup structures. This channel rotation is most visible among consumers aged 25-40 in Brazil's southeastern cities, where digital health literacy and disposable income concentrate.
South America Probiotics Market Segmentation
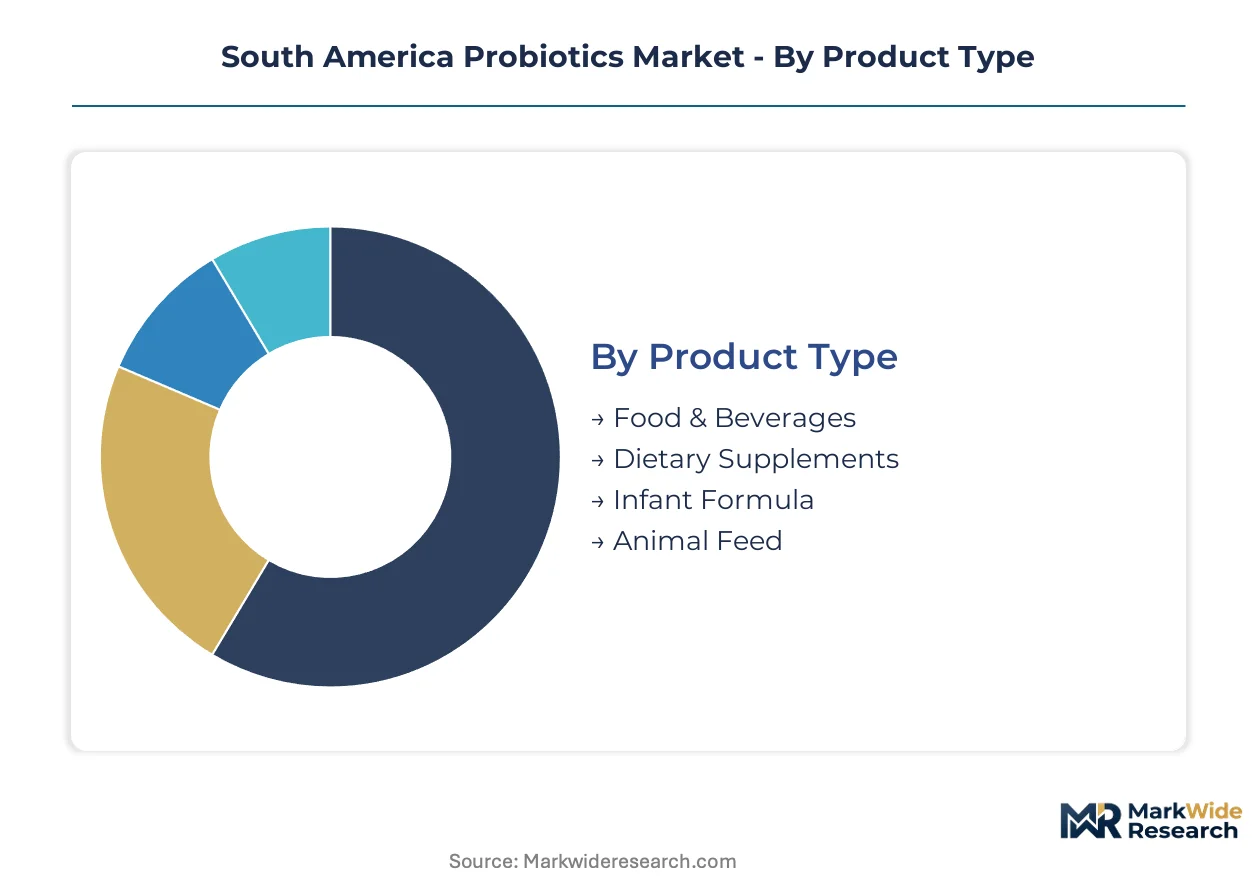
Probiotic manufacturers across South America configure product portfolios around four intersecting dimensions. Each segmentation axis carries distinct margin profiles, regulatory pathways, and shelf velocity characteristics that determine resource allocation between Brazilian, Argentine, and Colombian operations.
Product Type:
Inventory turns range from weeks for refrigerated dairy to months for shelf-stable supplements, creating divergent working capital demands across manufacturing footprints.
- Food & Beverages:Fermented dairy products and functional beverages carry live cultures at 10^6 to 10^9 CFU per serving, requiring cold chain integrity from São Paulo processing plants through southeastern Brazilian retail networks. ANVISA's novel food guidelines govern strain-specific claims for digestive and immune benefits in this category.
- Dietary Supplements:Capsule and sachet formats attract Colombian and Brazilian consumers seeking targeted gut health applications beyond traditional yogurt consumption. These products bypass refrigerated logistics constraints through lyophilization and enteric coating technologies.
- Infant Formula:Specialized Bifidobacterium strains for neonatal gut colonization face extended safety validation timelines under Brazilian and Argentine pediatric nutrition frameworks.
- Animal Feed:Livestock probiotic additives for poultry and cattle operations concentrate in Argentina's Pampas dairy belt and southern Brazilian ranching regions.
Food & Beverages anchors the volume base while Dietary Supplements gains share at the steepest rate.
Application:
Clinical validation requirements vary sharply by health outcome, with digestive claims clearing ANVISA fastest while mental wellness positioning demands extended neurobiological evidence.
- Gut Health:Digestive wellness applications dominate prescription and over-the-counter channels across Brazilian pharmacy networks. Lactobacillus rhamnosus and Bifidobacterium lactis strains command premium positioning where clinical trials demonstrate irritable bowel syndrome symptom reduction.
- Immune Support:Respiratory and systemic immunity claims accelerate fastest in Colombian and Argentine markets following pandemic-era consumer education. Formulations targeting upper respiratory tract infections require seasonal marketing coordination with southern hemisphere cold cycles.
- Mental Health:Psychobiotic applications linking gut microbiota to mood regulation remain emergent, with São Paulo research institutes conducting the region's primary clinical investigations.
- Skin Health:Topical and oral probiotic interventions for dermatological conditions occupy niche positioning in Brazilian urban wellness retail.
Gut Health commands the established revenue base while Immune Support climbs the fastest as consumers prioritize preventive health expenditure.
End User:
Purchase frequency and price sensitivity diverge across life stages, with infant formulations generating highest per-unit margins and senior applications driving volume through chronic condition management.
- Adults:Working-age consumers in São Paulo, Rio de Janeiro, and Belo Horizonte metropolitan areas sustain recurring purchase patterns through pharmacy subscription models and employer wellness programs.
- Infants:Pediatric probiotic formulations face concentrated demand from middle-class Brazilian households seeking allergy prevention and digestive comfort for neonates.
- Seniors:Age-related microbiome degradation drives sustained consumption among Argentine and Brazilian retirees managing polypharmacy-induced gastrointestinal disruption.
- Athletes:Sports nutrition applications for endurance and recovery remain underdeveloped relative to North American and European markets, with Brazilian football academy programs representing primary demand concentration.
Adults represent the volume foundation while Seniors expands most quickly as regional populations age and healthcare access broadens.
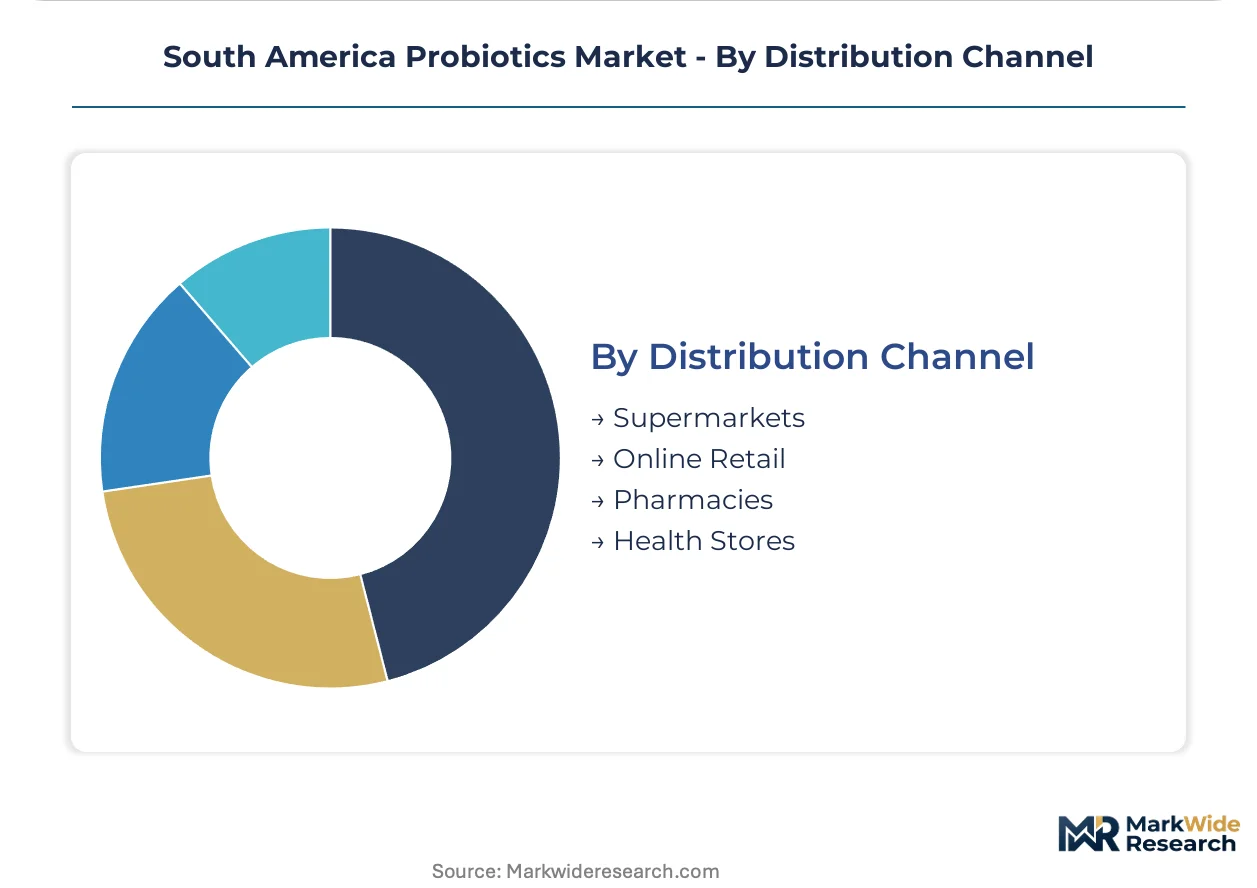
Distribution Channel:
Channel economics fragment across margin structures, with direct-to-consumer platforms capturing highest gross margins and supermarket chains demanding promotional investment for shelf placement.
- Supermarkets:Brazilian retail giants anchor refrigerated probiotic yogurt distribution through southeastern urban corridor stores, where cold chain infrastructure concentrates.
- Online Retail:São Paulo-based wellness platforms and Mercado Libre marketplace vendors displace traditional replenishment cycles among digitally literate professionals aged 25-40.
- Pharmacies:Brazilian and Colombian drugstore chains validate clinical efficacy claims through pharmacist consultation, supporting premium pricing for strain-specific formulations.
- Health Stores:Specialized nutrition retailers in Bogotá and Medellín remain underpenetrated relative to Brazilian retail density, presenting expansion opportunity for supplement-focused brands.
Supermarkets hold the volume position while Online Retail gains share fastest as logistics networks mature and subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's 2023 novel food guideline revision compresses strain registration timelines from 24 months to 14 months, accelerating domestic and imported live culture approvals while intensifying competitive pressure on established Brazilian suppliers.
Brazil
Fermented dairy infrastructure concentrates in São Paulo, Rio de Janeiro, and Belo Horizonte, where cold chain distribution capacity supports refrigerated probiotic yogurt penetration. ANVISA governs novel food and ingredient approvals, elevating compliance costs for new entrants while validating clinical efficacy requirements that protect established strain suppliers. The southeastern urban corridor anchors pharmacy and health store networks that reshape how probiotic products reach consumers.
Argentina
Middle-class households in Buenos Aires and Córdoba sustain demand for pediatric probiotic formulations targeting allergy prevention and neonatal digestive comfort. The national food safety authority enforces labeling standards for live culture claims across dairy and supplement products, creating duplicate testing protocols for cross-border Mercosur distribution. Regional dairy cooperatives in the Pampas dairy belt seek strain development alliances to reduce reliance on imported live cultures.
Colombia
Health store networks in Bogotá and Medellín remain underdeveloped for probiotic supplements relative to Brazilian retail density, presenting expansion opportunity for supplement-focused brands. Consumers in these metropolitan areas shift toward capsule and sachet formats for targeted gut health and immune support applications. Pharmacy channel infrastructure lacks the density of southeastern Brazil, constraining last-mile logistics for temperature-sensitive formulations.
Chile
Santiago's concentrated urban population supports subscription-based wellness platforms that bundle personalized microbiome testing with curated probiotic regimens. The country's national pharmaceutical regulator maintains distinct efficacy thresholds from ANVISA, complicating harmonization efforts for multinational supplement manufacturers. Southern hemisphere cold cycle coordination shapes seasonal marketing for respiratory immunity claims in metropolitan retail.
South America Probiotics Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability clusters: integrated dairy processors with captive fermentation infrastructure, specialized strain developers with clinical validation libraries, and diversified nutrition conglomerates with multi-channel distribution reach. Strategic archetypes include cold-chain dependent fresh product specialists, shelf-stable formulation innovators leveraging spore-forming Bacillus strains, and direct-to-consumer platforms bypassing traditional pharmacy markup structures. Dominant competitive moves encompass backward integration into strain development capabilities and geographic expansion through Mercosur mutual recognition frameworks.
Among European-originated culture houses, Chr. Hansen exemplifies the specialized strain developer archetype through partnerships with regional dairy cooperatives. Nestle SA and Groupe Danone occupy positions as integrated dairy processors, with the former leveraging dairy processing infrastructure and the latter anchoring premium positioning through specialized fermentation capabilities. These three entities represent the competitive spectrum from ingredient supply through finished product manufacturing.
| Leading Market Players |
|---|
| Nestle SA |
| Groupe Danone |
| Yakult Honsha Co Ltd. |
| Chr. Hansen |
| PepsiCo Inc. |
| Fonterra Cooperative Group |
| Kerry Group plc |
| Beneo GmbH |
| Mastellone Hnos SA |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazilian strain fermentation facilities is elevating spot pricing for validated Lactobacillus cultures while forcing Argentine and Colombian manufacturers toward longer-term offtake contracts with European culture houses.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade strain formulations from commodity dairy cultures across Brazilian procurement contracts. Price differentiation hinges on ANVISA registration status and cold chain certification tier, with registered strains commanding substantial premiums over novel food pathway candidates. Cost compression in economy-tier yogurt cultures is intensifying because domestic cooperatives are expanding in-house propagation capabilities. Pharmacy networks demonstrate lowest price sensitivity due to clinical validation requirements, while supermarket private-label buyers drive hardest bargain on per-unit basis.
Supply Chain Analysis
Upstream feedstock for live culture propagation draws from Danish, French, and German culture bank repositories, with lyophilized mother cultures shipped under temperature-controlled protocols to São Paulo and Buenos Aires processing facilities. Key inputs encompass fermentation media substrates, cryoprotectant solutions, and pharmaceutical-grade packaging films. Single-source vulnerability concentrates in European strain authentication services, creating bottleneck risk for ANVISA submission timelines. Distribution runs through refrigerated trucking networks across Brazil's southeastern corridor, with ambient-stable supplements bypassing cold chain through pharmacy direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's probiotics sector represents early-cycle expansion as pharmacy channel penetration accelerates beyond traditional dairy consumption patterns.
For Market Incumbents: Pre-empt shelf-stable formulation disruption by acquiring microencapsulation technology capabilities before spore-forming Bacillus strains displace refrigerated yogurt dominance in Colombian and Argentine markets. Secure backward integration into strain development partnerships with São Paulo research institutes to reduce royalty outflows to European culture houses.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting Bogotá and Medellín health-conscious professionals aged 25-40, where pharmacy channel density remains underdeveloped relative to Brazilian benchmarks. Prioritize sachet-format immune support formulations with seasonal respiratory marketing synchronized to southern hemisphere cold cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer wellness platforms bundling microbiome testing with curated probiotic regimens, suggesting superior cash flow quality versus transactional dairy processors. Long-term viability favors acquisition targets with captive strain development capabilities and ANVISA registration libraries. Watch for Mercosur mutual recognition framework finalization as inflection signal for cross-border claim harmonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Development Partnership | Argentine dairy cooperatives reduce import dependency through captive fermentation capabilities in Pampas dairy belt. |
| Shelf-Stable Formulation Launch | Spore-forming Bacillus strains enable ambient distribution without refrigerated logistics infrastructure investment. |
| Direct-to-Consumer Platform Buildout | São Paulo wellness platforms bypass retail markup structures through personalized microbiome testing integration. |
| ANVISA Registration Acceleration | Compressed 14-month timelines reward early clinical trial investment with first-mover premium positioning. |
| Pharmacy Channel Expansion | Colombian health store networks in Bogotá present whitespace opportunity for supplement-focused brand penetration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation facility managers, regulatory affairs specialists at ANVISA, pharmacy chain procurement directors, and clinical research coordinators at São Paulo institutes; alongside secondary validation through ANVISA novel food submission databases, Argentine national food safety authority labeling guidelines, Mercosur harmonization documentation, and regional dairy cooperative processing statistics. Bottom-up strain volume estimates triangulated against top-down category spending projections.
Forecast inputs span product type segmentation across food and beverages, dietary supplements, infant formula, and animal feed applications; application dimensions covering gut health, immune support, mental health, and skin health positioning; and distribution channel splits between supermarkets, online retail, pharmacies, and health stores. CAGRs derived from regression analysis against historical adoption curves and regulatory pathway acceleration effects. Modeled variables incorporate ANVISA registration timeline compression and cold chain infrastructure expansion rates.
Sensitivities concentrate around Mercosur mutual recognition delays, European strain supplier concentration risk, and microbiome research talent scarcity in secondary Argentine and Colombian cities. Forecasts reflect documented assumptions on regulatory harmonization progress and pharmacy channel penetration trajectories. Cross-checking against Brazilian pharmaceutical distribution association volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Psychobiotic Supplements Market