
 Anti-Diarrheal Supplements Market | 2026-2036
Anti-Diarrheal Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Diarrheal Supplements Market Analytics
USP verification and NSF International certification for dietary supplements is redrawing competitive boundaries in anti-diarrheal formulations. GlaxoSmithKline leverages its established OTC infrastructure to sustain shelf presence across pharmacy chains. Johnson & Johnson anchors consumer trust through rigorous quality protocols that exceed baseline regulatory requirements. Pfizer competes on clinical credibility, extending its pharmaceutical heritage into consumer health positioning.
Anti-diarrheal supplements comprise pharmacologically active agents and probiotic cultures formulated to attenuate intestinal motility, absorb toxins, or restore gut microbiome equilibrium, typically standardized to deliver measurable concentrations of active compounds per dose unit. Probiotics segments command premium positioning as live-culture stability requirements create formulation barriers for new entrants. Loperamide-based products occupy mature, price-sensitive channels where generic substitution pressures margins. The travelers end-user category differentiates through portable packaging formats that address convenience-driven purchasing.
FDA OTC monograph compliance, EMA traditional herbal medicine registration, and India's CDSCO AYUSH product licensing collectively determine which formulations achieve commercial scale across major markets. These frameworks elevate manufacturing costs for entrants lacking pre-validated production systems, concentrating volume among established operators with dedicated regulatory affairs capabilities. Stakeholders must weigh probiotic strain patent expiries against emerging microbiome-targeted delivery technologies when allocating R&D investment.
Market Dynamics
FDA OTC monograph reform is compressing manufacturing capacity as smaller operators face facility upgrade costs exceeding $2 million per site, concentrating volume among established players with pre-validated quality systems.
Growth Catalysts
- Pediatric formulation demand:Health-conscious parents in India and Brazil are driving adoption of zinc-based supplements and probiotic drops for childhood diarrhea management, expanding the addressable population base.
- EMA traditional herbal medicine registration:Simplified pathways for Ayurveda-derived formulations are accelerating European market entry for Indian manufacturers with documented botanical safety profiles.
- Live-culture stability advances:Microencapsulation technologies for probiotic strains are extending shelf life from 12 to 24 months, reducing cold-chain dependency and enabling pharmacy retail distribution.
Market Restraints
- API supply concentration:Loperamide hydrochloride active pharmaceutical ingredient production clusters in Zhejiang Province, China, exposing formulators to single-source disruption risk and import tariff volatility.
- Clinical validation costs:Probiotic strain-specific health claims require placebo-controlled trials costing $3-8 million per indication, blocking mid-tier entrants from premium positioning.
- Generic substitution pressure:Off-patent synthetic anti-diarrheals face pharmacy-level substitution mandates in US Medicaid programs, eroding branded supplement margins in the mass channel.
Strategic Opportunities
- Travelers segment expansion:Portable single-dose sachet formats targeting Southeast Asian tourism corridors address convenience gaps in current blister-pack dominated offerings.
- Microbiome-targeted delivery:Convergence of phage therapy and precision fermentation is creating next-generation formulations that restore gut equilibrium without motility suppression.
- India PLI scheme for pharmaceuticals:Production-linked incentives for domestic manufacturing of critical APIs are enabling backward integration into probiotic culture media and excipient production.
Industry Challenges
- Cold-chain infrastructure gaps:Last-mile temperature control failures in tropical climates degrade live probiotic potency, requiring reformulation investments or controlled-atmosphere packaging.
- Multi-jurisdiction dossier complexity:Simultaneous FDA OTC monograph compliance, EMA herbal registration, and CDSCO AYUSH licensing demands specialized regulatory affairs teams that smaller entrants cannot staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Diarrheal Supplements Market |
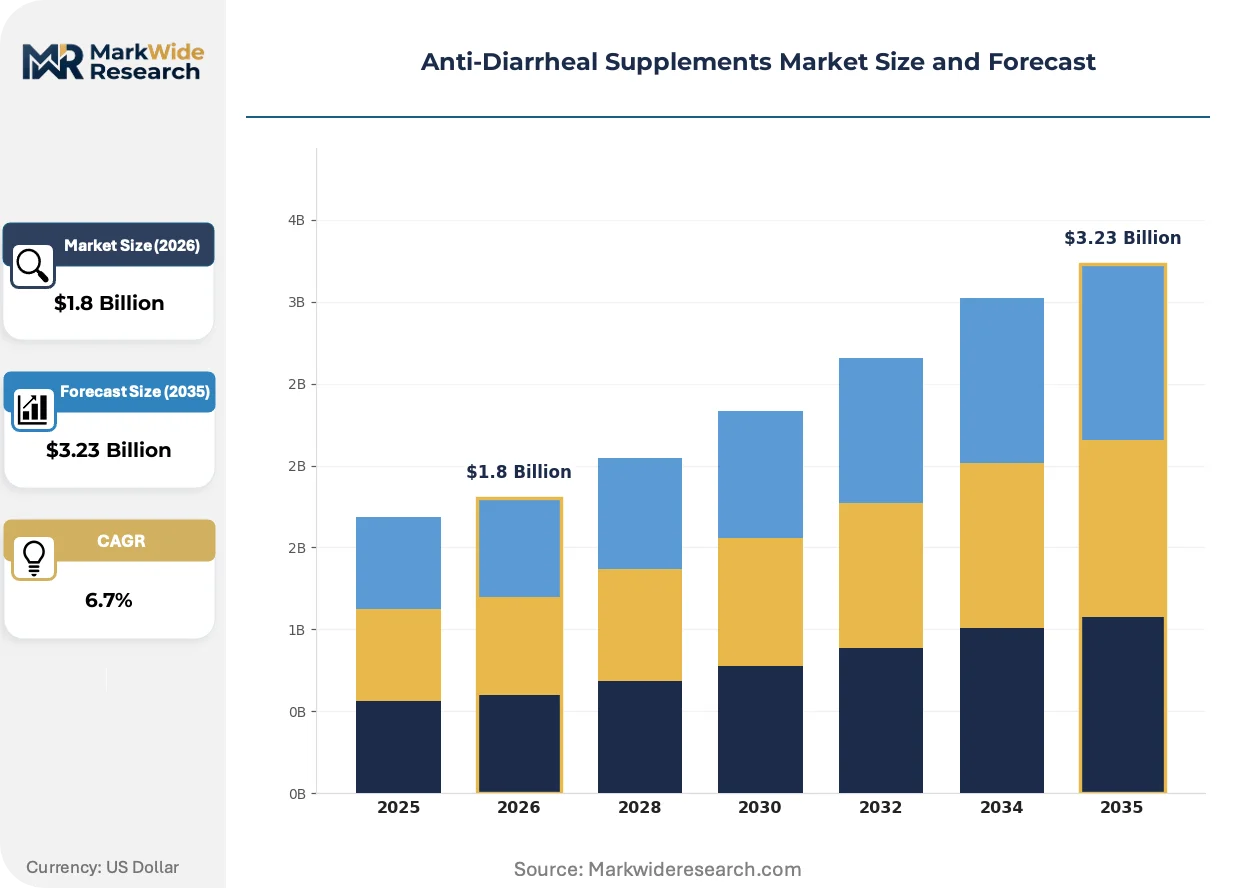
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loperamide, Bismuth Subsalicylate, Attapulgite, Probiotics Formulation: Caplets, Liquid, Gummies, Powder End User: Adults, Children, Seniors, Travelers Distribution Channel: Supermarkets, Pharmacies, Online Retail, Health Stores |
| Companies Covered | GlaxoSmithKline, Johnson & Johnson, Pfizer, Procter & Gamble, Abbott Laboratories, Sanofi, Bayer AG, Lupin, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Diarrheal Supplements Market Evolving Landscape
Formulation science and delivery mechanisms are diverging sharply between synthetic motility inhibitors and live biotherapeutic products, creating distinct competitive arenas with incompatible manufacturing competencies.
Microencapsulation technology for probiotic strains is bifurcating the formulation landscape. Layer-by-layer coating systems using alginate and chitosan matrices protect live cultures through gastric transit, enabling enteric release in the ileum. Pediatric and geriatric segments are adopting these formats fastest, drawn by taste-masking and dose-flexibility advantages. The structural consequence is compressing demand for traditional freeze-dried powder formats while elevating contract manufacturing premiums for validated microencapsulation lines.
CDSCO AYUSH product licensing harmonization with WHO Traditional Medicine Strategy standards is streamlining export pathways for Indian herbal anti-diarrheal formulations. The framework mandates GMP certification and heavy metal testing that eliminates artisanal producers from formal commerce. Ayurveda-inspired combinations containing Holarrhena antidysenterica and Aegle marmelos are gaining traction in Middle Eastern markets where allopathic resistance concerns drive botanical preference.
Direct-to-consumer subscription models are displacing pharmacy-centric replenishment for chronic gut health management. Urban professionals in tier-1 Indian cities and US coastal metros are purchasing probiotic regimens through telehealth-integrated platforms that bundle diagnostic testing with personalized strain selection. This channel shift concentrates customer data with platform operators, eroding brand loyalty for legacy OTC marketers dependent on retail shelf presence.
Anti-Diarrheal Supplements Market Segmentation
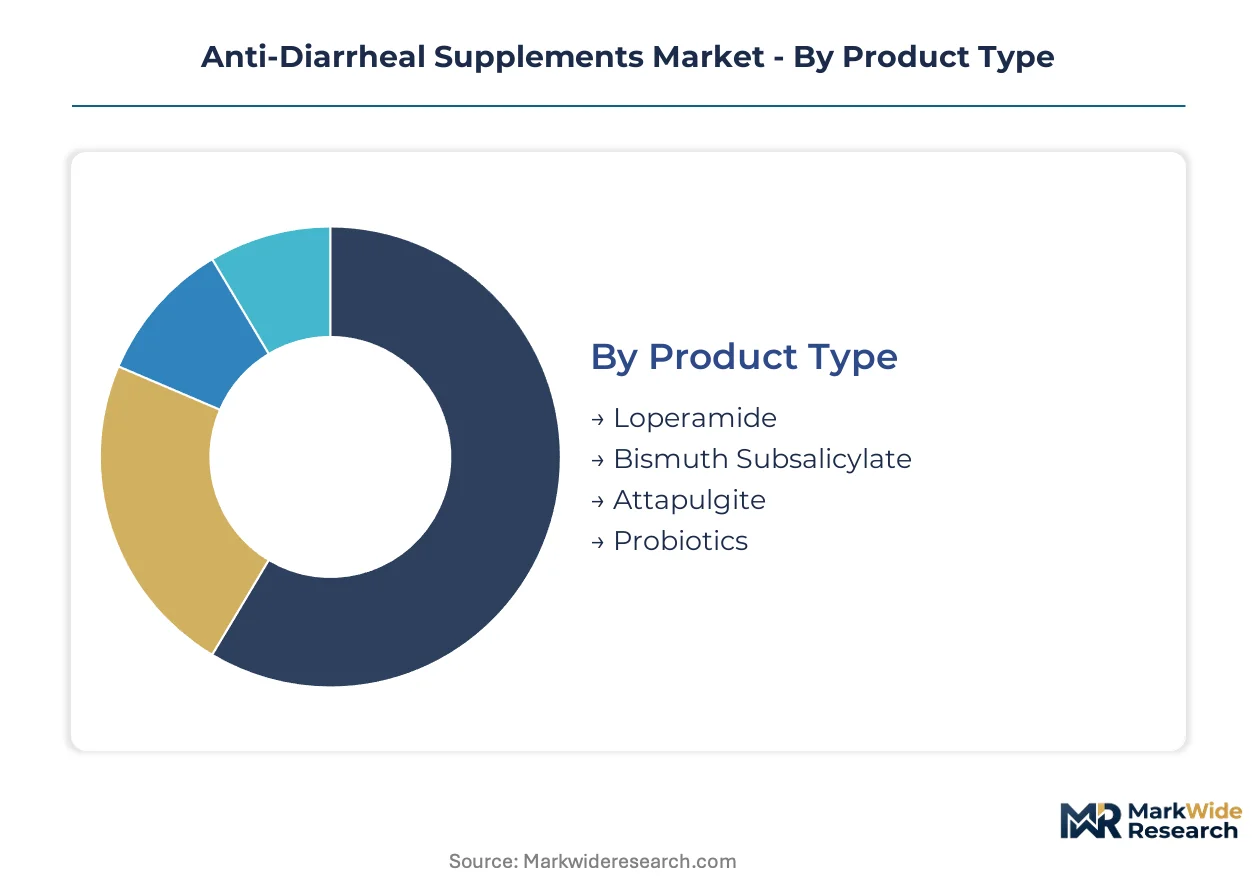
Segmentation in anti-diarrheal supplements determines regulatory pathways, pricing power, and shelf placement strategy. Each dimension carries distinct compliance burdens and margin profiles that shape competitive positioning.
Product Type:
FDA OTC monograph status and EMA traditional herbal registration create divergent approval timelines and manufacturing standards across active ingredient categories.
- Loperamide:Synthetic opioid agonist targeting intestinal μ-receptors to reduce peristalsis. Demand concentrates in US pharmacy chains where Medicaid substitution mandates compress branded margins but sustain high volume throughput.
- Probiotics:Live bacterial cultures including Lactobacillus and Bifidobacterium strains formulated for gut microbiome restoration. Pediatric applications in India and Brazil drive premium positioning as health-conscious parents seek zinc-enhanced drops for childhood diarrhea management.
- Bismuth Subsalicylate:Colloidal bismuth compound with antimicrobial and antisecretory properties. Standardized for travelers segment portability requirements.
- Attapulgite:Hydrated magnesium aluminum silicate clay adsorbent binding toxins in intestinal lumen. Mature demand in price-sensitive mass retail channels.
Loperamide handles the majority of throughput; probiotics are gaining share fastest on expanded pediatric indication approvals.
Formulation:
Manufacturing capital intensity and cold-chain requirements stratify competitive entry barriers across delivery formats.
- Liquid:Aqueous suspensions enabling dose flexibility for pediatric and geriatric populations. Concentrated demand in Indian urban households where taste-masking drives repeat purchase behavior.
- Caplets:Compressed tablet formulations with enteric coating for gastric acid resistance. US pharmacy chains favor this format for shelf stability and inventory efficiency.
- Powder:Sachet-packaged dry blends requiring reconstitution. Travelers segment in Southeast Asian tourism corridors adopts single-dose portable formats.
- Gummies:Gelatin-based chewable matrices with flavor masking. Emerging traction among adult wellness consumers in subscription-based direct-to-channel models.
Caplets dominate current volume; liquid formats are climbing the fastest on pediatric formulation demand.
End User:
Physiological vulnerability and purchasing authority create distinct customer acquisition economics across demographic segments.
- Children:Zinc-based supplements and probiotic drops targeting acute diarrhea episodes. Indian health-conscious parents drive category expansion through pediatrician recommendation networks.
- Travelers:Pre-positioned prophylactic use among international tourists. Southeast Asian corridors and Middle Eastern departure hubs concentrate demand for portable single-dose packaging.
- Adults:Self-medicating population seeking rapid symptom relief. Price-sensitive substitution behavior in US mass retail channels.
- Seniors:Chronic gut health management with polypharmacy considerations. Geriatric microencapsulation adoption for taste-masking and dose precision.
Adults represent the established volume base; children show the steepest expansion trajectory on emerging market premiumization.
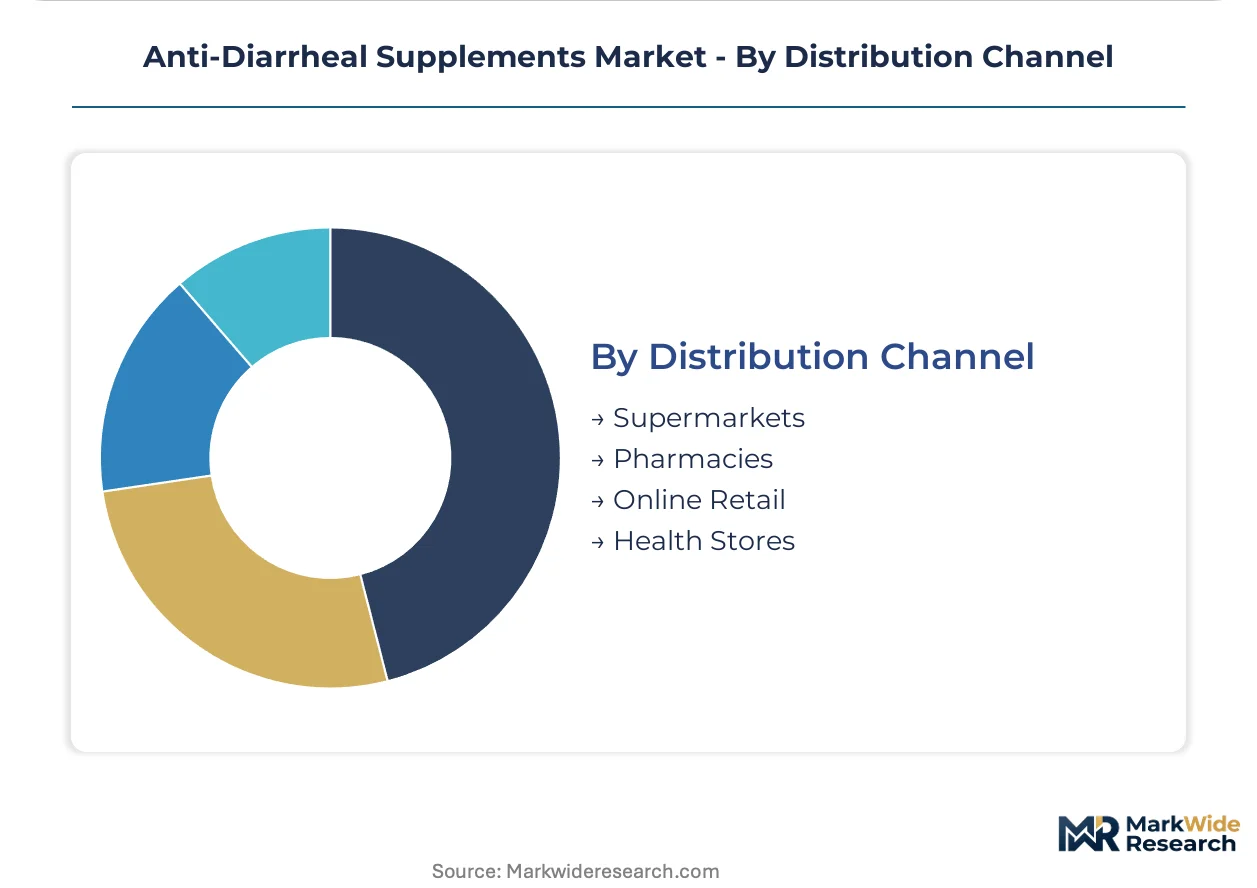
Distribution Channel:
Channel control determines customer data ownership and replenishment economics in a shifting retail landscape.
- Online Retail:Direct-to-consumer subscription platforms bundling diagnostic testing with personalized strain selection. Urban professionals in tier-1 Indian cities and US coastal metros concentrate demand.
- Pharmacies:Professional recommendation-driven purchase with pharmacist consultation. US chains and European apothecaries maintain OTC monograph compliance verification role.
- Supermarkets:Impulse and pantry-stock replenishment for acute symptom relief. Price competition and generic substitution pressure dominate.
- Health Stores:Wellness-positioned probiotics with USP verification and NSF International certification. Premium positioning through quality credential visibility.
Pharmacies process the majority of transactions; online retail is expanding most quickly on telehealth integration and subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Jawaharlal Nehru Port maritime corridor anchors Indian pharmaceutical exports, while the Rhine-Alpine rail freight corridor connects German chemical clusters to Mediterranean distribution hubs. These infrastructure backbones determine where formulation manufacturing concentrates and how finished goods reach terminal markets.
United States
FDA OTC monograph reform is compressing manufacturing capacity as smaller operators face facility upgrade costs exceeding $2 million per site. The 21 CFR Part 211 cGMP requirements for dietary supplements now mandate electronic batch records and environmental monitoring systems. New Jersey and Pennsylvania host the densest contract manufacturing clusters, where pre-validated quality systems attract volume consolidation from distressed facilities.
India
CDSCO AYUSH product licensing harmonization with WHO Traditional Medicine Strategy standards is streamlining export pathways for herbal anti-diarrheal formulations. The PLI scheme for pharmaceuticals offers production-linked incentives for domestic manufacturing of critical APIs and probiotic culture media. Hyderabad and Ahmedabad concentrate formulation science capabilities, with microencapsulation contract manufacturers serving both domestic and Middle Eastern markets.
Germany
EMA traditional herbal medicine registration creates simplified pathways for Ayurveda-derived formulations entering European commerce. The BfArM monograph system for well-established use claims reduces clinical trial burdens for documented botanical safety profiles. Bavaria and Baden-Württemberg host specialist probiotic fermentation facilities, where precision fermentation capabilities serve microbiome-targeted delivery development.
Brazil
Health-conscious parents in São Paulo and Rio de Janeiro are driving pediatric formulation demand for zinc-based supplements and probiotic drops. ANVISA's RDC 240/2018 dietary supplement regulations mandate GMP certification and stability testing that eliminates informal producers from pharmacy channels. The São Paulo metropolitan corridor concentrates distribution infrastructure for Latin American market access.
China
Loperamide hydrochloride API production clusters in Zhejiang Province, exposing formulators to single-source disruption risk and import tariff volatility. The NMPA's 2020 revised Drug Registration Regulations align with ICH guidelines for quality management. Shanghai and Suzhou host the primary probiotic strain development facilities, where domestic fermentation capacity serves both pharmaceutical and supplement applications.
Anti-Diarrheal Supplements Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs capabilities and manufacturing scale. The market structure concentrates volume among established operators with pre-validated quality systems, while mid-tier entrants face exclusion from premium positioning due to clinical validation cost barriers. Three archetypes dominate: multinational pharmaceutical heritage companies leveraging OTC infrastructure, domestic generic manufacturers with backward-integrated API supply, and microbiome-focused biotech specialists pursuing precision fermentation differentiation. Competitive moves center on M&A for strain patent portfolios and strategic partnerships for cold-chain distribution in tropical markets.
Within the pharmaceutical heritage tier, GlaxoSmithKline and Johnson & Johnson exemplify scale-driven operators with established shelf presence across pharmacy chains. Pfizer occupies a position bridging clinical credibility and consumer health positioning. Among domestic specialists, Lupin and Dr. Reddy's Laboratories represent Indian manufacturers with CDSCO-validated production systems and AYUSH licensing capabilities for botanical export. These companies anchor the competitive structure without exhaustive enumeration of strategic initiatives.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Johnson & Johnson |
| Pfizer |
| Procter & Gamble |
| Abbott Laboratories |
| Sanofi |
| Bayer AG |
| Lupin |
| Dr. Reddy's Laboratories |
| Others |
Value Network & Pricing Analysis
Probiotic strain substitution for synthetic motility inhibitors is redrawing procurement geography while compressing price premiums in legacy loperamide channels. Health-conscious parents in India and Brazil now prioritize live-culture stability over cost, forcing reformulation investments that elevate manufacturing fixed costs and reshape supplier selection criteria.
Pricing Analysis
Certification level creates the primary spread between USP-verified premium probiotics and unverified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA OTC monograph compliance costs, cold-chain infrastructure investments, and clinical validation depth. Pricing pressure stems from Medicaid substitution mandates eroding branded margins in US pharmacy chains. Price-sensitive adult self-medicators in mass retail channels drive volume, while pediatric zinc-enhanced formulations command loyalty premiums from quality-focused parents.
Supply Chain Analysis
Just-in-time inventory strategies dominate probiotic distribution where shelf-life sensitivity demands rapid turnover, while strategic stockpiling persists for loperamide hydrochloride API given Zhejiang Province concentration risk. Manufacturing draws from China for synthetic APIs, India for fermentation-derived cultures and botanical extracts, and Germany for precision encapsulation equipment. Single-source vulnerability in Chinese API production exposes formulators to tariff volatility and import disruption. Distribution runs through pharmacy chains for acute symptom relief, with direct-to-consumer platforms capturing chronic gut health regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market functions as a regulatory-entrenchment story where FDA OTC monograph compliance and multi-jurisdiction dossier requirements create switching costs that protect validated operators. Pre-validated quality systems constitute the structural moat.
For Market Incumbents: Fortify cold-chain distribution partnerships in tropical markets to defend probiotic potency claims against emerging microencapsulation specialists. Deepen backward integration into probiotic culture media production under India's PLI scheme to reduce fermentation input cost volatility. Prioritize EMA traditional herbal medicine registration for Ayurveda-derived portfolios to preempt Indian manufacturers' European expansion. For New Entrants and Emerging Players: Anchor in Southeast Asian travelers corridors where portable single-dose sachet formats face limited incumbent innovation. Target subscription-integrated telehealth platforms in tier-1 Indian cities where diagnostic bundling creates customer data advantages over legacy OTC marketers. Pursue CDSCO AYUSH licensing for botanical formulations as the most penetrable regulatory pathway. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors microbiome-focused biotech specialists with precision fermentation capabilities over generic synthetic manufacturers. Long-term viability hinges on strain patent portfolios and delivery technology differentiation. Watch for probiotic strain patent expiry schedules as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Layer-by-layer coating systems from alginate-chitosan matrices extend shelf life, enabling pharmacy retail distribution without cold-chain dependency. |
| EMA Traditional Herbal Medicine Registration | Simplified pathways for Ayurveda-derived formulations accelerate European market entry for Indian manufacturers with documented botanical safety profiles. |
| Direct-to-Consumer Platform Integration | Telehealth bundling with diagnostic testing concentrates customer data, eroding brand loyalty for legacy OTC marketers dependent on retail shelf presence. |
| CDSCO AYUSH Licensing Expansion | Harmonization with WHO Traditional Medicine Strategy standards streamlines export pathways for herbal anti-diarrheal formulations into Middle Eastern markets. |
| Precision Fermentation Capacity Buildout | Convergence of phage therapy and microbiome-targeted delivery creates next-generation formulations that restore gut equilibrium without motility suppression. |
Research Methodology
Operator-level perspectives from regulatory affairs directors, probiotic fermentation specialists, pharmacy chain category managers, and pediatric formulation scientists anchored the qualitative base. Primary interviews combined with secondary validation from FDA OTC monograph filings, CDSCO AYUSH product registrations, EMA traditional herbal medicine submissions, and hospital procurement databases. Bottom-up demand modeling across pediatric, travelers, adult, and senior segments triangulated with top-down market sizing from customs trade flows and pharmaceutical production statistics.
Sensitivity analysis tested forecast robustness across alternative regulatory compliance cost scenarios and probiotic strain stability assumptions. Segmentation dimensions modeled include active ingredient category, formulation format, end-user physiology, and distribution channel control structure. CAGRs derived from volume trajectory analysis incorporating patent expiry schedules, regional regulatory pathway timelines, and channel shift elasticity parameters. Forecast inputs incorporated microencapsulation technology adoption curves and PLI scheme uptake rates for domestic API manufacturing.
Underlying assumptions cover FDA monograph reform implementation pace, cold-chain infrastructure expansion in tropical climates, and EMA herbal registration harmonization progress, with deviation risk concentrated in Zhejiang Province API supply disruptions and probiotic potency degradation rates. Revision becomes warranted when live-culture stability technology crosses cost-parity thresholds with synthetic alternatives or when multi-jurisdiction dossier complexity triggers regulatory arbitrage restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Vegan Probiotics Market