
 Probiotic Strains Market | 2026-2036
Probiotic Strains Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Strains Market Outlook
Direct-to-practitioner distribution is tilting toward consolidated platforms that bundle strain-specific clinical evidence with formulation support. Novonesis leverages its merged enzymatic and microbial platform to sustain R&D intensity across human and animal probiotic applications. Chr. Hansen anchors the high-value dairy inoculant segment through proprietary strain collections and fermentation expertise. DSM competes by extending its nutritional ingredient portfolio into synbiotic combinations that pair targeted strains with prebiotic substrates.
Probiotic strains are live microorganisms, typically bacteria or yeast, delivered at defined colony-forming unit counts and selected for survival through gastric transit, intestinal adhesion, and targeted metabolic activity; manufacturers culture, concentrate, freeze-dry, and stabilize these organisms for incorporation into finished products. Lactobacillus and Bifidobacterium genera occupy the core of human supplement and functional food formulations, where decades of clinical documentation support premium positioning. Saccharomyces boulardii differentiates within the pharmaceutical and travel-health segments due to its antibiotic-resistant yeast biology and established use in gastrointestinal disorder protocols. Dietary supplements in capsule and powder forms lead current value contribution, while gummy and liquid formats for pediatric and senior end users represent the fastest-growing delivery innovation.
EFSA health claims evaluation, FDA GRAS self-affirmation, and EMA-qualified presumption of safety pathways collectively shape strain commercialization timelines and investment thresholds. Strain developers must navigate divergent evidentiary standards across jurisdictions, with European novel food requirements imposing additional pre-market authorization burdens on non-traditional species. Stakeholders should monitor emerging national strain registries and evolving microbiome characterization standards that will determine competitive moats in the next phase of market development.
Market Dynamics
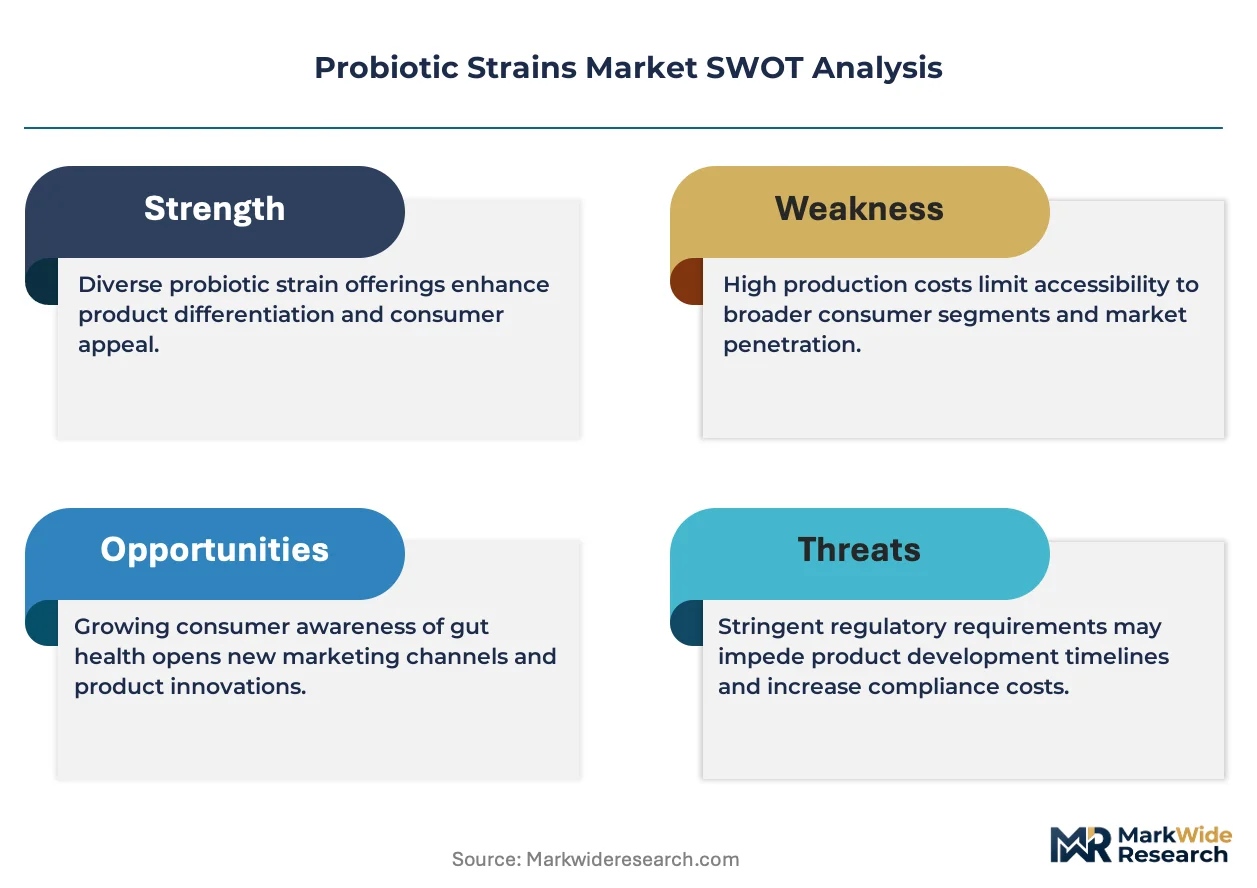
Strain-level substantiation requirements are forcing manufacturers to restructure R&D portfolios around documented clinical endpoints rather than generic genus-level claims. The documentation burden has shifted competitive advantage toward entities with established strain libraries and fermentation infrastructure.
Growth Catalysts
- EFSA Qualified Health Claims Pathway:European manufacturers investing in randomized controlled trials gain differentiated positioning in functional foods. The regulatory clarity rewards early movers with proprietary strain dossiers.
- Clean-Label Formulation Pressure:North American functional food brands are removing synthetic preservatives and demanding viable cell counts through shelf life. This specification pull elevates suppliers with stabilization expertise.
- China Domestic Strain Library Expansion:Local cultivation of Lactobacillus and Bifidobacterium isolates is reducing import dependency. SAMR strain registration requirements are accelerating indigenous R&D investment.
Market Restraints
- Freeze-Drying Energy Intensity:Lyophilization consumes substantial electricity per batch, constraining margin expansion in markets with volatile utility pricing. European manufacturers face particular pressure from F-Gas Regulation compliance costs.
- Single-Source Master Cell Bank Risk:Concentrated supply of characterized reference strains creates vulnerability. Disruption at primary culture collection facilities would cascade through downstream formulation.
- Antibiotic Resistance Gene Screening:EMA and FDA both mandate exclusion of strains carrying transferable resistance determinants. This technical filter eliminates candidate isolates that would have qualified under earlier safety paradigms.
Strategic Opportunities
- South Korea MFDS Strain Registration Streamlining:Accelerated approval timelines for documented probiotic ingredients are opening functional food applications. Domestic manufacturers are expanding into adjacent beauty-from-within segments.
- Synbiotic Formulation Convergence:Pairing targeted strains with precision prebiotic substrates enables differentiated positioning. DSM and specialized ingredient houses are developing substrate-strain specificity databases.
- Direct-to-Practitioner Platform Consolidation:Bundled clinical evidence and formulation support is displacing fragmented distributor networks. Practitioners gain strain-specific protocols for gastrointestinal and immune applications.
Industry Challenges
- PhD-Level Strain Characterization Talent Scarcity:Whole-genome sequencing and metabolomic profiling require specialized expertise. Compensation inflation in bioinformatics is compressing R&D budgets.
- Multi-Jurisdiction Dossier Harmonization:Divergent evidentiary standards between EFSA, FDA, and MFDS force redundant study design. Submission preparation timelines extend commercialization pathways.
- Legacy Fermentation Asset Reconfiguration:Existing tank infrastructure optimized for enzymatic production requires capital modification for anaerobic probiotic culture. Depreciation schedules complicate investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Strains Market |
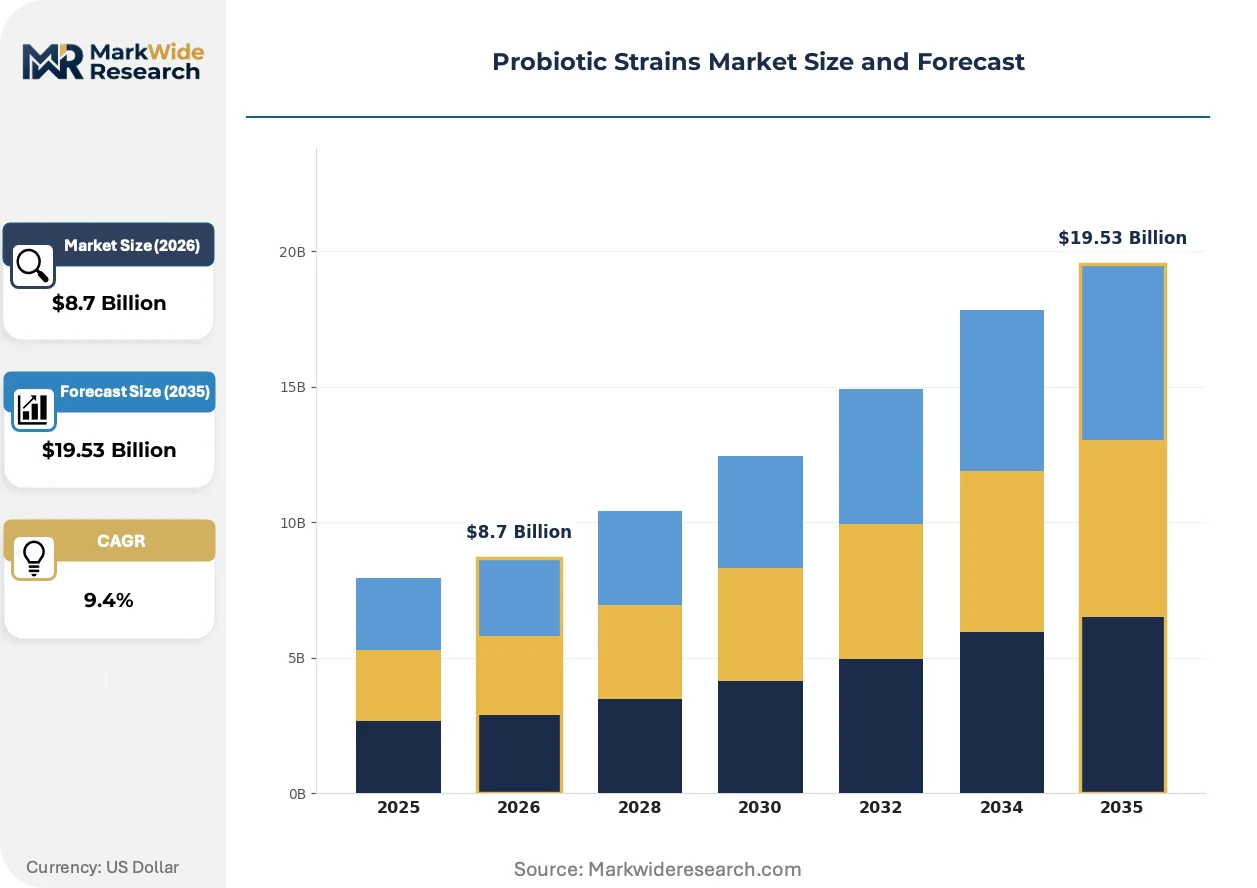
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactobacillus, Bifidobacterium, Saccharomyces, Streptococcus Application: Dietary Supplements, Functional Foods, Animal Feed, Pharmaceuticals Form: Capsules, Powders, Liquids, Gummies End User: Health Conscious Consumers, Athletes, Seniors, Children |
| Companies Covered | Novonesis, Chr. Hansen, DSM, Lallemand, ADM, International Flavors & Fragrances, DuPont, Probi, BioGaia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Strains Market Strategic Shifts
Multi-omics characterization platforms are compressing strain discovery timelines while regulatory agencies tighten safety documentation requirements. These simultaneous pressures favor integrated players with analytical infrastructure and clinical trial capabilities.
Whole-genome sequencing combined with metabolomic profiling is collapsing the traditional strain selection pipeline. Functional food manufacturers now demand transcriptomic evidence of bile salt tolerance and mucin adhesion before pilot-scale evaluation. This analytical depth is compressing the competitive field to entities with captive sequencing infrastructure.
EFSA's 2023 updated guidance on Article 13.1 health claims has tightened the evidentiary threshold for gut microbiota modulation claims. Manufacturers must now demonstrate strain-specific mechanisms rather than genus-level associations. Dairy and supplement segments in Germany, France, and the Netherlands are reformulating around dossier-ready strains with published clinical endpoints.
Buyer concentration among consolidated direct-to-practitioner platforms is reshaping distribution economics. Independent practitioners now access strain-specific clinical protocols through subscription-based digital platforms rather than traditional medical food distributors. This channel shift is most visible in the US and UK, where functional medicine networks have achieved critical mass for platform viability.
Probiotic Strains Market Segmentation
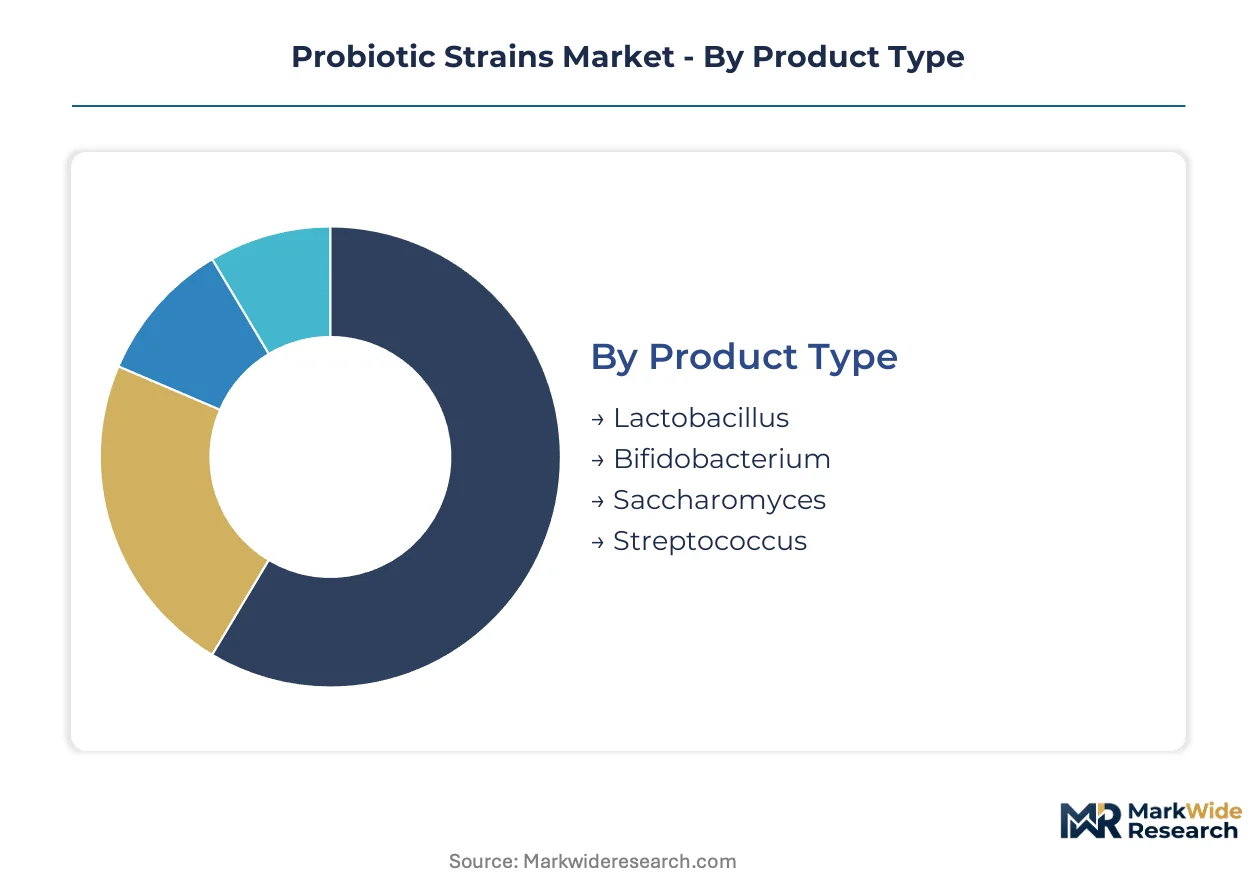
Strain-level documentation requirements and delivery format innovations are fragmenting the probiotic strains market into distinct competitive arenas. Manufacturers must align R&D investment with segment-specific regulatory pathways and end-user performance expectations.
Product Type:
Mature genera dominate commercial volume while emerging species face heightened safety screening.
- Lactobacillus:Acid-tolerant rod-shaped bacteria with documented bile salt hydrolase activity and mucin adhesion properties. German and Dutch dairy manufacturers anchor demand for L. rhamnosus and L. acidophilus in fermented milk applications. EFSA Article 13.1 health claims substantiation requirements favor established strain dossiers over novel isolates.
- Bifidobacterium:Anaerobic gram-positive bacteria specialized in oligosaccharide fermentation and short-chain fatty acid production. Infant formula manufacturers in France and Italy specify B. infantis and B. breve for early-life microbiome modulation. Strain-specific clinical endpoints for gut barrier function command premium positioning.
- Saccharomyces:Thermotolerant yeast strains resistant to common antibiotics and gastric acidity. Pharmaceutical applications in travel-health and antibiotic-associated diarrhea protocols concentrate demand.
- Streptococcus:Lactic acid bacteria primarily deployed in dairy starter cultures and kefir fermentation. Traditional food culture applications limit pharmaceutical-grade documentation investment.
Lactobacillus handles the majority of throughput; Bifidobacterium is the fastest mover on share.
Application:
Cost tier differentiation separates commodity-scale food cultures from pharmaceutical-grade documentation investments.
- Dietary Supplements:Capsule and powder delivery of defined CFU counts with gastric survival guarantees. US direct-to-practitioner platforms bundle strain-specific clinical protocols with subscription fulfillment.
- Functional Foods:Shelf-stable incorporation into yogurt, kefir, and fermented beverages with viable cell guarantees through expiration. Clean-label pressure from North American brands eliminates synthetic preservative dependencies.
- Animal Feed:Poultry and swine gut health applications with feed conversion efficiency endpoints. Novonesis leverages merged enzymatic platforms for ruminant and monogastric strain development.
- Pharmaceuticals:Drug Master File submissions and IND-enabling studies for live biotherapeutic products. EMA qualified presumption of safety and FDA GRAS notification pathways impose parallel documentation burdens.
Dietary Supplements command the highest margin tier; Functional Foods deliver volume scale.
Form:
Customer type preferences are driving format innovation beyond traditional capsule delivery.
- Capsules:Hard-shell gelatin and hydroxypropyl methylcellulose encapsulation with enteric coating for gastric bypass. Adult supplement users prioritize convenience and precise dosing.
- Powders:Bulk sachets and stick packs with flavor masking for beverage incorporation. Sports nutrition and clinical settings favor flexible dosing protocols.
- Liquids:Ready-to-drink formulations with suspended microencapsulation for pediatric and geriatric compliance. Dropper delivery enables precise titration for infant applications.
- Gummies:Pectin and gelatin matrices with moisture barrier coatings for chewable delivery. Children and senior segments drive format expansion despite thermal stability constraints.
Capsules retain the largest installed base; Gummies are climbing the fastest on share.
End User:
Application specificity varies sharply across demographic segments with distinct performance expectations.
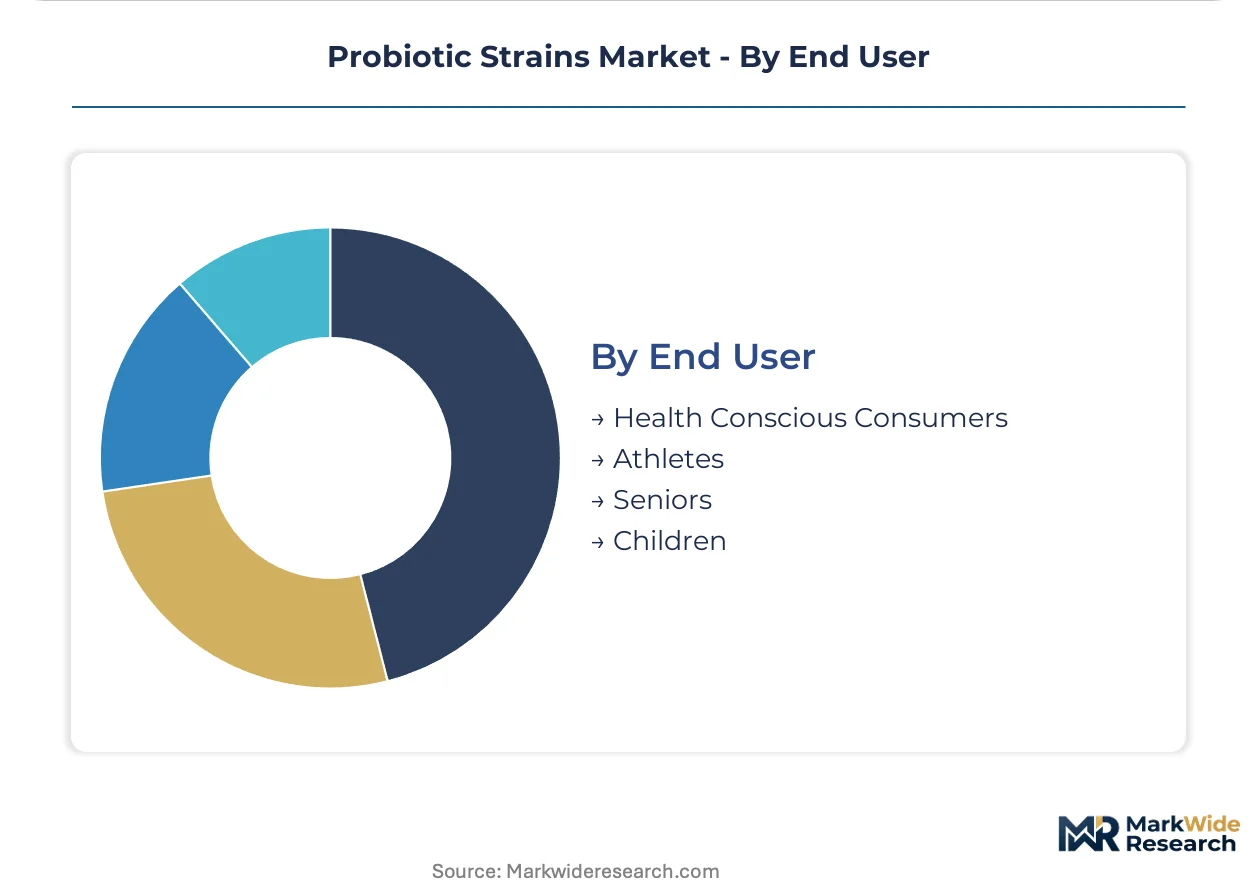
- Health Conscious Consumers:General wellness positioning with immune and digestive maintenance claims. E-commerce subscription models and functional medicine practitioner recommendations drive acquisition.
- Athletes:Exercise-induced gastrointestinal stress and upper respiratory tract infection protocols. Strain-specific documentation for cortisol modulation and protein absorption garners loyalty.
- Seniors:Age-related microbiome diversity decline and medication interaction management. Liquid and gummy formats address dysphagia and polypharmacy compliance challenges.
- Children:Early-life immune programming and antibiotic recovery applications. Pediatrician endorsement requirements elevate safety documentation thresholds.
Health Conscious Consumers generate the broadest addressable base; Children present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's probiotic ingredient trade, while China's high-speed rail network connects Yangtze River Delta fermentation clusters to domestic distribution hubs.
United States
Direct-to-practitioner platforms and functional medicine networks concentrate demand in California and New York. FDA GRAS self-affirmation pathways shape strain commercialization timelines for domestic manufacturers. Chicago-area dairy processors anchor Midwest fermentation capacity expansion.
Germany
EFSA Article 13.1 health claims substantiation rewards early movers with proprietary strain dossiers. The F-Gas Regulation imposes compliance costs on freeze-drying operations. Bavarian dairy cooperatives drive Lactobacillus rhamnosus demand for fermented milk applications.
China
SAMR strain registration requirements accelerate indigenous R&D investment in Lactobacillus and Bifidobacterium isolates. The country's dual carbon goals pressure energy-intensive lyophilization facilities. Shanghai biotech parks host expanding domestic strain library operations.
South Korea
MFDS strain registration streamlining opens functional food applications for documented probiotic ingredients. Accelerated approval timelines attract regional headquarters decisions. Seoul-based manufacturers expand into adjacent beauty-from-within segments leveraging fermentation expertise.
Netherlands
Clean-label formulation pressure from North American brands elevates suppliers with stabilization expertise. REACH compliance frameworks govern novel strain substance characterization. Wageningen University research clusters anchor strain characterization and clinical trial infrastructure.
Probiotic Strains Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying characterized master cell banks and fermentation-derived biomass. The vendor base stratifies across consolidated strain library holders, specialized stabilization service providers, and regional fermentation contractors. Three archetypes dominate: integrated enzymatic-microbial platforms, high-value dairy inoculant specialists, and precision prebiotic-substrate developers. Competitive moves center on synbiotic formulation convergence and direct-to-practitioner channel consolidation.
Within the integrated platform tier, Novonesis leverages its merged enzymatic and microbial infrastructure across human and animal applications. Chr. Hansen anchors the high-value dairy inoculant segment through proprietary strain collections. DSM competes by extending nutritional ingredient portfolios into synbiotic combinations that pair targeted strains with prebiotic substrates.
| Leading Market Players |
|---|
| Novonesis |
| Chr. Hansen |
| DSM |
| Lallemand |
| ADM |
| International Flavors & Fragrances |
| DuPont |
| Probi |
| BioGaia |
| Others |
Value Chain & Pricing Dynamics
Danish and Dutch fermentation clusters anchor master cell bank supply, concentrating margin capture with strain library holders while downstream formulation houses compete on stabilization expertise and clinical dossier depth.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade strains with drug master file documentation from commodity food cultures and premium synbiotic combinations. Price differentiation rests on EFSA dossier completeness and CFU stability guarantees through shelf life, with clean-label certification commanding measurable premiums. Pricing pressure stems from energy-intensive lyophilization costs and F-Gas Regulation compliance burdens in European manufacturing. Contract manufacturers exhibit highest price sensitivity, while direct-to-practitioner platforms prioritize clinical evidence over unit economics.
Supply Chain Analysis
Extended payment terms from consolidated direct-to-practitioner platforms are reshaping supplier-financing requirements for mid-tier fermentation houses. Geographic supply concentrates in Denmark, the Netherlands, and China, with Yangtze River Delta facilities drawing from domestic strain libraries. Raw material dependencies include cryoprotectant formulations, nitrogen gas for anaerobic culture, and pharmaceutical-grade growth media. Single-source master cell bank vulnerability represents the dominant structural risk. Distribution runs through cold-chain logistics networks anchored at Rotterdam and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against postbiotic and paraprobiotic formulations that threaten live culture relevance, requiring incumbents to deepen clinical differentiation beyond viability claims.
For Market Incumbents: Build regulatory dossier moats by accelerating EFSA Article 13.1 submissions and MFDS registrations ahead of emerging competitors. Secure backward integration into precision prebiotic substrates to anchor synbiotic convergence. Defend against postbiotic substitutes by commissioning mechanism-of-action studies that demonstrate live cell advantages in microbiome modulation endpoints.
For New Entrants and Emerging Players: South Korean beauty-from-within applications present underpenetrated white space where fermentation expertise transfers from food to cosmetic claims. Target pediatric liquid formats where dysphagia-driven demand outpaces incumbent innovation cycles. Enter through private-label partnerships with direct-to-practitioner platforms seeking differentiated strain protocols.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade live biotherapeutic manufacturing as EMA qualified presumption of safety requirements expand facility validation burdens. Prioritize acquisition targets with captive sequencing infrastructure and published clinical endpoints. Monitor SAMR strain registration velocity as the signal for Chinese market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Acceleration | Early movers secure proprietary positioning in German and French functional dairy segments. |
| Synbiotic Database Development | DSM and specialized houses are building substrate-strain specificity maps for differentiated formulations. |
| Direct-to-Practitioner Platform Integration | Consolidated digital channels displace fragmented distributor networks in US and UK functional medicine. |
| Domestic Strain Library Expansion | Chinese manufacturers reduce import dependency through SAMR-registered Lactobacillus isolates. |
| Lyophilization Energy Transition | European facilities face capital reconfiguration pressure from F-Gas Regulation compliance deadlines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA health claims registers, SAMR strain filings, and MFDS approval databases. Interviews with strain characterization scientists, regulatory affairs directors at fermentation houses, direct-to-practitioner platform procurement leads, and functional food brand managers informed demand-side validation. Bottom-up strain volume estimates triangulate against top-down functional food and supplement market sizing across the analysis window.
Forecast inputs include probiotic CFU consumption by delivery format, strain registration velocity by regulator, and clean-label penetration rates in North American retail. Segmentation models incorporate genus-tier dynamics, application-specific documentation requirements, and end-user demographic clustering. CAGRs derive from slope analysis of historical strain commercialization timelines projected against regulatory pathway acceleration or delay scenarios.
Practitioners should monitor EFSA guidance revisions, SAMR registration queue lengths, and postbiotic clinical trial readouts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Global Saccharomyces Boulardii Market