
 Europe Probiotics Market | 2026-2036
Europe Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Probiotics Market Analysis
Retail consumer demand in Europe is consolidating around pharmacy and supermarket chains with dedicated gut-health aisles, concentrating buyer power among a handful of pan-European distributors. Chr. Hansen leverages its strain library depth to anchor supply relationships with fermented dairy producers across Northern Europe. Danone competes through branded yogurt platforms that control refrigerated shelf space in France, Germany, and Spain. ADM extends its ingredient reach by supplying multi-strain concentrates to bakery and infant formula manufacturers seeking EFSA-compliant health claims.
Europe probiotics comprise live microbial preparations, typically containing Lactobacillus, Bifidobacterium, or Saccharomyces strains at minimum viable counts of 10^6 to 10^9 colony-forming units per serving, administered to confer digestive, immune, or metabolic benefits in humans or animals. Dietary supplements command premium shelf positioning in European pharmacies where healthcare professionals influence strain-specific purchasing, while yogurt remains the volume anchor in supermarket dairy cases with shorter innovation cycles. Functional foods and beverages represent the fastest-expanding margin pool as manufacturers infuse probiotic strains into non-dairy bases including oat, almond, and fermented teas to capture flexitarian consumers.
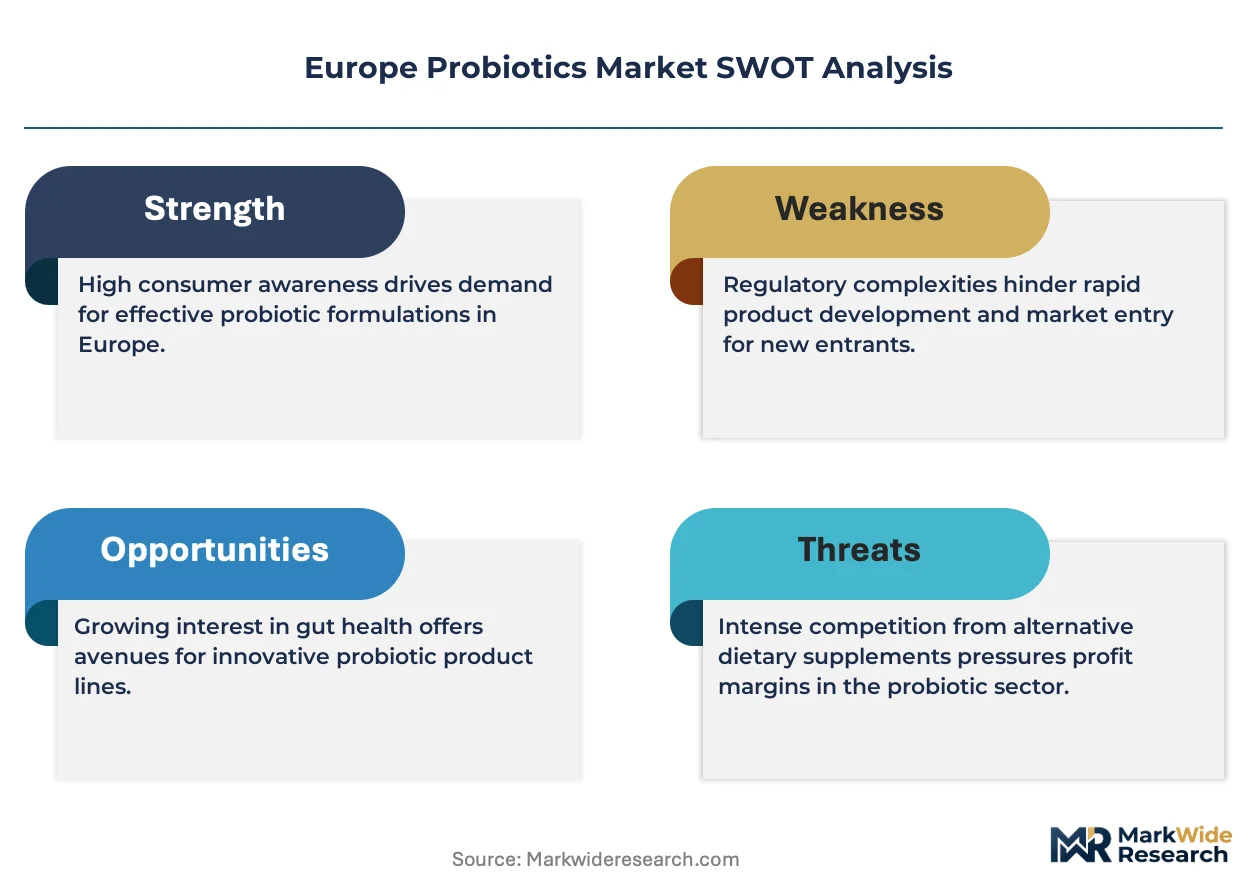
EFSA operates the gatekeeping function for health claims under EU Regulation 1924/2006, rejecting unsubstantiated probiotic marketing and compelling reformulation toward strains with dossier-backed efficacy. REACH and the EU Green Deal shape strain sourcing sustainability requirements, while national regulators including Germany's BfR and France's ANSES enforce post-market surveillance of novel microbial introductions. Stakeholders must monitor the pending revision of the EU Novel Food Catalogue, which could reclassify certain next-generation synbiotic formulations and alter market access timelines for innovators.
Market Dynamics
EFSA's gatekeeping function under EU Regulation 1924/2006 is compressing formulation pipelines toward dossier-backed strains, forcing manufacturers to consolidate R&D spend on clinically validated cultures while pharmacy channels amplify healthcare professional influence over strain-specific purchasing decisions.
Growth Catalysts
- EU Green Deal sustainability mandates:Strain sourcing requirements under REACH and circular economy frameworks are redirecting procurement toward fermentation-derived alternatives with verified carbon footprints, opening margin pools for suppliers with captive bioreactor capacity.
- Germany's pharmacy channel concentration:Healthcare professional recommendation networks in Apotheke and Drogerie channels are amplifying demand for condition-specific formulations with EFSA-aligned labeling, concentrating volume among strains with digestive and immune dossiers.
- Flexitarian dietary pivot:Oat, almond, and fermented tea bases are displacing dairy as the primary probiotic delivery vehicle among Northern European consumers, expanding addressable shelf space beyond refrigerated dairy cases.
Market Restraints
- EFSA health claims authorization friction:The dossier burden for substantiating strain-specific benefits under Regulation 1924/2006 extends development timelines and elevates regulatory capital requirements beyond mid-tier manufacturer thresholds.
- Live culture supply concentration:Northern European fermentation specialists control proprietary strain libraries, creating captive supply relationships that limit formulation flexibility and compress negotiating leverage for downstream finished goods producers.
- Stability limitations in ambient distribution:Viability decay in non-refrigerated supply chains constrains channel expansion into vending, convenience retail, and direct-to-consumer shipping without cold-chain infrastructure investment.
Strategic Opportunities
- Italy's underpenetrated functional beverage segment:Traditional fermented dairy dominance leaves white space for probiotic-infused kombucha, kefir waters, and botanical tonics targeting Mediterranean diet-aligned positioning.
- Next-generation synbiotic formulations:Prebiotic-probiotic combinations awaiting Novel Food Catalogue reclassification could capture metabolic health positioning with faster regulatory pathways than standalone strain dossiers.
- Veterinary and aquaculture applications:Live microbial feed additives for poultry, swine, and farmed salmon represent adjacent demand pools with lower EFSA scrutiny and shorter commercialization cycles than human therapeutics.
Industry Challenges
- Strain characterization and genomic documentation:Whole-genome sequencing requirements for Novel Food applications demand specialized bioinformatics capabilities scarce among traditional fermentation houses.
- Cold-chain infrastructure capex intensity:Viable count maintenance through last-mile distribution requires refrigerated warehousing and transport fleet investment that fragments margin structures in price-sensitive mass retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Probiotics Market |
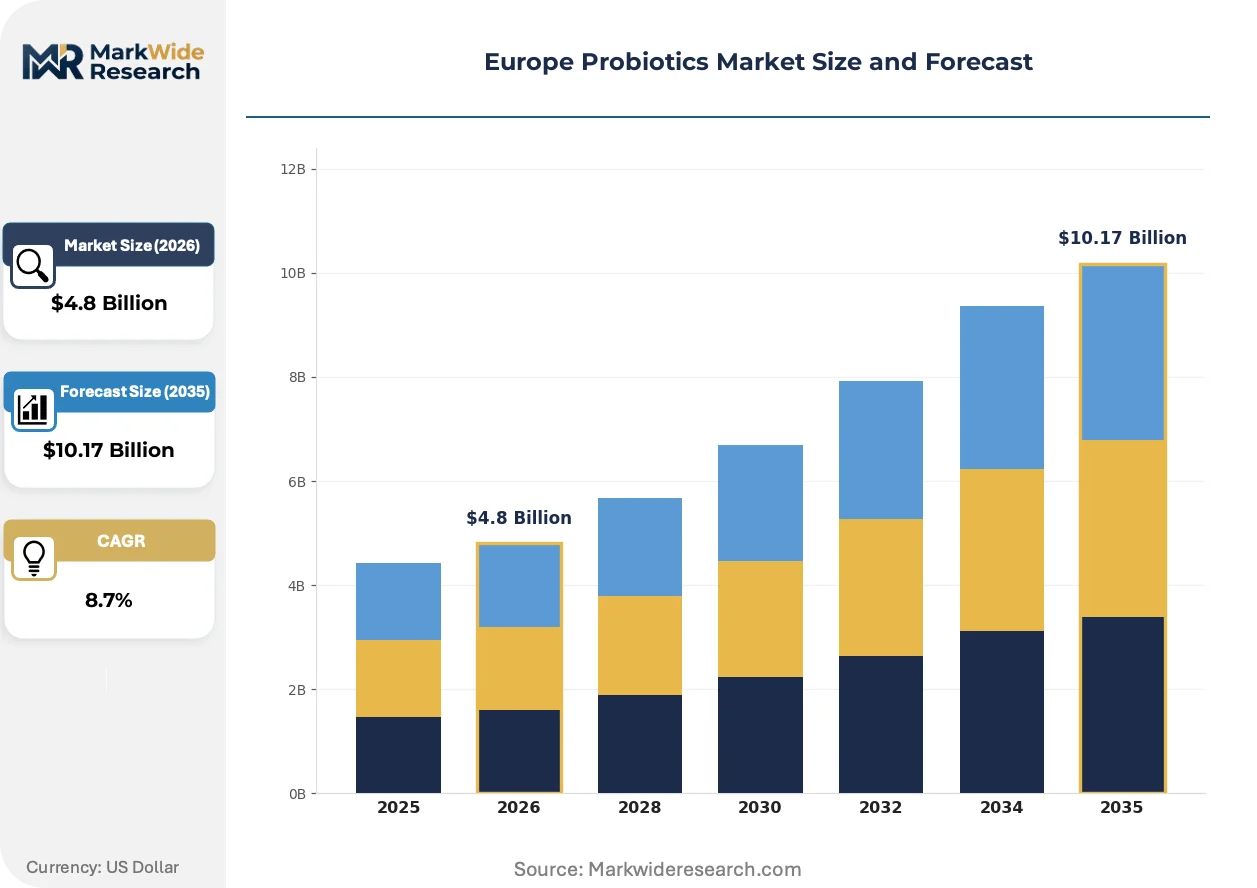
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Dietary Supplements, Beverages, Functional Foods Application: Dairy, Bakery, Infant Formula, Personal Care End User: Retail Consumers, Healthcare Professionals, Restaurants, Pharmacies Distribution Channel: Online, Supermarkets, Health Food Stores, Drug Stores |
| Companies Covered | Chr. Hansen, ADM, Danone, Bio-K Plus International, BioGaia, Nestlé, Probi, Daflorn, Yakult Honsha, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Probiotics Market Emerging Trajectories
Live microbial delivery systems are converging with precision fermentation and encapsulation technologies to extend viability windows beyond traditional refrigerated constraints, while regulatory pressure and channel evolution compress innovation cycles toward clinically validated, shelf-stable formats.
Microencapsulation via spray-drying and lipid-coating technologies is unifying stability and bioaccessibility in ambient probiotic applications. Bakery and confectionery manufacturers in France and Germany are adopting these formats for fortified cereals and chocolate products. This convergence is collapsing the traditional refrigerated barrier, enabling probiotic penetration into vending machines and convenience retail channels previously inaccessible to live cultures.
REACH substance registration requirements and the EU Green Deal's circular economy action plan are reshaping strain sourcing protocols. Manufacturers must now document fermentation feedstock sustainability and bioreactor energy intensity across the supply chain. Northern European dairy cooperatives and ingredient houses are responding by vertically integrating into captive fermentation capacity with renewable energy sourcing.
Pharmacy-led purchasing is displacing self-directed supermarket selection as the dominant decision mode for condition-specific probiotics. German and Austrian consumers increasingly defer to Apotheke staff for strain recommendations targeting antibiotic-associated diarrhea or IBS management. This channel shift elevates professional education investment and compresses marketing spend efficiency in traditional retail media.
Europe Probiotics Market Segmentation
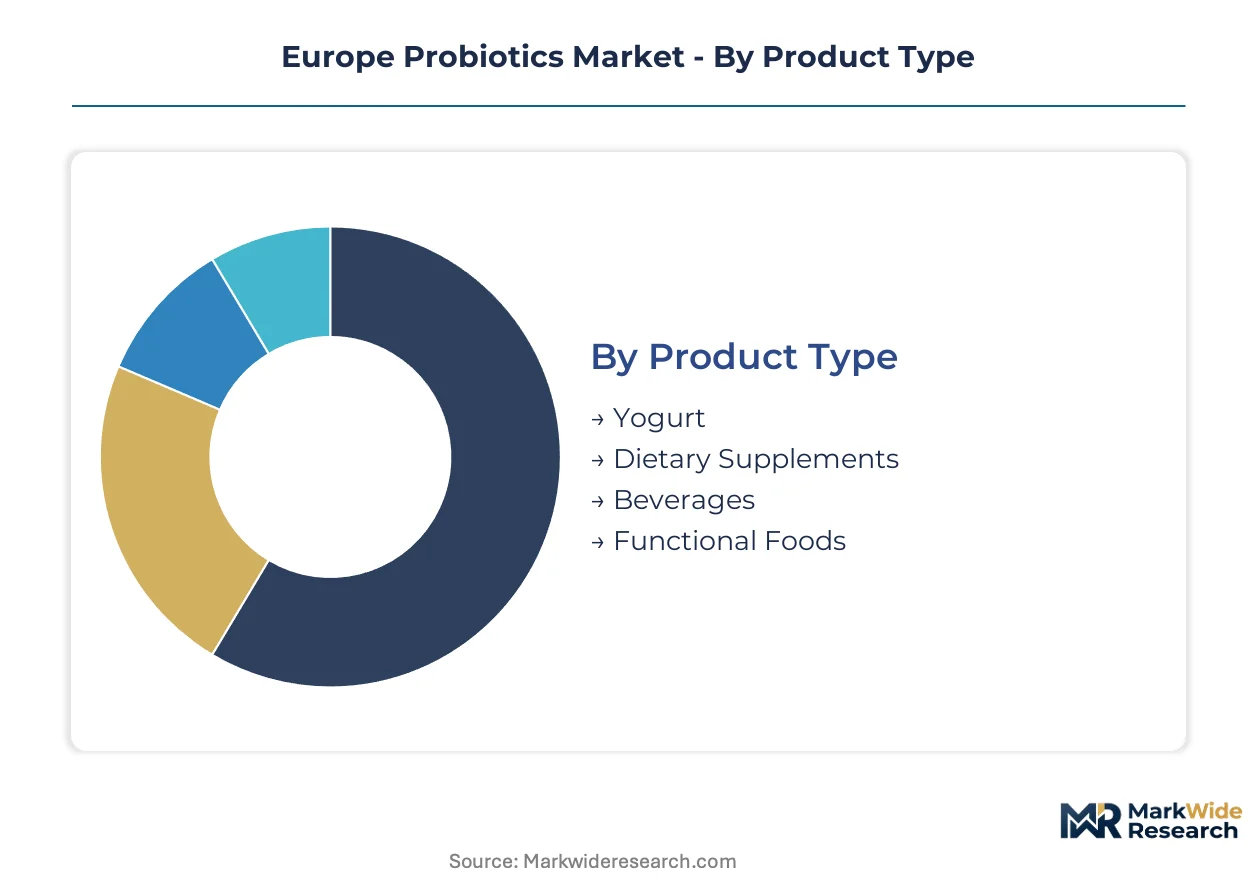
Strain viability requirements and EFSA compliance thresholds fragment the Europe probiotics landscape across delivery formats and professional intermediation. Manufacturers must align formulation investments with channel-specific regulatory burdens and cold-chain capabilities.
Product Type:
Standalone probiotic formats dominate pharmacy and mass retail shelves, while embedded strain integrations expand into ambient food matrices requiring stability engineering.
- Yogurt:Fermented dairy bases carry Lactobacillus and Bifidobacterium strains at 10^6 to 10^9 CFU per serving, with German and French dairy cooperatives controlling refrigerated shelf space through branded platform dominance. Live culture viability depends on unbroken cold chains from fermentation through retail display.
- Dietary Supplements:Capsule, tablet, and powder formats deliver strain-specific dosing with EFSA-aligned labeling for immune and digestive claims. German Apotheke channels concentrate demand for condition-specific formulations targeting antibiotic-associated diarrhea and IBS management.
- Beverages:Kombucha, kefir waters, and fermented teas displace dairy among flexitarian consumers in Northern Europe.
- Functional Foods:Microencapsulated strains penetrate bakery, confectionery, and cereal applications previously inaccessible to live cultures.
Volume placements concentrate in yogurt; the faster expansion belongs to functional foods.
Application:
Cost-tier stratification separates premium infant nutrition from commodity bakery fortification, with regulatory dossier requirements widening the investment gap.
- Dairy:Traditional fermented milk products anchor European probiotic consumption, with Northern European cooperatives leveraging captive fermentation capacity and renewable energy sourcing to meet EU Green Deal sustainability mandates.
- Infant Formula:Bifidobacterium strains with clinically validated early-life gut colonization dossiers command premium positioning. EFSA Novel Food requirements and genomic documentation burdens limit supplier pools to specialized fermentation houses with bioinformatics capabilities.
- Bakery:Spray-dried and lipid-coated strains enable ambient-stable fortification of breads and cereals.
- Personal Care:Topical probiotic formulations target skin microbiome positioning with lower regulatory barriers than ingestible claims.
Revenue concentrates in dairy; infant formula climbs the fastest.
End User:
Customer-type fragmentation splits between self-directed retail selection and healthcare professional intermediation, with pharmacy networks capturing condition-specific purchasing decisions.
- Retail Consumers:Supermarket and online shoppers drive volume in yogurt and functional beverage categories, with Northern European flexitarians displacing dairy for oat and almond-based alternatives.
- Healthcare Professionals:German and Austrian Apotheke staff influence strain-specific recommendations for digestive and immune indications, elevating professional education investment and compressing traditional retail marketing efficiency.
- Pharmacies:Dedicated gut-health aisles in drug store chains consolidate buyer power among pan-European distributors.
- Restaurants:Foodservice probiotic incorporation remains nascent, constrained by live culture stability in ambient holding environments.
Volume concentrates among retail consumers; healthcare professional channels gain share fastest.
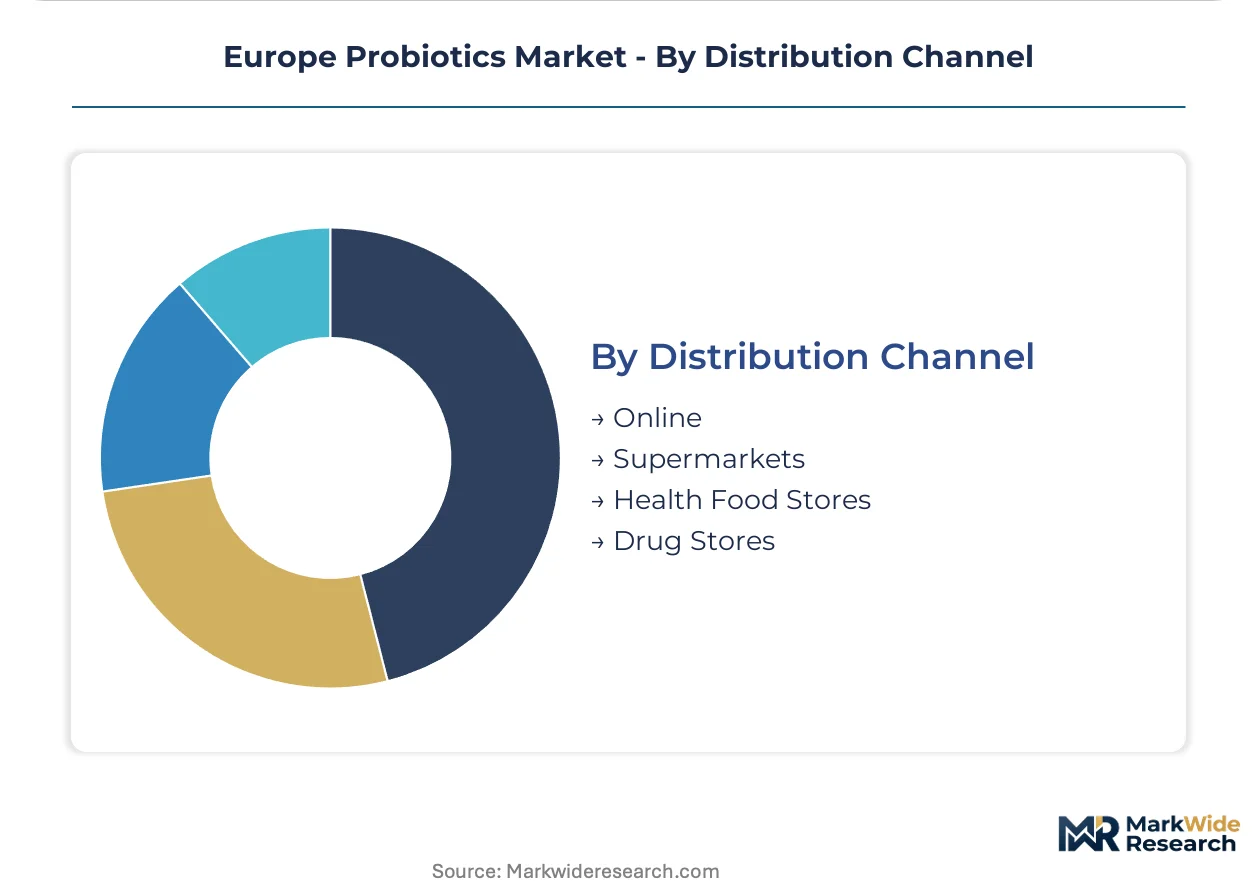
Distribution Channel:
Supply concentration in Northern European fermentation specialists shapes channel access, with cold-chain infrastructure requirements fragmenting margin structures.
- Drug Stores:German Drogerie and Apotheke networks dominate condition-specific probiotic dispensing, with healthcare professional recommendation networks amplifying demand for EFSA-aligned formulations.
- Supermarkets:Refrigerated dairy cases in France, Germany, and Spain anchor yogurt volume, with dedicated gut-health aisles expanding into functional foods and beverages.
- Online:Direct-to-consumer shipping confronts live culture viability decay without refrigerated last-mile infrastructure.
- Health Food Stores:Specialist retailers capture flexitarian and wellness-oriented consumers seeking non-dairy and organic-certified strains.
Volume concentrates in drug stores; online channels face steepest infrastructure constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy channel concentration in Germany and flexitarian dietary shifts across Northern Europe concentrate demand for condition-specific and non-dairy probiotic formats. EFSA regulatory frameworks and national health claim enforcement reshape formulation investments country by country.
Germany
Apotheke and Drogerie networks drive strain-specific purchasing for digestive and immune indications, with healthcare professional recommendations amplifying demand for EFSA-aligned formulations. BfR enforces post-market surveillance of novel microbial introductions, compressing timelines for dossier-backed products. Berlin and Hamburg anchor fermentation capacity investments serving pharmacy-distributed supplement brands.
France
Traditional fermented dairy dominance persists while flexitarian consumers displace yogurt with oat and almond-based alternatives in Paris and Lyon metro areas. ANSES coordinates with EFSA on Novel Food safety assessments, elevating genomic documentation requirements for new strain introductions. The Île-de-France region concentrates dairy cooperative headquarters controlling refrigerated retail shelf space.
Italy
Functional beverage penetration remains underdeveloped against Mediterranean diet-aligned positioning opportunities in kombucha and botanical tonics. REACH substance registration requirements redirect procurement toward fermentation feedstocks with verified carbon footprints. Emilia-Romagna's dairy processing clusters are integrating captive bioreactor capacity to meet EU Green Deal mandates.
United Kingdom
Health food store channels capture wellness-oriented consumers seeking organic-certified and non-dairy strains, with pharmacy influence weaker than Continental counterparts. The UK operates under retained EU Regulation 1924/2006 frameworks pending potential divergence, creating regulatory uncertainty for health claim substantiation. London anchors direct-to-consumer probiotic subscription services confronting last-mile cold-chain viability challenges.
Netherlands
Ingredient supply concentration in Randstad fermentation specialists creates captive relationships with downstream finished goods producers across Benelux markets. ECHA coordinates REACH enforcement on strain sourcing sustainability documentation, favoring suppliers with renewable energy-linked bioreactor operations. Wageningen University's research corridor drives encapsulation technology development for ambient-stable applications.
Europe Probiotics Market Vendor Landscape
Northern European producers anchor the strain library tier; North American and Japanese specialists hold positions in branded finished goods and condition-specific formulations. Market structure consolidates around three to five fermentation houses controlling proprietary culture collections, while downstream formulation fragments across dairy cooperatives, supplement manufacturers, and functional food innovators. Strategic archetypes include captive strain developers, refrigerated shelf space controllers, and ambient stability technology licensors. Competitive moves concentrate on M&A for bioreactor capacity and strategic partnerships for EFSA dossier access.
Among the strain development tier, Chr. Hansen and BioGaia exemplify Northern European fermentation specialists leveraging culture collection depth to anchor supply relationships with dairy and supplement manufacturers. Danone occupies a position as a branded platform controller across French, German, and Spanish refrigerated retail. ADM represents the ingredient house archetype extending multi-strain concentrate supply into bakery and infant formula applications seeking compliant health claims positioning.
| Leading Market Players |
|---|
| Chr. Hansen |
| ADM |
| Danone |
| Bio-K Plus International |
| BioGaia |
| Nestlé |
| Probi |
| Daflorn |
| Yakult Honsha |
| Others |
Supply Flow & Price Mechanics
German pharmacy chains and pan-European drug store networks concentrate procurement volumes for EFSA-aligned probiotic strains, anchoring a contract-based pricing structure that rewards dossier-backed suppliers with multi-year offtake premiums while compressing margins for undifferentiated culture providers.
Pricing Analysis
Volume placements in yogurt and mass-market supplements trade at commodity-equivalent rates, while condition-specific formulations for antibiotic-associated diarrhea and IBS management in German Apotheke channels capture premium positioning. Price differentiation hinges on EFSA health claim authorization status and strain-specific genomic documentation depth. Pricing pressure stems from live culture supply concentration among Northern European fermentation houses controlling proprietary libraries. Retail consumers in supermarket dairy cases exhibit highest price sensitivity; healthcare professional intermediation in pharmacy channels suppresses direct price comparison.
Supply Chain Analysis
Reverse-logistics flows for expired or temperature-compromised probiotic batches remain underdeveloped, with most ambient-stable functional food applications lacking established return channels for viability-failed product. Strain development concentrates in Denmark, the Netherlands, and Germany, where fermentation specialists maintain captive bioreactor capacity. Raw material dependencies include fermentation feedstocks, cryoprotectant formulations, and encapsulation substrates. Single-source vulnerability runs through Northern European culture collection holders. Distribution runs through cold-chain-dependent refrigerated warehousing into pharmacy, supermarket, and health food store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation 1924/2006 erects a cost-of-compliance barrier that favors incumbent fermentation houses with existing EFSA dossiers, creating a regulatory moat that elevates capital requirements beyond mid-tier manufacturer thresholds and consolidates margin pools among validated strain suppliers.
For Market Incumbents: Hedge against flexitarian dietary displacement by accelerating non-dairy format development in oat and almond bases while securing captive bioreactor capacity with renewable energy sourcing to meet EU Green Deal mandates. Threats from ambient-stable encapsulation technology licensors require defensive patent positioning in spray-drying and lipid-coating applications. Channel control through pharmacy network education investment remains the priority lever against direct-to-consumer entrants. For New Entrants and Emerging Players: Veterinary and aquaculture feed additive buyers represent an underserved archetype with lower EFSA scrutiny and shorter commercialization cycles than human therapeutics. Italy's underpenetrated functional beverage segment offers the most penetrable white space for kombucha and botanical tonic applications. A go-to-market angle anchored by metabolic health positioning through next-generation synbiotic formulations awaiting Novel Food Catalogue reclassification bypasses standalone strain dossier burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized fermentation houses with bioinformatics capabilities and genomic documentation infrastructure in the Netherlands and Denmark over branded finished goods producers facing margin compression. Long-term viability across the analysis window rests on regulatory compliance asset accumulation rather than consumer brand equity. The signal to watch is pending EU Novel Food Catalogue revision timelines for synbiotic reclassification as an inflection indicator for metabolic health positioning plays.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Investment | Health claim authorization under Regulation 1924/2006 unlocks pharmacy channel premium positioning. |
| Captive Bioreactor Capacity | In-house fermentation with renewable energy sourcing satisfies REACH and EU Green Deal sustainability mandates. |
| Encapsulation Technology Licensing | Spray-dried and lipid-coated strains enable ambient-stable penetration into vending and convenience retail. |
| Pharmacy Channel Education Programs | Healthcare professional recommendation networks in German Apotheke amplify condition-specific formulation demand. |
| Veterinary Feed Additive Expansion | Poultry, swine, and farmed salmon applications offer adjacent demand pools with reduced regulatory friction. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fermentation house R&D directors, pharmacy chain procurement managers, dairy cooperative supply planners, and EFSA regulatory affairs consultants. Secondary sources included EFSA health claim submission databases, REACH substance registration records, EU Novel Food Catalogue entries, and national pharmacy sales audits. Bottom-up strain volume estimates triangulated against top-down category expenditure data.
Data-stream reconciliation across production volume disclosures, import-export flows, and channel inventory positions informed the analytical framework. Segmentation dimensions modeled included product type, application, end user, and distribution channel alongside strain viability requirements and cold-chain infrastructure intensity. CAGRs derived from trend extrapolation of historical trajectory patterns adjusted for regulatory inflection points. Forecast inputs incorporated EFSA authorization pipeline timelines and EU Green Deal implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Novel Food Catalogue revision timing and synbiotic reclassification decisions. Forecasts reflect documented assumptions regarding strain stability technology advancement and pharmacy channel consolidation trajectories. Practitioners should monitor EFSA health claim authorization velocity and ambient encapsulation cost curves for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Probiotic for Men Market