
 Global Saccharomyces Boulardii Market | 2026-2036
Global Saccharomyces Boulardii Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saccharomyces Boulardii Market Foresight
A shortage of qualified fermentation technologists is unwinding capacity expansion timelines across probiotic active pharmaceutical ingredient facilities. Chr. Hansen Holding A/S leverages its Danish culture collection to dominate strain authentication standards for pharmaceutical applications. Lallemand Inc. sustains North American manufacturing scale through backward integration into yeast propagation. Biocodex anchors European prescription probiotic channels with specialized sachet formulations for Clostridium difficile protocols.
Saccharomyces boulardii denotes a non-pathogenic yeast probiotic, typically lyophilized to preserve viability above 10^9 CFU per gram, manufactured through controlled aerobic fermentation for gastrointestinal therapeutic use. Capsule and sachet formats lead consumer preference in diarrhea management applications, where unit-dose stability commands margin premiums over bulk powder. The antibiotic-associated diarrhea segment grows fastest among clinical indications, driven by hospital formulary adoption and post-antibiotic recovery protocols.
FDA strain-level identity requirements and EMA qualified presumption of safety assessments shape product registration pathways and manufacturing documentation burdens. Health Canada and Australia's TGA impose parallel stability testing mandates that filter out smaller probiotic suppliers lacking analytical infrastructure. Stakeholders must monitor evolving pharmacovigilance expectations for live biotherapeutic products as regulators distinguish dietary supplements from prescription-grade probiotics.
Market Dynamics
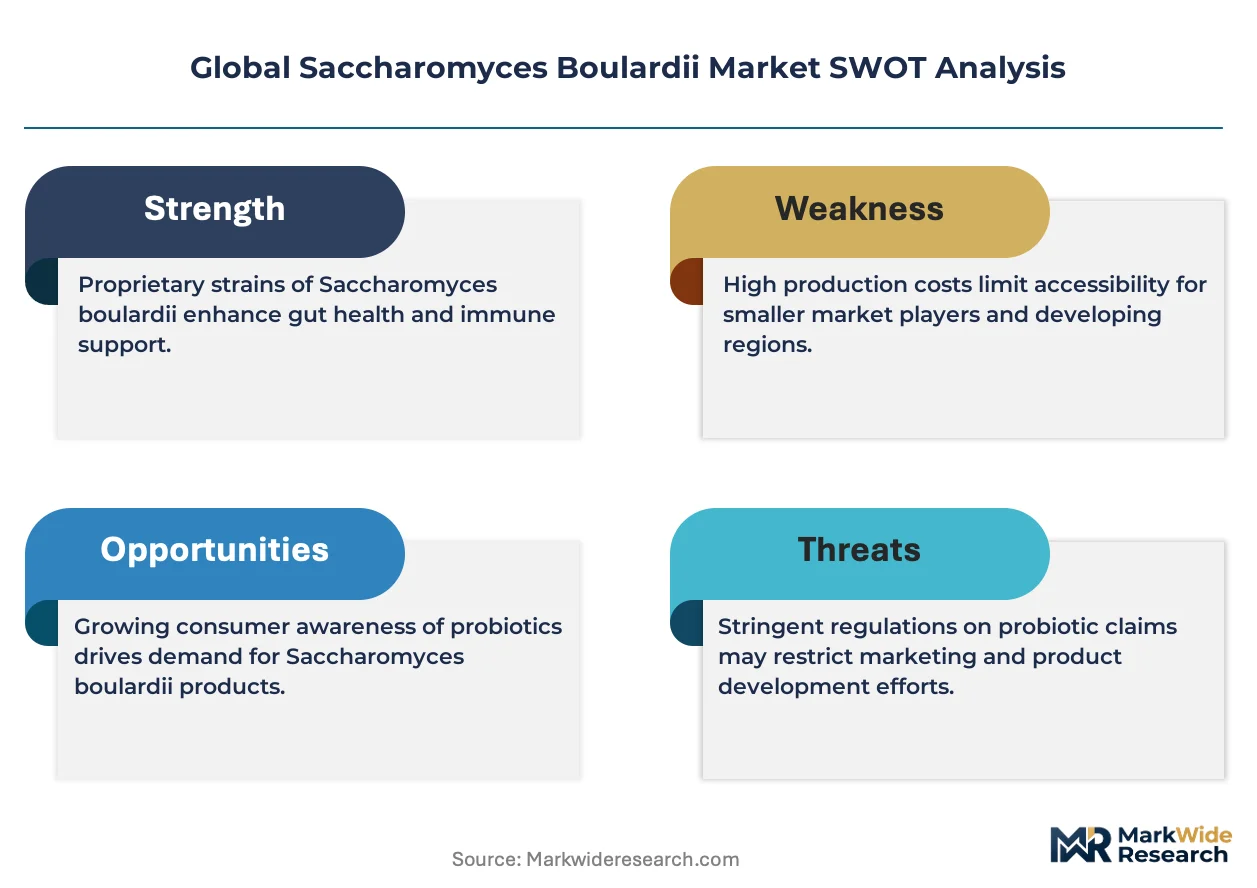
Fermentation capacity scarcity is compressing expansion timelines as qualified technologist pipelines fail to match pharmaceutical-grade probiotic demand. Strain authentication documentation burdens from FDA and EMA are redrawing competitive moats around culture collection depth.
Growth Catalysts
- Antibiotic stewardship protocols:Hospital formulary adoption of Saccharomyces boulardii for Clostridium difficile prevention is accelerating across German and French acute care networks. Post-antibiotic recovery regimens now specify live yeast therapeutics in Denmark and Sweden.
- EMA qualified presumption of safety pathway:Streamlined pharmaceutical registration for documented strains is reducing time-to-market for verified manufacturers. This regulatory clarity is pulling investment toward GMP-certified fermentation infrastructure.
- Lyophilization advances:Improved cryoprotectant formulations are extending shelf stability above 24 months at ambient temperature. Cold-chain elimination opens distribution to pharmacy networks in India and Brazil.
Market Restraints
- Molasses and yeast extract price volatility:Fermentation feedstock costs swing with sugar commodity markets and bioethanol demand competition. Input cost unpredictability erodes margin visibility for toll manufacturers.
- Danish-German production concentration:Over half of pharmaceutical-grade capacity sits within 500 kilometers of Copenhagen and Hamburg. Geographic clustering creates single-point vulnerability for strain supply security.
- PCR-based strain identification costs:Regulatory mandates for genetic authentication at batch release impose analytical infrastructure barriers. Smaller contract manufacturers lack capital for in-house sequencing capability.
Strategic Opportunities
- Pediatric diarrhea protocols in Southeast Asia:WHO guidelines for acute gastroenteritis management remain underimplemented in Indonesia and Vietnam. Local production partnerships could capture hospital channel access.
- Companion animal dermatology applications:Veterinary probiotic formulations for atopic skin conditions represent adjacent demand with lower regulatory hurdles than human pharmaceuticals. Pet insurance expansion in Japan and South Korea accelerates premium product uptake.
- Health Canada natural health product stream:Parallel regulatory pathway for non-prescription positioning allows faster market entry than FDA drug designation. This tailwind suits supplement-format innovators targeting North American retail pharmacy.
Industry Challenges
- Fermentation technologist scarcity:Specialized expertise in aerobic yeast culture at pharmaceutical scale commands premium compensation. Training pipelines at technical universities in Denmark and Germany cannot replenish retirement outflows.
- Stability testing timeline compression:Accelerated shelf-life validation for new cryoprotectant matrices conflicts with ICH guideline minimum durations. Manufacturers face pressure to launch before full real-time data completion.
- Live biotherapeutic product pharmacovigilance:Evolving FDA expectations for adverse event reporting strain quality systems designed for traditional small molecules. Post-market surveillance infrastructure requires new investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saccharomyces Boulardii Market |
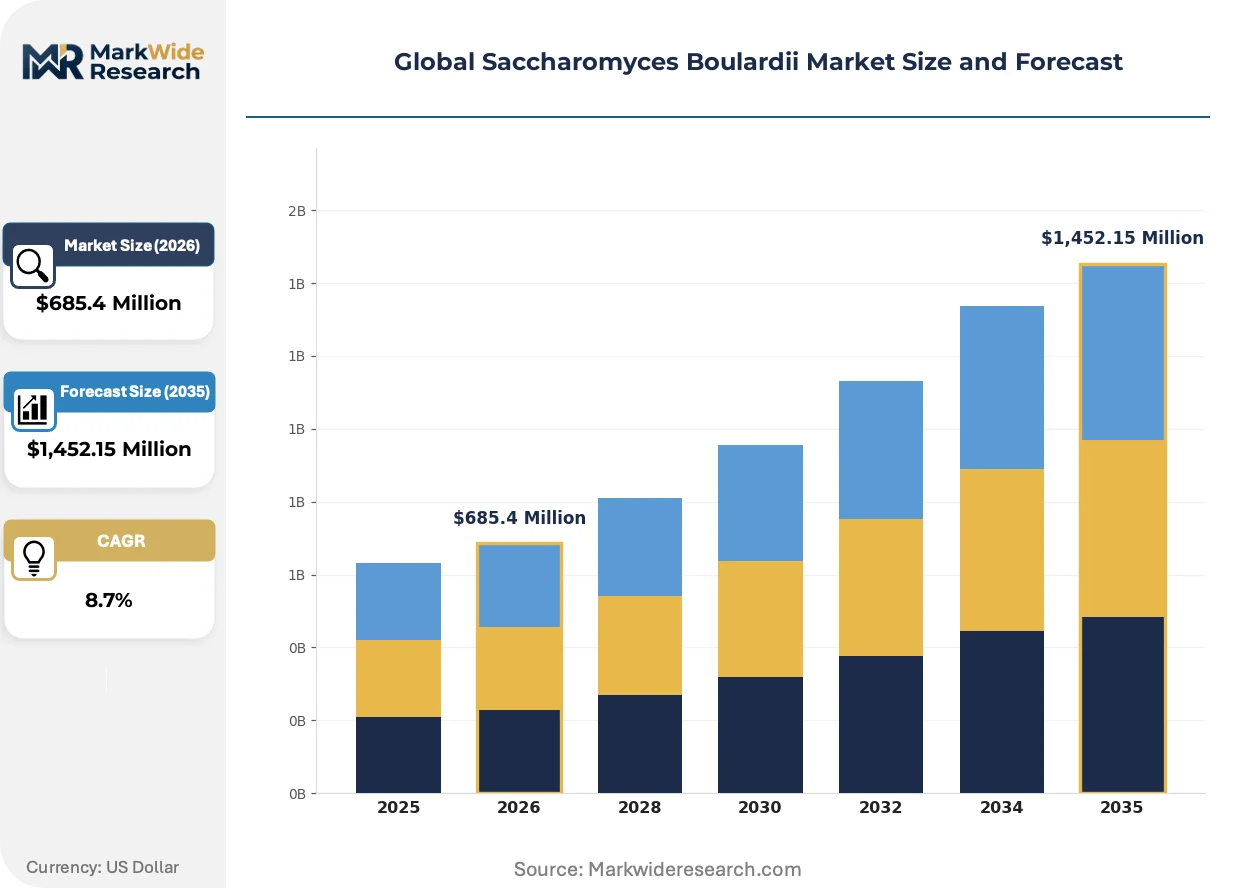
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Tablet, Sachet Application: Diarrhea Management, Irritable Bowel Syndrome, Antibiotic-Associated Diarrhea, Clostridium Difficile Infection, Traveler’s Diarrhea End User: Pharmacies, Health Clinics, Nutritional Supplement Providers, Wellness Centers, Veterinary Clinics Distribution Channel: Online Retailers, Drugstores, Direct Sales, Specialty Health Stores, Supermarkets |
| Companies Covered | Biocodex, Chr. Hansen Holding A/S, Lallemand Inc., Lesaffre Group, Probiotical S.p.A., Sanofi, DuPont, Nestlé Health Science, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saccharomyces Boulardii Market Shifts & Advancements
Strain-level genetic verification is displacing phenotypic identification as the baseline for pharmaceutical registration. Manufacturing documentation now traces from culture collection deposit through final lyophilization.
Single-use bioreactor systems for yeast fermentation are decomposing the capital intensity barrier that previously favored stainless steel installations at scale. Mid-sized contract manufacturers in the Netherlands and Switzerland are adopting disposable vessel technology to capture batch-flexible production contracts. This shift is compressing minimum efficient scale thresholds and fragmenting supply concentration.
EMA's updated guideline on quality of medicines containing live microorganisms is tightening stability demonstration requirements for multi-year shelf claims. Manufacturers must now submit accelerated and real-time data from three production batches minimum. The antibiotic-associated diarrhea segment faces the steepest compliance burden as hospital procurement mandates extend documentation depth.
Direct-to-clinic distribution models are bypassing traditional pharmaceutical wholesale channels for institutional probiotic procurement. German hospital pharmacies increasingly contract directly with manufacturers for sachet formulations. This disintermediation concentrates in acute care networks with centralized formulary committees and integrated purchasing authority.
Global Saccharomyces Boulardii Market Segmentation
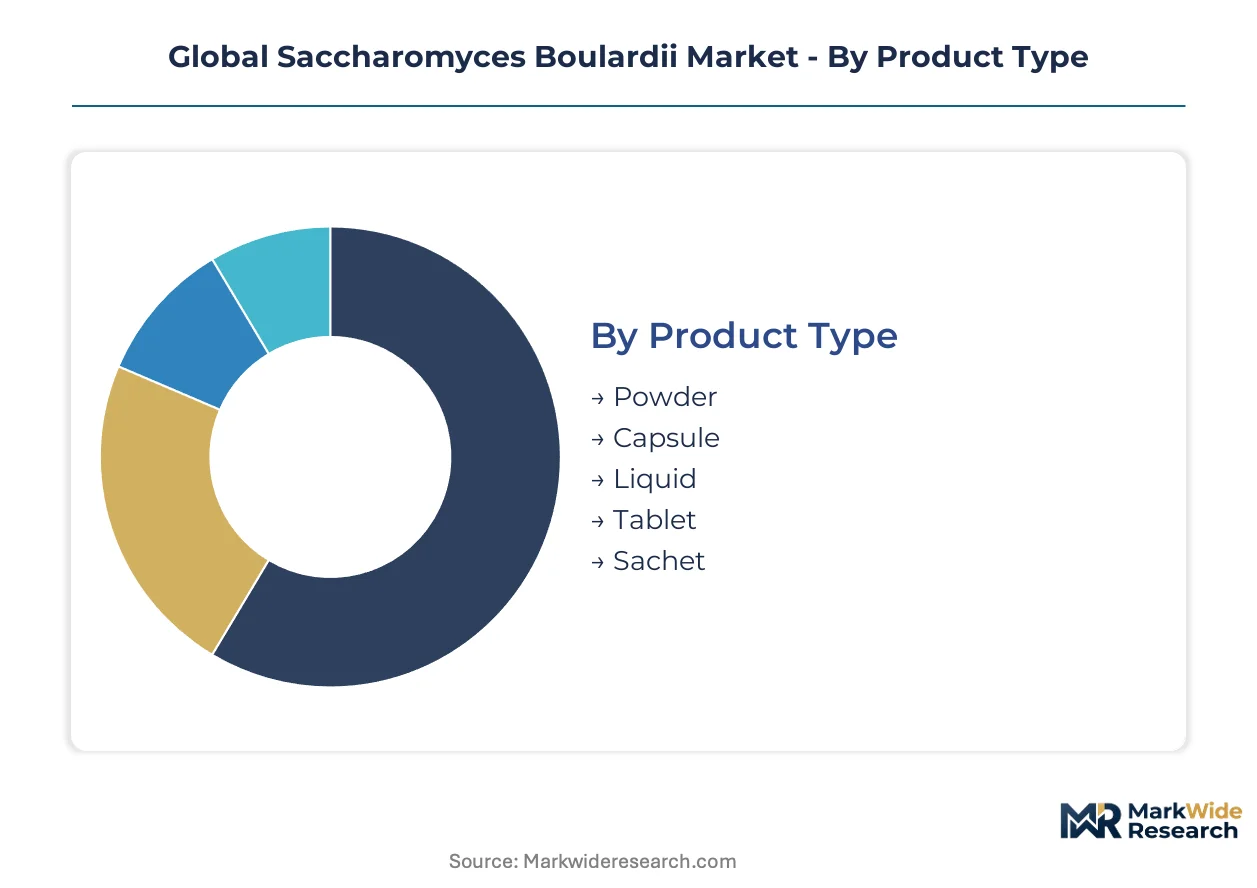
Segmentation in the Saccharomyces boulardii market reveals how formulation formats, clinical indications, and procurement channels create distinct margin structures. Each dimension carries different regulatory burdens and substitution vulnerabilities that reshape competitive positioning.
Product Type:
Capsule and powder formats face the strongest substitution pressure from emerging liquid concentrates and effervescent tablets targeting pediatric and geriatric populations who struggle with solid dosing.
- Capsule:Gelatin or vegetable-based shells containing lyophilized yeast at standardized potencies, typically 250mg or 500mg unit doses. German hospital pharmacies specify hard-shell capsules for formulary compliance in Clostridium difficile protocols, where precise CFU counts per dose reduce therapeutic variability.
- Powder:Bulk lyophilized material requiring reconstitution, favored by compound pharmacies and veterinary formulators seeking dose flexibility. Brazilian nutritional supplement providers blend powder into multi-strain synbiotic products, though ambient stability concerns limit export potential.
- Liquid:Aqueous suspensions with shorter shelf life, positioned for pediatric administration in French and Italian markets.
- Tablet:Compressed formulations with binders and disintegrants, competing on convenience in North American retail channels.
- Sachet:Single-dose foil packets, dominant in Southeast Asian hospital procurement for traveler’s diarrhea prophylaxis.
Capsule anchors the volume base while sachet gains share at the steepest rate.
Application:
Cost tier stratification separates hospital-grade prescription indications from self-directed wellness applications, with reimbursement status determining formulation investment intensity.
- Antibiotic-Associated Diarrhea:Hospital-acquired infection prevention protocols in Denmark and Sweden specify live yeast therapeutics for post-antibiotic recovery regimens. EMA qualified presumption of safety documentation supports prescription positioning, commanding premium pricing over supplement-grade alternatives.
- Clostridium Difficile Infection:Adjunctive therapy for recurrent C. difficile, with German acute care networks driving formulary adoption. Biocodex anchors European prescription channels with specialized sachet formulations requiring strain authentication at batch release.
- Diarrhea Management:General acute gastroenteritis indication spanning OTC and prescription tiers.
- Irritable Bowel Syndrome:Emerging evidence base supports symptom modulation, though regulatory classification varies by jurisdiction.
- Traveler’s Diarrhea:Prophylactic use in tourism and military contexts, with stability requirements favoring lyophilized formats.
Diarrhea management anchors the volume base while antibiotic-associated diarrhea climbs the fastest.
End User:
Customer type concentration reflects divergent procurement authority, with institutional buyers demanding documentation depth that filters out smaller suppliers.
- Pharmacies:Community and hospital dispensaries with formulary committees or direct purchasing authority. German hospital pharmacies increasingly contract directly with manufacturers, bypassing wholesale intermediaries for sachet formulations.
- Health Clinics:Outpatient facilities integrating probiotics into functional medicine protocols, particularly in Swiss and Austrian markets.
- Nutritional Supplement Providers:Direct-to-consumer brands and private label manufacturers, facing FDA strain verification requirements.
- Wellness Centers:Preventive health facilities with lower regulatory scrutiny but price-sensitive clientele.
- Veterinary Clinics:Companion animal dermatology and gastrointestinal applications, with Japan and South Korea showing premium product uptake through pet insurance expansion.
Pharmacies anchor the volume base while veterinary clinics expand most quickly.
Distribution Channel:
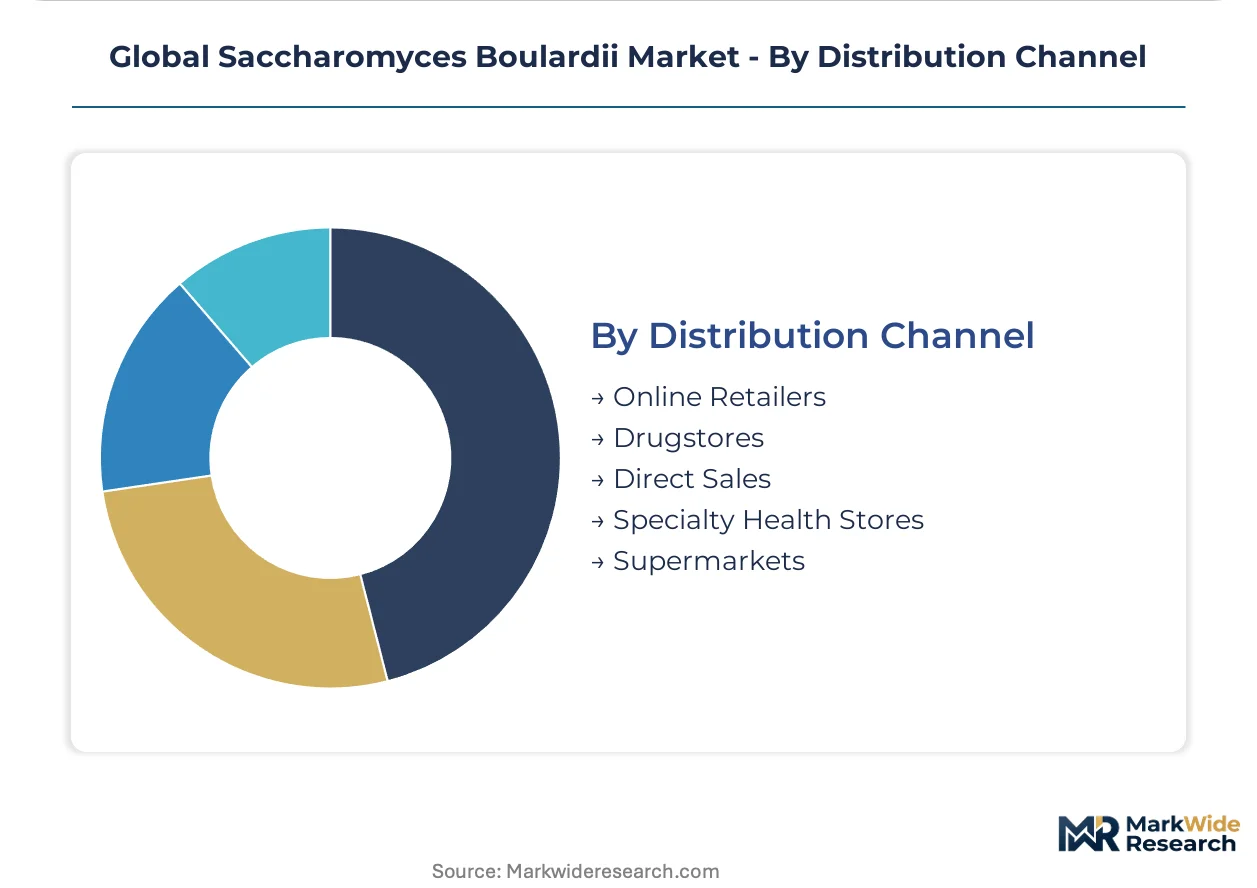
Supply concentration in direct sales and specialty channels reflects the technical consultation required for strain-specific therapeutic selection.
- Direct Sales:Manufacturer-to-institution contracts for hospital formulary placement, dominant in German and French acute care networks with centralized purchasing authority.
- Drugstores:Brick-and-mortar pharmacy retail with pharmacist consultation, maintaining share in European markets with strong community pharmacy traditions.
- Online Retailers:E-commerce platforms capturing self-directed consumers, though cold-chain concerns limit liquid format participation.
- Specialty Health Stores:Natural products retailers with trained staff, concentrated in North American urban markets.
- Supermarkets:Mass-market retail with minimal staff guidance, suited to established brands with consumer recognition.
Drugstores anchor the volume base while direct sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA qualified presumption of safety assessments anchor European pharmaceutical-grade production, while FDA strain verification protocols shape North American market entry. German and Danish industrial clusters concentrate half of global fermentation capacity within a 500-kilometer radius.
Germany
Hospital formulary adoption for Clostridium difficile protocols drives institutional procurement across acute care networks. The national pharmaceutical regulator enforces batch-level strain authentication for prescription-grade probiotics. Hamburg anchors production capacity where manufacturers contract directly with hospital pharmacies, bypassing wholesale intermediaries.
United States
FDA strain-level identity requirements filter out smaller suppliers lacking analytical infrastructure for genetic verification. Health Canada parallel stability testing mandates create cross-border regulatory alignment for North American market access. Greater Boston and Research Triangle Park host quality control laboratories serving contract manufacturers seeking drug designation pathways.
France
ANSM pharmacovigilance expectations for live biotherapeutic products reshape post-market surveillance investment. EMA guideline updates on quality of medicines containing live microorganisms tighten stability demonstration requirements. Lyon and Paris clusters specialize in lyophilized sachet formulations for pediatric and geriatric administration.
Denmark
Post-antibiotic recovery regimens specifying live yeast therapeutics accelerate hospital channel demand. The national technical university pipeline fails to replenish retirement outflows among specialized fermentation technologists. Copenhagen anchors strain authentication standards through culture collection depth and GMP-certified infrastructure.
India
WHO guideline underimplementation for acute gastroenteritis management creates hospital channel access opportunities. CDSCO natural health product pathways offer faster market entry than pharmaceutical drug designation. Hyderabad and Bangalore clusters develop ambient-stable formulations eliminating cold-chain requirements for domestic pharmacy distribution.
Global Saccharomyces Boulardii Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the fermentation value chain. The market structures around three tiers: integrated culture collection owners, toll manufacturers with GMP infrastructure, and supplement-format brands lacking strain verification capability. Danish and North American players anchor the premium tier through backward integration into yeast propagation. Competitive moves concentrate on capacity expansion timelines and direct-to-clinic distribution partnerships that disintermediate wholesale channels.
Within the integrated pharmaceutical-grade tier, Chr. Hansen Holding A/S and Lallemand Inc. exemplify archetypes combining culture collection depth with manufacturing scale. Biocodex occupies a distinct position specializing in prescription-channel sachet formulations. These three entities represent the dominant competitive anchors as regulatory documentation burdens redraw competitive moats around strain authentication infrastructure.
| Leading Market Players |
|---|
| Biocodex |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| Lesaffre Group |
| Probiotical S.p.A. |
| Sanofi |
| DuPont |
| Nestlé Health Science |
| DSM-Firmenich |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German hospital pharmacies and Copenhagen-based fermentation facilities lock in strain supply security while capping price volatility for pharmaceutical-grade lyophilized yeast. These agreements bind capacity reservation fees to EMA qualified presumption of safety documentation milestones, creating mutual dependency that shields qualified manufacturers from spot-market molasses cost swings.
Pricing Analysis
German hospital procurement commands premium spreads over Brazilian nutritional supplement channels, where ambient-stable formulations trade at standard-tier discounts. Three-tier pricing structure across premium prescription-grade, standard dietary supplement, and economy bulk powder levels reflects certification depth and strain authentication burden. Cost compression in the economy tier intensifies because toll manufacturers lack in-house PCR sequencing capability. Nutritional supplement providers show highest price sensitivity, while German acute care networks prioritize documentation reliability over unit cost.
Supply Chain Analysis
Germany and Denmark anchor pharmaceutical-grade fermentation capacity, with Hamburg and Copenhagen clusters housing over half of global GMP-certified yeast propagation infrastructure. Production draws from molasses feedstock and specialized yeast extract nutrients, both subject to sugar commodity market volatility and bioethanol demand competition. Single-point vulnerability concentrates in the Danish-German corridor, where qualified technologist scarcity constrains capacity expansion timelines. Distribution runs through direct-to-clinic contracts for hospital formulary placement, bypassing traditional pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where EMA and FDA strain verification protocols create switching costs that cement incumbent positions. The documentation burden for live biotherapeutic product registration erects barriers that compound over time.
For Market Incumbents: Fortify culture collection depth through exclusive access agreements with national fermentation technical universities, countering technologist retirement outflows that threaten capacity expansion timelines. Deepen backward integration into captive yeast propagation to insulate margin structures from molasses price volatility and bioethanol demand competition. For New Entrants and Emerging Players: Pediatric diarrhea protocol implementation gaps in Indonesian and Vietnamese hospital channels represent underserved demand with lower regulatory documentation thresholds than European prescription pathways. Local production partnerships with WHO guideline alignment offer faster market access than competing directly with Biocodex's European sachet dominance. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized contract manufacturers with disposable bioreactor adoption and pending EMA qualified presumption of safety submissions, positioning for hospital channel consolidation. Watch for CDSCO natural health product pathway acceleration in India as signal of ambient-stable formulation viability and cold-chain elimination economics.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualified Presumption of Safety Submission | Streamlined pharmaceutical registration reduces time-to-market for verified manufacturers against supplement-grade competitors. |
| Disposable Bioreactor Technology Adoption | Single-use vessel systems compress minimum efficient scale thresholds and fragment supply concentration among mid-sized players. |
| Direct-to-Clinic Distribution Partnership | Bypassing wholesale intermediaries captures margin and locks in German hospital formulary placement through sachet specialization. |
| Culture Collection Depth Expansion | Exclusive strain authentication infrastructure redraws competitive moats as FDA and EMA tighten batch-release genetic verification mandates. |
| Companion Animal Dermatology Formulation Development | Veterinary probiotic applications face lower regulatory hurdles than human pharmaceuticals while pet insurance expansion accelerates premium uptake in Japan. |
Research Methodology
A standing panel of fermentation technologists, regulatory affairs directors at probiotic manufacturers, German hospital pharmacy procurement managers, and EMA qualified person consultants provided ongoing calibration across the research window. Primary interviews combined with secondary validation from FDA strain verification guidance documents, EMA quality of medicines containing live microorganisms guidelines, CDSCO natural health product regulations, and customs trade data for molasses and yeast extract feedstocks. Bottom-up capacity modeling and top-down demand triangulation anchored market sizing.
Consistency checks validated volume and value outputs against hospital formulary adoption rates, strain authentication batch-release frequencies, and lyophilization capacity utilization surveys. The analytical framework modeled formulation format, clinical indication, procurement channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth drivers and constraint analysis, with specific inputs including antibiotic stewardship protocol expansion timelines and fermentation technologist pipeline graduation rates.
Underlying assumptions cover EMA guideline stability, FDA pharmacovigilance expectations for live biotherapeutic products, and molasses commodity price bands, with deviation risk concentrated in regulatory timeline acceleration or feedstock supply disruption. Recalibration cycles align with material shifts in hospital formulary adoption, strain verification technology costs, or single-use bioreactor adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Global Liquid Feed Supplements Market