

Bifidobacteria Lysates Market Size, Share, and Industry Trends Forecast 2026-2036
Bifidobacteria Lysates Market Insights
Asset-light contract fermentation and toll-manufacturing arrangements are tilting competitive dynamics toward brands that lack captive bioreactor capacity. BASF leverages its industrial biotechnology infrastructure to supply lysate concentrates at scale. Croda International anchors its position through lipid-compatible formulation expertise that integrates lysates into emulsion systems. Evonik Industries differentiates via high-purity filtration and downstream processing capabilities that meet pharmaceutical-grade specifications.
Bifidobacteria lysates comprise cell-wall fragments, metabolites, and exopolysaccharides extracted through controlled fermentation and mechanical lysis of Bifidobacterium strains, typically standardized for protein content and endotoxin levels. These preparations modulate skin microbiome balance and reduce inflammatory cytokine expression in topical applications, while oral forms support gastrointestinal barrier integrity. Freeze-dried powder dominates current supply volumes due to stability advantages in long-haul distribution, though liquid suspension formats are gaining traction in premium dermatological care where freshness signaling commands formulation value. Digestive health retains the largest therapy area footprint, yet dermatological care represents the fastest-expanding margin pool as cosmetic specialists seek clinically positioned alternatives to traditional preservatives.
The EU Cosmetics Regulation and REACH frameworks govern ingredient safety documentation and restrict preservative alternatives, creating compliance thresholds that favor established lysate suppliers with toxicological dossiers. FDA oversight of cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act intensifies documentation demands for US market entry. South Korea's MFDS and Ministry of Food and Drug Safety maintain stringent fermentation-derived cosmetic ingredient standards that shape regional quality benchmarks. Stakeholders must monitor evolving preservative restriction schedules and build dual-purpose oral-topical manufacturing flexibility before regulatory divergence fragments supply qualification requirements.
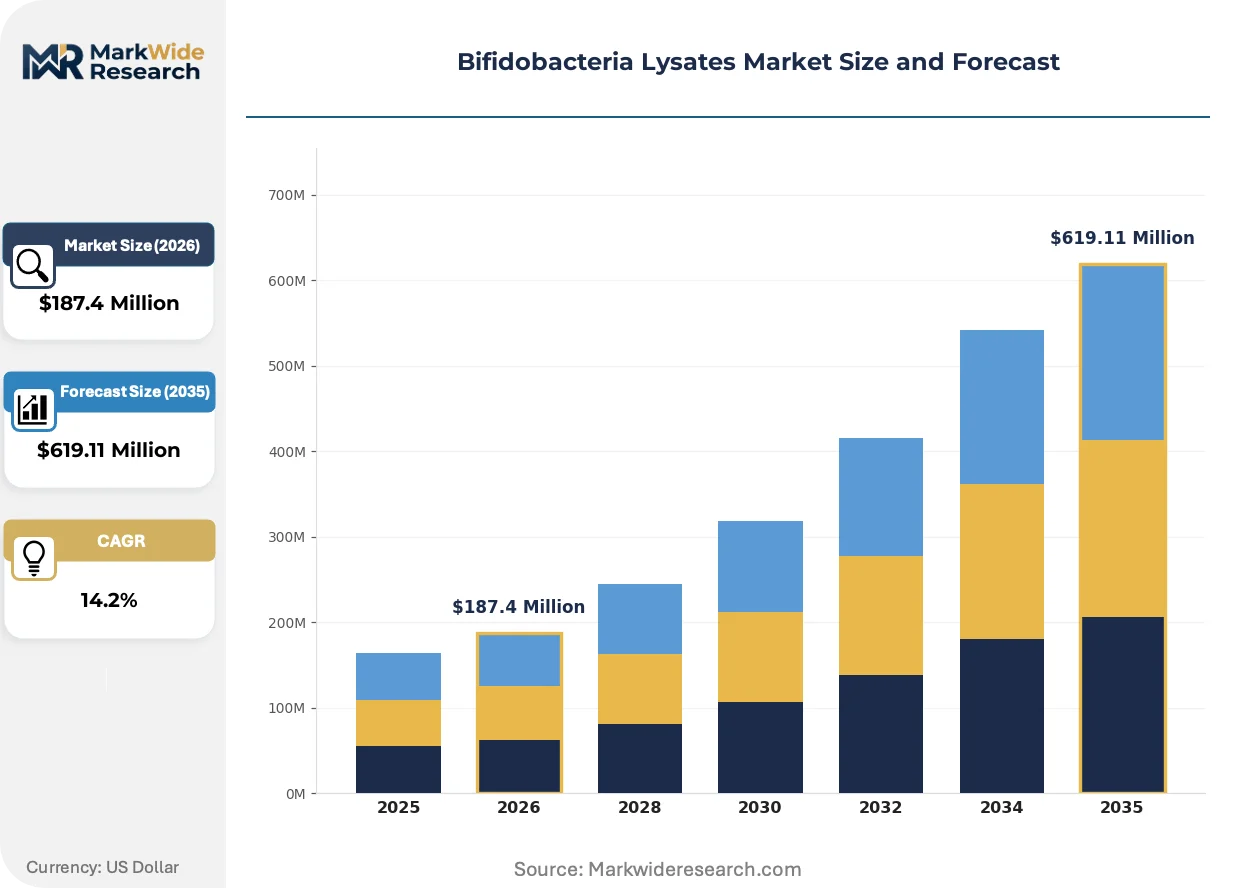
Market Dynamics
Asset-light contract fermentation arrangements are concentrating supply leverage with toll-manufacturing specialists, tilting competitive dynamics toward brands lacking captive bioreactor capacity and forcing R&D budget reallocation toward external lysate sourcing partnerships.
Growth Catalysts
- EU Cosmetics Regulation disclosure mandates:Stricter ingredient transparency requirements under REACH and the EU Cosmetics Regulation are accelerating procurement of fermentation-derived actives with established toxicological dossiers.
- K-Beauty microbiome positioning:South Korean cosmetic specialists are expanding procurement of topical-grade lysates as MFDS standards shape regional quality benchmarks for probiotic skincare.
- Freeze-dried powder stability advantages:Long-haul distribution requirements favor lyophilized formats, with liquid suspensions gaining traction specifically in premium dermatological care segments.
Market Restraints
- Endotoxin control costs:Pharmaceutical-grade filtration and downstream processing requirements impose capital intensity that excludes smaller fermentation operators from qualification pools.
- East Asian supply concentration:Demand gravity in South Korea, Japan, and China creates geographic vulnerability to regional regulatory divergence and logistics disruption.
- Preservative substitution complexity:FDA oversight under the Modernization of Cosmetics Regulation Act intensifies documentation burdens for US market entry, extending qualification timelines.
Strategic Opportunities
- Oral-topical manufacturing flexibility:Dual-purpose production infrastructure enables suppliers to pivot between digestive health and dermatological applications as regulatory schedules fragment.
- US dermatological channel expansion:Underpenetrated clinical skincare positioning in North American markets offers margin expansion beyond commodity probiotic supplements.
- Exopolysaccharide standardization:Emerging metagenomic quality control methods enable premium tiering based on specific metabolite profiles rather than crude protein content.
Industry Challenges
- Bioprocess engineering talent scarcity:Specialized expertise in mechanical lysis optimization and strain-specific fermentation protocols concentrates among legacy pharmaceutical microbiology teams.
- Dual jurisdiction compliance synchronization:Maintaining parallel toxicological dossiers for EU REACH and FDA cosmetic ingredient safety requirements strains smaller supplier documentation capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifidobacteria Lysates Market Trends and Innovations
Fermentation-derived actives are commanding formulation value through clinical positioning, with technology convergence and regulatory pressure reshaping how lysates integrate into finished product architectures across oral and topical delivery systems.
Continuous fermentation monitoring via inline metabolite sensors is rendering obsolete batch-release quality control that relies on post-hoc endotoxin testing. Cosmetic formulators in Seoul and Tokyo are adopting real-time bioprocess data to compress supplier qualification cycles. This shift compresses working capital requirements for brands while raising technical barriers for legacy toll-manufacturers lacking digital bioreactor infrastructure.
REACH restriction schedules for traditional cosmetic preservatives are accelerating R&D migration toward fermentation-derived alternatives with inherent antimicrobial properties. The EU Green Deal's chemical sustainability targets are amplifying pressure on formulators to document biodegradability across ingredient supply chains. Dermatological care segments in Germany and France are responding fastest, with procurement specifications now prioritizing lysates with cradle-to-gate lifecycle assessments.
Freshness signaling in premium skincare is displacing shelf-stable commodity positioning as the primary value anchor for liquid suspension formats. Direct-to-consumer channels in South Korea are unbundling clinical credibility from institutional pharmacy distribution, with tele-dermatology platforms driving ingredient literacy among end-users. This behavioral shift concentrates margin capture with brands that can communicate strain-specific mechanistic claims rather than generic probiotic labeling.
Bifidobacteria Lysates Market Segmentation
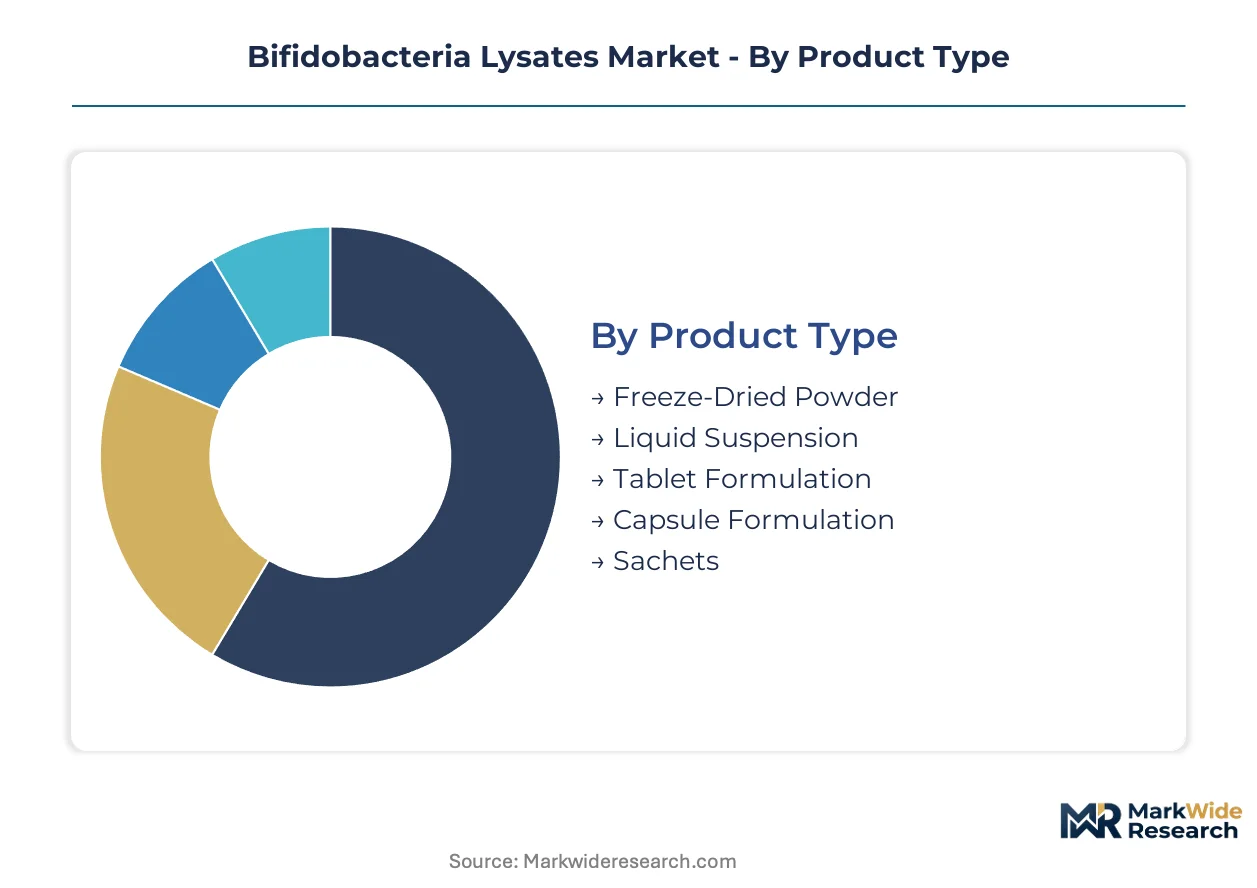
Segmentation in bifidobacteria lysates reflects divergent technical specifications across delivery formats and therapy areas. Formulation stability requirements and regulatory qualification thresholds create distinct margin architectures for each category.
Product Type:
After-sales technical support intensity varies sharply across formats, with lyophilized powders demanding minimal field service while liquid suspensions require cold-chain monitoring and freshness validation protocols.
- Freeze-Dried Powder:Lyophilized cell lysates with standardized protein content and endotoxin levels dominate long-haul distribution networks. Pharmaceutical procurement in Germany and Japan prioritizes this format for gastrointestinal applications where shelf stability reduces inventory risk.
- Liquid Suspension:Fresh lysate concentrates with intact metabolite profiles command premium positioning in Seoul's cosmetic formulation studios. MFDS-compliant cold-chain documentation and real-time bioprocess data enable compressed supplier qualification cycles for dermatological brands.
- Tablet Formulation:Compressed delivery systems with enteric coating for gastric bypass in oral digestive health applications.
- Capsule Formulation:Gelatin or HPMC encapsulation for consumer supplement channels requiring dose precision.
- Sachets:Single-unit powder packaging for institutional nutritional programs and travel-oriented wellness positioning.
Freeze-dried powder holds the largest share; momentum sits with liquid suspension.
Therapy Area:
Cost tier stratification separates commodity gastrointestinal positioning from premium dermatological claims, with regulatory documentation burdens scaling directly with clinical positioning intensity.
- Digestive Health:Oral formulations targeting intestinal barrier integrity and microbiome modulation retain the broadest reimbursement coverage and pharmacy distribution footprint. EU EFSA health claim substantiation requirements favor established suppliers with longitudinal clinical datasets.
- Dermatological Care:Topical lysates with anti-inflammatory cytokine modulation properties are expanding fastest among Seoul and Tokyo cosmetic formulators. REACH-compliant toxicological dossiers and preservative-free positioning drive procurement specifications in France and Germany.
- Immune Support:Respiratory and systemic immune modulation applications with emerging clinical trial backing.
- Respiratory Wellness:Nasal delivery systems targeting upper airway microbiome colonization.
- Nutritional Supplementation:General wellness positioning with lower regulatory barriers and commodity pricing dynamics.
Digestive health commands volume leadership; dermatological care is climbing the fastest.
End User:
Customer type concentration determines contract structure, with institutional buyers demanding multi-year supply agreements and cosmetic specialists preferring flexible toll-manufacturing arrangements.
- Cosmetic Specialists:Seoul-based formulators and Parisian dermatological brands drive premium lysate procurement with strain-specific mechanistic claims. Direct-to-consumer tele-dermatology platforms are unbundling clinical credibility from traditional pharmacy distribution, concentrating margin with ingredient-literate brands.
- Pharmacies:German and Japanese retail pharmacy networks anchor digestive health volume with established probiotic supplement shelving. Reimbursement code availability and pharmacist recommendation protocols sustain repeat purchase patterns.
- Wellness Clinics:Functional medicine practitioners in California and integrative health centers in Switzerland.
- Nutritional Centers:Sports nutrition and personalized wellness programs with subscription-based delivery models.
- Research Institutes:Academic microbiome studies and clinical trial material supply with batch documentation requirements.
Pharmacies retain the largest share; cosmetic specialists are gaining share fastest.
Delivery Mode:
Supply concentration for specialized delivery infrastructure creates qualification bottlenecks, with nasal and injectable formats dependent on contract manufacturing partners with dedicated sterile processing lines.
- Oral Administration:Capsule, tablet, and sachet formats dominate volume through established supplement manufacturing infrastructure. FDA dietary supplement cGMP compliance and EU food supplement directives govern qualification thresholds for US and European market entry.
- Topical Application:Emulsion-compatible lysate concentrates integrate into Seoul's K-Beauty microbiome-friendly formulations. Croda's lipid-compatible formulation expertise and BASF's industrial biotechnology infrastructure enable scale supply for premium skincare brands.
- Nasal Spray:Upper respiratory microbiome targeting with specialized atomization device compatibility.
- Injectable Form:Parenteral-grade endotoxin control for clinical research and specialized therapeutic applications.
- Transdermal Patch:Extended-release dermal delivery systems with adhesive matrix compatibility requirements.
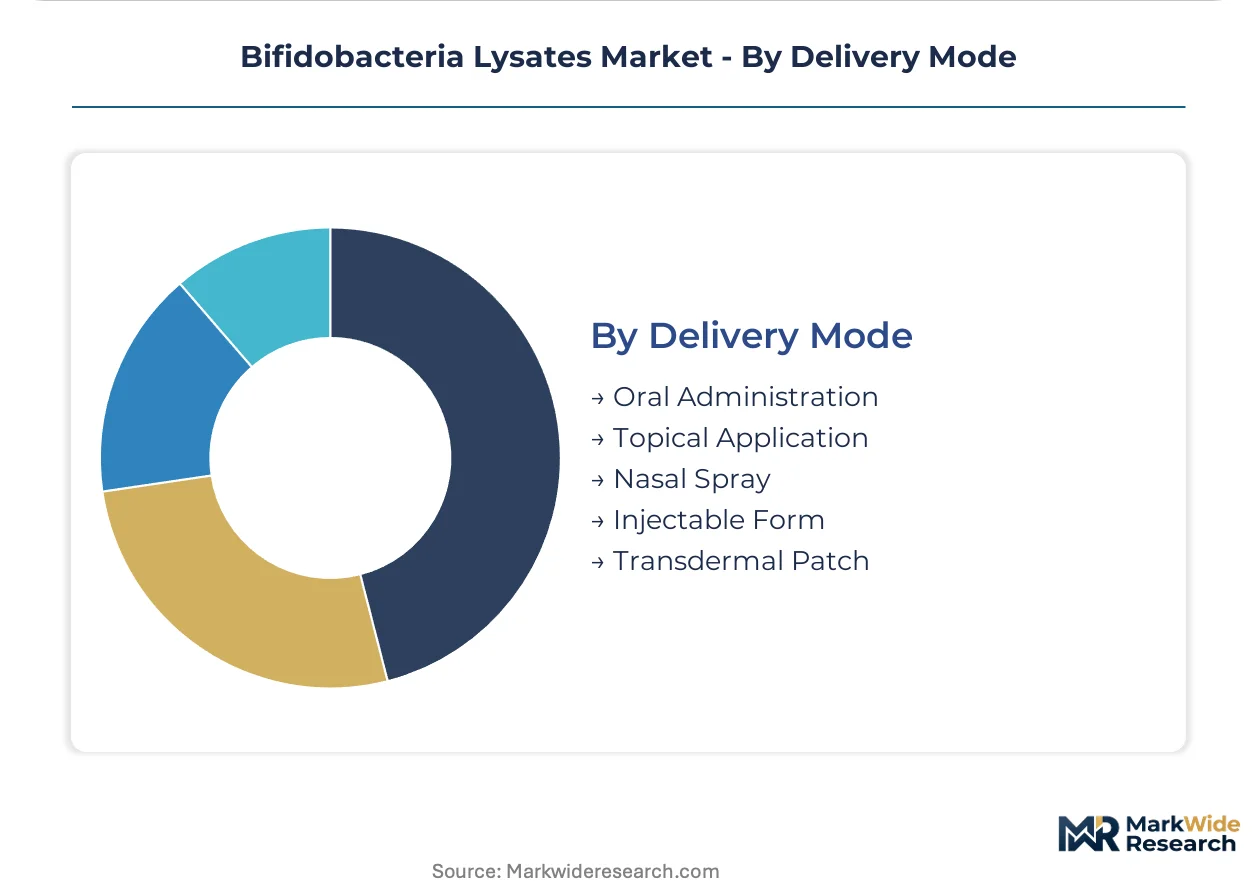
Oral administration holds the largest share; topical application shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul commands premium pricing for topical-grade lysates while German procurement anchors volume at standardized rates, creating a transregional arbitrage that shapes contract fermentation capacity allocation.
South Korea
Seoul's cosmetic formulation studios drive premium lysate procurement through K-Beauty microbiome positioning and tele-dermatology platform expansion. MFDS maintains stringent fermentation-derived cosmetic ingredient standards that filter supplier qualification pools. The capital region concentrates toll-manufacturing partnerships for liquid suspension formats with real-time bioprocess data requirements.
Germany
Pharmaceutical procurement in Germany prioritizes freeze-dried powder formats for gastrointestinal applications with established EFSA health claim dossiers. REACH and EU Cosmetics Regulation frameworks govern ingredient safety documentation and preservative restriction schedules. The Rhine-Ruhr industrial corridor hosts industrial biotechnology infrastructure serving both oral and topical lysate production.
United States
California functional medicine practitioners and institutional supplement channels sustain digestive health volume despite underpenetrated dermatological positioning. FDA oversight under the Modernization of Cosmetics Regulation Act intensifies documentation burdens for cosmetic ingredient market entry. The Boston-Cambridge biotechnology cluster concentrates contract fermentation R&D for pharmaceutical-grade endotoxin control.
Japan
Tokyo and Osaka retail pharmacy networks anchor probiotic supplement distribution with established reimbursement codes and pharmacist recommendation protocols. METI and PMDA standards shape quality benchmarks for oral lysate formulations. The Kanto region concentrates legacy pharmaceutical microbiology teams with specialized bioprocess engineering expertise.
France
Parisian dermatological brands and cosmetic formulators drive REACH-compliant lysate procurement with cradle-to-gate lifecycle assessment requirements. ANSM enforces preservative-free positioning standards that accelerate R&D migration toward fermentation-derived alternatives. The Île-de-France region concentrates premium skincare brands seeking clinically positioned microbiome actives.
Bifidobacteria Lysates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with bioreactor capacity and filtration expertise. The vendor base concentrates around three tiers: multinational chemical conglomerates with industrial biotechnology infrastructure, specialty ingredient houses with formulation integration capabilities, and toll-manufacturing specialists with flexible fermentation assets. Strategic moves center on contract fermentation partnerships and dual-purpose oral-topical manufacturing flexibility.
Among multinational chemical conglomerates, BASF leverages industrial biotechnology infrastructure to anchor supply scale. Croda International and Evonik Industries exemplify the specialty ingredient tier, with the former representing lipid-compatible formulation expertise and the latter occupying a position in high-purity downstream processing. These three entities sit within distinct competitive archetypes that structure procurement options for brands lacking captive bioreactor capacity.
| Leading Market Players |
|---|
| BASF |
| Croda International |
| Evonik Industries |
| Symrise |
| Seppic |
| Ashland |
| Clariant |
| Shiseido |
| Estée Lauder Companies |
| Others |
Pricing and Supply Chain Analysis
Contract fermentation undercapacity in South Korea's capital region tilts supplier bargaining power toward brands with multi-year offtake commitments, compressing spot-market availability while elevating configured-to-order premiums for cosmetic-grade lysates. This utilization squeeze propagates through German pharmaceutical procurement channels, where freeze-dried powder contracts now carry extended lead-time penalties.
Pricing Analysis
The customization-premium spread separates liquid suspension formats with real-time bioprocess data from commodity freeze-dried powders, with pricing stratifying across pharmaceutical-grade, cosmetic-grade, and feed-grade certification tiers. Price differentiation hinges on endotoxin documentation depth and MFDS-compliant cold-chain validation, with cosmetic specialists in Seoul showing lowest price sensitivity due to freshness-signaling formulation value. Cost compression in standard-grade digestive health powders is intensifying because toll-manufacturers compete for pharmaceutical contract volume, while premium dermatological lysates maintain pricing power through strain-specific mechanistic claims.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment limit bioreactor capacity expansion in emerging supply zones, concentrating qualified production among South Korea, Germany, and Japan. Raw material flows draw from specialized Bifidobacterium strain banks, pharmaceutical-grade filtration membranes, and lyophilization excipients, with supply chain risk anchored in single-source vulnerability for high-purity downstream processing equipment. Distribution runs through cold-chain logistics partnerships for liquid formats and ambient pharmaceutical distribution networks for freeze-dried powders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
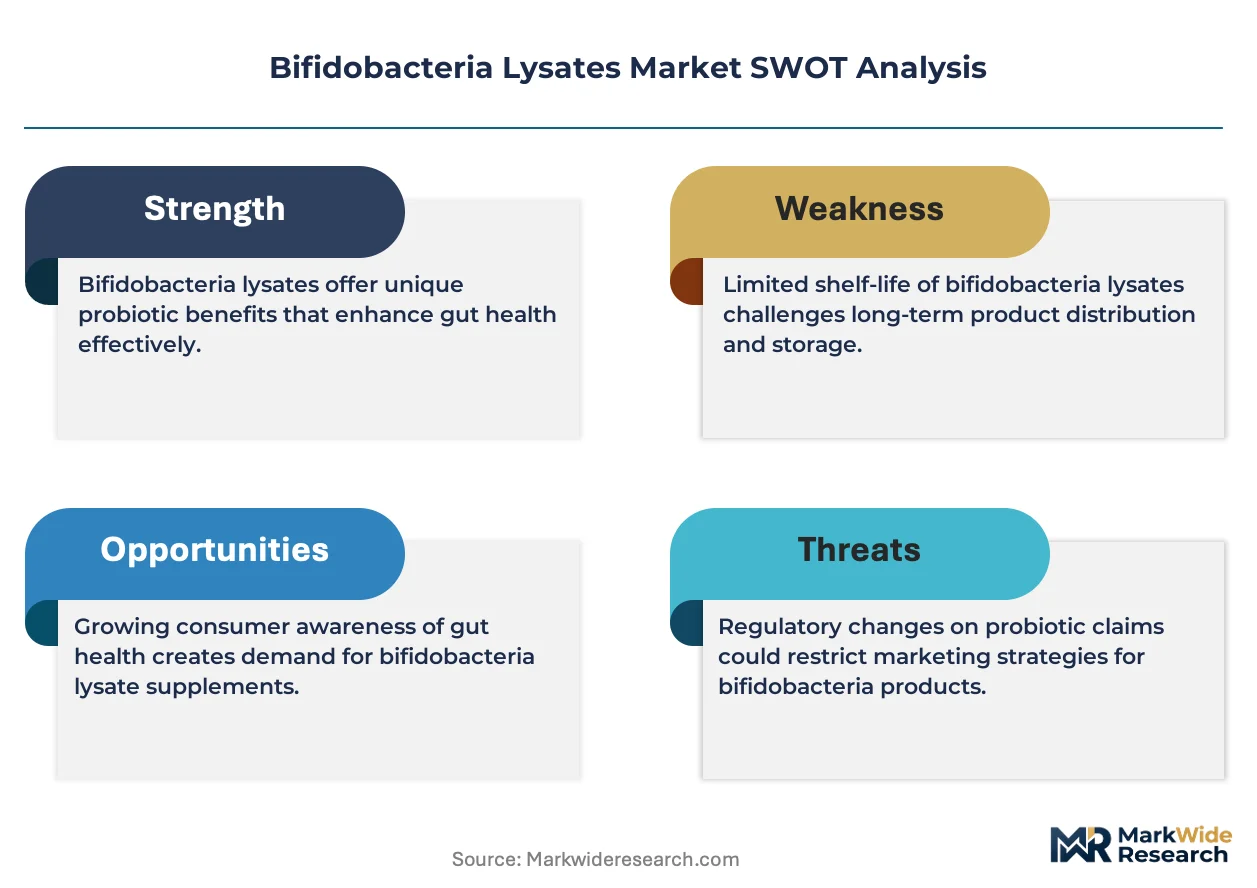
The Bifidobacteria Lysates Market tracks a cyclical recovery pattern as post-pandemic inventory destocking in oral digestive health supplements exhausts, with restocking demand from German and Japanese pharmacy channels driving volume normalization.
For Market Incumbents: Build regulatory dossier moats by filing parallel EFSA health claim substantiations and FDA cosmetic ingredient safety documentation before divergence between EU and US preservative restriction schedules widens qualification gaps. Incumbents should anchor capacity addition in the Rhine-Ruhr corridor to serve dual oral-topical demand, while investing in inline metabolite sensor infrastructure to compress supplier qualification cycles for Seoul-based cosmetic formulators threatened by digital bioreactor entrants. For New Entrants and Emerging Players: Build out toll-manufacturing partnerships with asset-light fermentation operators in South Korea's capital region, where MFDS compliance infrastructure already exists but local bioprocess engineering talent scarcity constrains scale-up velocity. The most penetrable white space sits in North American dermatological channels, where clinical skincare positioning remains underdeveloped relative to commodity probiotic supplements; entrants should pursue tele-dermatology platform partnerships to bypass traditional pharmacy distribution barriers and capture margin through direct-to-consumer ingredient literacy. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract fermentation specialists with multi-year cosmetic supply agreements, where qualification switching costs lock in offtake visibility across regulatory cycles. Long-term viability in this market rests on dual-purpose oral-topical manufacturing flexibility, making toll-manufacturing assets with existing bioreactor infrastructure the priority acquisition archetype. The signal to watch is MFDS adoption of real-time bioprocess data standards, which would accelerate consolidation toward digitally enabled suppliers and strand legacy batch-release operators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Purpose Manufacturing Flexibility | Enables pivot between digestive health and dermatological applications as EU and US regulatory schedules diverge on preservative alternatives. |
| Real-Time Bioprocess Data Integration | Compresses supplier qualification cycles for Seoul cosmetic formulators adopting inline metabolite sensors over batch-release testing. |
| Parallel Regulatory Dossier Filing | Builds defensible positioning against REACH and FDA cosmetic ingredient safety documentation burdens before qualification thresholds rise. |
| Tele-Dermatology Channel Partnership | Unbundles clinical credibility from institutional pharmacy distribution, capturing margin through direct-to-consumer ingredient literacy platforms. |
| Strain-Specific Mechanistic Claims | Differentiates premium lysate positioning from generic probiotic labeling as K-Beauty microbiome positioning intensifies competitive pressure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MFDS guidance documents, EFSA health claim registers, and REACH restriction schedules, with input from fermentation process engineers, cosmetic formulation specialists, pharmaceutical procurement managers, and toll-manufacturing contract officers. Secondary validation drew from customs trade data, industrial biotechnology patent filings, and EU Cosmetics Regulation ingredient safety dossiers, with bottom-up capacity modeling triangulated against top-down therapy area demand aggregation.
Forecast inputs span product type segmentation across freeze-dried powder, liquid suspension, and encapsulation formats; therapy area splits between digestive health, dermatological care, and immune support; and end-user concentration among cosmetic specialists, pharmacies, and wellness clinics. CAGRs were derived through regression analysis of historical procurement volume against regulatory event timing, with projection sensitivity tested against strain bank access constraints and bioprocess engineering labor availability across the analysis window.
Stress conditions across endotoxin control cost inflation, bioreactor capacity utilization thresholds, and regulatory documentation timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions of continued K-Beauty microbiome positioning momentum and stable REACH enforcement intensity. Material shifts in FDA cosmetic ingredient safety documentation requirements or MFDS real-time data standard adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.