
 Synbiotic Foods Market | 2026-2036
Synbiotic Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Synbiotic Foods Market Outlook
A widening capability gap between fermentation infrastructure investments is rotating competitive advantage toward vertically integrated suppliers. Chr. Hansen Holding A/S leverages its strain library and bioprocessing capacity to dominate industrial ingredient supply. Danone S.A. anchors its position through refrigerated distribution networks that protect live culture viability. Kerry Group plc competes by extending flavor masking technologies that improve palatability in high-potency synbiotic formulations.
Synbiotic foods contain synergistic combinations of live microorganisms and selectively fermented substrates that enhance host microbial colonization, typically requiring minimum viable counts of 10^6 to 10^9 CFU per serving at point of consumption. These formulations serve commercial purposes across gut health modulation, immune marker improvement, and metabolic management applications. Functional beverages carry premium positioning due to cold-chain requirements and shorter shelf lives that limit private label encroachment. Fermented products occupy mature volume positions while health snacks represent the fastest-expanding margin pool as brands integrate synbiotic powders into ambient-stable formats. Probiotic supplements face structural pressure from whole-food positioning trends among nutritional experts.
The European Food Safety Authority demands strain-specific human intervention studies for Article 13 health claims, while the FDA exercises enforcement discretion over probiotic structure-function claims pending formal guidance. Health Canada requires Natural Product Number licensing for synbiotic supplements sold through nutrition shops. Stakeholders must monitor evolving live culture stability standards as regulators tighten quantification methodologies and shelf-life verification protocols.
Market Dynamics
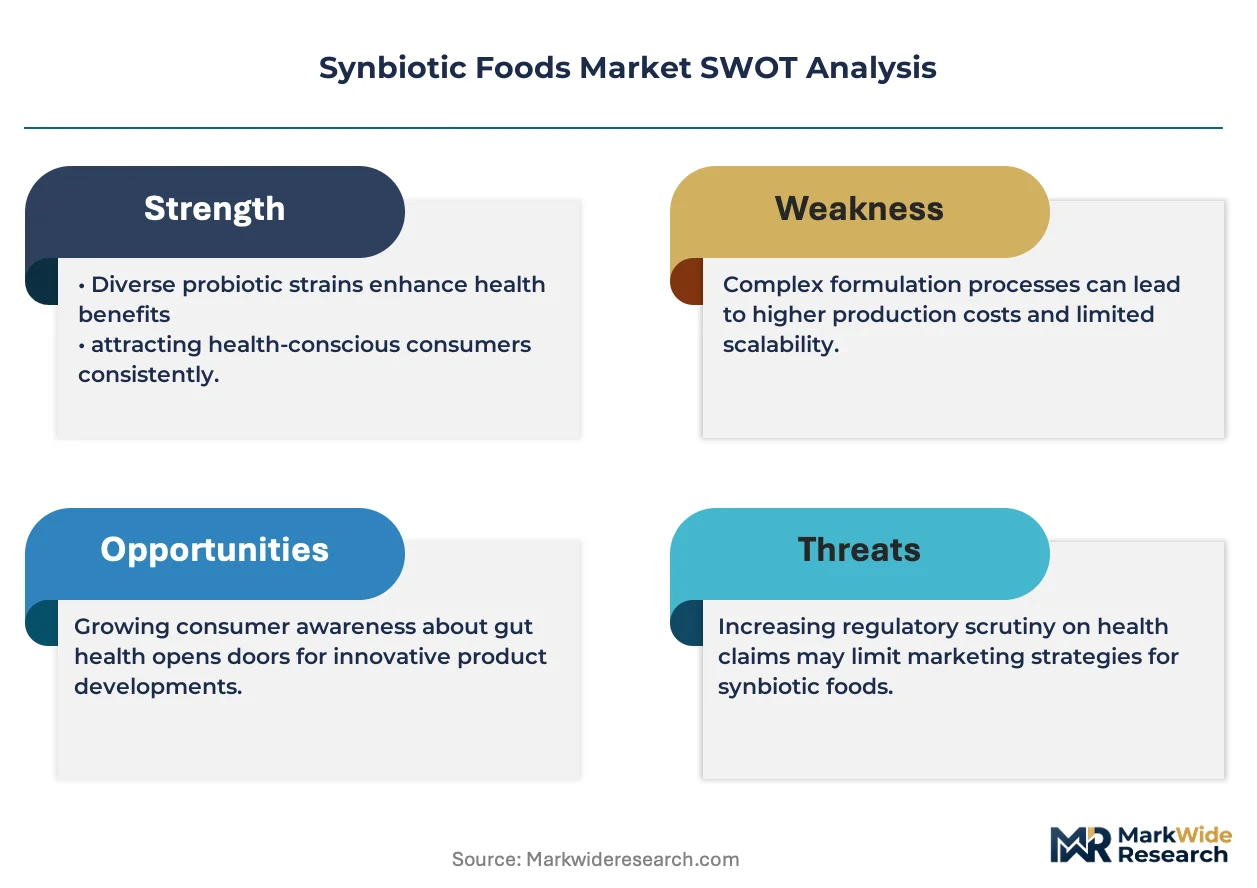
EFSA's tightening substantiation requirements for live culture claims is compressing market access timelines and forcing strain-level investment differentiation among ingredient suppliers.
Growth Catalysts
- Fitness enthusiast demand:Functional beverage adoption accelerates as athletic communities prioritize gut health modulation alongside protein intake.
- German market concentration:Gut health applications draw disproportionate R&D investment as consumer willingness-to-pay for synbiotic yogurt and kefir outpaces neighboring economies.
- Cold-chain infrastructure expansion:Refrigerated logistics networks in France and the Netherlands now protect 10^6 to 10^9 CFU viability across last-mile delivery.
Market Restraints
- Strain stability costs:Maintaining minimum viable counts through shelf-life requires microencapsulation technologies that inflate unit economics.
- EFSA claim substantiation:Article 13 health claim approvals demand strain-specific human intervention studies costing €2-4 million per submission.
- Live culture substitutes:Heat-killed postbiotics and fermented whole foods capture price-sensitive consumers unwilling to manage cold-chain requirements.
Strategic Opportunities
- Health snack white space:Ambient-stable synbiotic powder integration into bars and crisps bypasses refrigerated distribution constraints entirely.
- Metabolic management pivot:Glucose response and weight management positioning opens reimbursement pathways through employer wellness programs.
- Health Canada NPN pathway:Natural Product Number licensing for synbiotic supplements creates regulated channel differentiation against unapproved competitors.
Industry Challenges
- CFU quantification standardization:Regulators in Germany and France are tightening shelf-life verification protocols, forcing reformulation of legacy stability models.
- Fermentation talent scarcity:Industrial-scale bioprocessing expertise for high-potency synbiotic production concentrates among a handful of European technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synbiotic Foods Market |
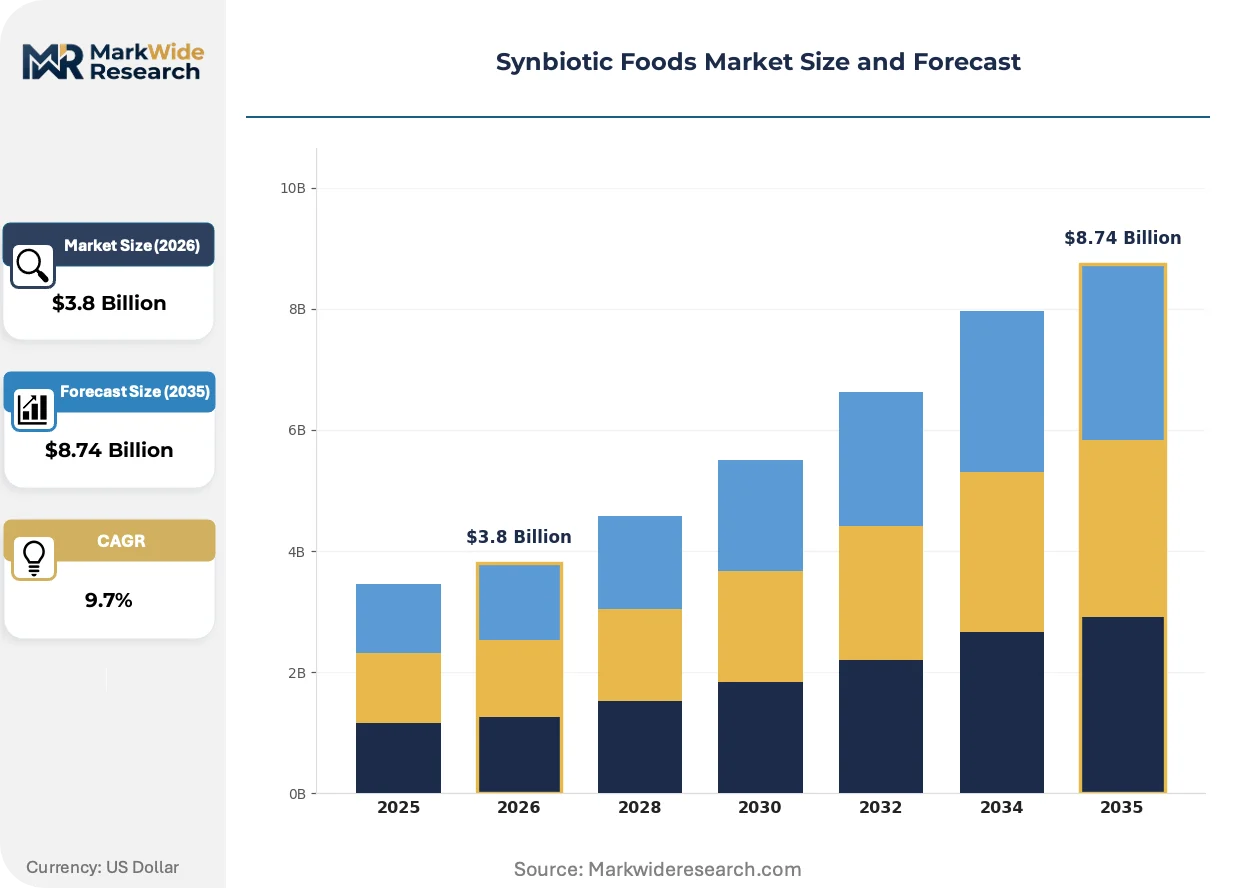
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Products, Probiotic Supplements, Functional Beverages, Health Snacks End User: Health-Conscious Consumers, Nutritional Experts, Wellness Centers, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Nutrition Shops Application: Gut Health, Immune Support, Weight Management, Digestive Aid |
| Companies Covered | Chr. Hansen Holding A/S, Kerry Group plc, Danone S.A., Herbalife Nutrition Ltd., Sabinsa Corporation, Yakult Honsha Co., Ltd., Nestlé S.A., Lallemand Inc., Probiotical S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synbiotic Foods Market Strategic Shifts
Strain-specific formulation science and ambient stability breakthroughs are redrawing competitive boundaries between refrigerated and shelf-stable delivery formats.
Microencapsulation via spray-drying with protein-carbohydrate matrices is supplanting traditional freeze-drying for live culture protection. Sports nutrition brands in Germany and the UK are adopting these cost-reduced powders at triple-digit annual rates. The technology is compressing price premiums between refrigerated beverages and ambient-stable formats.
EFSA's 2023 updated guidance on quantification methodologies for live microorganisms now mandates flow cytometry over plate counting for novel food approvals. This regulatory shift elevates capital requirements for analytical capabilities. Small ingredient suppliers in Italy and Spain are outsourcing testing to certified laboratories rather than building in-house capacity.
Whole-food positioning among nutritional experts is redirecting consumer spending from isolated probiotic supplements toward fermented vegetables and synbiotic-enriched dairy. Functional beverage brands in France respond by emphasizing "food-first" messaging and transparent strain sourcing. This behavioral pivot is most visible in Paris and Lyon metropolitan purchasing data.
Synbiotic Foods Market Segmentation
Channel economics and cold-chain requirements segment the synbiotic foods market into fundamentally different margin structures. Product stability at ambient temperatures versus refrigerated distribution creates divergent competitive moats and customer acquisition costs across formats.
Product Type:
Cold-chain intensity and shelf-life constraints determine which product types flow through refrigerated versus ambient distribution networks.
- Functional Beverages:Live culture drinks requiring 10^6 to 10^9 CFU viability depend on uninterrupted cold-chain logistics from production through last-mile delivery. German fitness enthusiasts drive disproportionate demand for kefir and drinkable yogurt formats that command premium positioning.
- Health Snacks:Ambient-stable bars and crisps integrate microencapsulated synbiotic powders that bypass refrigeration entirely. French and UK sports nutrition brands are adopting these formats at accelerated rates as spray-dried protein-carbohydrate matrices reduce unit costs.
- Fermented Products:Traditional yogurt, kimchi, and sauerkraut occupy mature volume positions with established retail placement.
- Probiotic Supplements:Capsule and tablet formats face structural pressure from whole-food positioning trends among nutritional experts.
Fermented products dominate installed base. Health snacks are where expansion concentrates.
End User:
Professional credentialing and purchasing authority create distinct customer tiers with divergent price elasticity and formulation requirements.
- Nutritional Experts:Registered dietitians and clinical nutritionists specify strain-specific formulations for metabolic management protocols, driving demand for substantiated health claims and transparent sourcing documentation.
- Fitness Enthusiasts:Athletic communities prioritize gut health modulation alongside protein intake, concentrating demand in German and UK sports nutrition channels.
- Health-Conscious Consumers:Self-directed purchasers respond to food-first messaging and ambient convenience.
- Wellness Centers:Spa and retreat operators bulk-purchase synbiotic-enriched foods for curated wellness programming.
Nutritional experts anchor premium pricing. Fitness enthusiasts are climbing the fastest.
Distribution Channel:
Regulatory licensing requirements and live culture handling protocols fragment channel economics across temperature-controlled and ambient pathways.
- Specialty Stores:Dedicated health food retailers with trained staff explain CFU counts and strain specificity to educated consumers, supporting premium positioning in German urban markets.
- Nutrition Shops:Health Canada NPN licensing creates regulated channel differentiation for synbiotic supplements against unapproved competitors in Canadian markets.
- Online Retail:Direct-to-consumer platforms require cold-chain fulfillment partnerships that inflate logistics costs.
- Supermarkets:Mass retail placement demands ambient stability or dedicated refrigerated section allocation.
Specialty stores dominate margin capture. Nutrition shops are gaining share fastest.
Application:
Clinical substantiation depth and reimbursement potential stratify applications by regulatory investment requirements and pricing power.
- Gut Health:Microbial colonization claims require EFSA strain-specific human intervention studies costing €2-4 million per Article 13 submission, concentrating R&D investment in German and French markets.
- Metabolic Management:Glucose response and weight management positioning opens employer wellness program reimbursement pathways in North American corporate settings.
- Immune Support:Structure-function claims face FDA enforcement discretion pending formal guidance.
- Digestive Aid:General wellness positioning competes with fermented whole foods on price.
Gut health dominates substantiation investment. Metabolic management is where reimbursement pathways are opening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers purchase synbiotic kefir and drinkable yogurt at rates that outpace French and UK adoption, while North American buyers gravitate toward employer-sponsored metabolic management programs. This consumption-mix differential creates divergent regulatory investment priorities across markets.
Germany
Fitness enthusiasts in Bavaria and North Rhine-Westphalia drive disproportionate demand for high-CFU functional beverages that command premium positioning. EFSA Article 13 substantiation requirements for gut health claims concentrate strain-specific R&D investment in Munich and Frankfurt biotech clusters. Cologne anchors industrial-scale fermentation capacity as ingredient suppliers expand bioprocessing facilities to serve domestic yogurt and kefir manufacturers.
France
Paris and Lyon metropolitan purchasing data reveal accelerating whole-food positioning trends that redirect spending from supplements toward fermented vegetables. ANSM and DGCCRF enforcement of live culture stability standards tightens shelf-life verification protocols for refrigerated distribution networks. The Auvergne-Rhône-Alpes region hosts spray-drying innovation clusters that reduce microencapsulation costs for ambient-stable synbiotic powders.
United States
Employer wellness programs in California and Massachusetts create reimbursement pathways for metabolic management applications targeting glucose response. FDA enforcement discretion over probiotic structure-function claims pending formal guidance sustains market access uncertainty. Greater Boston anchors clinical research infrastructure that supports structure-function claim substantiation for sports nutrition brands.
United Kingdom
Sports nutrition channels in London and Manchester adopt ambient-stable synbiotic bars at triple-digit annual rates as spray-dried formats compress price premiums. The Food Standards Agency maintains novel food consultation pathways for live culture ingredients that lack EU-equivalent approval history. Cambridge biotech clusters concentrate fermentation talent scarce across broader European technical institutes.
Canada
Health Canada NPN licensing requirements create regulated channel differentiation for synbiotic supplements sold through nutrition shops in Ontario and British Columbia. Natural Product Number pathways demand strain-specific documentation that elevates compliance costs for imported formulations. Toronto anchors distribution infrastructure that manages cold-chain fulfillment partnerships for direct-to-consumer platforms.
Synbiotic Foods Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on formulation science and ambient stability breakthroughs. The upper tier controls strain libraries and captive bioprocessing capacity that secures industrial ingredient supply contracts. Mid-tier specialists differentiate through flavor masking technologies and microencapsulation process improvements. Dominant competitive moves include backward integration into fermentation infrastructure and strategic partnerships with refrigerated logistics providers.
Within the integrated leader tier, Chr. Hansen Holding A/S and Danone S.A. exemplify divergent strategic positions—one anchoring industrial ingredient supply through strain library depth, the other controlling last-mile live culture viability through refrigerated distribution networks. Kerry Group plc occupies a position among formulation specialists that extend palatability technologies into high-potency applications. These three represent archetypes that structure competitive dynamics: upstream bioprocessing captivity, downstream cold-chain control, and mid-stream formulation enablement.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Kerry Group plc |
| Danone S.A. |
| Herbalife Nutrition Ltd. |
| Sabinsa Corporation |
| Yakult Honsha Co., Ltd. |
| Nestlé S.A. |
| Lallemand Inc. |
| Probiotical S.p.A. |
| Others |
Value Chain & Pricing Dynamics
EFSA Article 13 health claim substantiation gates both supplier qualification and price differentiation simultaneously, as ingredient suppliers lacking strain-specific human intervention studies cannot access premium positioning regardless of production scale. Cold-chain infrastructure investments further stratify market access, concentrating margin capture among vertically integrated players with captive bioprocessing capacity.
Pricing Analysis
Long-term offtake contracts dominate industrial ingredient supply between strain library holders and functional beverage manufacturers, while spot purchasing persists for ambient-stable synbiotic powders in health snack applications. Price differentiation rests on certification tier (EFSA novel food approval status) and cold-chain reliability guarantees, with German fitness enthusiasts showing lowest price sensitivity for refrigerated kefir formats. Cost compression in ambient-stable segments is intensifying as spray-dried protein-carbohydrate matrices reduce microencapsulation economics. Health-conscious consumers in France and the UK exhibit highest price sensitivity, gravitating toward fermented whole foods when synbiotic premiums exceed perceived value thresholds.
Supply Chain Analysis
Fermentation talent scarcity in European technical institutes creates a chokepoint that constrains industrial-scale bioprocessing expansion for high-potency synbiotic production. Geographic supply concentration centers on Denmark, France, and Germany for strain development and bioprocessing infrastructure, with raw material dependencies spanning dairy substrates from the Netherlands, specialized carbohydrate matrices from Belgium, and analytical testing capacity outsourced to certified laboratories in Italy and Spain. Single-source vulnerability runs through Copenhagen and Munich biotech clusters where industrial-scale fermentation expertise concentrates. Distribution feeds from captive refrigerated logistics networks in Germany and France into specialty retail and direct-to-consumer cold-chain fulfillment partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as heat-killed postbiotics and fermented whole foods capture price-sensitive consumers unwilling to manage cold-chain requirements, eroding addressable market for live culture products.
For Market Incumbents: Fortify strain library depth through targeted acquisition of specialized fermentation assets in Munich and Frankfurt biotech corridors, while extending captive refrigerated distribution networks to protect last-mile viability advantages against ambient-stable substitutes. EFSA quantification methodology shifts toward flow cytometry elevate compliance costs that favor scaled players with in-house analytical capabilities. For New Entrants and Emerging Players: Anchor in health snack white space where ambient-stable synbiotic powder integration bypasses refrigerated infrastructure requirements entirely, targeting UK and French sports nutrition channels adopting spray-dried formats at accelerated rates. Employer wellness program reimbursement pathways for metabolic management applications in North American corporate settings offer the most penetrable go-to-market angle with lower regulatory barriers than gut health claims. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across analytical testing and microencapsulation equipment as EFSA mandates flow cytometry over plate counting, favoring acquisition targets with certified laboratory partnerships rather than capital-heavy infrastructure buildouts. Long-term viability over the next decade hinges on backward integration into strain development capabilities rather than formulation-only positioning. The signal to watch is Health Canada NPN licensing velocity as a proxy for regulated channel differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | EFSA novel food approvals require proprietary strain documentation that locks out commodity suppliers. |
| Cold-Chain Infrastructure Partnership | Refrigerated logistics networks in Germany protect live culture viability through last-mile delivery. |
| Microencapsulation Process Scale-Up | Spray-dried protein-carbohydrate matrices reduce unit costs for ambient-stable health snack formats. |
| Health Canada NPN Pathway Investment | Natural Product Number licensing creates regulated channel differentiation against unapproved competitors. |
| Metabolic Management Clinical Substantiation | Glucose response positioning opens employer wellness program reimbursement in North American markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and retail audit databases through structured interviews with fermentation scientists, regulatory affairs leads at ingredient suppliers, category buyers at German specialty retailers, and cold-chain logistics operators. Bottom-up demand modeling triangulates against top-down value chain analysis to isolate price elasticity variations across refrigerated versus ambient distribution pathways.
Segmentation dimensions modeled span product type stability requirements, end-user credentialing tiers, distribution channel regulatory intensity, and application-specific substantiation depth across the projection horizon. CAGRs derive from volume trajectory analysis incorporating EFSA approval timelines, Health Canada NPN licensing velocity, and employer wellness program adoption curves for metabolic management positioning.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA enforcement stringency and cold-chain infrastructure expansion; material deviation in regulatory timelines or substitute technology cost curves would warrant model refresh. Practitioners should keep alternative scenarios live as flow cytometry standardization and postbiotic competitive positioning evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Europe Probiotic Supplements Market