
 Asia-Pacific Feed Probiotics Market | 2026-2036
Asia-Pacific Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Probiotics Market Outlook
Australian probiotic fermentation capacity is decoupling from European parent strain dependency as regional toll manufacturers scale GMP-compliant facilities near Melbourne and Sydney. Chr. Hansen Holding A/S leverages its Copenhagen-derived strain libraries to dominate thermotolerant yeast probiotic supply for tropical poultry operations. dsm-firmenich sustains competitive positioning through backward integration into prebiotic substrate production, cutting third-party oligosaccharide exposure. Lallemand Inc. anchors Asia-Pacific presence with dedicated Bacillus subtilis production lines serving Vietnamese shrimp feed mills.
Asia-Pacific feed probiotics comprise live microbial preparations, typically containing 10^6 to 10^9 colony-forming units per gram, administered through compound feed or drinking water to modulate gastrointestinal microbiota and enhance nutrient absorption in food-producing animals. Their primary commercial purpose centers on replacing antibiotic growth promoters banned or restricted across major livestock jurisdictions. Lactic acid bacteria formulations command premium positioning in ruminant applications where rumen pH stabilization justifies higher inclusion rates. Powder and granule forms dominate manufacturing throughput due to superior thermostability during pelting and extrusion processes compared to liquid alternatives. Yeast probiotics, specifically Saccharomyces cerevisiae derivatives, represent the fastest-expanding product category as aquaculture feed producers seek protein-sparing gut health solutions.
China's SAMR enforces GB standards on microbial feed additive registration, requiring strain-level safety documentation that filters out uncertified suppliers. India's BIS and FSSAI jointly oversee feed-grade probiotic quality benchmarks, while Australia's APVMA regulates veterinary biologicals entering the ruminant sector. Japan's MAFF maintains additional import phytosanitary layers that shape cross-border formulation trade. Stakeholders must monitor evolving strain patent expiries and regulatory equivalence agreements that could redraw competitive boundaries across the region.
Market Dynamics
Antibiotic growth promoter bans across Southeast Asian livestock sectors are forcing feed formulators to rebuild gut health protocols around live microbial additives, creating immediate substrate demand for thermotolerant Bacillus and Saccharomyces strains.
Growth Catalysts
- Vietnam's aquaculture expansion:Mekong Delta shrimp and pangasius operations now mandate probiotic inclusion in grower diets to meet export certification requirements for EU and US retail chains.
- China's GB 13078 feed safety standards:SAMR enforcement of strain-level registration documentation filters uncertified suppliers and concentrates volume with compliant domestic and import players.
- Thermostable spore formulations:Bacillus subtilis and coagulans variants surviving pelleting temperatures above 85°C unlock inclusion in tropical poultry and swine extruded feeds previously limited to post-pellet liquid application.
Market Restraints
- Parent strain import dependency:Australian and Southeast Asian toll manufacturers rely on European and North American culture collections for proprietary thermotolerant isolates, exposing supply to phytosanitary delays and strain patent cliffs.
- Prebiotic substrate cost volatility:Mannan-oligosaccharide and fructo-oligosaccharide prices track molasses and chicory root commodity swings, compressing blended probiotic-prebiotic margin structures.
- Regulatory equivalence gaps:Japan's MAFF phytosanitary layers and Australia's APVMA veterinary biologicals classification create non-tariff barriers that fragment formulation trade across otherwise aligned Asia-Pacific markets.
Strategic Opportunities
- Indonesia's broiler corridor consolidation:Java-based integrators scaling to 50 million+ bird annual throughput seek single-source probiotic-prebiotic suppliers capable of just-in-time delivery to 40+ feed mills.
- India's FSSAI-aligned feed safety protocols:BIS quality benchmarks and state-level dairy cooperative procurement mandates create first-mover advantage for strain-registered suppliers in Uttar Pradesh and Gujarat ruminant markets.
- Precision fermentation capacity:Cell-culture-derived postbiotic metabolites and spent yeast fractions are converging with live probiotic formulations to create hybrid gut health products with extended shelf stability.
Industry Challenges
- Strain characterization bottlenecks:Whole-genome sequencing and safety documentation for SAMR and APVMA submissions require 18-24 month timelines, delaying market entry for novel isolates.
- Technical service capacity gaps:Feed mill microbiome diagnostics and inclusion rate optimization demand field veterinarians and nutritionists scarce in Vietnam's Mekong Delta and Indonesia's outer island provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Probiotics Market |
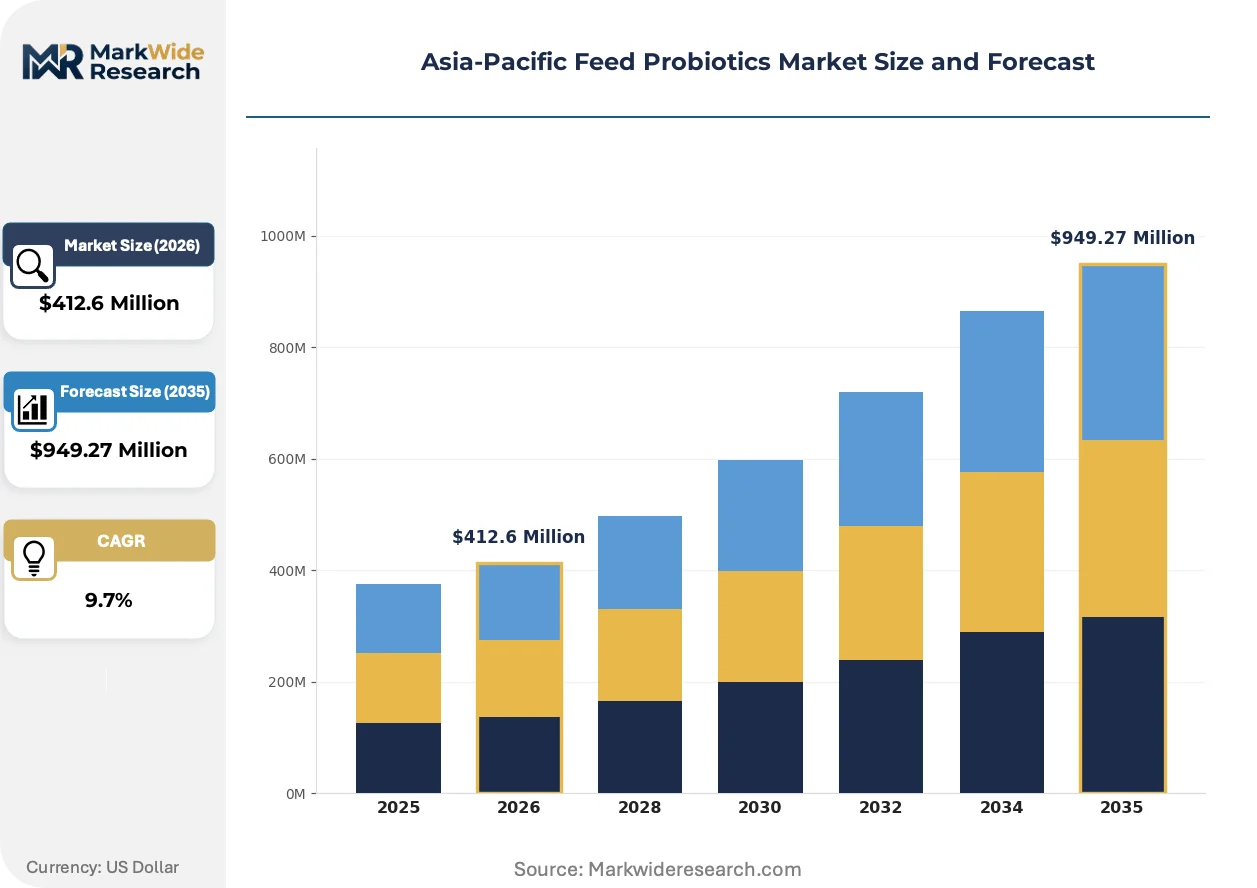
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Probiotics, Lactic Acid Bacteria, Bifidobacterium, Others End User: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granules, Capsules Distribution Channel: Online, Retail, Distributor, Direct Sales |
| Companies Covered | Chr. Hansen Holding A/S, dsm-firmenich, Novonesis, Evonik Industries AG, ADM, International Flavors & Fragrances Inc., Lallemand Inc., Yakult Honsha Co. Ltd, Nestle S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Probiotics Market Strategic Shifts
Livestock gut health management is pivoting from generic probiotic inclusion toward strain-specific microbiome modulation protocols, with aquaculture and ruminant applications driving the most rapid formulation evolution.
Multi-strain consortia engineering is unifying previously separate lactic acid bacteria, Bacillus spores, and yeast derivatives into single-matrix products with synergistic colonization kinetics. Vietnamese shrimp feed mills and Australian dairy nutritionists are adopting these complexes at accelerating rates. This unification is compressing the addressable market for standalone single-strain commoditized offerings while expanding premium positioning for characterized consortium suppliers.
China's SAMR microbial feed additive registration requirements now mandate whole-genome sequencing and toxigenicity screening for every commercialized strain, extending approval timelines but elevating quality floors. Domestic strain libraries in Shanghai and Guangzhou biotech parks are expanding to reduce import dependency. Tropical poultry operations in Thailand and Malaysia are prioritizing SAMR-registered suppliers to ensure uninterrupted cross-border feed trade.
Integrated poultry and aquaculture operations are consolidating procurement around full-service gut health programs combining live probiotics, prebiotic substrates, and postbiotic metabolites with on-site technical support. Vietnam's CP Group and Indonesia's Japfa Comfeed are displacing spot-market ingredient purchasing with annual partnership contracts. This behavioral shift is most visible in Mekong Delta aquaculture clusters and Java's integrated broiler belt.
Asia-Pacific Feed Probiotics Market Segmentation
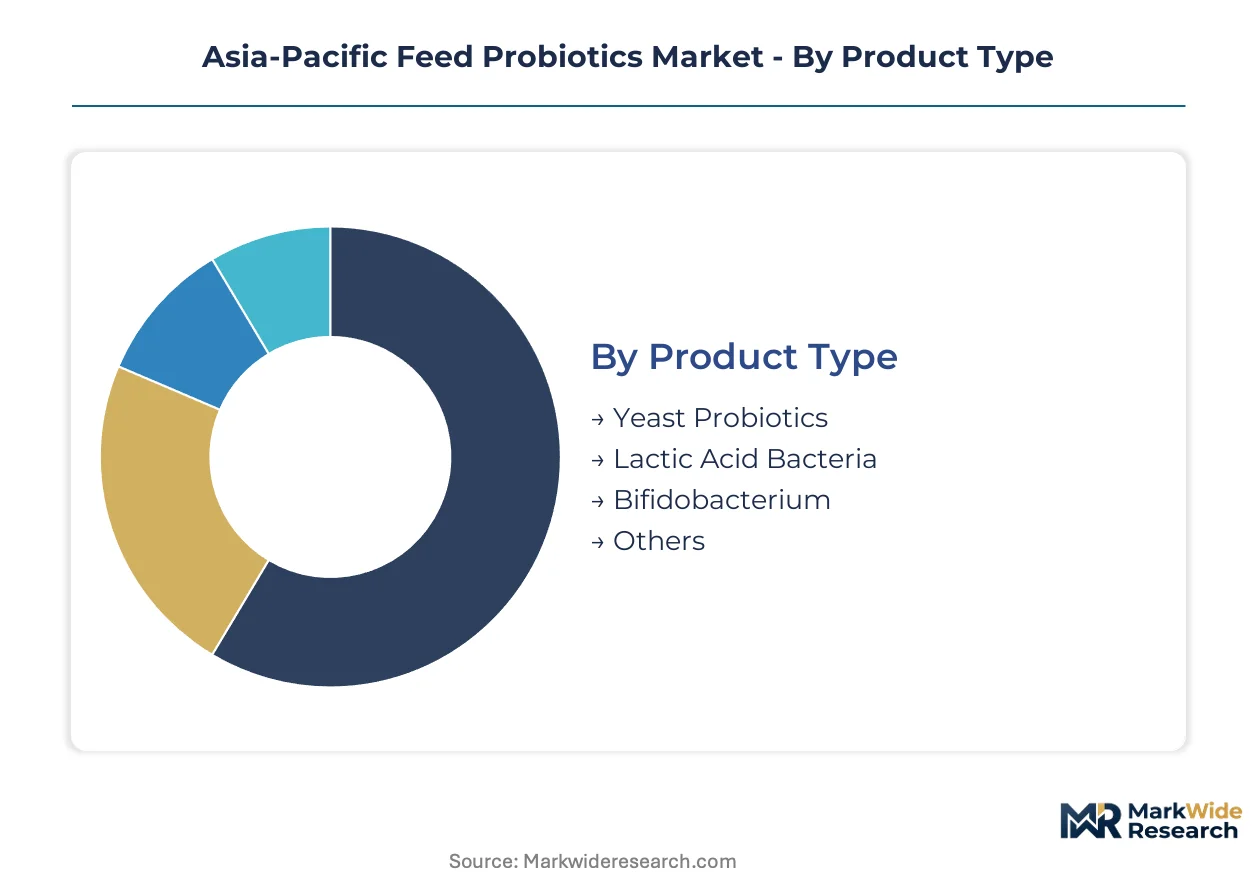
Feed probiotic purchasing decisions across Asia-Pacific hinge on thermal tolerance, target species physiology, and integration depth with compound feed manufacturing. Segmentation reveals how suppliers align formulation portfolios with regulatory strain registrations and pelleting infrastructure constraints.
Product Type:
Upgrade cycles in Asia-Pacific probiotic manufacturing are accelerating as toll producers replace heat-sensitive cultures with thermotolerant alternatives capable of surviving extrusion above 85°C.
- Yeast Probiotics:Saccharomyces cerevisiae derivatives dominate aquaculture applications in Vietnam's Mekong Delta, where protein-sparing gut health solutions command premium positioning in shrimp and pangasius grower diets. Vietnamese feed mills now specify yeast cell wall fractions for export-certified operations supplying EU retail chains.
- Lactic Acid Bacteria:Rumen pH stabilization in Indian dairy cooperatives and Australian pastoral operations justifies higher inclusion rates and premium pricing for Lactobacillus and Enterococcus formulations. These cultures require microencapsulation or post-pellet application, constraining deployment to facilities with liquid dosing lines.
- Bifidobacterium:Swine nursery diets in China's Guangdong and Sichuan provinces incorporate these anaerobes for pathogen competitive exclusion during weaning stress windows.
- Others:Bacillus subtilis and coagulans spore formulations serve tropical poultry integrators in Thailand and Indonesia seeking pelleting-compatible alternatives to heat-labile cultures.
Yeast probiotics sit at the top of the volume ranking, with Bacillus spore formulations climbing the fastest as pelleting infrastructure spreads across Southeast Asia.
End User:
Cost tier differentiation across livestock sectors separates commodity spot purchasing from integrated partnership contracts with embedded technical service.
- Poultry:Broiler integrators in Indonesia's Java corridor and Thailand's central plains mandate thermotolerant spore inclusion at 50 million+ bird annual throughput scales. These operations displace generic probiotic purchasing with annual gut health program contracts combining live cultures, prebiotic substrates, and on-site microbiome diagnostics.
- Aquaculture:Mekong Delta shrimp feed mills specify multi-strain consortia unifying Bacillus, yeast derivatives, and lactic acid bacteria in single-matrix products for export certification compliance. Pangasius operations in An Giang and Dong Thap provinces drive fastest formulation evolution as EU and US retail chain requirements tighten.
- Ruminants:India's Uttar Pradesh and Gujarat dairy cooperatives procure strain-registered lactic acid bacteria under FSSAI-aligned procurement mandates, while Australian pastoral operations prioritize APVMA-registered veterinary biologicals.
- Swine:China's Sichuan and Henan provinces concentrate demand for weaning-phase probiotics as GB standards on antibiotic-free production tighten substrate quality requirements.
Poultry commands the largest procurement volumes, though aquaculture applications are expanding most quickly as Vietnamese and Indonesian export certification requirements proliferate.
Form:
Manufacturing throughput concentrates in solid formats where thermostability during pelleting and extrusion unlocks inclusion in tropical feed production.
- Powder:Dominates manufacturing throughput across Asia-Pacific compound feed mills due to superior flowability in premix blending and compatibility with existing handling infrastructure. Powdered Bacillus spores serve Indonesian and Vietnamese poultry operations lacking liquid dosing equipment.
- Granules:Encapsulated formats with enhanced moisture resistance target aquaculture feed producers in Vietnam's Mekong Delta facing tropical storage humidity challenges.
- Liquid:Post-pellet application lines in Australian dairy nutrition and premium Thai poultry operations preserve viability of heat-sensitive lactic acid bacteria cultures.
- Capsules:Veterinary therapeutic applications in Japanese livestock operations and specialized Australian ruminant formulations where precise dosing control outweighs cost premiums.
Powder formats lead volume throughput, with granule formulations gaining share fastest as humidity-resistant packaging spreads through Southeast Asian aquaculture clusters.
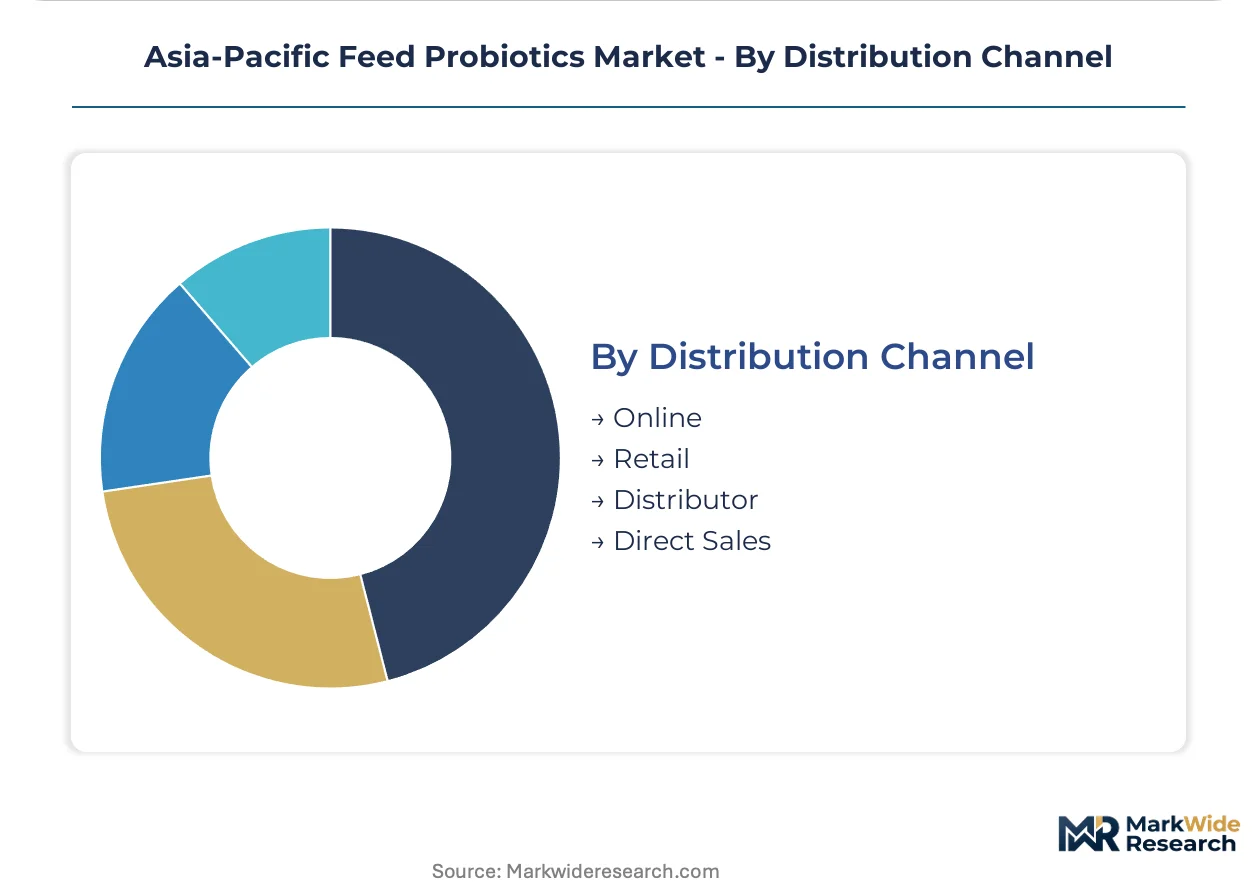
Distribution Channel:
Customer type fragmentation separates spot-market ingredient traders from integrated procurement platforms consolidating annual partnership contracts.
- Direct Sales:CP Group in Vietnam and Japfa Comfeed in Indonesia negotiate annual gut health program contracts displacing spot-market purchasing. These partnerships bundle live probiotics, prebiotic substrates, postbiotic metabolites, and embedded technical service across 40+ feed mill networks.
- Distributor:Regional feed additive distributors serve mid-tier poultry and swine operations in India's Maharashtra and Karnataka, bridging strain-registered suppliers with state-level dairy cooperatives lacking direct procurement scale.
- Online:Emerging procurement channel for smaller aquaculture operations in Vietnam's outer Mekong Delta provinces and Indonesian layer farms seeking transparent strain documentation and SAMR registration verification.
- Retail:Limited to backyard poultry and smallholder livestock operations in Philippines and rural Indonesia where feed mill integration remains incomplete.
Direct sales channels capture the highest value contracts, with distributor networks expanding most rapidly as mid-tier integrators in India and Southeast Asia consolidate procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate fermentation capacity toward jurisdictions with streamlined strain registration pathways and lower compliance burdens. China's SAMR documentation requirements and Australia's APVMA veterinary biologicals classification create divergent cost-of-compliance tiers that influence where regional supply concentrates.
China
Guangdong and Sichuan provinces drive thermotolerant Bacillus demand as GB 13078 feed safety standards tighten antibiotic-free livestock protocols. SAMR's whole-genome sequencing mandates for microbial feed additives filter uncertified suppliers and concentrate volume with compliant domestic players. Shanghai biotech parks are expanding strain libraries to reduce European parent culture dependency.
Vietnam
Mekong Delta shrimp and pangasius operations mandate probiotic inclusion in grower diets to meet EU and US retail chain export certifications. An Giang and Dong Thap provinces anchor formulation demand as multi-strain consortia replace single-culture additives. CP Group consolidates procurement across 40+ feed mills through annual gut health program contracts.
Indonesia
Java's integrated broiler corridor scaling to 50 million+ bird annual throughput seeks just-in-time probiotic-prebiotic delivery. Japfa Comfeed displaces spot-market purchasing with partnership contracts bundling live cultures and technical service. Toll manufacturers face strain characterization bottlenecks as BPI certification requirements extend approval timelines.
India
Uttar Pradesh and Gujarat dairy cooperatives procure strain-registered lactic acid bacteria under FSSAI-aligned state procurement mandates. BIS quality benchmarks create first-mover advantage for suppliers with documented safety dossiers. Maharashtra and Karnataka mid-tier poultry operations rely on distributor networks bridging registered suppliers with fragmented feed mill infrastructure.
Australia
Victoria and New South Wales GMP-compliant toll manufacturing facilities near Melbourne and Sydney decouple from European parent strain dependency. APVMA veterinary biologicals classification shapes ruminant sector procurement as pastoral operations prioritize registered veterinary biologics. Queensland aquaculture clusters adopt humidity-resistant granule formats for tropical storage conditions.
Asia-Pacific Feed Probiotics Market Competitive Environment
European producers anchor one tier; Asia-Pacific toll manufacturers and domestic specialists hold differentiated positions across thermotolerance and regulatory compliance vectors. Market structure concentrates around strain-registered suppliers capable of navigating SAMR, APVMA, and FSSAI documentation requirements simultaneously. Three archetypes dominate: Copenhagen-derived culture collection licensors, backward-integrated prebiotic substrate producers, and GMP-compliant regional toll fermenters. Competitive moves center on captive strain library expansion and precision fermentation capacity addition.
Within the culture collection tier, Chr. Hansen Holding A/S and Lallemand Inc. occupy positions defined by thermotolerant yeast and Bacillus spore expertise respectively. Among diversified nutrition ingredient conglomerates, dsm-firmenich exemplifies backward integration into prebiotic substrate production. These three anchors represent distinct strategic postures: proprietary strain licensing, integrated substrate-probiotic bundling, and dedicated production line regionalization.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| dsm-firmenich |
| Novonesis |
| Evonik Industries AG |
| ADM |
| International Flavors & Fragrances Inc. |
| Lallemand Inc. |
| Yakult Honsha Co. Ltd |
| Nestle S.A. |
| Others |
Value Chain & Pricing Dynamics
Fermentation microbiologist concentration in Shanghai and Guangzhou biotech parks compresses labor-cost differentials between premium strain-registered suppliers and economy-tier toll manufacturers, widening pricing spreads as SAMR documentation requirements filter uncertified competitors from compliant volume.
Pricing Analysis
Distributor margin layers in Vietnam's Mekong Delta and Indonesia's Java corridor absorb 15-25 point spreads between ex-works fermentation yields and delivered feed mill pricing. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-registered multi-strain consortia from generic Bacillus spores and uncharacterized culture blends. Cost compression in economy-tier spot purchasing intensifies as molasses and chicory root commodity swings transmit into prebiotic substrate costs. Mid-tier poultry integrators in India's Maharashtra and Karnataka exhibit highest price sensitivity, while Australian pastoral operations purchasing APVMA-registered veterinary biologicals show lowest elasticity.
Supply Chain Analysis
Returns of expired or temperature-compromised probiotic inventories flow back to regional toll manufacturers near Melbourne and Sydney for strain recovery and substrate reprocessing. Supply concentrates in China, Vietnam, and Australia as GB standards, EU export certifications, and APVMA registrations respectively shape production footprints. Raw material dependencies on European parent strain libraries, molasses-derived mannan-oligosaccharides, and chicory root fructo-oligosaccharides create input vulnerability. Single-source parent culture dependency from Copenhagen-derived collections exposes supply to phytosanitary delays. Distribution runs through direct sales channels for integrated poultry and aquaculture operations, with regional feed additive distributors serving fragmented mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific feed probiotics function as a stable compounder where antibiotic growth promoter bans across Southeast Asian livestock sectors generate steady substrate demand replacement cycles.
For Market Incumbents: Hedge European parent strain dependency by expanding captive culture collections in Shanghai and Guangzhou biotech parks before patent cliffs expose supply vulnerability. Anchor backward integration into prebiotic substrate production to buffer molasses and chicory root commodity volatility compressing blended margin structures. Defend positioning through SAMR, APVMA, and FSSAI simultaneous registration maintenance that filters uncertified competitors. For New Entrants and Emerging Players: Regional toll manufacturers with GMP-compliant fermentation capacity represent the most accessible channel partnership archetype for market penetration. White-space concentrates in Vietnam's outer Mekong Delta provinces and Indonesia's outer island feed mill networks where technical service capacity gaps delay microbiome diagnostics deployment. Target precision fermentation-derived postbiotic metabolites as the most penetrable product category converging with live probiotic formulations. Pursue annual gut health program contracts displacing spot-market purchasing as the dominant go-to-market angle. For Investors and Strategic Acquirers: Nutrition ingredient conglomerates seeking gut health portfolio expansion are the most active acquirer in this space, with dsm-firmenich's backward integration model representing the benchmark transaction archetype. Long-term viability centers on strain library depth and regulatory registration moats across SAMR, APVMA, and FSSAI jurisdictions. Monitor BPI certification timeline extensions in Indonesia and MAFF phytosanitary layer modifications in Japan as early signals of compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Strain Library Expansion | Reduces European parent culture dependency as Shanghai biotech parks scale domestic collections. |
| Precision Fermentation Capacity Addition | Enables postbiotic metabolite production converging with live probiotic formulations for extended shelf stability. |
| Multi-Strain Consortium Engineering | Unifies Bacillus, yeast, and lactic acid bacteria into single-matrix products compressing commoditized single-strain markets. |
| Annual Partnership Contract Conversion | Displaces spot-market purchasing for CP Group and Japfa Comfeed integrated operations across 40+ feed mills. |
| Regulatory Registration Synchronization | Secures SAMR, APVMA, and FSSAI compliance simultaneously to filter uncertified regional competitors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation facility managers, feed mill procurement leads, regulatory affairs specialists at strain-registered suppliers, and veterinary nutritionists at integrated poultry operations with secondary validation from SAMR microbial feed additive registrations, APVMA veterinary biologicals databases, FSSAI quality benchmark notifications, and customs trade data on probiotic import flows. Bottom-up volume triangulation across Vietnamese shrimp feed mills, Indonesian broiler integrators, and Indian dairy cooperatives converged with top-down market sizing from regional compound feed production statistics.
The forecast window anchored to historical reference periods spanning pre-antibiotic-ban baseline through current GB 13078 enforcement and EU export certification proliferation. Segmentation dimensions modeled include product type thermotolerance tiers, target species physiology, form factor compatibility with pelleting infrastructure, and integration depth with compound feed manufacturing. CAGRs derived from elasticity-adjusted volume projections across the analysis window, incorporating strain registration approval timelines and toll manufacturing capacity expansion schedules as industry-specific forecast inputs.
Revisions become necessary when SAMR accelerates whole-genome sequencing requirements, APVMA reclassifies probiotic veterinary biologicals, or parent strain patent expiries redraw competitive boundaries faster than anticipated. Practitioners should monitor BPI certification timelines in Indonesia, MAFF phytosanitary modifications in Japan, and European culture collection licensing terminations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
South America Digestive Health Supplements Market