
 Probiotics Gummies Market | 2026-2036
Probiotics Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotics Gummies Market Insights
Asset-light contract manufacturing and white-label financing is reconfiguring competitive entry barriers in probiotics gummies, allowing challenger brands to scale without capital-intensive fermentation facilities. Olly leverages direct-to-consumer channel control to sustain premium positioning against mass-market incumbents. Church & Dwight Co., Inc. (Vitafusion) anchors retail shelf presence through pharmacy and supermarket dominance, while Garden of Life differentiates via organic certification and clean-label ingredient sourcing.
Probiotics gummies are chewable confectionery vehicles delivering viable colony-forming units of beneficial bacteria, typically formulated with pectin or gelatin matrices that protect strains from gastric acid degradation until intestinal release. Fruit flavor formulations currently lead volume share, though organic ingredient source segments command disproportionate margin pools due to certified supply chain premiums. Children-targeted products represent the fastest-growing audience segment, while online retail channels are displacing traditional health food stores as the primary discovery and purchase pathway for repeat buyers.
FDA dietary supplement regulations under DSHEA, USDA organic certification standards, and Non-GMO Project verification requirements collectively shape formulation costs and label claim permissibility across the United States market. The Federal Trade Commission monitors advertising substantiation for live culture count claims, creating compliance friction for brands without clinical trial backing. Stakeholders must monitor evolving state-level sugar content restrictions and probiotic strain-specific health claim adjudications as the primary determinants of permissible market positioning.
Market Dynamics
Pediatric wellness applications are pulling capital toward strain-specific formulation R&D, while contract manufacturing networks compress fixed-cost barriers for new entrants seeking shelf placement.
Growth Catalysts
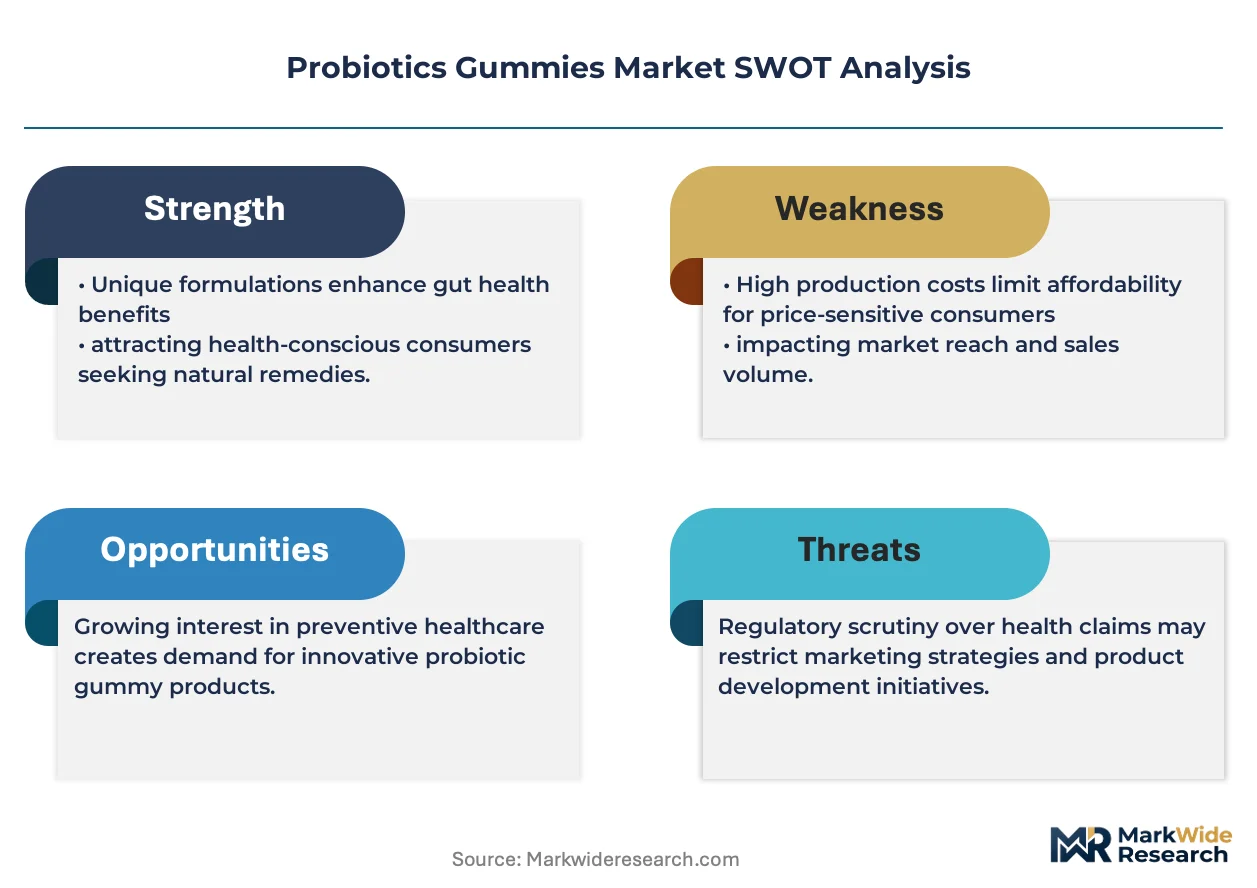
- DSHEA framework evolution:FDA's tightening substantiation requirements for live culture count claims are filtering out undercapitalized competitors, concentrating shelf space among clinical trial-backed portfolios.
- Pectin matrix innovation:Plant-derived gelling agents are displacing gelatin in premium positioning, unlocking vegan-certified distribution through natural channel gatekeepers.
- Pediatric segment concentration:Health-conscious parents in United States metropolitan clusters are driving repeat purchase velocity through subscription direct-to-consumer models.
Market Restraints
- Strain stability costs:Refrigerated supply chain requirements for high-CFU formulations inflate last-mile logistics expenditure versus ambient-stable alternatives.
- Fermentation capacity concentration:Viable culture supply concentrates among North American and European contract manufacturers, creating input bottlenecks during demand surges.
- FTC enforcement friction:Advertising substantiation investigations into unqualified microbiome health claims impose legal contingency reserves on emerging brands.
Strategic Opportunities
- Senior digestive health:Underpenetrated geriatric positioning beyond pediatric SKUs opens pharmacy channel expansion with clinician endorsement pathways.
- USDA organic certification:Certified supply chain premiums command margin expansion in natural retail formats versus conventional ingredient sourcing.
- Strain-library licensing:Biotechnology firms with proprietary human-origin isolates are monetizing exclusive formulation partnerships with finished goods marketers.
Industry Challenges
- CFU count verification:Third-party laboratory testing protocols for end-of-shelf-life viability claims extend product development timelines by 4-6 months.
- Flavor-mask formulation:Active culture bitterness suppression without sugar alcohol load requires iterative sensory testing that compresses gross margins on iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotics Gummies Market |
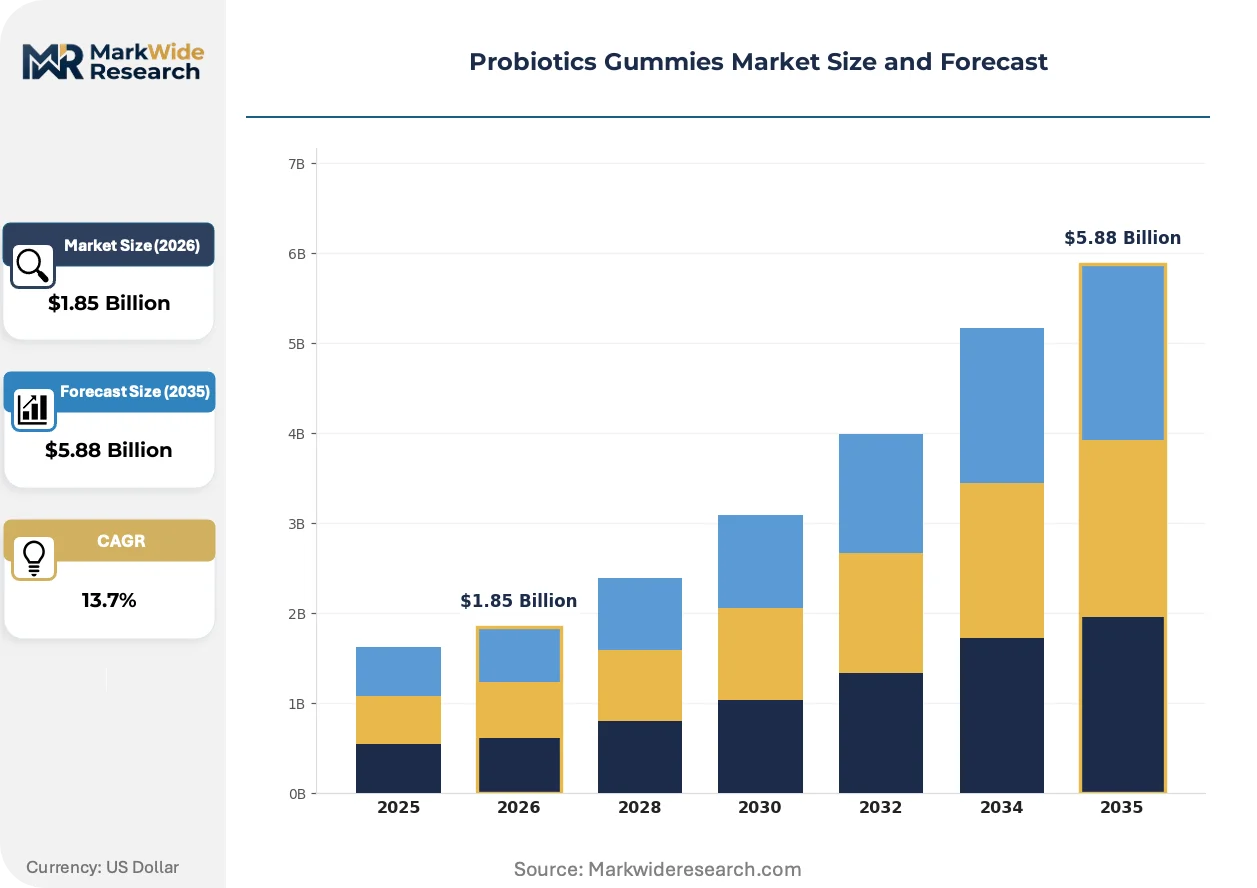
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavor, Herbal Blend, Chocolate, Mixed Berry Target Audience: Children, Adults, Seniors, Pregnant Women Distribution Channel: Online Retail, Health Food Stores, Supermarkets, Pharmacies Ingredient Source: Natural, Organic, Synthetic, Non-GMO |
| Companies Covered | Olly, SmartyPants Vitamins, Culturelle, Garden of Life, Nature's Bounty, Church & Dwight Co., Inc. (Vitafusion), Pharmavite LLC (Nature Made), NOW Foods, Digestive Advantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotics Gummies Market Trends and Innovations
Formulation science and channel architecture are converging to redefine how viable cultures reach target demographics, with matrix technology and regulatory precision separating sustainable positioning from commodity competition.
Microencapsulation technology is migrating from pharmaceutical applications into confectionery-grade probiotic protection, enabling gastric acid survival without enteric coating. Pediatric and senior-focused marketers are adopting these spray-dried lipid or polysaccharide shells at accelerated cadence. The shift is compressing differentiation timelines for brands reliant on basic pectin or gelatin matrices without secondary protection mechanisms.
Non-GMO Project verification requirements are expanding from voluntary premium signaling toward retail gatekeeping in United States natural channel distribution. Mass-market retailers are conditioning shelf access on third-party certification completion. Organic and natural-positioned SKUs face compressed margin structures from dual certification costs, while conventional formulations lose access to high-velocity placement.
Subscription-based replenishment models are capturing repeat purchase economics previously retained by brick-and-mortar pharmacy loyalty programs. Direct-to-consumer platforms with strain-specific educational content are displacing health food store discovery for informed buyers. United States urban and suburban households with children under twelve demonstrate highest subscription attachment rates, driven by convenience positioning and pediatric formulation specialization.
Probiotics Gummies Market Segmentation
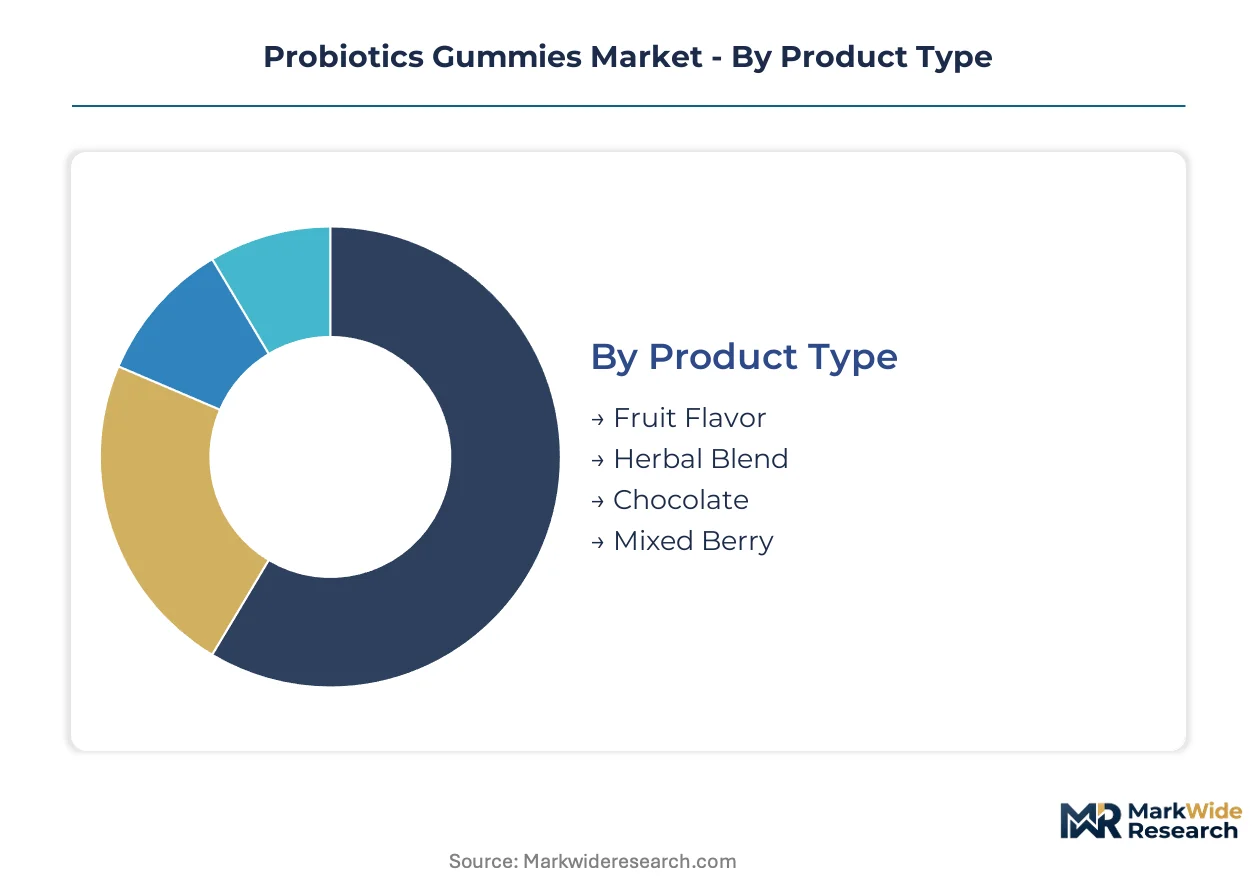
Probiotics gummies manufacturers navigate distinct formulation, certification, and channel requirements across each segment dimension. Product type and ingredient source decisions determine margin architecture, while target audience selection shapes clinical substantiation investments and regulatory pathway complexity.
Product Type:
After-sales engagement intensity varies sharply by flavor profile, with pediatric-focused fruit variants requiring subscription retention support and adult herbal blends demanding strain-specific educational content.
- Fruit Flavor:Pectin-based matrices deliver strawberry, orange, and tropical profiles with high palatability acceptance among children. Demand clusters in United States metropolitan households with children under twelve, driven by parental preference for recognizable, clean-label flavor systems that mask active culture bitterness without artificial sweeteners.
- Herbal Blend:Ginger, turmeric, and botanical infusions target adult digestive wellness positioning with functional ingredient stacking. United States natural channel distribution concentrates here, as retailers condition shelf access on dual certification completion for botanical-probiotic combination products.
- Chocolate:Cocoa butter lipid matrices provide secondary gastric protection for acid-sensitive strains while delivering indulgence-positioned adult SKUs.
- Mixed Berry:Anthocyanin-rich formulations leverage antioxidant co-positioning in premium-tier pharmacy and online channels.
By volume, Fruit Flavor leads. By growth pace, Herbal Blend is ahead.
Target Audience:
Cost tier stratification separates pediatric mass-market penetration from senior-focused pharmacy premium positioning, with formulation R&D intensity scaling directly by age demographic.
- Children:Low-sugar pectin matrices with 1-5 billion CFU counts dominate, requiring extensive sensory testing for bitterness masking. Subscription direct-to-consumer models capture highest repeat purchase velocity in United States suburban households.
- Adults:Strain-specific portfolios target digestive, immune, and mood positioning with higher CFU thresholds and multi-strain complexity.
- Seniors:Clinician endorsement pathways and pharmacy channel concentration define this underpenetrated segment, with acid-resistant formulations commanding premium shelf placement.
- Pregnant Women:Lactobacillus rhamnosus GG and other obstetrician-recommended strains require pregnancy-specific safety substantiation and prenatal channel distribution.
Children segment holds volume leadership. Seniors segment climbs the fastest on expansion trajectory.
Distribution Channel:
Volume concentration tilts toward mass retail, while margin capture concentrates in channels with educational content integration and subscription mechanics.
- Online Retail:Direct-to-consumer platforms with strain-specific educational content displace health food store discovery for informed buyers. United States urban households demonstrate highest subscription attachment rates.
- Health Food Stores:Natural channel gatekeepers condition shelf access on Non-GMO Project and organic certification completion, compressing margin structures for dual-certified SKUs.
- Supermarkets:Mass-market velocity depends on trade promotion intensity and retail shelf presence through pharmacy and supermarket dominance.
- Pharmacies:Clinician endorsement pathways and refrigerated supply chain requirements for high-CFU formulations inflate last-mile logistics expenditure.
Supermarkets lead by volume throughput. Online Retail gains share fastest on channel shift momentum.
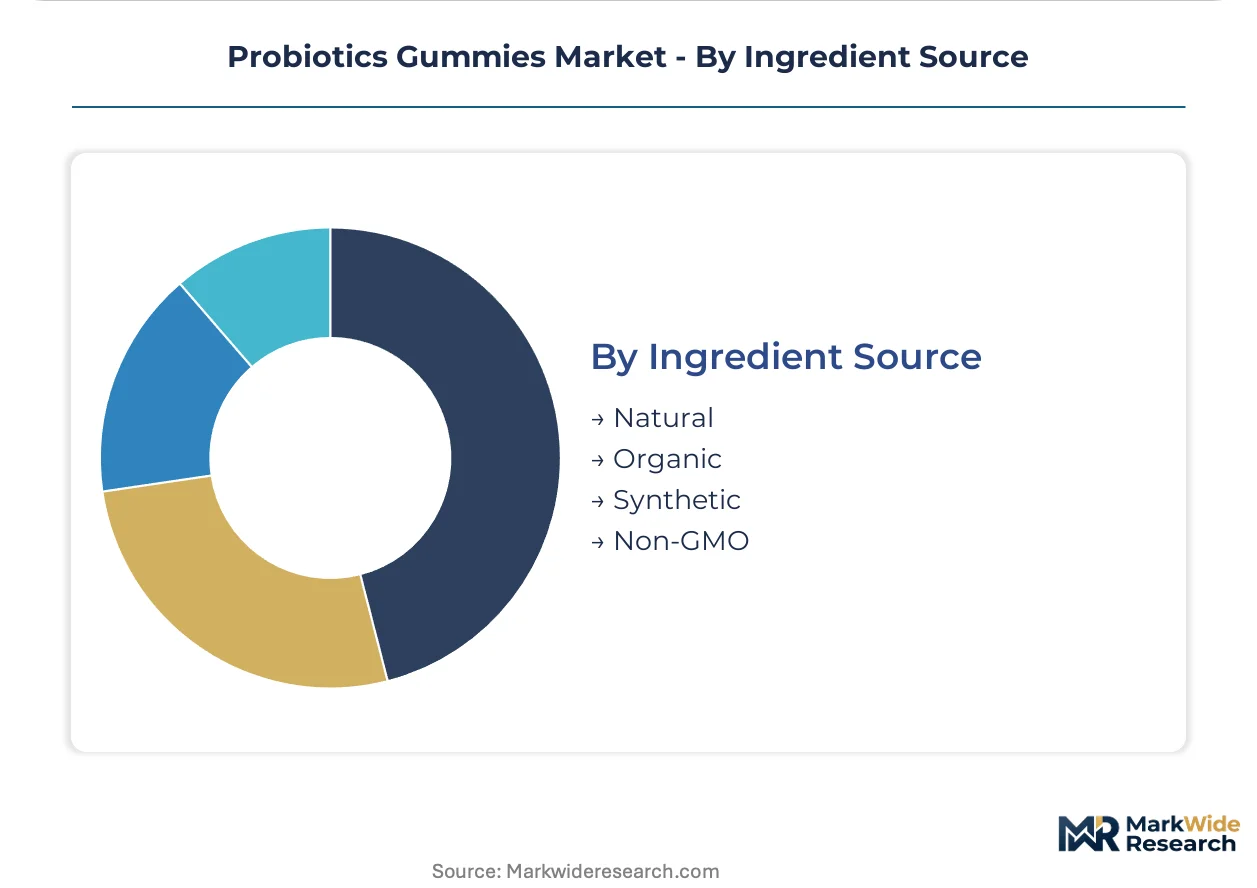
Ingredient Source:
Supply concentration among North American and European contract manufacturers creates input bottlenecks for certified organic and non-GMO sourcing during demand surges.
- Natural:Conventional plant-derived ingredients without synthetic additives meet baseline clean-label expectations in mass-market distribution.
- Organic:USDA certification commands margin expansion in natural retail formats versus conventional ingredient sourcing, with certified supply chain premiums reflecting dual certification costs.
- Synthetic:Artificial flavors and colors retain limited positioning in value-tier segments facing compressed access to high-velocity placement.
- Non-GMO:Project verification requirements expand from voluntary premium signaling toward retail gatekeeping in United States natural channel distribution.
Natural segment dominates volume. Organic segment shows steepest expansion trajectory on certification-driven premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious parents in metropolitan clusters drive demand concentration, with subscription direct-to-consumer models capturing repeat purchase velocity among suburban households with children under twelve.
United States
Metropolitan households with children under twelve dominate volume consumption through subscription replenishment models. FDA dietary supplement regulations under DSHEA tighten substantiation requirements for live culture count claims, filtering undercapitalized competitors from shelf placement. California and New York clusters concentrate functional confectionery innovation, with direct-to-consumer platforms displacing health food store discovery for informed buyers.
Germany
Natural channel gatekeepers in urban centers condition shelf access on organic certification completion, compressing margin structures for dual-certified SKUs. EFSA strain-specific health claim adjudications shape permissible positioning for microbiome-related advertising. Bavaria anchors contract manufacturing networks for pectin-based vegan formulations serving pan-European distribution.
United Kingdom
Pharmacy channel concentration defines senior-focused positioning, with clinician endorsement pathways opening underpenetrated geriatric segments. Medicines and Healthcare products Regulatory Agency oversight applies to products making disease-related claims, creating compliance friction for brands without clinical trial backing. London and Southeast England clusters lead online retail subscription attachment among health-conscious professionals.
Canada
Health food store distribution concentrates in Toronto and Vancouver metropolitan areas, with Non-GMO Project verification expanding from voluntary premium signaling toward retail gatekeeping. Health Canada Natural and Non-prescription Health Products Directorate regulates site license requirements for domestic manufacturing. Prairie provinces supply organic ingredient sourcing for certified supply chain premiums.
Australia
Therapeutic Goods Administration listing requirements for products making specific health claims extend product development timelines for strain-specific formulations. Sydney and Melbourne clusters concentrate pediatric wellness applications through pharmacy and supermarket channels. Queensland supplies tropical fruit flavor ingredient sourcing for pectin-based matrices targeting Asia-Pacific export markets.
Probiotics Gummies Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered positioning vectors, with retail shelf dominance separating mass-market incumbents from premium direct-to-consumer challengers. The vendor base fragments across contract manufacturing networks, asset-light white-label entrants, and integrated fermentation-to-finished-goods operators. Three archetypes define competitive positioning: pharmacy-retail anchors with trade promotion scale, organic-certified specialists with natural channel gatekeeper relationships, and digital-native brands with subscription retention mechanics. M&A activity concentrates on strain-library licensing deals and contract manufacturing capacity acquisition.
Within the direct-to-consumer archetype, Olly occupies a position exemplifying channel control through educational content integration and subscription mechanics. Among pharmacy-retail anchors, Church & Dwight Co., Inc. (Vitafusion) represents mass-market shelf presence through supermarket and pharmacy dominance. Garden of Life sits within the organic-certified specialist tier, anchoring natural channel positioning through USDA certification and clean-label ingredient sourcing.
| Leading Market Players |
|---|
| Olly |
| SmartyPants Vitamins |
| Culturelle |
| Garden of Life |
| Nature's Bounty |
| Church & Dwight Co., Inc. (Vitafusion) |
| Pharmavite LLC (Nature Made) |
| NOW Foods |
| Digestive Advantage |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on North American contract fermentation capacity determines both tiered pricing spreads across organic certification levels and supply chain shape through refrigerated last-mile requirements. Buyers face compressed margin structures when dual certification demands intersect with strain stability costs, forcing trade-offs between ambient-stable formulations and premium refrigerated positioning.
Pricing Analysis
Cost-plus contracts with gelatin and pectin indexation dominate procurement between finished goods marketers and contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified SKUs from natural-positioned and synthetic formulations. Cost compression in mass-market tiers is intensifying because supermarket trade promotion demands absorb margin, while pharmacy and direct-to-consumer channels show lowest price sensitivity due to subscription retention mechanics and clinician endorsement premiums.
Supply Chain Analysis
Upstream feedstock of viable bacterial cultures draws from North American and European fermentation facilities, with pectin and gelatin matrices sourcing from Brazil and Southeast Asia. Strain stability requirements hinge on refrigerated logistics networks, creating single-source vulnerability when demand surges exceed contract manufacturing capacity. Distribution runs through direct-to-consumer platforms for premium tiers, while mass-market volume flows through supermarket and pharmacy wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology migration from pharmaceutical applications signals high-growth disruption, with DSHEA substantiation tightening filtering undercapitalized competitors from shelf placement.
For Market Incumbents: Build clinical trial-backed moats around strain-specific health claims before FTC enforcement friction escalates. Secure exclusive formulation partnerships with biotechnology firms holding proprietary human-origin isolates. Expand refrigerated distribution capacity in United States metropolitan clusters to defend against ambient-stable challengers. For New Entrants and Emerging Players: Pursue senior digestive health positioning in pharmacy channels, the most penetrable segment beyond saturated pediatric SKUs. Target USDA organic certification as the fastest route to natural channel gatekeeper access. Launch with subscription direct-to-consumer mechanics to capture repeat purchase economics without retail slotting fee burdens. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors strain-library licensing deals and contract manufacturing capacity acquisition. Long-term viability rests on clinical substantiation depth rather than flavor innovation. Watch FTC advertising substantiation investigations as the inflection indicator for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Library Licensing Agreement | Biotechnology firms monetize proprietary human-origin isolates through exclusive partnerships with finished goods marketers. |
| USDA Organic Certification Investment | Dual certification completion unlocks natural channel gatekeeper relationships and margin expansion in premium retail formats. |
| Microencapsulation Technology Adoption | Spray-dried lipid shells enable gastric acid survival without enteric coating, compressing differentiation timelines for basic matrix competitors. |
| Direct-to-Consumer Platform Launch | Subscription mechanics with strain-specific educational content displace health food store discovery for informed repeat buyers. |
| Refrigerated Distribution Network Expansion | Last-mile cold chain capacity secures high-CFU formulation placement in pharmacy channels with clinician endorsement pathways. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at finished goods marketers, category buyers at natural channel retailers, contract manufacturing operations directors, and regulatory affairs specialists, then refined through secondary validation against FDA dietary supplement filings, USDA organic certification databases, FTC advertising substantiation records, and Nielsen retail audit data. Bottom-up strain-specific demand modeling and top-down functional confectionery market sizing were triangulated to converge on volume and value estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, ingredient source certification tier, target audience age demographic, and distribution channel format. CAGRs were derived from iterative convergence between historical trajectory analysis and forward-looking input cost elasticity assumptions, incorporating pediatric subscription attachment rates and pharmacy channel expansion velocity as industry-specific forecast inputs.
Sensitivities concentrate around DSHEA framework evolution, FTC enforcement intensity, and strain stability cost inflation. Forecasts reflect assumptions on certification adoption curves and channel shift momentum without guarantee of realization. Cross-checking against Nielsen retail velocity data and FDA warning letter trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
South America Digestive Health Supplements Market