
 Dibutyl Maleate (DBM) Market | 2026-2036
Dibutyl Maleate (DBM) Market Size, Share, and Industry Trends Forecast 2026-2036
Dibutyl Maleate (DBM) Market Outlook
Product bundling around plasticizer-coating combinations is consolidating procurement decisions for compounders seeking formulation efficiency. Celanese Corporation leverages its integrated acetyls chain to anchor supply security for downstream DBM derivatives. Polynt SpA specializes in maleic anhydride-based chemistry, sustaining cost advantages across European coating applications. Weifang Tuoshi Chemical Co., Ltd. dominates regional distribution networks, competing on freight-optimized deliveries to East Asian polymer processors.
Dibutyl Maleate functions as a dibutyl ester of maleic acid, manufactured through esterification of maleic anhydride with n-butanol under acid catalysis, serving primarily as an internal plasticizer and copolymerizable monomer in vinyl resin systems. The plasticizers segment leads volume consumption due to entrenched PVC modification demand across wire insulation and flooring substrates. Coatings applications represent the fastest-expanding category as waterborne alkyd and acrylic formulations adopt DBM for improved flexibility and adhesion. The adhesives segment occupies narrower but higher-margin niches in electronics assembly and automotive bonding where copolymerization with vinyl acetate enhances thermal resistance.
REACH registration requirements under ECHA govern DBM import and manufacture across the European Union, compelling substance characterization and supply chain communication obligations. China's MEE enforces emission controls on butanol and maleic anhydride production facilities, tightening feedstock availability for domestic DBM synthesis. The EPA Toxic Substances Control Act subjects imported chemical substances to pre-manufacture notification pathways in the United States. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost shifts and qualify alternative ester chemistries before supply bottlenecks materialize.
Market Dynamics
REACH chemical safety thresholds in Germany are compelling PVC compounders to reformulate interior automotive applications, redirecting specification authority from processors to certified chemical suppliers.
Growth Catalysts
- Automotive interior mandates:German OEMs now require REACH-compliant plasticizers for cabin vinyl components, accelerating DBM qualification in seat coverings and dashboard skins.
- Electronics-grade coatings:Buyers in China and the United States are consolidating procurement around certified high-purity grades for circuit board protection and display lamination.
- Waterborne alkyd adoption:Coatings formulators are substituting solvent-based flexibilizers with DBM to meet volatile organic compound restrictions without sacrificing adhesion performance.
Market Restraints
- Maleic anhydride feedstock volatility:China's MEE emission controls on anhydride production facilities have tightened domestic availability, elevating spot price uncertainty for East Asian DBM synthesis.
- Phthalate substitution competition:Adipate and citrate esters compete for PVC modification share in flooring and wire insulation, pressuring DBM volume in cost-sensitive construction segments.
- Butanol supply concentration:Regional n-butanol production clusters in the Middle East and Southeast Asia create freight exposure for European and North American DBM manufacturers.
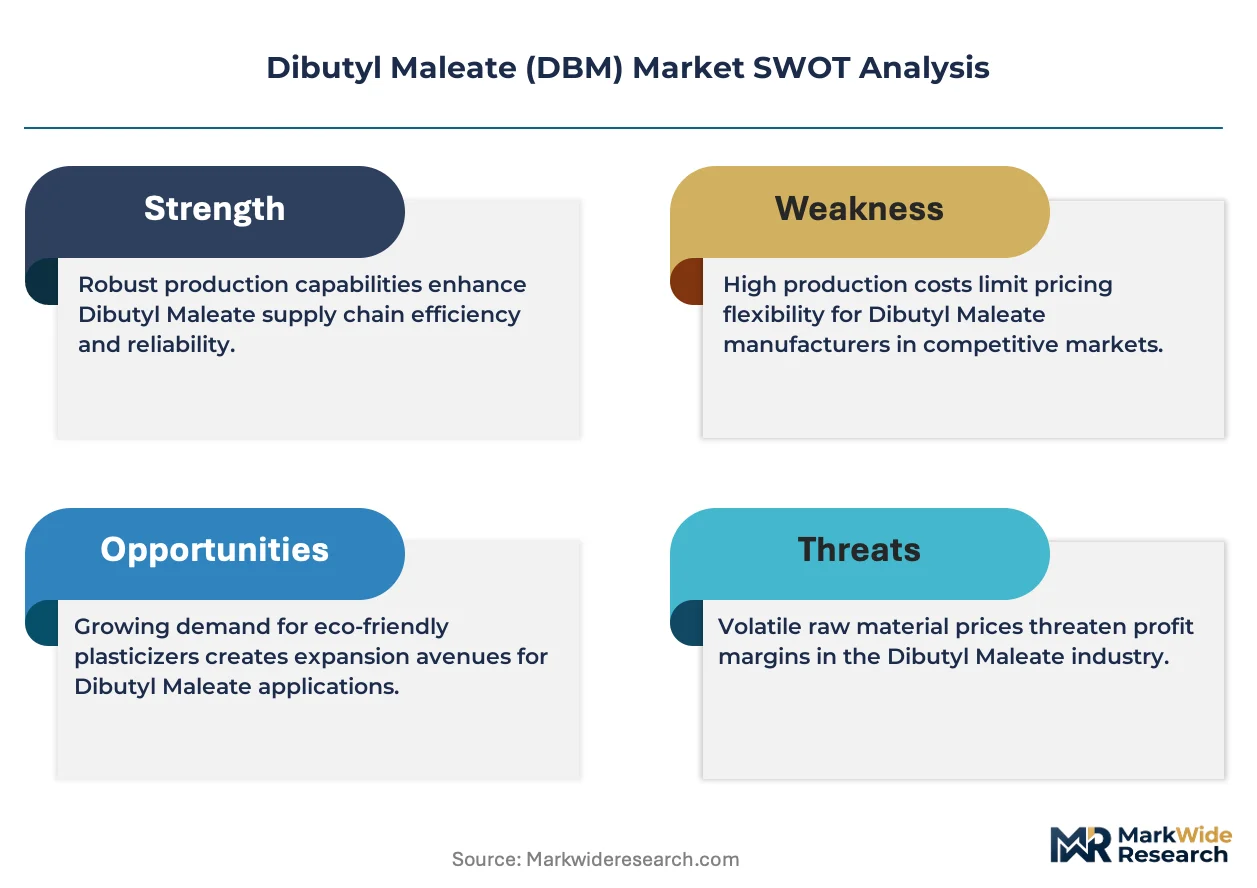
Strategic Opportunities
- India specialty chemicals expansion:BIS certification pathways for industrial chemicals remain underdeveloped, offering first-mover positioning for compliant DBM grades in emerging polymer processing hubs.
- Bio-based maleic anhydride:Fermentation-derived feedstocks are converging with conventional catalytic esterification, enabling carbon-intensity claims for sustainability-indexed coating formulations.
- Direct-to-compounder distribution:Digital procurement platforms are bypassing traditional distributor tiers, allowing producers to capture margin from formulation-technical service bundling.
Industry Challenges
- ECHA dossier maintenance burden:Substance characterization updates and supply chain communication obligations consume specialized regulatory affairs capacity at mid-scale manufacturers.
- Legacy equipment retrofit costs:Waterborne DBM incorporation requires mixing vessel and drying line modifications that strain capital allocation at regional coatings operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dibutyl Maleate (DBM) Market |
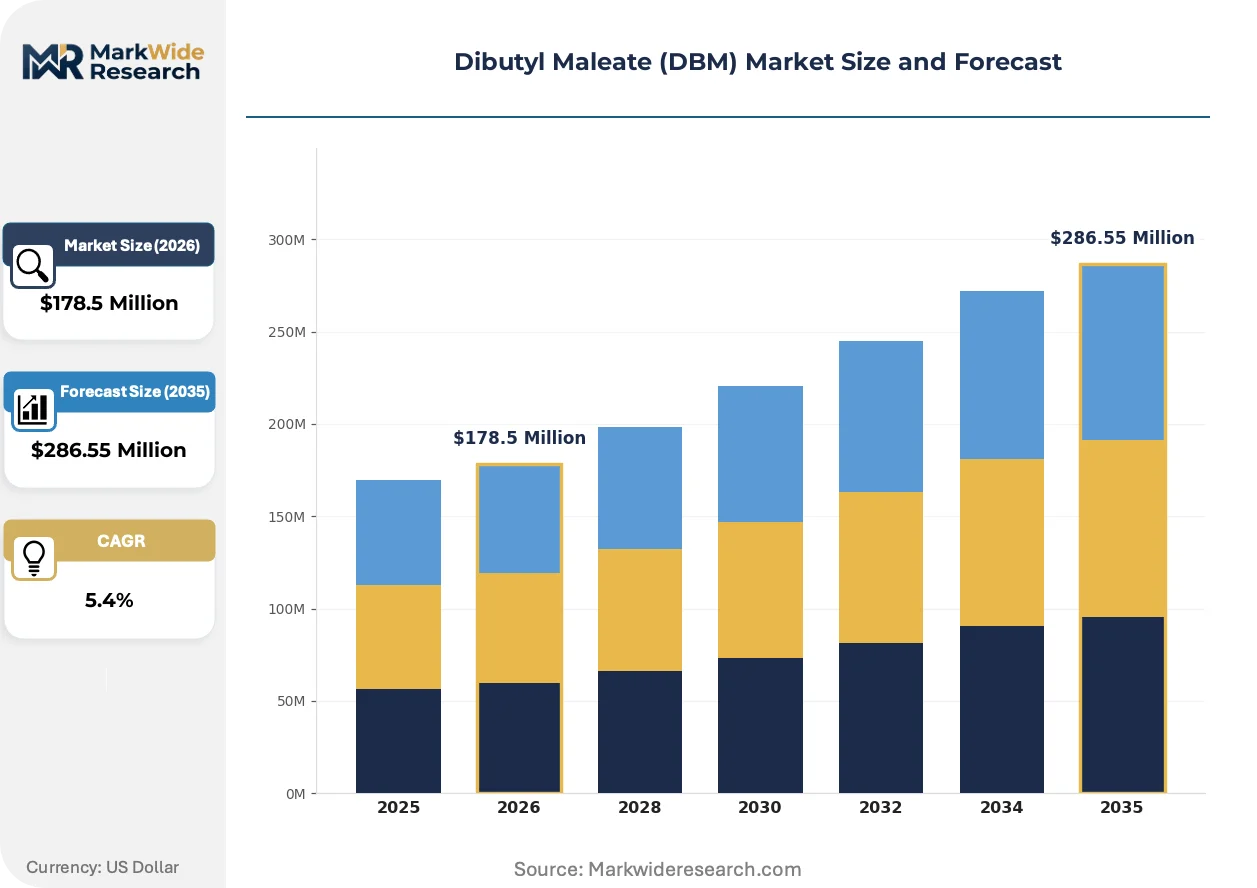
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $286.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Coatings, Adhesives, Solvents End Use Industry: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Online, Direct Sales, Distributors, Retail Application: Paints, Sealants, Inks, Textiles |
| Companies Covered | Baoji Jinbaoyu Technology Co., Ltd., ChemService, Inc., Celanese Corporation, Loba Chemie Pvt. Ltd., Weifang Tuoshi Chemical Co., Ltd., Sigma-Aldrich, Nayakem, Silver Fern Chemical, Polynt SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dibutyl Maleate (DBM) Market Strategic Shifts
Formulation chemistry is pivoting toward reactive plasticizers that copolymerize into resin matrices rather than leaching over product lifecycles, compressing the distinction between monomer and additive categories.
Reactive diluent technology is absorbing the functional role of conventional external plasticizers in radiation-cured coatings. Automotive refinish shops and industrial maintenance painters are adopting these systems to eliminate solvent flash-off stages. The technology is absorbing volume from traditional DBM applications in high-performance metal coatings by enabling single-coat buildup with equivalent flexibility.
EPA Toxic Substances Control Act pre-manufacture notification pathways are lengthening qualification timelines for imported chemical substances. Industrial buyers are responding by dual-sourcing from domestic synthesis assets and maintaining larger safety stocks. Electronics-grade coating operations in Texas and California face the most acute compliance timeline pressure due to just-in-sequence supply contracts.
Compounders are consolidating vendor relationships around formulation-technical service bundles rather than discrete chemical procurement. Regional polymer processors in the Ohio River Valley and Lower Rhine industrial corridor now specify plasticizer-coating combinations from single suppliers. This concentration is most visible in wire and cable manufacturing, where compounders trade formulation control for regulatory documentation efficiency.
Dibutyl Maleate (DBM) Market Segmentation
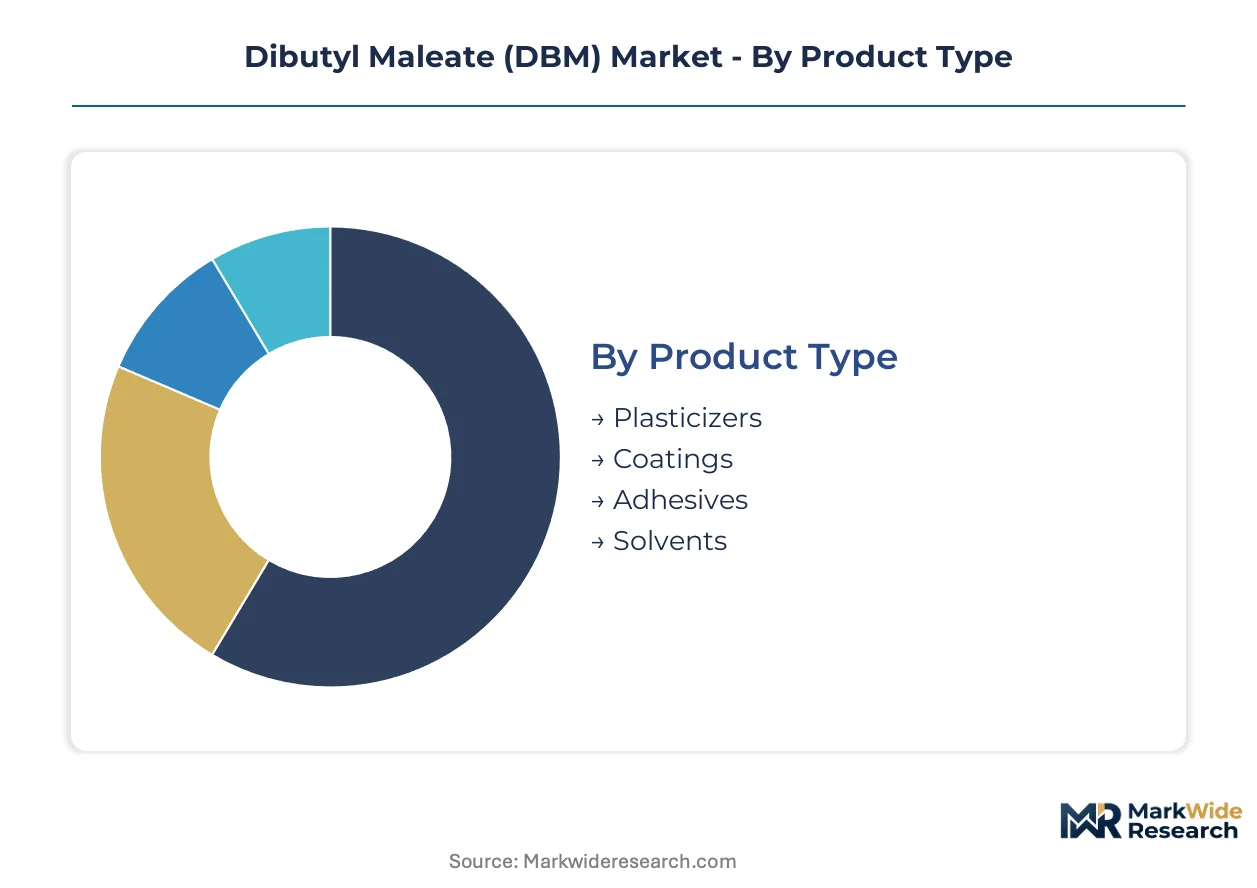
DBM procurement patterns diverge sharply across end-use specifications, with automotive OEMs demanding REACH-compliant certification bundles while electronics buyers prioritize purity-grade documentation. Compounders select product types based on copolymerization requirements rather than commodity pricing, concentrating volume in plasticizer grades that internalize within PVC matrices.
Product Type:
Buyers prioritize functional permanence over initial cost, selecting grades that chemically bind into resin systems rather than migrate over service life.
- Plasticizers:These internal plasticizers copolymerize with vinyl acetate and PVC resins to eliminate plasticizer bleed in wire insulation and flooring substrates. German automotive seat manufacturers now mandate REACH-registered grades from certified suppliers, redirecting procurement authority upstream to substance registrants with complete ECHA dossiers.
- Coatings:Waterborne alkyd and acrylic formulations incorporate DBM as a flexibilizing comonomer that maintains adhesion under VOC restrictions. Demand concentrates in China and the United States for electronics-grade protective coatings on circuit boards and display laminations, where buyers consolidate procurement around certified high-purity supply.
- Adhesives:Copolymerization with vinyl acetate enhances thermal resistance in electronics assembly and automotive bonding applications.
- Solvents:Reactive diluent applications in radiation-cured systems serve refinish shops seeking single-coat buildup with equivalent flexibility.
Volume sits with Plasticizers; growth tilts toward Coatings.
End Use Industry:
Specification authority varies by sector maturity, with automotive and electronics buyers wielding documentation requirements that filter supplier pools.
- Automotive:Cabin vinyl components including dashboard skins and seat coverings drive reformulation activity as German OEMs enforce REACH-compliant plasticizer mandates. KBA vehicle-type approval processes now reference substance registration status, compelling compounders to source from ECHA-registered suppliers with complete safety data chain communication.
- Electronics:Circuit board protection and display lamination applications demand certified high-purity grades with documented impurity profiles. Texas and California coating operations face acute EPA Toxic Substances Control Act compliance timeline pressure due to just-in-sequence supply contracts, driving dual-sourcing from domestic synthesis assets.
- Construction:Wire insulation and flooring substrates consume standard-grade plasticizers where adipate and citrate esters compete on cost.
- Consumer Goods:Flexible packaging and household product applications occupy narrower specification niches with less stringent registration requirements.
Automotive commands procurement spend; Electronics expands most quickly.
Distribution Channel:
Channel selection reflects buyer scale and formulation complexity, with large compounders bypassing intermediaries to capture technical service value.
- Direct Sales:Polymer processors in the Ohio River Valley and Lower Rhine industrial corridor specify plasticizer-coating combinations through single-supplier relationships. Celanese Corporation and Polynt SpA anchor supply security through integrated production chains, offering formulation-technical service bundles that consolidate vendor relationships.
- Distributors:Weifang Tuoshi Chemical Co., Ltd. dominates East Asian regional networks, competing on freight-optimized deliveries to polymer processors with less sophisticated formulation requirements.
- Online:Digital procurement platforms emerge for standard-grade spot purchases by small-scale compounders.
- Retail:Limited to solvent-grade volumes for maintenance and repair applications.
Direct Sales captures margin from formulation bundling; Online gains share fastest among small buyers.
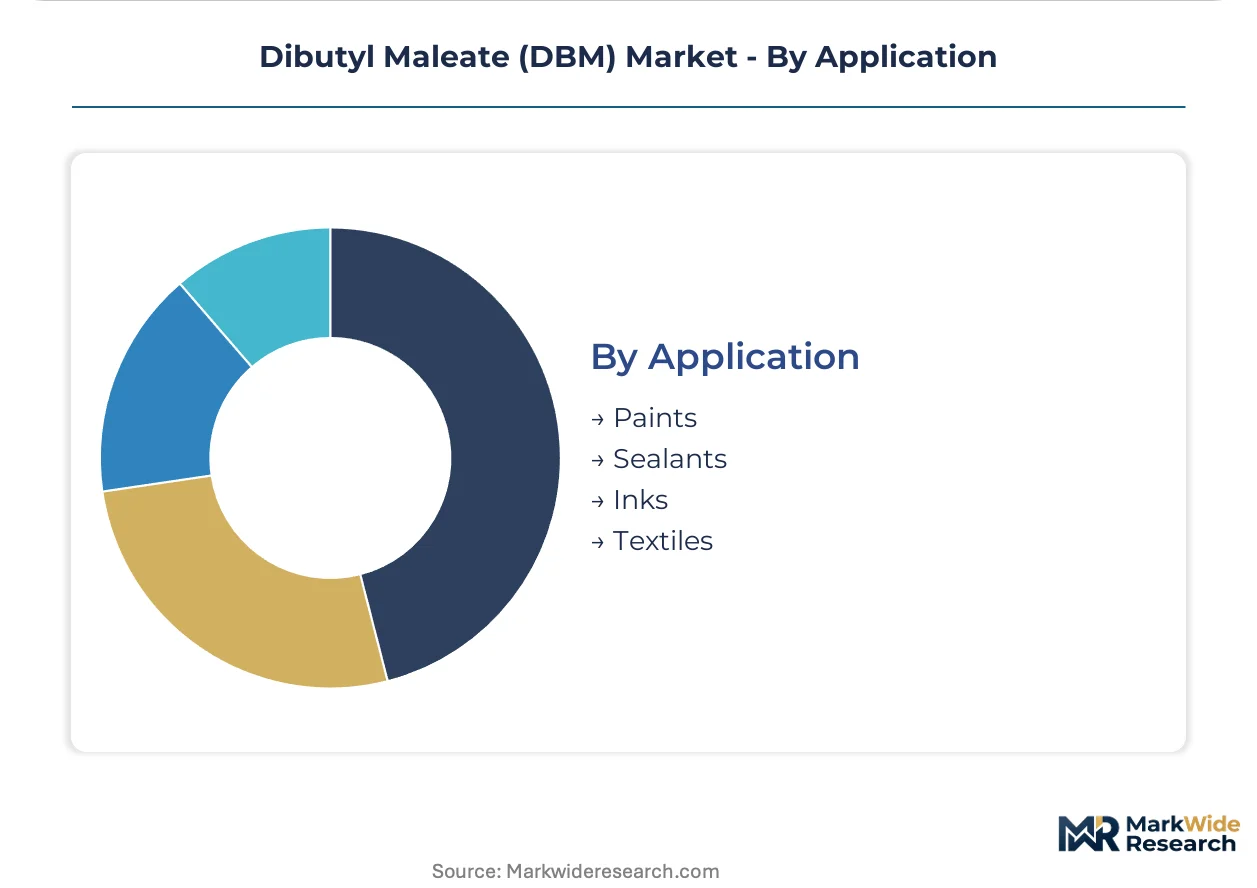
Application:
Performance requirements segment demand by durability and environmental exposure conditions.
- Paints:Industrial maintenance and automotive refinish applications adopt waterborne alkyd formulations with DBM flexibilizers to meet volatile organic compound restrictions without sacrificing adhesion performance.
- Sealants:Construction joint and automotive seam sealing applications require copolymerizable grades that maintain elasticity under thermal cycling.
- Inks:Flexographic and gravure printing formulations utilize DBM as a reactive diluent in radiation-cured systems.
- Textiles:Synthetic fiber coatings and fabric finishing applications occupy specialty niches with limited volume scale.
Paints anchor current consumption; Sealants climb the fastest on infrastructure and automotive assembly demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates DBM production capacity while Germany and the United States absorb premium grades for automotive and electronics applications. This geographic split shapes trade flows and regulatory compliance burdens across the value chain.
China
Electronics-grade coating demand from circuit board manufacturers in Guangdong and Jiangsu provinces drives high-purity DBM procurement. MEE emission controls on maleic anhydride facilities tighten feedstock availability and elevate spot price uncertainty. The Yangtze River Delta cluster hosts polymer processors reformulating PVC compounds for export markets.
Germany
Automotive OEMs in Stuttgart and Munich mandate REACH-compliant plasticizers for cabin vinyl components. ECHA registration requirements govern substance characterization and supply chain communication obligations. The Lower Rhine industrial corridor concentrates wire insulation compounders sourcing from certified chemical suppliers.
United States
Texas and California electronics coating operations face acute EPA Toxic Substances Control Act compliance timeline pressure. Dual-sourcing from domestic synthesis assets expands as buyers respond to lengthening pre-manufacture notification pathways. The Ohio River Valley anchors polymer processors consolidating vendor relationships around formulation-technical service bundles.
India
Specialty chemicals expansion in Maharashtra and Gujarat creates first-mover positioning opportunities for compliant DBM grades. BIS certification pathways for industrial chemicals remain underdeveloped, filtering supplier pools. Polymer processing hubs in the Delhi-Mumbai Industrial Corridor seek freight-optimized deliveries from regional distributors.
Japan
Waterborne alkyd adoption in automotive refinish and industrial maintenance applications absorbs DBM flexibilizers. METI chemical management frameworks align with international sustainability indexing requirements. The Kansai region's coatings formulators substitute solvent-based systems to meet volatile organic compound restrictions.
Dibutyl Maleate (DBM) Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The vendor base separates into tiered clusters anchored by integrated acetyls producers, maleic anhydride specialists, and regional distribution optimizers. Three strategic archetypes dominate: backward-integrated chemical majors controlling feedstock security, formulation-technical service bundlers capturing compounder relationships, and freight-optimized regional distributors serving price-sensitive processors. Competitive moves concentrate on regulatory documentation bundling and direct-to-compounder digital procurement platforms.
Among integrated chemical majors, Celanese Corporation exemplifies the backward-integrated archetype through captive acetyls chain control. Polynt SpA occupies a position within maleic anhydride-based chemistry specialists sustaining cost advantages across European coating applications. Weifang Tuoshi Chemical Co., Ltd. represents the regional distribution optimizer archetype, anchoring East Asian supply networks through freight-optimized delivery configurations.
| Leading Market Players |
|---|
| Baoji Jinbaoyu Technology Co., Ltd. |
| ChemService, Inc. |
| Celanese Corporation |
| Loba Chemie Pvt. Ltd. |
| Weifang Tuoshi Chemical Co., Ltd. |
| Sigma-Aldrich |
| Nayakem |
| Silver Fern Chemical |
| Polynt SpA |
| Others |
Value Chain & Pricing Dynamics
Waterborne alkyd formulation adoption across automotive refinish and industrial maintenance applications compresses cost economics for solvent-based flexibilizers while concentrating procurement authority among compounders with ECHA-registered supply chains. This technology transition simultaneously elevates premium pricing for REACH-compliant grades and fragments spot-market liquidity for standard plasticizer tiers.
Pricing Analysis
Cost-down pressure on standard-grade plasticizers accelerates because adipate and citrate esters compete aggressively for PVC modification share in flooring and wire insulation applications. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with electronics-grade high-purity commands substantial premia over construction-grade volumes. Margin tightening in economy tiers reflects feedstock volatility from China's MEE emission controls on maleic anhydride facilities. Construction compounders exhibit highest price sensitivity, while automotive OEMs prioritize registration documentation over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification pathways and EPA pre-manufacture notification requirements in the United States reshape sourcing toward regional synthesis assets. Production concentrates in China, Germany, and the United States, with the Yangtze River Delta and Lower Rhine industrial corridor anchoring feedstock security. Supply chains draw from maleic anhydride, n-butanol, and acid catalyst inputs, creating exposure to butanol supply concentration in Middle Eastern and Southeast Asian production clusters. Single-source vulnerability intensifies around certified high-purity grades for electronics applications. Distribution runs through direct sales relationships for large compounders and freight-optimized regional networks for smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive diluent technology displaces conventional external plasticizers in radiation-cured coatings, compressing legacy DBM applications while opening formulation-technical service bundling opportunities for qualified suppliers.
For Market Incumbents: Hedge against phthalate substitution competition by deepening captive supply of maleic anhydride feedstocks and anchoring ECHA dossier maintenance capacity. Celanese Corporation's integrated acetyls chain exemplifies backward integration into feedstock security. Prioritize certification investment for REACH-compliant grades as German OEMs redirect procurement authority upstream. For New Entrants and Emerging Players: Small-scale compounders in India's Delhi-Mumbai Industrial Corridor represent an underserved buyer archetype seeking freight-optimized deliveries with basic formulation support. BIS certification gaps filter incumbent supplier pools, creating white-space for compliant-grade entrants. Digital procurement platforms offer direct-to-compounder go-to-market angles bypassing traditional distributor tiers. For Investors and Strategic Acquirers: Exit pathways concentrate in backward-integrated chemical majors acquiring formulation-technical service bundlers. Long-term viability hinges on carbon-intensity positioning as bio-based maleic anhydride fermentation converges with conventional esterification. Watch for dual-sourcing acceleration among Texas and California electronics coating operations as inflection signal for domestic synthesis asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Celanese Corporation's captive acetyls chain anchors supply security for downstream DBM derivatives. |
| REACH Certification Investment | ECHA-registered suppliers capture procurement authority from German automotive OEMs mandating compliant plasticizers. |
| Digital Procurement Platform Launch | Direct-to-compounder distribution captures margin from formulation-technical service bundling relationships. |
| Bio-Based Feedstock Transition | Fermentation-derived maleic anhydride enables carbon-intensity claims for sustainability-indexed coating formulations. |
| Regional Distribution Network Expansion | Weifang Tuoshi Chemical Co., Ltd. dominates East Asian freight-optimized deliveries to polymer processors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors. Bottom-up and top-down triangulation validated volume estimates against ACC and Cefic industry reports, SEC 10-K disclosures, and ECHA registration databases.
Reconciling production capacity data with end-use consumption patterns across the projection horizon, the analytical framework modeled grade tier, end-use industry, and regional production hub segmentation. CAGRs derived from elasticity-adjusted demand curves incorporating automotive interior mandate timelines and electronics-grade purity specifications.
Revisions become necessary when REACH threshold updates, MEE emission control intensification, or bio-based feedstock cost parity materialize outside baseline assumptions. Forecasts reflect documented elasticity parameters and regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
PVA Glue Market