
 Ethylene Butyl Acrylate Market | 2026-2036
Ethylene Butyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Butyl Acrylate Market Analysis
The capital-intensity divergence between reactor-scale producers and batch compounders is bifurcating competitive returns in ethylene butyl acrylate supply. Westlake Corporation leverages its integrated ethylene chain to control feedstock volatility across Gulf Coast operations. INEOS Group Limited anchors European supply through its Rotterdam crackers and downstream polymerization assets. SK Functional Polymer differentiates via specialized grafting technology for automotive sealant grades in South Korea.
Ethylene butyl acrylate is a random copolymer synthesized through high-pressure free-radical polymerization, typically containing 15-35% butyl acrylate by weight to balance flexibility with thermal stability. The material functions primarily as a tackifier and sealant base in hot-melt adhesives, impact modifier in asphalt roofing, and compatibilizer in polymer blends. The emulsion product type leads volume owing to waterborne coating mandates in construction and automotive refinishing. Packaging as an end-use industry captures expanding margin pools as e-commerce fulfillment drives demand for tamper-evident flexible seals. Granule form dominates industrial procurement channels due to melt-processing convenience and reduced dust exposure.
EPA air-quality standards for volatile organic compound emissions constrain solvent-based solution processes in U.S. manufacturing facilities. REACH registration requirements under ECHA enforce monomer purity thresholds that elevate compliance costs for European importers. FDA food-contact notifications shape copolymer migration limits in packaging applications across North America. Stakeholders must monitor feedstock spreads between ethylene and butyl acrylate monomers while positioning for bio-based acrylic acid pilot programs that could redraw raw-material economics.
Market Dynamics
High-pressure free-radical polymerization economics are squeezing batch compounders while favoring integrated ethylene producers with captive butyl acrylate supply. The resulting margin compression is forcing mid-scale processors to specialize in narrow automotive or medical grades or exit entirely.
Growth Catalysts
- E-commerce fulfillment packaging:Tamper-evident flexible seals in food and consumer goods are consuming higher volumes of hot-melt adhesive formulations. Major packaging converters in China and Germany are expanding dedicated EBA compounding lines.
- REACH registration thresholds:ECHA monomer purity mandates are elevating compliance barriers for low-grade importers. European compounders with certified supply chains are capturing displaced volume from non-compliant traders.
- Asphalt roofing modification:Impact modifier demand for SBS-modified bitumen membranes is accelerating in North American residential construction. EBA grafting improves low-temperature flexibility in polymer-modified asphalt.
Market Restraints
- Butyl acrylate feedstock volatility:Acrylic acid supply disruptions propagate directly to EBA copolymer cost structures. Producers without backward integration into ethylene face margin instability during propylene price spikes.
- Rotterdam-Gulf Coast supply concentration:European crackers and Texas ethylene hubs control over 60% of merchant butyl acrylate monomer. Geographic concentration risk elevates during Atlantic shipping disruptions or hurricane-season outages.
- Waterborne emulsion technical ceilings:High-moisture environments degrade EBA emulsion adhesion in exterior construction applications. Solvent-based alternatives retain performance advantages despite EPA VOC constraints.
Strategic Opportunities
- India packaging conversion:Domestic flexible food packaging capacity is expanding 12-15% annually with limited local EBA supply. Early entrants can anchor toll-compounding partnerships with Mumbai and Ahmedabad converters.
- Bio-based acrylic acid pilots:Fermentation-derived acrylic acid from agricultural feedstocks could redraw raw-material economics. EBA producers positioning offtake agreements now secure cost-advantaged positions if scale validates.
- Automotive lightweighting adhesives:Multi-material vehicle bodies require compatibilized bonding between dissimilar substrates. EBA grafting technology enables direct adhesion between polyolefin interiors and engineered thermoplastic structural elements.
Industry Challenges
- High-pressure reactor engineering talent:Free-radical polymerization at 1000-3000 bar requires specialized process safety expertise. The workforce pipeline for supercritical ethylene operations is thinning across European chemical engineering programs.
- FDA food-contact notification timelines:New copolymer grade approvals for direct food contact require 18-24 month review cycles. Migration testing protocols for fatty food simulants add substantial certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Butyl Acrylate Market |
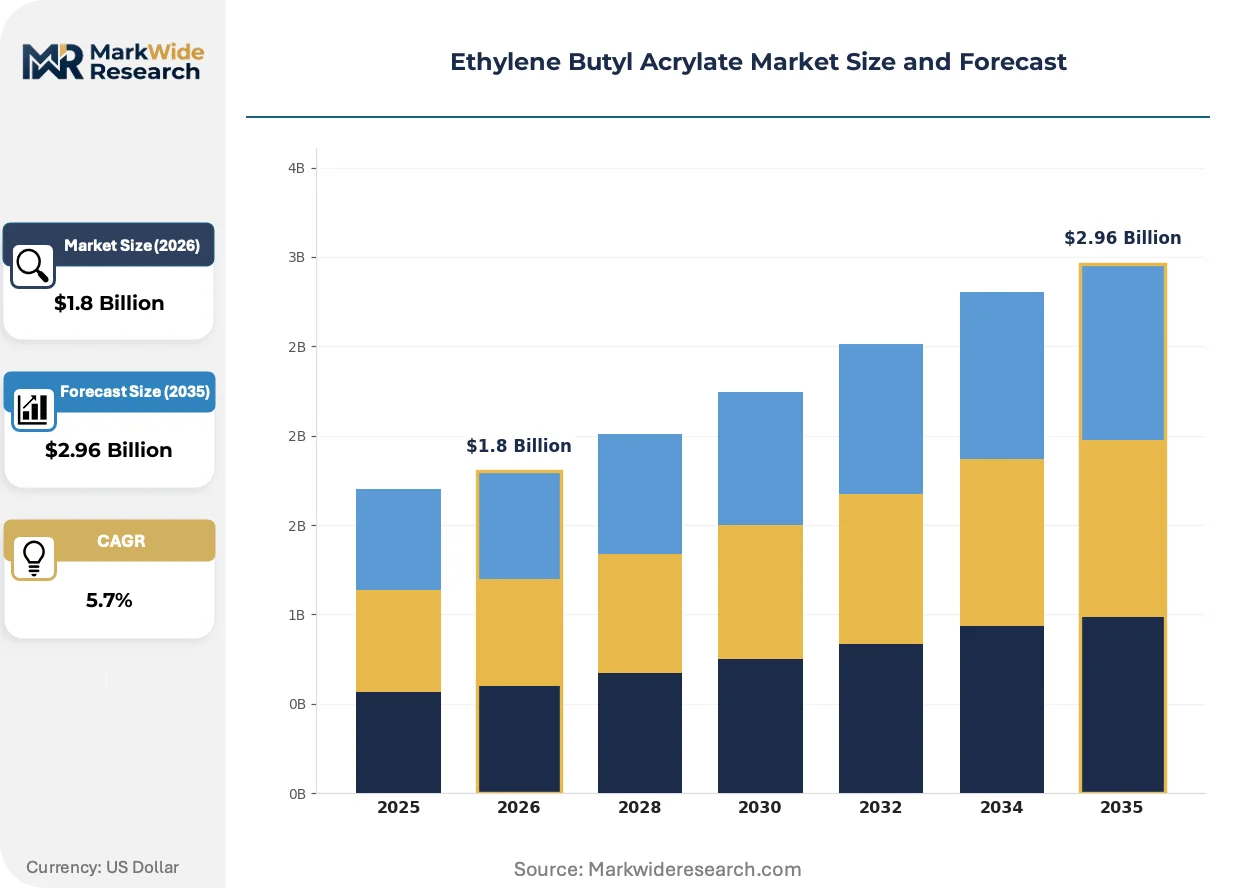
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solution, Coated, Adhesives End Use Industry: Automotive, Construction, Packaging, Textiles Form: Granules, Liquid, Powder, Sheet Technology: Traditional, Advanced, Hybrid, Others |
| Companies Covered | Westlake Corporation, INEOS Group Limited, Dow Chemical Company, LyondellBasell Industries Holdings B.V., SK Functional Polymer, ExxonMobil Chemical, Repsol S.A., SABIC, Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Butyl Acrylate Market Emerging Trajectories
Reactive extrusion and advanced grafting chemistries are fragmenting the traditional commodity-compounder hierarchy. Technical differentiation now concentrates in specialized sealant and compatibilizer grades rather than volume emulsion production.
Metallocene-catalyzed EBA variants with narrow molecular weight distribution are bifurcating the automotive sealant segment from conventional Ziegler-Natta material. Tier-1 suppliers in South Korea and southern Germany are qualifying these grades for electric vehicle battery module encapsulation. The technology is compressing margins for legacy high-pressure producers while enabling premium pricing for precision-rheology formulations.
EPA National Emission Standards for Hazardous Air Pollutants are tightening residual monomer limits in solvent-based EBA solution processes. U.S. Gulf Coast facilities face retrofit investments or process abandonment by 2027. The construction coatings segment is responding with accelerated waterborne emulsion qualification programs, though performance gaps persist in high-humidity exterior applications.
Specification-driven procurement is consolidating buyer power among multinational packaging converters with centralized adhesive formulation teams. Regional compounders in Italy and Thailand are losing share to integrated suppliers offering technical service bundled with volume contracts. The shift is most visible in European flexible food packaging, where sustainability scorecards now weight bio-content and carbon intensity alongside unit pricing.
Ethylene Butyl Acrylate Market Segmentation
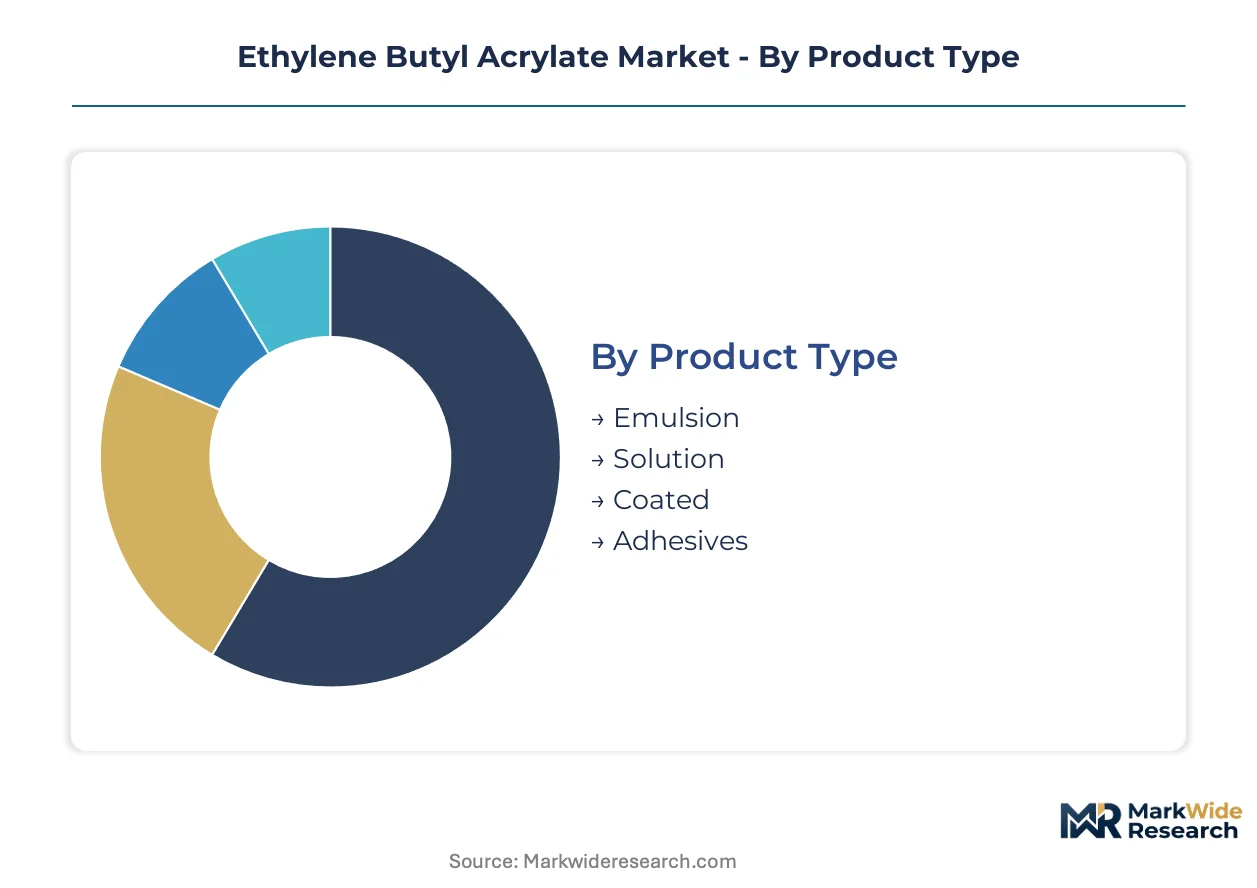
Segmentation in ethylene butyl acrylate markets reveals how technical specifications align with regulatory constraints and processing economics. Substitution pressures from metallocene polyolefins and bio-based tackifiers reshape competitive intensity across product categories.
Product Type:
Emulsion formulations face acute substitution pressure from solvent-free hot-melt alternatives as EPA VOC limits tighten, while solution grades confront direct displacement by reactive extrusion technologies in automotive sealants.
- Emulsion:Waterborne EBA dispersions incorporate surfactant-stabilized copolymer particles at 40-60% solids content for direct coating application. Packaging converters in China and Germany are expanding dedicated emulsion compounding lines to serve e-commerce fulfillment adhesive demand under evolving FDA food-contact migration limits.
- Solution:Solvent-dissolved EBA at 20-30% concentration delivers superior substrate wetting for asphalt roofing modification. North American residential construction drives consumption, though EPA National Emission Standards for Hazardous Air Pollutants force Gulf Coast facilities toward retrofit investments or process abandonment.
- Coated:Pre-applied EBA layers on carrier films enable clean-room bonding in medical device assembly.
- Adhesives:Formulated hot-melt sticks and bulk tank systems target high-speed packaging line integration.
Emulsion retains volume leadership; adhesives hold the steepest expansion curve.
End Use Industry:
Cost-tier stratification separates specification-grade automotive and medical applications from commodity construction and packaging volumes.
- Automotive:EBA grafting technology enables direct adhesion between polyolefin interiors and engineered thermoplastic structural elements in multi-material vehicle bodies. South Korean battery module encapsulation programs and southern German Tier-1 supplier qualifications are accelerating metallocene-catalyzed grade adoption for electric vehicle thermal management.
- Packaging:Hot-melt adhesive formulations for tamper-evident flexible seals concentrate demand among multinational converters with centralized technical service requirements. Sustainability scorecards now weight bio-content and carbon intensity alongside unit pricing in European flexible food packaging procurement.
- Construction:SBS-modified bitumen membranes for residential roofing consume impact modifier grades.
- Textiles:Lamination adhesives for technical nonwovens and protective apparel applications.
Packaging commands the broadest customer base; automotive generates the highest margin per kilogram.
Form:
Volume concentration favors melt-processable formats that minimize dust exposure and enable continuous extrusion feeding.
- Granules:Pelletized EBA at 2-4mm diameter dominates industrial procurement channels for melt-processing convenience and reduced workplace particulate exposure. Rotterdam crackers and Texas ethylene hubs supply over 60% of merchant material, creating geographic concentration risk during Atlantic shipping disruptions.
- Liquid:Molten bulk tank delivery eliminates solidification energy costs for high-volume adhesive compounders.
- Powder:Micronized grades for solvent slurry preparation in specialty coating applications.
- Sheet:Calendered film formats for die-cut gasket and membrane lamination.
Granules capture procurement standardization; liquid forms are gaining share in continuous process integration.
Technology:
Margin distribution bifurcates between legacy high-pressure producers and advanced grafting specialists.
- Traditional:High-pressure free-radical polymerization at 1000-3000 bar produces commodity copolymers with broad molecular weight distribution. Batch compounders without captive ethylene supply face margin compression forcing specialization or exit.
- Advanced:Metallocene-catalyzed variants with narrow molecular weight distribution enable precision-rheology formulations for electric vehicle battery encapsulation. SK Functional Polymer and southern German compounders qualify these grades at premium pricing.
- Hybrid:Reactive extrusion combining grafting and compounding in single-pass processing.
- Others:Emerging bio-based acrylic acid pilot programs and fermentation-derived monomer trials.
Traditional technology maintains installed capacity dominance; advanced platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ethylene butyl acrylate primarily for packaging adhesive compounding, while Germany and the United States concentrate demand in automotive sealant and asphalt modification grades. This consumption-mix differential shapes regional supply chain configurations and regulatory compliance priorities.
China
Domestic ethylene capacity expansion along the Yangtze River Delta supports localized butyl acrylate copolymer production for flexible food packaging converters. MIIT industrial standards for food-contact materials enforce migration testing protocols that elevate purity requirements for copolymer grades. Shanghai and Jiangsu province host expanding hot-melt adhesive formulation facilities serving e-commerce fulfillment demand.
Germany
Tier-1 automotive suppliers in Baden-Württemberg qualify metallocene-catalyzed EBA grades for electric vehicle battery module encapsulation. REACH registration requirements under ECHA enforce monomer purity thresholds that displace non-compliant import volumes. The southern German polymerization cluster around Ludwigshafen anchors European supply of specification-grade sealant materials.
United States
Gulf Coast ethylene crackers supply captive butyl acrylate for asphalt roofing modification in residential construction markets. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based solution processes, forcing facility retrofits or abandonment by 2027. Texas and Louisiana host integrated producers controlling feedstock volatility through backward ethylene integration.
South Korea
Battery module encapsulation programs for electric vehicle thermal management accelerate demand for precision-rheology copolymer formulations. MFDS pharmaceutical and medical device standards shape purity specifications for healthcare-grade EBA applications. The Busan-Ulsan industrial corridor concentrates specialized grafting technology capabilities for automotive sealant production.
India
Domestic flexible food packaging capacity expands 12-15% annually with limited local EBA supply, creating toll-compounding partnership opportunities. BIS standards for food-contact plastics are converging toward EU migration limit frameworks. Mumbai and Ahmedabad converters are establishing dedicated adhesive formulation lines for tamper-evident flexible seals.
Ethylene Butyl Acrylate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in ethylene butyl acrylate supply. Gulf Coast and Rotterdam crackers control over 60% of merchant butyl acrylate monomer, creating geographic concentration that favors producers with captive ethylene supply. Three strategic archetypes dominate: integrated petrochemical majors with backward ethylene control, specialized grafting technology compounders, and regional toll-compounding operators serving packaging converters. Competitive moves concentrate on capacity expansion in high-growth Asian markets and technology licensing for metallocene-catalyzed grade production.
Among integrated petrochemical majors, Westlake Corporation exemplifies the Gulf Coast ethylene-integrated archetype with control over feedstock volatility, while INEOS Group Limited anchors European supply positioning through Rotterdam cracker assets. SK Functional Polymer occupies a specialized tier, representing the precision-rheology compounder archetype focused on automotive and battery encapsulation grades. These three companies illustrate the bifurcation between commodity volume production and technical differentiation strategies reshaping competitive returns.
| Leading Market Players |
|---|
| Westlake Corporation |
| INEOS Group Limited |
| Dow Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| SK Functional Polymer |
| ExxonMobil Chemical |
| Repsol S.A. |
| SABIC |
| Arkema S.A. |
| Others |
Supply Flow & Price Mechanics
REACH registration requirements under ECHA simultaneously gate European supply qualification and stratify price tiers between certified and non-certified copolymer grades. This dual gating mechanism compresses margins for importers while enabling premium capture by domestic compounders with verified purity documentation.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated ethylene producers and packaging converters, insulating volume buyers from butyl acrylate monomer volatility. Spot purchasing persists among mid-scale compounders lacking backward integration, exposing them to margin compression during propylene price spikes. Price differentiation rests on REACH certification tier and volume scale, with food-contact-grade material commanding substantial premiums over industrial grades. Packaging converters in China exhibit highest price sensitivity due to thin adhesive formulation margins, while automotive Tier-1 suppliers in Germany prioritize rheology precision over unit cost.
Supply Chain Analysis
China, the United States, and Germany anchor global ethylene butyl acrylate production through integrated crackers and downstream polymerization assets. Raw material flows draw from ethylene steam crackers, acrylic acid oxidation units, and specialized free-radical initiator supply chains. Single-source vulnerability concentrates around Rotterdam-Gulf Coast butyl acrylate monomer corridors, where Atlantic shipping disruptions or hurricane-season outages propagate rapidly. Distribution runs through bulk tank rail delivery to adhesive compounders and packaged granule shipments to construction material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene butyl acrylate markets are entering a cyclical recovery phase as residential construction activity rebounds and e-commerce packaging investment accelerates. This cyclical upturn favors positioned incumbents with captive ethylene supply and certified food-contact grades.
For Market Incumbents: Consolidate position through selective capacity addition in Yangtze River Delta packaging corridors and deepening backward integration into butyl acrylate monomer production. Metallocene-catalyzed grade proliferation from South Korean specialists threatens premium tier margins; incumbents should accelerate reactive extrusion technology licensing to defend automotive sealant positioning. For New Entrants and Emerging Players: FDA food-contact notification fast-tracks offer the most penetrable entry path for regional compounders lacking REACH certification infrastructure. India's expanding flexible packaging capacity presents white-space opportunity for toll-compounding partnerships with Mumbai and Ahmedabad converters. New entrants should anchor go-to-market strategy on sustainability scorecard compliance, bundling carbon intensity documentation with volume contracts to displace legacy European suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified petrochemical majors seeking to divest non-core polymerization assets amid portfolio rationalization pressures. Mid-scale European batch compounders facing margin compression represent viable acquisition candidates for platform consolidation. Long-term viability over the coming decade hinges on positioning for bio-based acrylic acid offtake agreements; the inflection signal to monitor is fermentation-derived monomer pilot scale-up announcements from agricultural feedstock processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butyl Acrylate | Captive monomer supply insulates margin stability during propylene volatility cycles. |
| Metallocene Technology Licensing | Precision-rheology grades capture automotive battery encapsulation premium pools. |
| REACH Certification Investment | Verified purity documentation displaces non-compliant import volumes in European packaging. |
| India Toll-Compounding Partnership | Early anchoring with Ahmedabad converters secures share in 12-15% annual capacity expansion. |
| Bio-Based Acrylic Acid Offtake | Fermentation-derived monomer agreements position for raw-material economics redraw. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at integrated ethylene producers, procurement leads at packaging converters, technical R&D directors at adhesive compounders, and distribution channel partners; alongside secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up volume modeling from individual facility capacities triangulated against top-down demand aggregation from end-use industry consumption patterns.
Across the analysis window, forecasts incorporate grade tier stratification, end-use industry mix, packaging format evolution, and regional production hub shifts. CAGRs were derived from segmented growth trajectory analysis weighted by installed capacity utilization and demand elasticity coefficients. Key inputs included ethylene-butyl acrylate feedstock spread projections and regulatory compliance cost escalators for food-contact certification tiers.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce packaging investment and stable Atlantic shipping corridors; material deviation in construction activity or monomer supply disruption would warrant model refresh. Recalibration cycles align with material shifts in REACH enforcement intensity and bio-based acrylic acid commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Russia Sealants Market