
 High Performance Adhesives Market | 2026-2036
High Performance Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Adhesives Market Intelligence
German chemical producers is hardening capacity for aerospace-grade epoxy systems ahead of next-generation narrowbody programs. Henkel AG & Co. KGaA leverages its automotive OEM relationships to cross-sell structural bonding platforms into electric vehicle battery pack assembly. Sika AG anchors its position through construction-sector channel density and specification capture in infrastructure rehabilitation. Huntsman Corp. differentiates via formulated systems for composite-to-metal bonding in wind turbine blade manufacturing.
High performance adhesives are formulated systems engineered to withstand thermal cycling, chemical exposure, and mechanical loads exceeding 20 MPa lap-shear strength, serving primarily to replace mechanical fasteners in weight-critical or vibration-dampening assemblies. Epoxy formulations dominate structural bonding applications where modulus and creep resistance determine joint longevity, while UV-cured acrylics represent the fastest-expanding curing mechanism segment due to throughput advantages in electronics miniaturization. Polyurethane adhesives occupy mature volume positions in construction and transportation sealing where flexibility and moisture tolerance outweigh absolute strength requirements.
REACH registration requirements and RoHS substance restrictions in Europe compel reformulation away from legacy curatives and halogenated flame retardants, elevating compliance costs for importers while creating specification advantages for EU-based compounders. The EPA and OSHA jointly influence US workplace exposure limits and volatile organic compound thresholds that shape regional product availability and local manufacturing investment decisions. Stakeholders must monitor evolving automotive crashworthiness certification protocols and electronics reliability standards to anticipate specification shifts before they propagate through tiered supply chains.
Market Dynamics
Automotive electrification is compressing specification cycles for structural bonding systems as battery pack architectures demand thermal runaway containment and crash-resistant joint designs that legacy mechanical fastening cannot deliver.
Growth Catalysts
- EU Green Deal industrial mandates:Carbon border adjustments and embodied carbon disclosure requirements are accelerating specification of lightweight bonded assemblies in German and French automotive manufacturing.
- Wind turbine blade scaling:Rotor diameters exceeding 150 meters require composite-to-metal bonding systems that tolerate extreme centrifugal loads and offshore salt exposure.
- 5G infrastructure deployment:Base station antenna modules and small-cell enclosures demand UV-curable acrylics for rapid throughput in electronics contract manufacturing.
Market Restraints
- Specialty epoxy resin concentration:Bisphenol A and F feedstock supply clusters in the US Gulf Coast and Rotterdam-Antwerp corridor create geographic vulnerability to weather and logistics disruptions.
- REACH authorization timelines:ECHA's substance of very high concern listings for certain aromatic amine curatives are forcing reformulation investments that compress margin structures for importers.
- Mechanical fastening residual preference:Aerospace MRO facilities and legacy automotive assembly lines retain qualified rivet and bolt specifications that bonded joints must displace through extended airworthiness certification.
Strategic Opportunities
- India PLI scheme for advanced chemistry:Production-linked incentives for specialty chemicals and electric vehicle manufacturing are attracting adhesive compounders to establish localized formulation capacity.
- Two-part polyurethane spray equipment convergence:Portable metering and mixing systems are enabling on-site infrastructure rehabilitation applications that bypass distributor inventory constraints.
- Japan METI carbon neutrality roadmaps:Hydrogen economy infrastructure targets are creating specification demand for cryogenic-tolerant sealing systems in fueling station and pipeline applications.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in rheology control and cure kinetics for multi-substrate bonding is concentrating among retiring specialists at established European and Japanese compounders.
- Aerospace qualification timelines:OEM-specific material specifications and FAA/EASA joint certification protocols extend validation cycles to 18-36 months for new structural adhesive introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Adhesives Market |
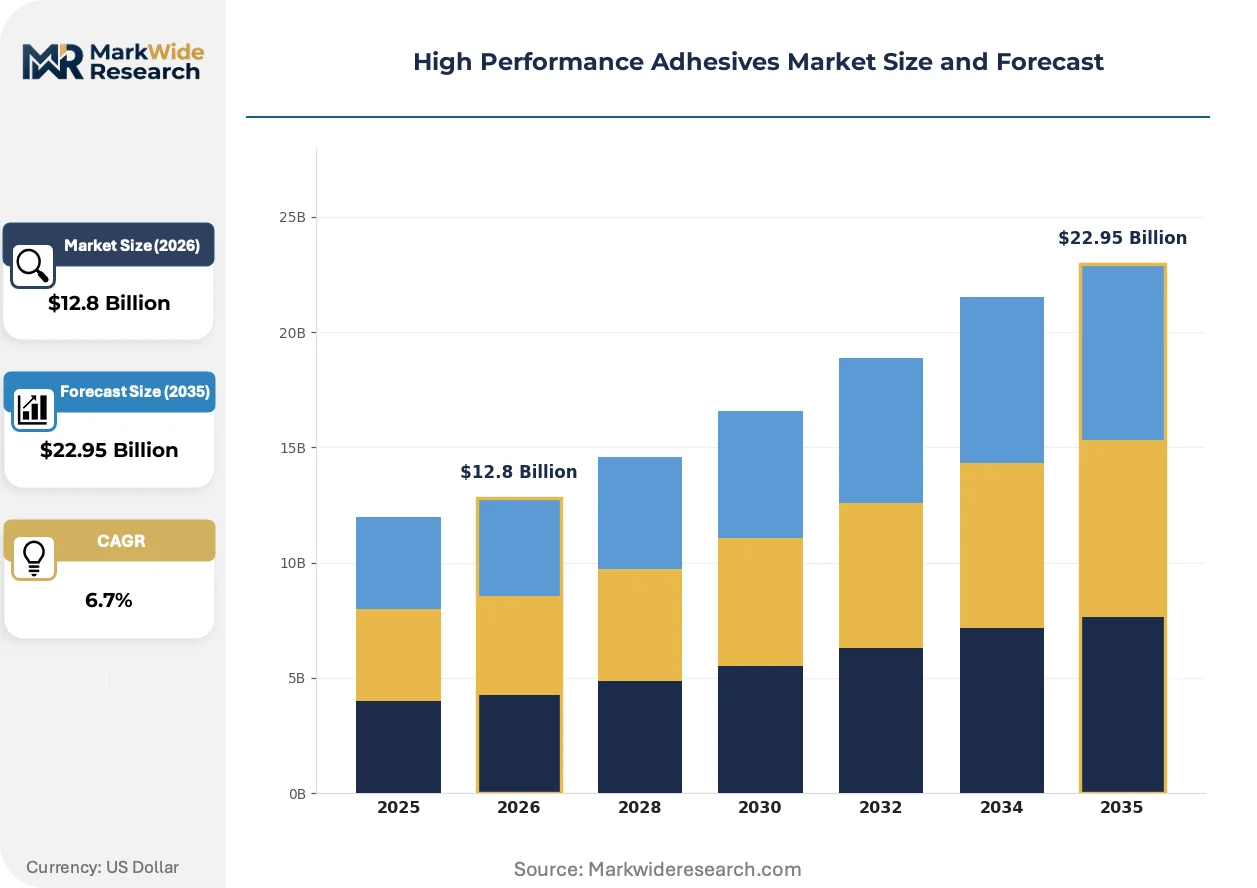
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Adhesive Type: Epoxy, Polyurethane, Acrylic, Silicone End User Industry: Aerospace, Automotive OEMs, Electronics, Construction Application: Structural Bonding, Surface Mount Technology, Packaging, Assembly Curing Mechanism: Heat-Cured, UV-Cured, Moisture-Cured, Room Temperature-Cured |
| Companies Covered | Sika AG, Huntsman Corp., Henkel AG & Co. KGaA, Ashland, Avery Dennison Corp., 3M, Arkema, Dymax Corporation, H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Adhesives Market Strategic Shifts & Innovations
Digital manufacturing integration and predictive specification tools are compressing the traditional trial-and-error adhesive selection process, while regulatory chemistry restrictions and end-use performance demands pull formulation innovation in divergent directions.
Robotic dispensing and inline cure monitoring is automating quality assurance in automotive battery pack assembly lines. Tier one suppliers in Germany and South Korea are deploying vision-guided adhesive application systems that adjust bead geometry in real time based on substrate surface energy readings. This automation is compressing defect rates and enabling statistical process control data that OEMs require for warranty risk allocation.
REACH authorization and restriction procedures are systematically removing legacy curatives from the EU market. ECHA's 2024-2025 work program targets additional aromatic amines and halogenated flame retardants used in electronics-grade formulations. Electronics contract manufacturers in Hungary and Poland are accelerating qualification of aliphatic amine and phosphorus-based alternatives ahead of sunset date enforcement.
Direct specification relationships between adhesive compounders and automotive OEM engineering teams are displacing traditional distributor-led technical selling. Battery pack designers at German and US manufacturers now engage formulation scientists in joint development agreements that lock in multi-year supply commitments. This pattern is most visible in the electric vehicle segment where thermal runaway containment bonding requires application-specific rheology and cure profiles.
High Performance Adhesives Market Segmentation
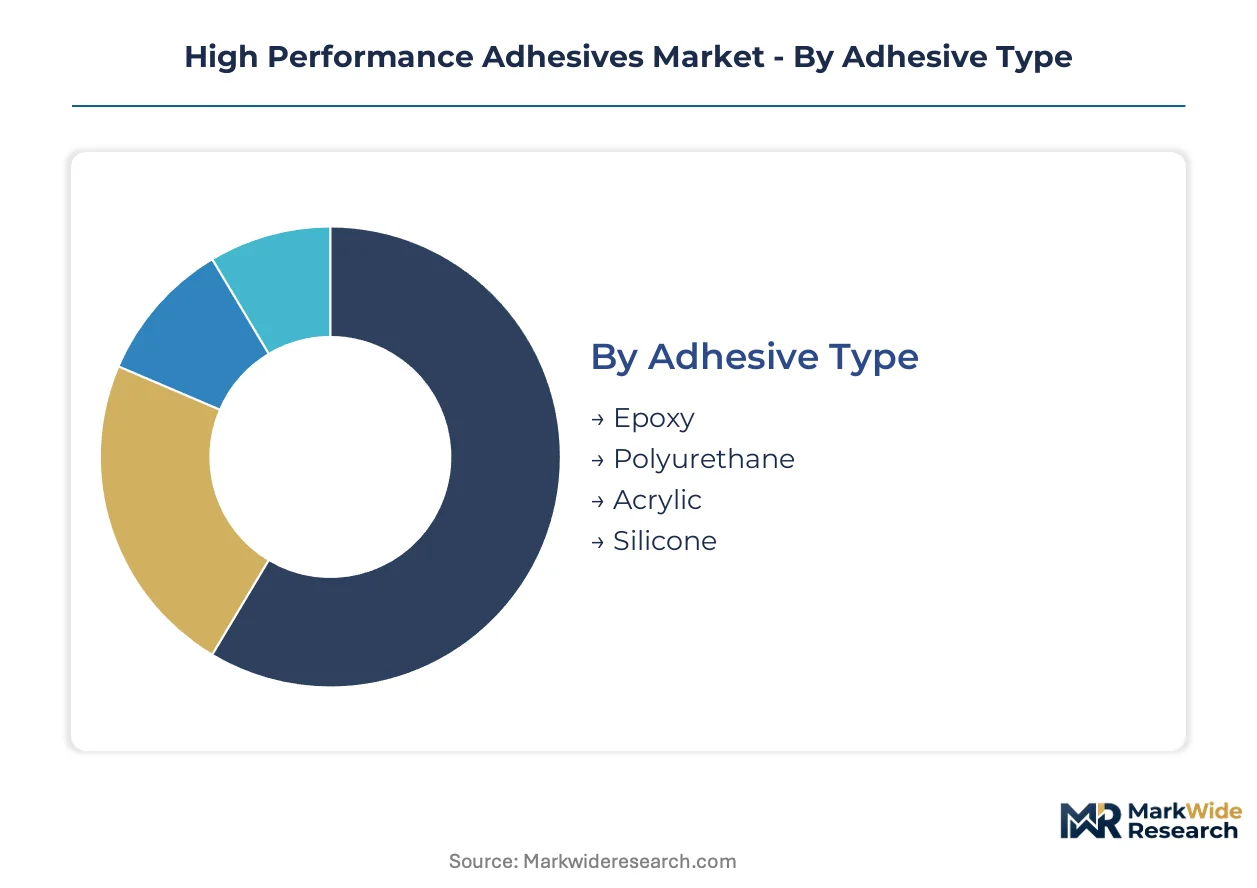
High performance adhesives demand divergent formulation architectures across end-use contexts, with specification authority residing at the OEM engineering level rather than distributor channels. Segmentation reveals how thermal, chemical, and mechanical load requirements fragment procurement patterns across aerospace qualification protocols, automotive crashworthiness mandates, and electronics miniaturization timelines.
Adhesive Type:
Material selection hinges on modulus requirements versus flexibility tolerance, with each chemistry commanding distinct specification networks and qualified supplier bases.
- Epoxy:Rigid thermoset systems built from bisphenol A/F resins and amine or anhydride curatives deliver lap-shear strength exceeding 25 MPa. German automotive OEMs and tier suppliers anchor procurement for battery pack structural bonding where thermal runaway containment demands creep resistance under sustained load.
- Polyurethane:Elastomeric systems formed from isocyanate-terminated prepolymers tolerate substrate movement and moisture exposure. Construction-sector channel density in infrastructure rehabilitation applications leverages portable spray equipment to bypass traditional distribution constraints.
- Acrylic:UV-curable formulations with photoinitiator packages enable rapid polymerization for electronics contract manufacturing throughput. 5G base station antenna modules and small-cell enclosures in South Korean and Taiwanese manufacturing clusters drive specification volume.
- Silicone:Polysiloxane backbones with condensation or addition cure mechanisms maintain elasticity across temperature extremes from -50°C to 200°C. Aerospace engine nacelles and exhaust systems require FAA/EASA-qualified formulations.
Epoxy leads on scale; acrylic leads on momentum.
End User Industry:
Procurement concentration tracks OEM engineering headcount and specification authority, with direct compounder relationships displacing distributor-led technical selling in high-complexity segments.
- Aerospace:OEM-specific material specifications and joint FAA/EASA certification protocols extend validation cycles to 18-36 months for structural adhesive introductions. Bonded composite assemblies in next-generation narrowbody programs reduce airframe weight versus riveted joints.
- Automotive OEMs:Battery pack architectures demand thermal runaway containment and crash-resistant joint designs that legacy mechanical fastening cannot deliver. German OEM engineering teams engage formulation scientists in joint development agreements locking multi-year supply commitments.
- Electronics:Miniaturization trends and reliability standards for handheld devices and base station infrastructure compress qualification timelines. REACH authorization procedures are systematically removing legacy aromatic amine curatives from EU-sourced formulations.
- Construction:Infrastructure rehabilitation specifications capture channel density through Sika AG and similar compounders with established contractor relationships. Two-part polyurethane spray equipment convergence enables on-site applications.
Automotive OEMs concentrate procurement authority; electronics contracts expand most quickly.
Application:
Functional role determines rheology requirements, cure kinetics, and quality assurance protocols across manufacturing processes.
- Structural Bonding:High-modulus epoxy systems replace mechanical fasteners in load-bearing assemblies where joint longevity depends on creep resistance. Wind turbine blade manufacturing demands composite-to-metal bonding tolerating centrifugal loads exceeding 150-meter rotor diameters.
- Surface Mount Technology:Rapid-cure acrylics and specialized epoxies secure components to printed circuit boards with precision placement requirements. Electronics contract manufacturers in Hungary and Poland accelerate qualification of aliphatic amine alternatives ahead of ECHA sunset dates.
- Packaging:Barrier and sealing applications prioritize moisture resistance and food-contact compliance where flexibility outweighs absolute strength.
- Assembly:General industrial bonding spans substrate diversity from metals to engineered plastics with formulation customization for production line integration.
Structural bonding commands specification premiums; surface mount technology shows steepest expansion trajectory.
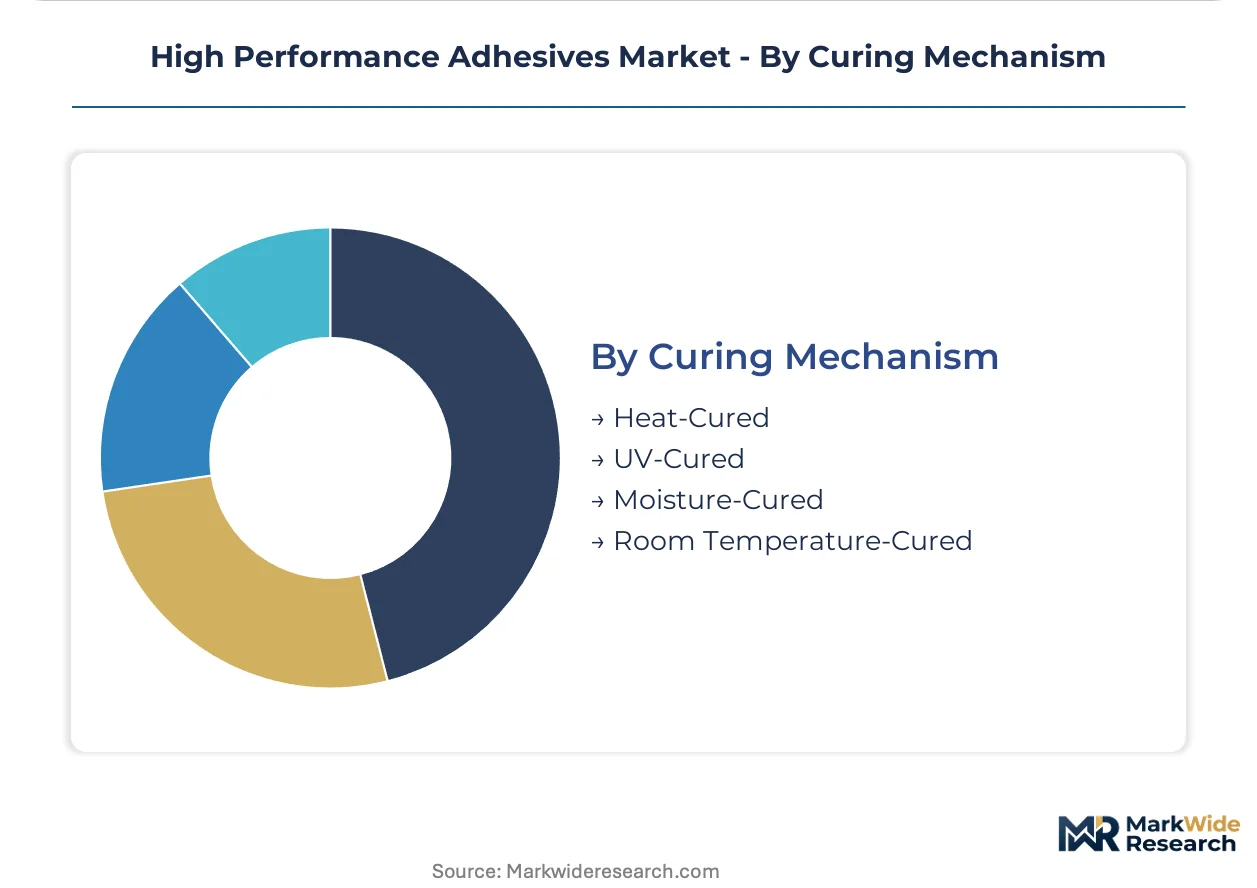
Curing Mechanism:
Throughput economics and substrate thermal sensitivity determine curing technology selection, with automation readiness increasingly shaping procurement decisions.
- Heat-Cured:Elevated temperature activation delivers complete polymerization and maximum crosslink density for structural applications. Aerospace composite bonding ovens and automotive paint shop integration leverage existing thermal infrastructure.
- UV-Cured:Photoinitiator-triggered polymerization completes in seconds under UV-A or UV-C exposure, enabling electronics manufacturing line speeds incompatible with thermal processes. Robotic dispensing with inline cure monitoring automates quality assurance.
- Moisture-Cured:Atmospheric humidity or substrate surface moisture triggers isocyanate or alkoxy-silane reactions for field applications without controlled environments.
- Room Temperature-Cured:Two-part mixing or latent hardener systems eliminate energy input for large-scale infrastructure or repair scenarios where heating is impractical.
Heat-cured systems retain volume leadership; UV-cured platforms gain share fastest in electronics manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting formulation capacity toward jurisdictions with clearer chemical authorization pathways. REACH compliance costs in Europe are accelerating investment in US Gulf Coast and Asian manufacturing clusters where EPA oversight offers more predictable substance approval timelines.
Germany
Automotive OEMs in Stuttgart and Munich are driving specification of battery pack structural adhesives with thermal runaway containment requirements. ECHA's 2024-2025 work program on aromatic amine curatives is forcing reformulation investments among compounders in North Rhine-Westphalia. The Rhine-Ruhr chemical cluster is expanding aerospace-grade epoxy capacity ahead of next-generation narrowbody programs.
United States
EPA workplace exposure limits and OSHA volatile organic compound thresholds are shaping regional product availability for electronics and automotive applications. The US Gulf Coast bisphenol A and F feedstock concentration creates geographic vulnerability to weather disruptions. Texas and Louisiana chemical producers are hardening supply chain redundancy for specialty resin inputs.
China
MIIT industrial standards and dual carbon goals are compressing specification cycles for lightweight bonded assemblies in electric vehicle manufacturing. The Yangtze River Delta electronics contract manufacturing cluster is accelerating UV-curable acrylic qualification for 5G base station antenna modules. Shanghai and Suzhou compounders are building formulation capacity for domestic wind turbine blade bonding.
Japan
METI carbon neutrality roadmaps are creating specification demand for cryogenic-tolerant sealing systems in hydrogen economy infrastructure. The Nagoya automotive engineering corridor is engaging adhesive compounders in joint development agreements for fuel cell vehicle assembly. Chubu region producers are qualifying formulated systems for pipeline applications at hydrogen fueling stations.
South Korea
Electronics reliability standards for handheld devices and telecommunications infrastructure are compressing qualification timelines for miniaturized bonding applications. The Seoul Capital Area manufacturing cluster is deploying vision-guided adhesive application systems with inline cure monitoring for battery pack assembly. Busan-Ulsan port logistics are enabling import of specialty epoxy resins for composite-to-metal bonding in shipbuilding.
High Performance Adhesives Market Key Industry Players
German chemical producers anchor one tier; US and Japanese specialists hold differentiated positions in electronics and aerospace qualification. The vendor base concentrates among established compounders with deep formulation expertise and OEM specification capture. Three archetypes dominate: construction-sector channel capturers, automotive OEM relationship holders, and electronics throughput enablers. Competitive moves center on direct specification relationships with engineering teams and capacity expansion in regulatory-advantaged jurisdictions.
Within the automotive OEM relationship tier, Henkel AG & Co. KGaA and Huntsman Corp. represent distinct geographic anchoring strategies. Sika AG exemplifies construction-sector channel density with established contractor specification capture. Among diversified chemical conglomerates, 3M and Arkema occupy positions spanning multiple end-use segments through portfolio breadth. Avery Dennison Corp. and H.B. Fuller represent adhesive specialists with focused formulation expertise.
| Leading Market Players |
|---|
| Sika AG |
| Huntsman Corp. |
| Henkel AG & Co. KGaA |
| Ashland |
| Avery Dennison Corp. |
| 3M |
| Arkema |
| Dymax Corporation |
| H.B. Fuller |
| Others |
Cost & Logistics Intelligence
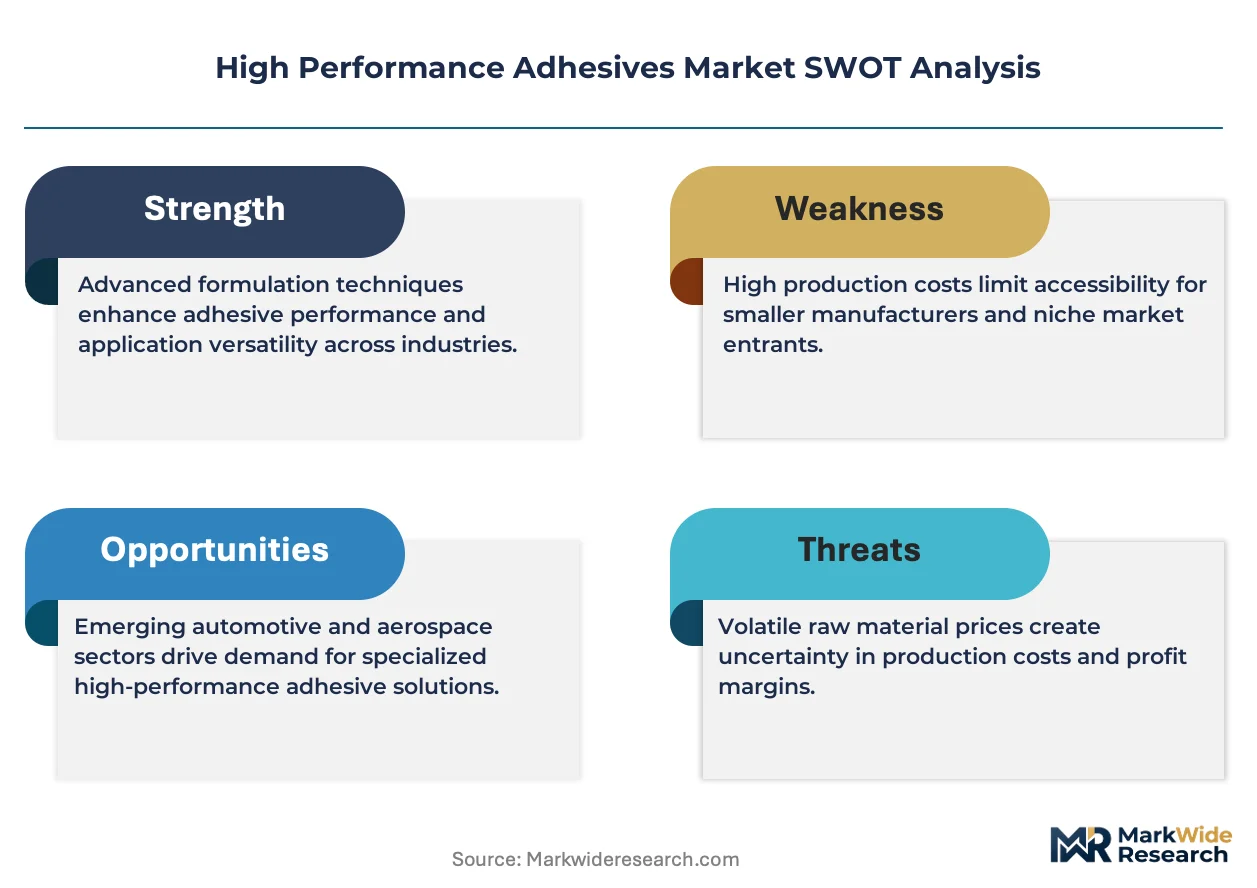
Bisphenol A spot price indices on the US Gulf Coast cascade through formulation costs into three distinct pricing tiers for epoxy systems, with aerospace-grade specifications commanding premiums that reflect REACH compliance investments and qualification timelines.
Pricing Analysis
Distributor margins absorb the steepest compression as direct compounder-to-OEM relationships displace traditional technical selling channels. A three-tier pricing structure separates aerospace-qualified formulations from automotive-grade systems and construction-sector polyurethanes, with price differentiation anchored in certification grade and volume scale. Pricing pressure stems from ECHA authorization timelines forcing reformulation investments that compress margin structures for importers. Construction contractors exhibit the highest price sensitivity, while German automotive OEMs prioritize thermal runaway performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with bisphenol A and F feedstock concentration across the US Gulf Coast and Rotterdam-Antwerp corridor, where weather disruptions and logistics bottlenecks propagate through specialty resin availability. Raw material dependencies draw from aromatic amine curatives, halogenated flame retardants, and photoinitiator packages sourced predominantly from China, Germany, and Japan. Supply chain risk centers on ECHA substance of very high concern listings that force qualified alternative sourcing. Distribution runs through construction-sector channel capturers in Europe and electronics contract manufacturing clusters in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU REACH compliance costs and US EPA substance approval timelines, with formulation capacity migration toward regulatory-advantaged jurisdictions capturing margin expansion.
For Market Incumbents: Anticipate specification capture erosion as digital manufacturing tools compress adhesive selection cycles and enable statistical process control data sharing that weakens traditional technical service differentiation. Defend position by accelerating backward integration into specialty epoxy resin production in Texas and Louisiana to harden feedstock security. Prioritize certification investment for cryogenic-tolerant systems ahead of Japan METI hydrogen economy infrastructure deployment. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry opens a window for localized formulation capacity serving electric vehicle battery pack assembly and wind turbine blade manufacturing. Target on-site infrastructure rehabilitation applications enabled by portable two-part polyurethane spray equipment that bypasses established distributor inventory constraints. Pursue joint development agreements with Tier 1 automotive suppliers rather than direct OEM engagement to compress qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap compounders possessing aerospace qualification credentials and untapped capacity in regulatory-advantaged geographies. Long-term viability favors specialists with deep rheology expertise and OEM specification lock-in across multiple end-use segments. Watch for inflection signals in India PLI scheme disbursement rates and Japan hydrogen fueling station deployment milestones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Huntsman Corp. and Henkel AG harden Gulf Coast feedstock security against weather disruptions. |
| REACH-Compliant Formulation Transition | Aliphatic amine alternatives displace aromatic curatives ahead of ECHA sunset enforcement. |
| Direct OEM Specification Relationships | German battery pack designers lock multi-year supply commitments through joint development agreements. |
| Portable Spray Equipment Convergence | Two-part polyurethane systems enable on-site infrastructure rehabilitation bypassing distributor constraints. |
| Cryogenic-Tolerant System Qualification | Chubu region producers target METI hydrogen economy pipeline and fueling station specifications. |
Research Approach
Direct dialogue with adhesive compounder R&D directors, automotive Tier 1 procurement leads, aerospace material qualification engineers, and electronics contract manufacturing operations heads grounded this analysis in operational reality. Secondary validation drew from ECHA substance registration databases, USITC trade flow records, SEC 10-K filings of listed chemical producers, and MIIT industrial standard disclosures. Bottom-up segmentation modeling and top-down macroeconomic anchoring were triangulated against production capacity announcements and OEM specification timelines.
Bottom-up demand modeling aggregated end-use consumption patterns across aerospace qualification protocols, automotive crashworthiness mandates, and electronics miniaturization timelines, while top-down validation checked against chemical industry production capacity and feedstock availability across the analysis window. Segmentation dimensions included adhesive chemistry, curing mechanism, end-use industry, and regional regulatory cluster. CAGRs were derived from production volume trends, OEM platform deployment schedules, and substitution rates for mechanical fastening. Forecast inputs incorporated ECHA authorization timeline probabilities and India PLI scheme capacity buildout trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restrictions or Gulf Coast hurricane disruptions that exceed historical severity. Forecasts reflect documented assumptions regarding qualification timeline compression and regulatory arbitrage sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Epoxy Active Diluent Market