
 Global Acrylic Adhesives Market | 2026-2036
Global Acrylic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Adhesives Market Foresight
The acrylic adhesives sector is consolidating around a widening split between high-performance structural grades for aerospace and automotive bonding and commodity water-based formulations serving packaging and construction. Henkel AG & Co. KGaA leverages its European formulation heritage to dominate engineered reactive acrylics for industrial assembly. Dow anchors North American supply through integrated acrylic monomer production and downstream adhesive manufacturing. Sika AG specializes in construction-grade structural acrylics, competing on building code certifications and applicator channel control.
Acrylic adhesives are thermoplastic or thermosetting polymers formulated from acrylic monomers that cure through solvent evaporation, moisture exposure, UV radiation, or anaerobic reaction to form durable bonds across metals, plastics, and composites. Their glass transition temperatures typically range from -40°C to 150°C, determining flexibility and load-bearing capacity in bonded joints. Pressure sensitive acrylics lead volume consumption due to their dominance in tapes and labels, though UV-curable acrylics represent the fastest-growing technology segment as electronics assemblers seek instant curing without thermal damage to sensitive components. Water-based technology occupies the mature core of construction and packaging applications, where cost efficiency outweighs performance premiums.
EPA VOC regulations and REACH chemical restrictions are forcing reformulation of solvent-based acrylics, redirecting R&D investment toward water-based and radiation-curing platforms. ECHA substance evaluations and FDA indirect food contact rules further constrain monomer selection, raising compliance barriers for new entrants. OEM procurement teams and adhesive formulators must monitor evolving chemical hazard classifications across EPA, ECHA, and China's MEE to anticipate raw material discontinuations and qualification requirements.
Market Dynamics
The Global Acrylic Adhesives Market is bifurcating sharply between high-performance structural formulations demanded by automotive lightweighting programs and commodity water-based grades serving packaging consolidation. This split is compressing mid-tier product margins while rewarding specialized formulators with certified aerospace and EV battery assembly qualifications.
Growth Catalysts
- REACH chemical restrictions:European ECHA substance evaluations are phasing out legacy solvent-based monomers, redirecting formulation investment toward compliant water-based and UV-curable platforms that command performance premiums in medical device and food-contact applications.
- Automotive lightweighting:Bonded aluminum-intensive vehicle architectures in Germany and Japan are displacing mechanical fastening with structural acrylics rated for crash-load transfer and galvanic corrosion resistance.
- Electronics cluster concentration:Pressure-sensitive acrylic tape demand concentrates in China's Shenzhen-Dongguan corridor, where display lamination and battery pack assembly lines consume rolls at industrial scale.
Market Restraints
- Acrylic monomer supply concentration:Integrated petrochemical producers in the US Gulf Coast and Northeast Asia control bulk methyl methacrylate supply, exposing formulators to feedstock volatility and force majeure disruptions.
- Technical performance ceiling:Acrylics remain thermally limited compared to epoxy and polyurethane alternatives, constraining adoption in underhood automotive and aerospace engine-zone applications above 150°C continuous service.
- Substitution by silicone pressure sensitives:High-temperature electronics and healthcare applications are migrating to silicone PSA tapes where acrylic thermal stability proves inadequate.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone and component assembly are creating greenfield demand for clean-room-grade acrylic tapes in Noida and Sriperumbudur production zones.
- UV-LED curing convergence:Instant-cure acrylic formulations compatible with 395nm LED arrays are enabling high-speed electronics bonding without thermal damage to OLED displays and flexible PCBs.
- Construction adhesive certification:Building code recognition of structural acrylics for curtain wall and cladding attachment in seismic zones opens specification-driven replacement of mechanical anchors.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in radical polymerization kinetics and adhesion science is retiring faster than universities replenish talent pipelines, lengthening R&D cycle times for new product qualification.
- Multi-regulatory qualification burden:Simultaneous EPA VOC, ECHA SVHC, and FDA indirect food contact approvals require 18-36 month validation timelines that delay commercialization of reformulated portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Adhesives Market |
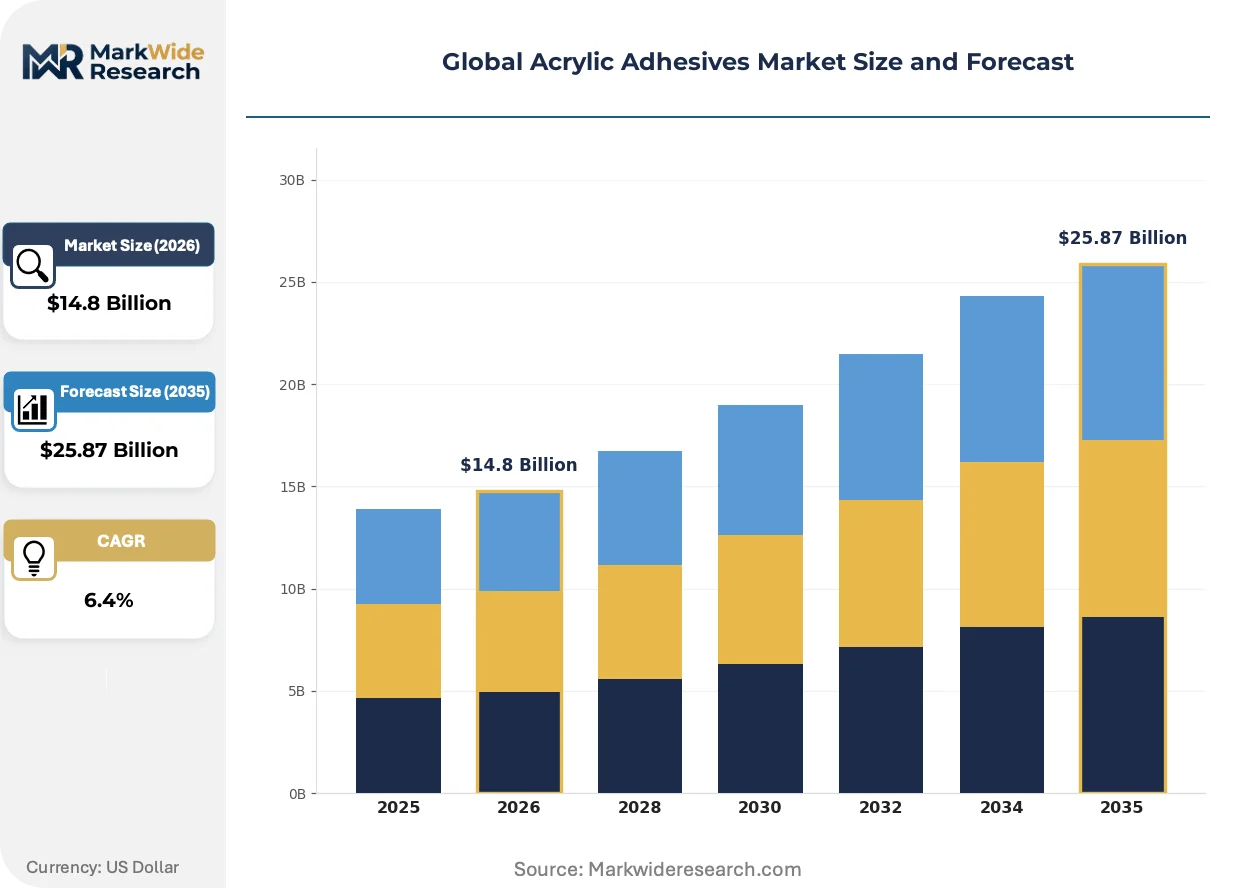
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Acrylics, Reactive Acrylics, Pressure Sensitive Acrylics, UV-Curable Acrylics Technology: Solvent-Based, Water-Based, Hot Melt, 100% Solid, Radiation Curing Application: Construction Bonding, Electronics Assembly, Packaging Sealing, Aerospace Bonding, Footwear Manufacturing End User: OEMs, Aftermarket Suppliers, Aircraft Manufacturers, Electronics Assemblers, Footwear Producers |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Avery Dennison Corporation, H.B. Fuller Company, Sika AG, BASF, Dow, Arkema, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Adhesives Market Shifts & Advancements
Acrylic adhesive technology is converging around instant-cure platforms and bio-based monomer feedstocks that reduce regulatory exposure while meeting performance thresholds previously reserved for petrochemical formulations. Formulators are racing to qualify these advances across automotive, electronics, and medical device verticals before compliance deadlines force portfolio obsolescence.
UV-LED curable acrylic systems are automating high-speed assembly lines in electronics manufacturing by eliminating thermal curing ovens and enabling inline quality inspection. Smartphone and tablet assemblers in Korea and Taiwan are retrofitting bonding stations with 395nm LED arrays that cure structural acrylics in under five seconds. This automation is compressing production cycle times from minutes to seconds while reducing factory energy consumption and footprint.
EPA VOC regulations and evolving state-level air quality mandates in California and Texas are forcing solvent-based acrylic formulators to accelerate water-based platform development or exit industrial coating applications. The industrial maintenance and transportation coatings segments are absorbing the highest compliance costs as legacy products lose market access. Formulators with qualified low-VOC alternatives are capturing specification-driven replacement volumes in marine and rail OEM accounts.
Electronics OEM procurement teams are consolidating adhesive supplier bases from multi-source commodity purchasing to single-source strategic partnerships with integrated formulation and tape-converting capabilities. This consolidation is displacing independent distributors in favor of direct technical service relationships with Henkel, Dow, and 3M. The shift is most visible in Korea's Samsung and LG supply chains, where supplier reduction programs have halved qualified adhesive vendors since 2020.
Global Acrylic Adhesives Market Segmentation
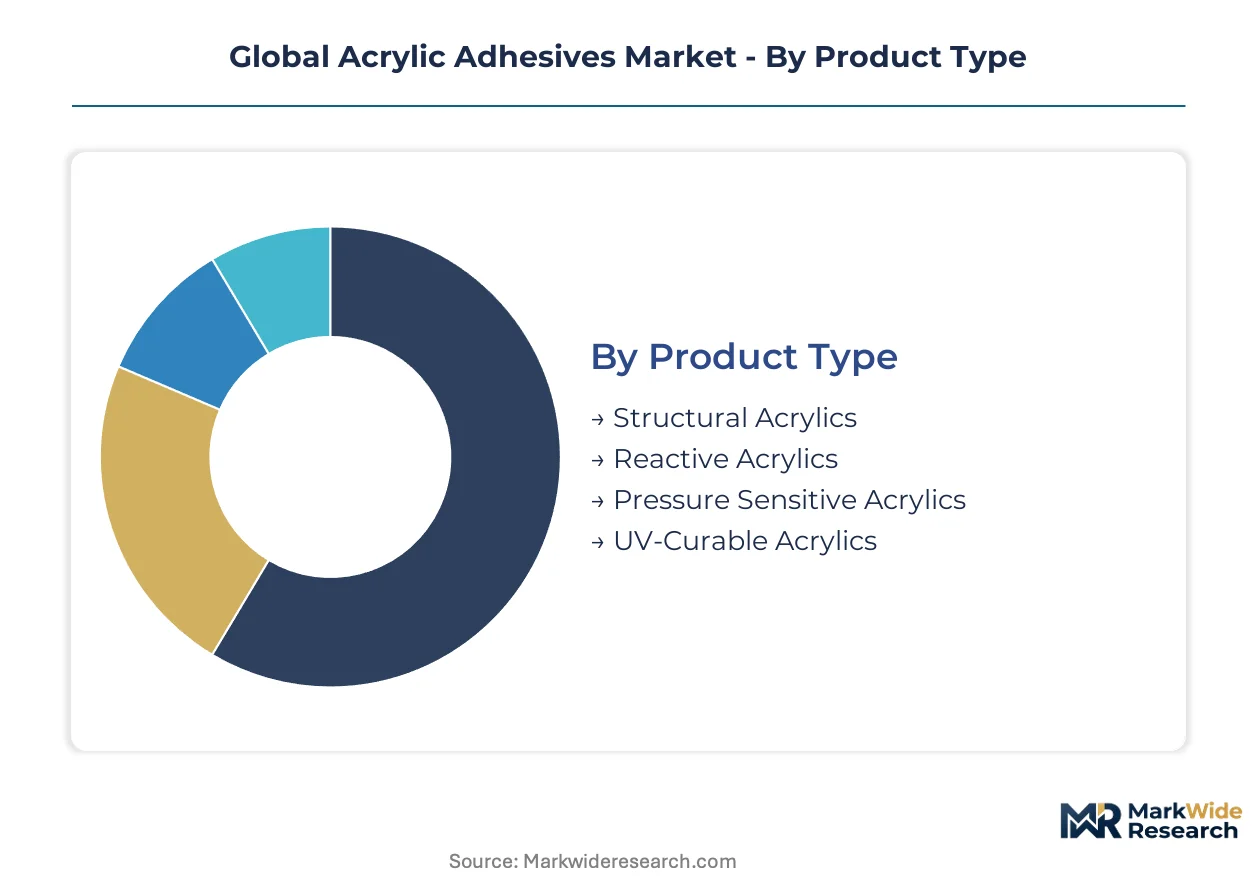
Acrylic adhesive buyers navigate a fragmented specification landscape where structural grades command aerospace premiums and commodity water-based formulations compete on bulk volume. Segmentation strategy determines whether formulators capture certified OEM supply chains or distribute through construction retail channels.
Product Type:
Customization intensity varies sharply across this category, from engineered reactive systems requiring radical polymerization expertise to standardized pressure-sensitive tapes produced at commodity scale.
- Structural Acrylics:Two-part formulations cure through anaerobic or moisture-triggered mechanisms to achieve load-bearing bonds on aluminum and composite substrates. Demand concentrates in German and Japanese automotive lightweighting programs where bonded chassis assemblies displace spot welding.
- UV-Curable Acrylics:Photoinitiator-loaded oligomers polymerize instantly under 395nm LED arrays, eliminating thermal damage to OLED displays and flexible circuits. Shenzhen-Dongguan electronics clusters consume rolls at industrial scale for smartphone lamination and battery pack assembly.
- Reactive Acrylics:Engineered systems for industrial assembly requiring precise mix ratios and controlled cure kinetics.
- Pressure Sensitive Acrylics:Tackified thermoplastic formulations dominating tape and label applications through room-temperature bonding.
Leading the category by volume: Pressure Sensitive Acrylics. Growing fastest: UV-Curable Acrylics.
Technology:
Cost tier stratification separates premium radiation-curing platforms from mature water-based systems competing on raw material efficiency.
- Solvent-Based:Legacy formulations delivering aggressive tack and rapid set on low-surface-energy substrates face regulatory phase-out under EPA VOC rules and REACH chemical restrictions. Reformulation timelines stretch 18-36 months for compliant alternatives.
- Water-Based:Emulsion polymers displace solvent systems in construction and packaging where cost efficiency outweighs performance premiums. Mature production infrastructure across US Gulf Coast and Northeast Asia monomer supply clusters supports volume scale.
- Hot Melt:Thermoplastic block copolymers applied molten for instant green strength in packaging consolidation.
- 100% Solid:Reactive systems with zero volatile content serving aerospace and medical device bonding.
- Radiation Curing:UV and electron-beam platforms enabling inline curing without thermal ovens.
Highest margin capture: Radiation Curing. Steepest volume trajectory: Water-Based.
Application:
Application concentration tracks end-use certification requirements, from building code compliance in construction to FAA airworthiness standards in aerospace.
- Electronics Assembly:Clean-room-grade pressure-sensitive tapes bond display stacks and battery cells in Korea's Samsung and LG supply chains. Supplier consolidation programs have halved qualified adhesive vendors since 2020.
- Construction Bonding:Structural acrylics achieve curtain wall and cladding attachment certification in seismic zones, displacing mechanical anchors. Sika and Henkel compete on applicator channel control and building code recognition.
- Packaging Sealing:Water-based and hot melt systems serve high-speed carton sealing and flexible film lamination.
- Aerospace Bonding:Qualified structural grades meet FAA and EASA airworthiness standards for interior and secondary structural applications.
- Footwear Manufacturing:Solvent-free formulations bond sole units and upper materials in Vietnam and Indonesia production zones.
Fastest specification-driven growth: Electronics Assembly. Mature volume anchor: Packaging Sealing.
End User:
Customer type determines procurement modality, from strategic partnerships with integrated formulators to spot purchasing through distribution.
- Electronics Assemblers:Korea's Samsung and LG procurement teams consolidate supplier bases toward direct technical service relationships with Henkel, Dow, and 3M. Clean-room qualification requirements favor integrated formulation and tape-converting capabilities.
- OEMs:Automotive and industrial equipment manufacturers specify structural acrylics for bonded aluminum-intensive architectures, requiring crash-load transfer certification and galvanic corrosion resistance validation.
- Aftermarket Suppliers:Distributors serving repair and maintenance channels with standardized product portfolios.
- Aircraft Manufacturers:Boeing and Airbus tier suppliers qualify adhesives to FAA and EASA material specifications.
- Footwear Producers:Nike, Adidas, and regional brands source bonding systems through Asia-Pacific chemical distributors.
Most concentrated procurement power: Electronics Assemblers. Highest qualification barriers: Aircraft Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan anchor acrylic adhesive demand through China's electronics manufacturing corridor, where display lamination and battery assembly lines consume pressure-sensitive tapes at industrial scale. German automotive lightweighting programs and Japanese bonded aluminum architectures pull structural formulations into OEM supply chains. Regulatory divergence across EPA, ECHA, and China's MEE creates compliance complexity for multinational formulators.
United States
EPA VOC regulations and state-level air quality mandates in California and Texas force solvent-based acrylic formulators toward water-based platform development. The industrial maintenance and transportation coatings segments absorb highest compliance costs as legacy products lose market access. Formulators with qualified low-VOC alternatives capture specification-driven replacement volumes in marine and rail OEM accounts concentrated along the Gulf Coast petrochemical corridor.
Germany
Automotive lightweighting programs at BMW, Mercedes-Benz, and Volkswagen displace mechanical fastening with structural acrylics rated for crash-load transfer. REACH compliance through ECHA substance evaluations phases out legacy monomers, redirecting R&D investment toward compliant alternatives. The Stuttgart and Munich manufacturing belts concentrate bonded aluminum-intensive vehicle architecture development.
China
Electronics OEM procurement teams in Korea's Samsung and LG supply chains consolidate adhesive vendors toward direct technical service relationships with integrated formulators. China's MEE chemical hazard classifications constrain monomer selection, raising qualification barriers. The Shenzhen-Dongguan corridor consumes clean-room-grade pressure-sensitive acrylic tapes for smartphone lamination and EV battery pack assembly.
Japan
Bonded aluminum-intensive vehicle architectures at Toyota, Honda, and Nissan pull high-performance structural acrylics into assembly lines. METI industrial standards and chemical substance regulations under CSCL drive reformulation toward low-VOC and UV-curable platforms. The Nagoya and Tokyo manufacturing clusters concentrate automotive adhesive qualification and specification development.
South Korea
Samsung and LG procurement consolidation programs have halved qualified adhesive vendors since 2020, favoring integrated formulation and tape-converting capabilities. MFDS medical device regulations and K-Battery certification requirements constrain supplier selection for healthcare and EV applications. The Seoul Capital Area and Busan-Ulsan industrial zones concentrate electronics assembly and battery manufacturing adhesive demand.
Global Acrylic Adhesives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and application complexity, with aerospace-qualified structural grades commanding multiples over packaging water-based formulations. The vendor base stratifies into three tiers: integrated petrochemical giants with captive monomer supply, specialized adhesive formulators with OEM qualification depth, and regional tape converters serving distribution channels. Dominant competitive moves include strategic partnerships with electronics OEMs for clean-room qualification and geographic expansion into India's PLI-subsidized manufacturing zones.
Among diversified chemical conglomerates, 3M, Henkel AG & Co. KGaA, and Dow occupy positions that exemplify different archetype strategies. 3M represents the integrated materials science platform with downstream tape-converting capabilities. Henkel AG & Co. KGaA anchors the European formulation heritage vector through engineered reactive systems. Dow sits within the petrochemical integration tier through captive acrylic monomer production and downstream adhesive manufacturing.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Sika AG |
| BASF |
| Dow |
| Arkema |
| Illinois Tool Works Inc. |
| Others |
Supply & Pricing Matrix
Methyl methacrylate monomer costs cascade through acrylic adhesive pricing tiers, with integrated producers on the US Gulf Coast and in Northeast Asia capturing margin premiums while independent formulators absorb feedstock volatility. Spot market exposure to force majeure disruptions concentrates pricing power among backward-integrated players, compressing margins for commodity water-based grades while structural aerospace and automotive formulations retain value-based premiums.
Pricing Analysis
Yield-guaranteed throughput pricing anchors structural acrylic contracts in automotive and aerospace verticals, where OEM qualification barriers protect premium tiers. Certification grade and volume scale drive price differentiation, with FDA-compliant medical device formulations and EASA-qualified aerospace grades commanding substantial premiums over construction-grade alternatives. Cost compression in water-based packaging segments is intensifying because Asian emulsion producers are scaling capacity, while electronics assemblers show least price sensitivity due to clean-room qualification lock-in.
Supply Chain Analysis
Recirculation of spent solvent and monomer recovery streams from adhesive manufacturing feeds back into virgin feedstock pools, though limited reverse-logistics infrastructure constrains circularity economics. Production concentrates in the United States, China, and Germany, with captive methyl methacrylate supply resting on naphtha-cracking and acetone-cyanohydrin routes. Single-source vulnerability from hurricane exposure on the US Gulf Coast threatens feedstock security. Distribution runs through direct technical service relationships for qualified OEM accounts and regional chemical distributors for construction and packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic adhesive markets are consolidating around captive monomer supply and downstream tape-converting integration, with qualification depth replacing commodity scale as the decisive competitive moat.
For Market Incumbents: Anticipate silicone PSA substitution in high-temperature electronics by accelerating UV-LED curing platform development and securing clean-room certifications ahead of Korean procurement consolidation waves. Prioritize backward integration into methyl methacrylate production or long-term offtake agreements with US Gulf Coast and Northeast Asian petrochemical complexes to defend margin structure against feedstock volatility. For New Entrants and Emerging Players: E-commerce-enabled technical distribution offers the lowest-friction entry path into India's PLI-subsidized electronics manufacturing zones, where qualified adhesive vendors remain scarce. Target Noida and Sriperumbudur production corridors with clean-room-grade pressure-sensitive tape formulations, leveraging direct technical service relationships to bypass entrenched distribution channels serving legacy automotive and construction segments. For Investors and Strategic Acquirers: ECHA substance evaluation announcements triggering legacy monomer phase-outs are the leading indicator that reformulation-capable specialists will command acquisition premiums. Position for five-to-ten year holding periods around mid-cap formulators with integrated tape-converting assets and dual EPA-REACH qualification pipelines, monitoring MEE chemical hazard classification updates for parallel regulatory tightening in China's electronics clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive methyl methacrylate production insulates margins from Gulf Coast force majeure disruptions. |
| UV-LED Curing Platform Qualification | 395nm-compatible formulations unlock Samsung and LG high-speed lamination line specifications. |
| Clean-Room Tape-Converting Capacity | In-house slitting and die-cutting capabilities satisfy electronics OEM single-source partnership requirements. |
| Multi-Regulatory Certification Pipeline | Simultaneous EPA, ECHA, and FDA tracks accelerate commercialization timelines for reformulated portfolios. |
| India Manufacturing Footprint Expansion | PLI scheme incentives in Noida and Sriperumbudur capture greenfield electronics assembly adhesive demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with adhesive formulators, automotive Tier 1 procurement leads, electronics OEM materials engineers, and construction applicator channel partners. Bottom-up triangulation combined production capacity databases, monomer trade flows, and qualified supplier registries with top-down validation against ACC and Cefic sector reports, SEC 10-K disclosures, and ECHA substance evaluation dockets.
Reconciliation of volume and value data streams across the projection horizon employed segmented modeling by technology platform, end-use industry, and regional production cluster. CAGRs derived from elasticity-adjusted demand curves incorporated automotive lightweighting penetration rates, electronics assembly line automation indices, and construction spending intensity by regulatory framework. Industry-specific inputs included UV-LED curing equipment installation counts, REACH SVHC list revision schedules, and India PLI scheme beneficiary rosters.
The model holds under stable petrochemical feedstock pricing and incremental regulatory phase-out timelines; deviation in force majeure frequency or accelerated ECHA restriction schedules would shift volume trajectories toward compliant technology platforms. Practitioners should monitor MEE chemical hazard classification updates and Korean supplier consolidation program announcements for early signals of qualification barrier elevation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Anaerobic Adhesives Market