
 Global Adhesive Coating Market | 2026-2036
Global Adhesive Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesive Coating Market Foresight
Aftermarket service revenue is fragmenting across adhesive coating value chains as OEMs internalize bonding-process expertise and reduce third-party maintenance reliance. Henkel AG & Co. KGaA leverages its European R&D footprint to sustain formulation leadership in high-performance automotive adhesives. H.B. Fuller Company anchors North American supply through controlled distribution networks for packaging-grade hot melts. BASF SE competes on polyurethane chemistry breadth across electronics and furniture end uses.
Adhesive coating comprises liquid or semi-liquid polymer formulations—typically acrylic, epoxy, or polyurethane resins dissolved or dispersed in water, solvent, or 100% solids systems—applied to substrates to create bonded joints or protective surface layers through mechanical interlocking, chemical crosslinking, or diffusion mechanisms. Water-based acrylics dominate packaging applications where FDA indirect food-contact compliance governs specification, while UV-curing epoxies command premium positioning in electronics assembly due to rapid line-speed compatibility and low-temperature substrate protection. Spray coating technology leads volume throughput in automotive Tier-1 operations, though roll coating sustains margin pools in furniture and textile lamination where film-thickness uniformity determines warranty performance.
EPA VOC emission limits and REACH substance restrictions are forcing solvent-based product reformulation across US and European manufacturing bases, while China's MEE enforcement tightens discharge permits for coating operations in the Yangtze and Pearl River deltas. FDA indirect food-contact standards and ECHA SVHC candidate list updates create dual compliance burdens for packaging adhesive suppliers serving multinational brand owners. Stakeholders must monitor regulatory divergence between major economies to avoid stranded formulation investments and secure cross-border qualification pathways.
Market Dynamics
Automotive lightweighting mandates and electronics miniaturization are compressing cure-cycle requirements, forcing adhesive suppliers to reconcile speed with bond durability across divergent substrate portfolios.
Growth Catalysts
- EPA VOC Phase-III Limits:US manufacturers face stricter emission ceilings for solvent-borne coatings, accelerating water-based acrylic transitions in packaging lines serving food-contact applications.
- EV Battery Pack Assembly:Thermal interface materials and structural bonding films are penetrating electric vehicle platforms as cell-to-pack architectures proliferate across German and Chinese OEM supply chains.
- UV-LED Curing Hardware:Semiconductor lamp efficiency gains are collapsing energy costs per bonded unit, enabling electronics assemblers in South Korea and Taiwan to retrofit legacy conveyor systems.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and isocyanate precursor costs swing with naphtha cracking margins, compressing formulation economics for mid-tier suppliers lacking backward integration into basic chemicals.
- MEE Discharge Permitting:China's Ministry of Ecology and Environment has frozen new coating operation licenses in the Yangtze River Delta, capping regional capacity expansion for water-based adhesive producers.
- Mechanical Fastener Substitution:Snap-fit polymer joints and laser welding are displacing adhesive bonds in automotive interior trim where reworkability and end-of-life disassembly carry regulatory weight.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for mobile device and component manufacturing are drawing adhesive coating investments toward Gujarat and Tamil Nadu assembly corridors.
- Bio-Based Polyurethane Feedstocks:Castor oil-derived polyols and lignin-modified epoxies are qualifying for EU Green Deal procurement preferences in furniture and construction applications.
- Direct-to-Converter Digital Platforms:Specialty adhesive distributors are bypassing regional stockists to serve mid-size packaging converters through specification tools and just-in-time replenishment algorithms.
Industry Challenges
- Formulation Chemist Scarcity:Cross-disciplinary expertise spanning polymer rheology, surface science, and regulatory toxicology is concentrating at multinational R&D centers, leaving regional compounders dependent on external technical service.
- Dual-Compliance Certification Burden:Suppliers serving multinational brand owners must simultaneously maintain FDA indirect food-contact dossiers and ECHA SVHC monitoring systems, extending product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesive Coating Market |
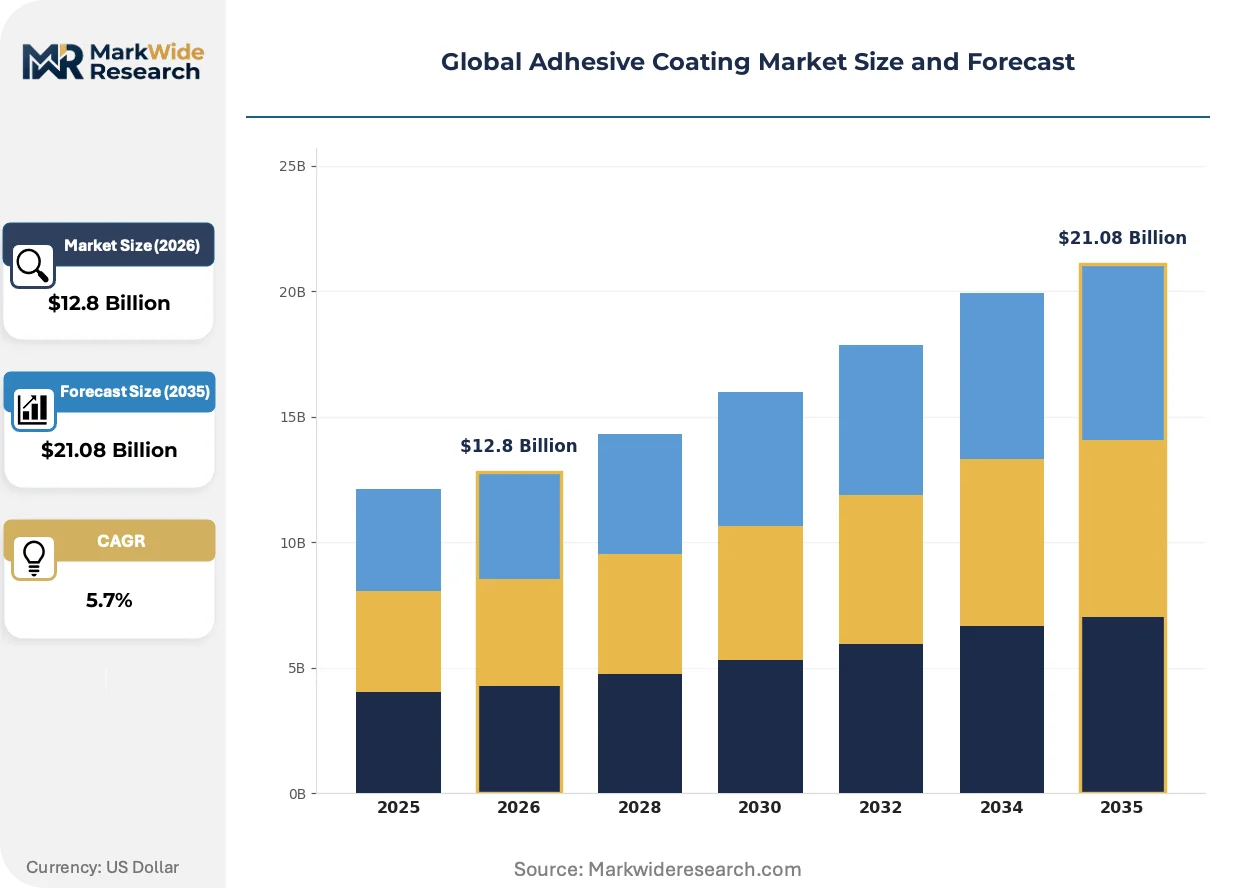
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, UV Curing, Epoxy, Acrylic Application: Packaging, Electronics Assembly, Woodworking, Automotive Tier-1 Suppliers, Textiles, Aerospace Technology: Spray Coating, Roll Coating, Curtain Coating, Dip Coating, Brush Coating, Electrostatic Coating End User: Electronics Manufacturers, Furniture Producers, Aircraft Assemblers, Footwear Makers, Household Goods |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Sika AG, Avery Dennison Corporation, Dow Inc., Arkema Group, BASF SE, Bostik SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesive Coating Market Shifts & Advancements
Formulation chemistry, curing hardware, and procurement interfaces are converging to redefine value capture in adhesive coating supply chains.
UV-LED curable epoxy acrylates are collapsing thermal exposure requirements for temperature-sensitive substrates. Electronics contract manufacturers in Mexico and Vietnam are adopting these systems to bond flexible printed circuit boards without warping polyimide films. The technology is collapsing the traditional trade-off between line speed and substrate protection that constrained solvent-borne thermal cure processes.
REACH Annex XIV authorization requirements are forcing substitution planning for diisocyanate-based polyurethane precursors. European automotive seating and footwear suppliers must document safer alternatives or secure time-limited authorizations, redirecting R&D spending toward silane-terminated polymer and waterborne polyurethane dispersion platforms. Germany's KBA and France's ANSES are coordinating enforcement timelines, creating compliance predictability for formulation investments.
Converter procurement teams are consolidating specification authority previously dispersed across plant-level engineers. North American packaging groups now centralize adhesive qualification through corporate sustainability offices, prioritizing suppliers with verified Scope 3 emissions data and closed-loop solvent recovery programs. This behavioral shift is visible most acutely in California and New York State where extended producer responsibility frameworks for flexible packaging are advancing through legislative committees.
Global Adhesive Coating Market Segmentation
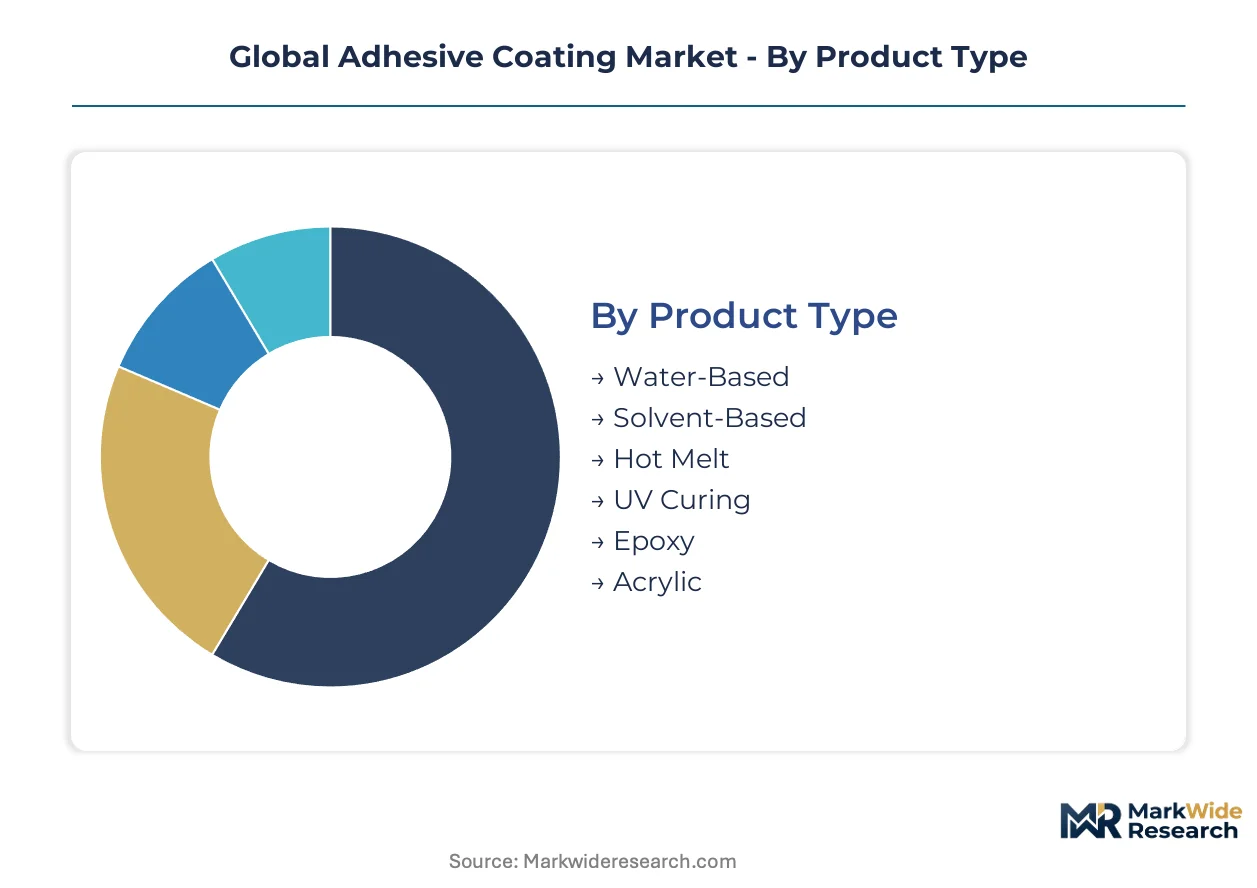
Segmentation reveals how adhesive coating procurement priorities diverge across formulation chemistries, application stresses, and assembly line configurations. Suppliers must align technical service intensity with the specific bonding challenges each segment presents.
Product Type:
After-sales service intensity varies sharply across formulation platforms, with reactive systems demanding field-level technical support while stable emulsions require minimal intervention.
- Water-Based:Acrylic and polyurethane dispersions in aqueous carriers serve food-contact packaging where FDA compliance governs migration limits. Demand concentrates in US and German folding carton operations as brand owners eliminate solvent residues from supply chains.
- Solvent-Based:These high-solids formulations penetrate difficult substrates in automotive interior lamination, though EPA VOC Phase-III limits are forcing reformulation investments across Ohio and Michigan assembly corridors.
- Hot Melt:Thermoplastic EVA and polyolefin systems dominate high-speed carton sealing.
- UV Curing:Photoinitiator-acrylate systems enable electronics bonding at line speeds exceeding thermal cure limits.
- Epoxy:Two-part systems anchor structural assemblies in aerospace primary structures.
- Acrylic:Pressure-sensitive variants serve label stock and medical tape applications.
Water-Based holds the largest share; momentum sits with UV Curing as LED hardware costs collapse.
Application:
Cost tier segmentation separates commodity bonding from specification-driven procurement where qualification timelines stretch across multiple OEM approval cycles.
- Packaging:Folding carton and corrugated case sealing consumes volume tonnage at thin-film economics. German and US beverage converters are consolidating adhesive specifications through corporate sustainability offices prioritizing Scope 3 verification.
- Electronics Assembly:Die attach, underfill, and display lamination demand precision rheology control. Taiwan and South Korean contract manufacturers are retrofitting lines with UV-LED curing to protect temperature-sensitive flexible circuits.
- Woodworking:Edgebanding and veneer pressing rely on hot melt and PVAc systems.
- Automotive Tier-1 Suppliers:Structural bonding films and NVH damping materials penetrate lightweight vehicle platforms.
- Textiles:Lamination adhesives bond technical fabrics for protective apparel.
- Aerospace:Film adhesives and paste systems serve primary and secondary structure bonding.
Packaging commands volume leadership; Electronics Assembly climbs fastest on miniaturization trends.
Technology:
Application method selection directly determines capital intensity, coating uniformity, and substrate compatibility across divergent manufacturing footprints.
- Spray Coating:Atomized delivery achieves complex geometries in automotive underbody and aerospace component finishing. Tier-1 suppliers in Stuttgart and Shanghai favor robotic spray cells for throughput consistency.
- Roll Coating:Metered nip systems deliver precise film weights in furniture veneer and textile lamination. Italian and North Carolina manufacturers sustain margin pools where thickness uniformity determines warranty exposure.
- Curtain Coating:Free-falling film coats flat panel stock in woodworking operations.
- Dip Coating:Immersion systems handle small parts and wire harness sealing.
- Brush Coating:Manual application persists in repair and specialty assembly.
- Electrostatic Coating:Charged particle deposition maximizes transfer efficiency in metal finishing.
Spray Coating dominates automotive throughput; Roll Coating sustains premium positioning in furniture.
End User:
Customer type segmentation separates multinational OEMs with centralized qualification authority from fragmented regional converters with plant-level purchasing autonomy.
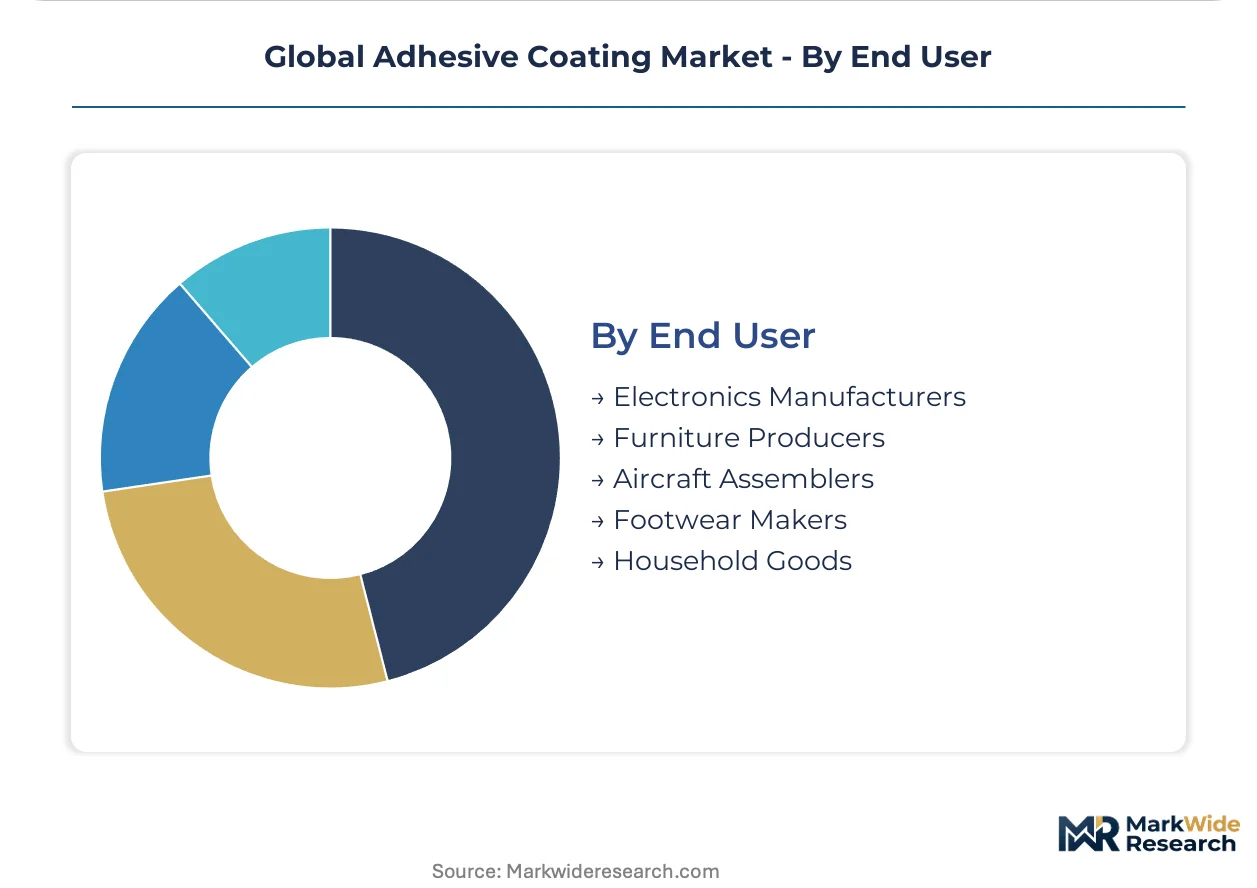
- Electronics Manufacturers:Contract assemblers and integrated device makers specify adhesives for thermal management and environmental protection. Vietnam and Mexico facilities are expanding procurement of UV-curable systems to meet consumer device volume ramps.
- Furniture Producers:Panel processors and upholstery manufacturers prioritize hot melt and waterborne systems. Poland and Vietnam export hubs are adopting bio-based polyurethane feedstocks to satisfy EU Green Deal procurement preferences.
- Aircraft Assemblers:OEMs and tier suppliers qualify structural film adhesives under FAA and EASA certification protocols.
- Footwear Makers:Upper lamination and sole attachment drive solventborne and waterborne consumption.
- Household Goods:Appliance and consumer product assembly uses pressure-sensitive and hot melt formats.
Electronics Manufacturers represent the most concentrated demand base; Furniture Producers are expanding most quickly on reshoring investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes adhesive coatings primarily for electronics assembly and EV battery bonding, whereas Germany and the United States concentrate procurement in automotive lightweighting and food-contact packaging respectively. This consumption-mix differential shapes formulation chemistry preferences and regulatory compliance investments across manufacturing bases.
China
EV battery pack assembly and consumer electronics contract manufacturing dominate adhesive coating procurement in the Yangtze River Delta. MEE discharge permitting restrictions have frozen new coating operation licenses in Jiangsu and Zhejiang provinces, redirecting capacity expansion toward inland provinces. Suzhou and Shenzhen clusters are retrofitting lines with water-based polyurethane systems to meet tightened environmental enforcement.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich are expanding structural bonding film procurement for lightweight vehicle platforms. REACH Annex XIV authorization timelines for diisocyanate precursors are forcing substitution planning across polyurethane formulation portfolios. The KBA coordinates enforcement with French ANSES, creating compliance predictability for R&D investments in silane-terminated polymer alternatives.
United States
Packaging converters in Ohio and Michigan are consolidating adhesive specifications through corporate sustainability offices prioritizing Scope 3 emissions verification. EPA VOC Phase-III limits are accelerating water-based acrylic transitions in food-contact folding carton operations. California and New York State legislative committees are advancing extended producer responsibility frameworks for flexible packaging.
India
Mobile device and component manufacturing incentives under the PLI scheme are drawing adhesive coating investments toward Gujarat and Tamil Nadu assembly corridors. BIS standards for electronics-grade adhesives are tightening qualification requirements for imported formulations. Ahmedabad and Chennai industrial zones are expanding UV-curable system adoption to meet export-quality specifications for consumer devices.
South Korea
Electronics contract manufacturers in Suwon and Gwangju are retrofitting legacy conveyor systems with UV-LED curing hardware to protect temperature-sensitive flexible circuits. MFDS oversight of industrial chemical safety is extending to adhesive formulation components used in medical device adjacent applications. The Seoul Capital Area remains the dominant procurement center for die attach and underfill materials serving semiconductor packaging.
Global Adhesive Coating Market Competitive Landscape
Capability concentration sits with European and North American multinationals commanding formulation chemistry breadth; scale advantage sits with Asian producers leveraging integrated petrochemical feedstock access. The market structure reflects a tiered hierarchy where global specialists compete on regulatory dossier depth against regional compounders competing on logistics proximity. Three archetypes dominate: integrated chemical conglomerates with backward control over resin precursors, specialty adhesive houses with concentrated R&D footprints, and diversified materials suppliers leveraging cross-selling into adjacent bonding applications. Competitive moves center on portfolio diversification into bio-based feedstocks and geographic expansion through controlled distribution networks.
Among German-based chemical conglomerates, Henkel AG & Co. KGaA and BASF SE exemplify the integrated archetype with European R&D footprints sustaining formulation leadership across multiple end-use verticals. H.B. Fuller Company represents the North American specialty house model, anchoring regional supply through distribution network control. These three occupy positions reflecting divergent strategic bets: European regulatory compliance depth versus North American packaging market penetration versus polyurethane chemistry breadth.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Sika AG |
| Avery Dennison Corporation |
| Dow Inc. |
| Arkema Group |
| BASF SE |
| Bostik SA |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta coating cluster in Jiangsu and Zhejiang provinces anchors global water-based adhesive capacity, and MEE discharge permit freezes there have concentrated pricing power with incumbents holding grandfathered environmental licenses. This supply bottleneck feeds downstream cost pass-through to packaging converters in Ohio and Michigan facing EPA VOC Phase-III compliance deadlines.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational OEMs and Tier-1 adhesive suppliers, insulating premium formulations from acrylic monomer spot volatility while exposing mid-tier compounders to naphtha-cracking margin swings. Price differentiation rests on FDA indirect food-contact certification tier and verified Scope 3 emissions data. Cost compression in standard-grade water-based acrylics is intensifying because Chinese MEE restrictions have capped regional capacity expansion. Brand-owning packaging groups exhibit lowest price sensitivity; commodity corrugated converters face acute margin pressure from feedstock pass-through.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electronics-grade UV-curable formulations. Manufacturing concentrates in China, Germany, and the United States, with formulation chemistry anchored in German R&D hubs and high-volume blending distributed across Chinese coastal provinces. Raw material dependencies center on acrylic monomers, isocyanate precursors, and photoinitiator packages sourced from integrated petrochemical complexes. Single-source vulnerability persists for silane-terminated polymer alternatives to REACH-restricted diisocyanates. Distribution runs through controlled technical service networks rather than commodity stockists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive coating procurement is shifting toward specification partnerships where formulation expertise and on-site technical service generate recurring revenue streams expanding faster than base chemical tonnage. This service-attach dynamic favors suppliers capable of embedding chemists directly into customer assembly lines.
For Market Incumbents: Entrench regulatory dossier depth as the primary defensive moat by accelerating REACH-compliant diisocyanate substitution programs and securing FDA indirect food-contact certifications ahead of brand-owner consolidation. Backward integration into acrylic monomer production in Texas and Louisiana mitigates naphtha volatility exposure threatening mid-tier competitors. Channel control through direct-to-converter digital platforms locks out regional stockists. For New Entrants and Emerging Players: Pursue bio-based polyurethane feedstock qualification for EU Green Deal procurement preferences in Polish and Vietnamese furniture export hubs. The most penetrable white space sits in UV-LED curable systems for Mexico and Vietnam electronics contract manufacturers retrofitting legacy thermal cure lines. A specification-led go-to-market partnering with LED hardware OEMs collapses customer adoption friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty adhesive houses with concentrated European R&D footprints over integrated chemical conglomerates facing petrochemical margin compression. Long-term viability across the projection horizon rests on regulatory compliance automation and bio-based feedstock transition execution. Acquisition targets should demonstrate closed-loop solvent recovery infrastructure and verified Scope 3 data systems. The signal to watch is MEE permitting relaxation in inland Chinese provinces redirecting capacity expansion geography.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply of feedstock insulates margin from naphtha cracking volatility in US Gulf Coast. |
| REACH-Compliant Diisocyanate Substitution Program | Silane-terminated polymer platforms secure authorization continuity for European automotive seating suppliers. |
| Direct-to-Converter Digital Platform Launch | Specification tools and just-in-time algorithms bypass regional stockists in North American packaging. |
| UV-LED Curing Hardware Partnership | System bundling with semiconductor lamp manufacturers accelerates electronics assembler retrofit adoption. |
| Bio-Based Polyurethane Feedstock Qualification | Castor oil-derived polyols unlock EU Green Deal procurement preferences in furniture and construction. |
Research Methodology
Cross-validation between primary interviews with adhesive formulators and secondary trade data anchors the qualitative findings in this study. Plant managers at coating operations, procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors at multinational chemical houses provided operational perspective. These sources were triangulated against customs records, ACC and Cefic industry reports, SEC 10-K filings, and EPA enforcement databases. Bottom-up volume estimates from individual production facilities were reconciled with top-down demand calculations across end-use segments.
Calibration against historical capacity utilization rates and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, application stress environment, curing technology platform, and regional manufacturing cluster. CAGRs were derived from slope analysis of normalized adoption curves adjusted for regulatory phase-in schedules. Industry-specific forecast inputs incorporated EV battery pack assembly ramp rates and UV-LED hardware cost decline trajectories.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, naphtha pricing spreads, or currency volatility in Asian manufacturing corridors would shift the trajectory. Forecasts reflect documented assumptions regarding MEE permitting continuity, REACH authorization timelines, and PLI scheme disbursement pacing in India. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives Market