
 North America Adhesives and Sealants Market | 2026-2036
North America Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Adhesives and Sealants Market Analysis
Aftermarket service revenue for adhesive application systems is rewriting how suppliers capture lifetime value from industrial accounts. H.B. Fuller Company leverages its direct service network to lock in recurring maintenance contracts across packaging lines. Henkel Corporation anchors its position through R&D intensity in reactive polyurethane platforms for automotive structural bonding. Dow competes on manufacturing scale, operating integrated silane and silicone precursor facilities along the US Gulf Coast.
Adhesives and sealants are polymeric formulations engineered to bond substrates or fill gaps through surface wetting, chemical curing, or physical setting, with viscosities ranging from thin liquids to paste-like consistencies depending on application method. They serve primary industrial purposes including structural load transfer, environmental sealing, thermal management, and aesthetic finishing across manufactured goods and built assets. Polyurethane formulations lead in automotive structural applications where crash-durability requirements command premium pricing, while water-based acrylics dominate packaging adhesives as converters phase out solvent-borne systems under EPA VOC limits. Reactive technologies represent the fastest-expanding technology category, driven by cure-on-demand processing advantages in electronics miniaturization and electric vehicle battery assembly.
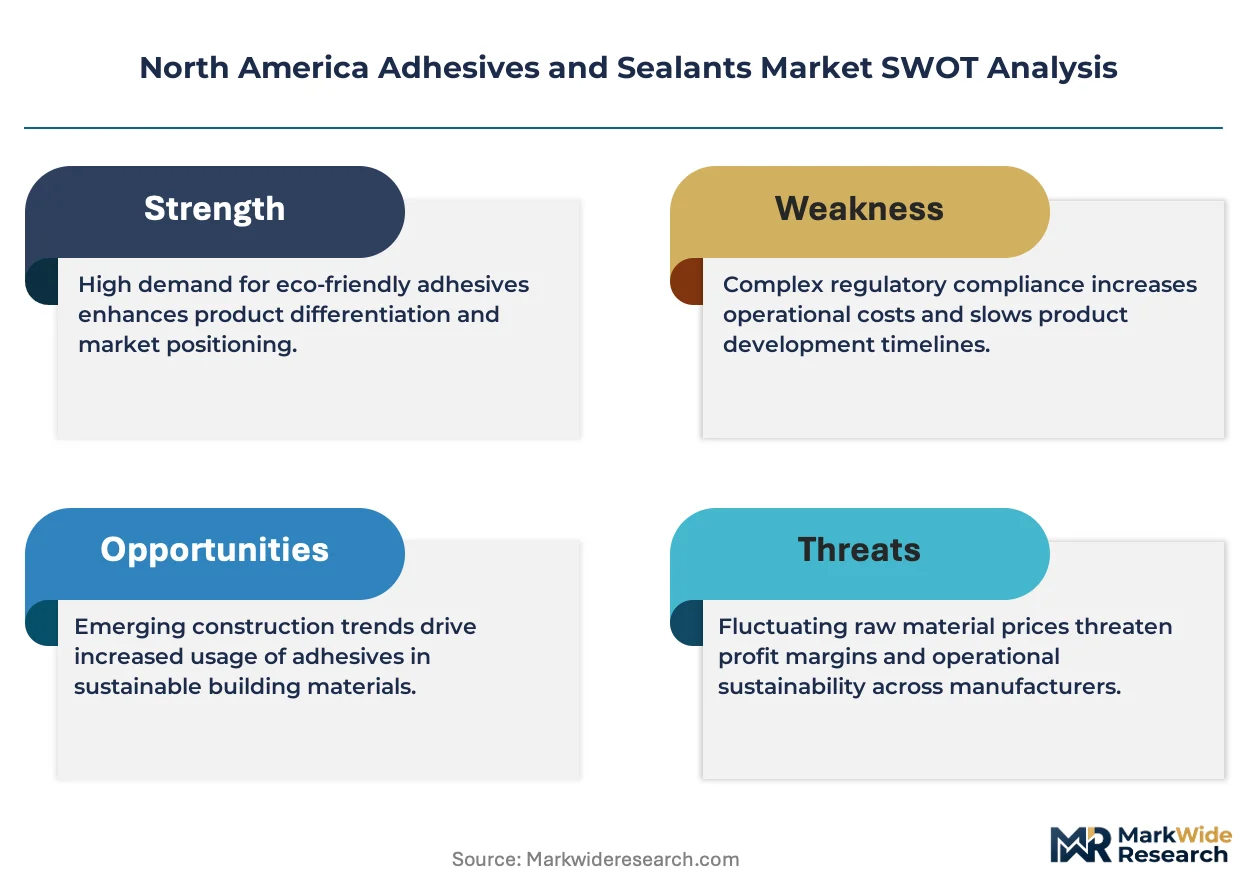
EPA VOC regulations, OSHA hazard communication standards, and California Air Resources Board (CARB) SCM-2007 limits collectively shape permissible solvent content, worker exposure thresholds, and product labeling requirements across US and Canadian manufacturing facilities. These frameworks elevate compliance costs for solvent-based formulations while accelerating capital redeployment into water-based and hot-melt production infrastructure. Stakeholders must monitor pending revisions to TSCA Section 6 chemical risk evaluations, as EPA prioritization of isocyanates and certain epoxy curing agents could force reformulation timelines that outpace existing R&D pipelines.
Market Dynamics
Automotive OEMs are systematically replacing mechanical fasteners with structural bonding across vehicle platforms, forcing formulation suppliers to reengineer crash-durable chemistries while retooling production assets for reactive polyurethane systems.
Growth Catalysts
- EPA VOC Phase-Out:Federal limits on solvent content in industrial coatings and adhesives are accelerating capital redeployment into water-based and hot-melt production infrastructure across US manufacturing facilities.
- Electric Vehicle Battery Assembly:Thermal management and structural bonding requirements in EV battery packs are pulling reactive cure-on-demand technologies into high-volume automotive lines.
- Ontario Manufacturing Belt:Concentrated automotive and packaging converter demand in Canada's industrial corridor is sustaining capacity utilization for regional adhesive formulators.
Market Restraints
- Isocyanate Feedstock Volatility:Polyurethane precursor costs fluctuate with benzene and propylene oxide pricing, compressing margin stability for structural adhesive producers.
- Gulf Coast Supply Concentration:Silane and silicone precursor manufacturing clusters along the Texas-Louisiana chemical corridor create geographic single-point vulnerability for silicone sealant supply.
- CARB SCM-2007 Compliance Friction:California's adhesive-specific volatile organic compound limits impose formulation complexity that smaller regional blenders struggle to absorb.
Strategic Opportunities
- US-Mexico Nearshoring:Automotive and appliance assembly migration to northern Mexico is generating greenfield demand for localized adhesive blending and technical service capabilities.
- Reactive Hot-Melt Convergence:Hybrid polyurethane-reactive hot-melt systems are opening packaging and assembly applications previously locked into conventional EVA or metallocene platforms.
- Infrastructure Resilience Mandates:Federal and state-level building code updates for seismic and climate resilience are expanding specification opportunities for high-performance construction sealants.
Industry Challenges
- Polymer Rheology Expertise Gap:Formulation chemistry programs at North American universities produce insufficient graduates trained in viscoelastic material design for industrial adhesive applications.
- Legacy Equipment Retrofit Complexity:Converters running solvent-borne application systems face capital-intensive transitions to accommodate water-based or reactive chemistries without line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Adhesives and Sealants Market |
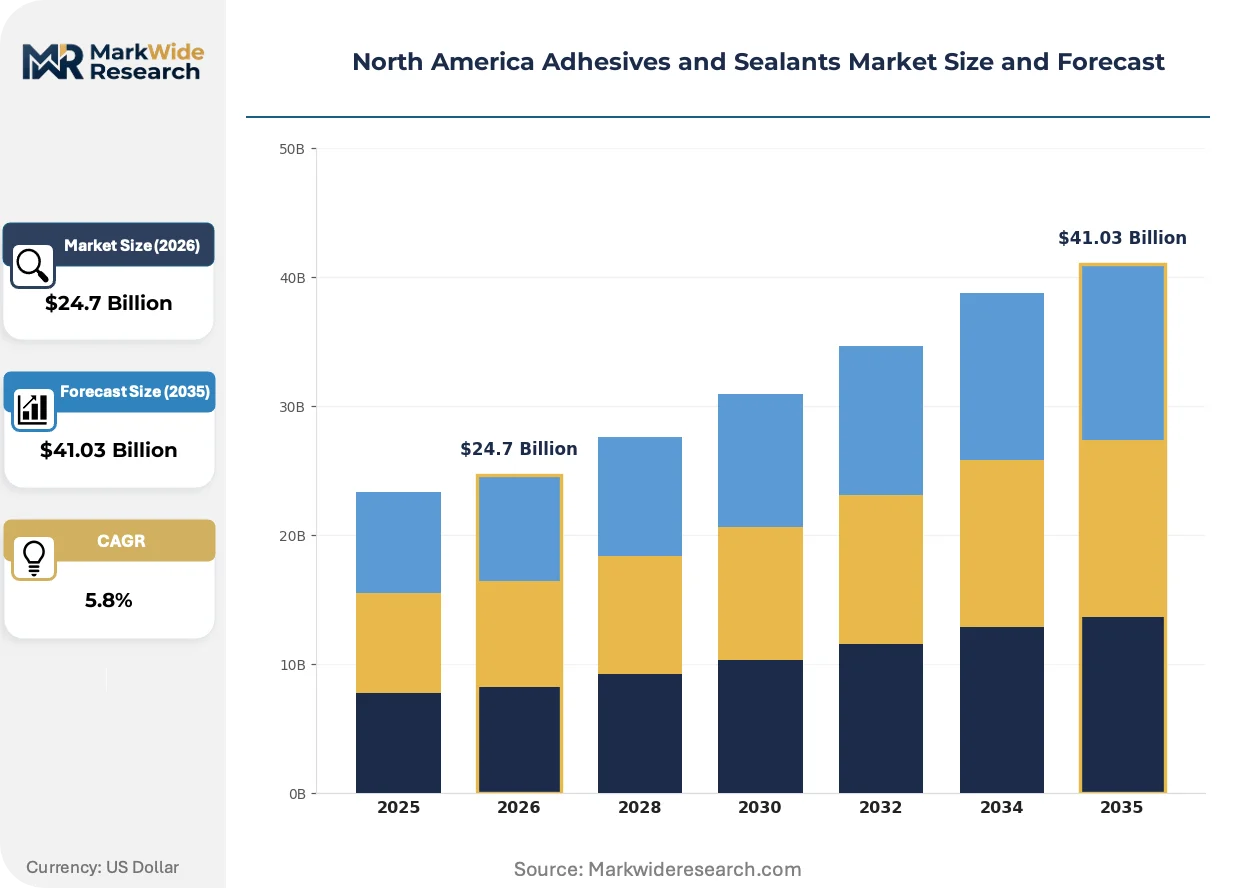
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Automotive, Construction, Electronics, Packaging End User: Manufacturers, Contractors, Retailers, Distributors Technology: Water-based, Solvent-based, Hot Melt, Reactive |
| Companies Covered | H.B. Fuller Company, Wacker Chemie AG, Henkel Corporation, RPM International Inc., Arkema, Sika AG, Dow, Evonik Industries, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Adhesives and Sealants Market Emerging Trajectories
Digital formulation platforms and predictive curing models are compressing R&D cycles while regulatory pressure on solvent content forces simultaneous reinvention of both chemistry and application equipment.
Reactive polyurethane hot-melt technology is virtualizing traditional solvent-borne assembly processes in automotive interior and electronics applications. Tier-1 seating and trim suppliers are adopting these systems at accelerated pace to eliminate drying ovens and reduce footprint. The technology is virtualizing capital allocation patterns, redirecting investment from emission-control infrastructure toward precision dispensing and inline monitoring equipment.
EPA prioritization of isocyanates under TSCA Section 6 chemical risk evaluations is forcing preemptive reformulation across structural adhesive portfolios. Industrial consequence includes accelerated screening of alternative curing chemistries and expanded toxicology documentation requirements. Automotive structural bonding applications are most affected, with formulators building contingency supply chains for non-isocyanate polyurethane platforms.
Converters are consolidating adhesive procurement through integrated supply contracts that bundle formulation, application equipment, and technical service. Packaging and automotive assembly operations are displacing transactional spot purchasing with multi-year partnerships anchored by line-efficiency guarantees. This pattern is most visible in the US Midwest and Ontario, where plant-level total cost of ownership calculations now dominate supplier selection over unit price.
North America Adhesives and Sealants Market Segmentation
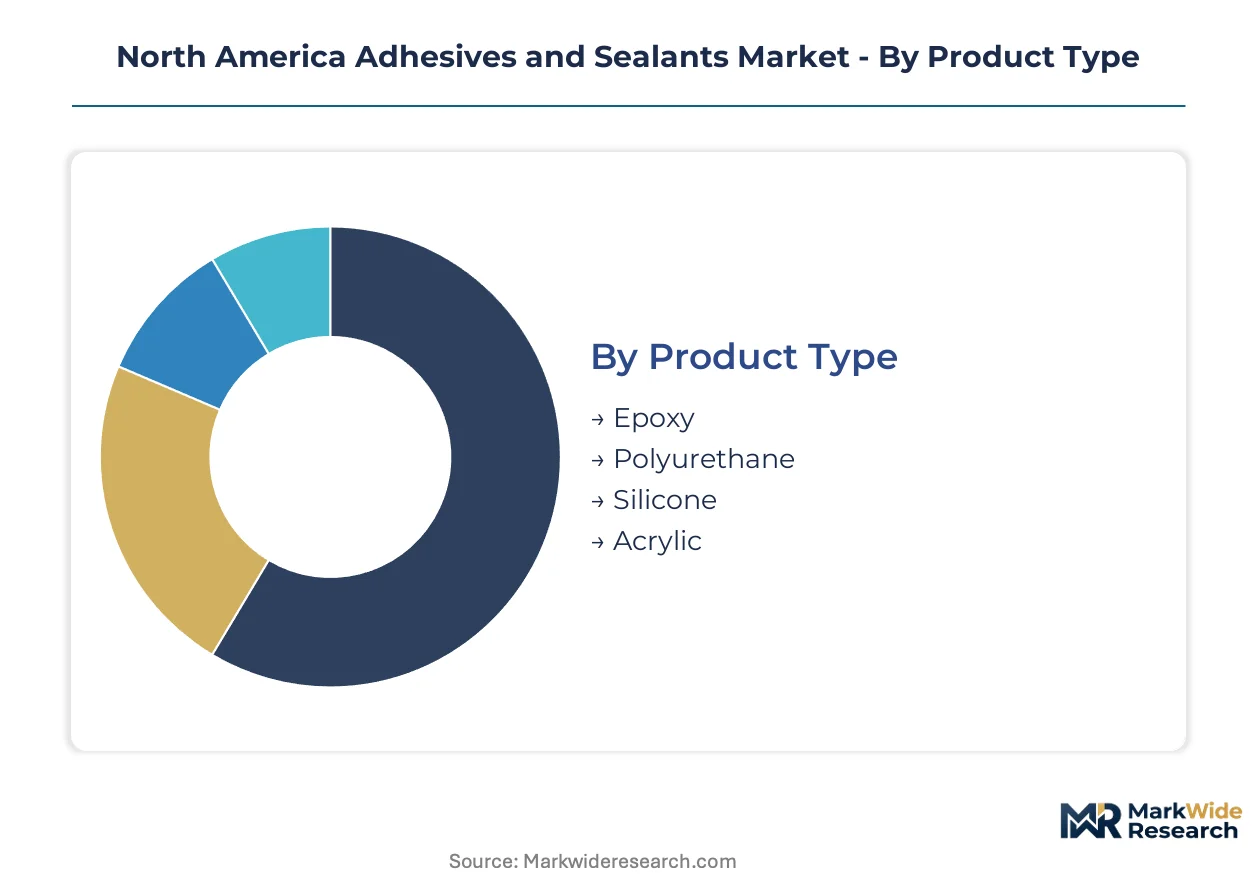
Adhesive and sealant procurement patterns diverge sharply across chemistry platforms, end-use specifications, and supply chain tiers. Each segmentation dimension reveals distinct margin structures, regulatory exposure profiles, and technical service intensity requirements that reshape supplier positioning across the US and Canada.
Product Type:
Polyurethane and silicone formulations command premium positioning in structural and environmental sealing applications, while epoxy and acrylic systems serve cost-sensitive assembly and coating markets.
- Polyurethane:Two-part and moisture-cure systems deliver crash-durable structural bonding with elongation properties exceeding 400%. Automotive OEMs in Michigan and Ontario specify these formulations for body-in-white assembly and battery pack thermal management where mechanical fastener replacement demands viscoelastic energy absorption.
- Silicone:Room-temperature-vulcanizing and heat-cured grades provide UV-stable, thermally conductive sealing across -55°C to 200°C operating windows. Gulf Coast petrochemical infrastructure and California solar installation codes sustain demand concentration for construction glazing and electrical potting applications.
- Epoxy:Rigid, high-modulus systems bond metal and composite substrates in aerospace tooling and industrial equipment repair.
- Acrylic:Water-borne and UV-cure variants serve pressure-sensitive tape and label markets with rapid green-strength development.
Established volume favors silicone; emerging adoption favors polyurethane.
Application:
End-use concentration determines formulation complexity, with automotive and electronics segments pulling reactive chemistries while construction and packaging sustain commodity-scale water-based consumption.
- Automotive:Structural bonding, interior trim assembly, and battery module encapsulation require crash-rated polyurethane and thermally conductive silicone platforms. EPA VOC limits and OEM lightweighting targets are displacing mechanical joining across vehicle platforms from Detroit to Puebla assembly corridors.
- Construction:Curtainwall glazing, concrete joint sealing, and waterproofing membranes specify silicone and hybrid polymer systems. California Title 24 energy codes and Florida hurricane resistance standards drive specification toward high-movement-capable sealants.
- Electronics:Miniaturized device assembly and PCB protection utilize low-outgassing silicone and epoxy underfill materials.
- Packaging:Folding carton and flexible film converting relies on hot-melt and water-based acrylic adhesives for high-speed line compatibility.
Construction maintains the largest installed base; automotive represents the steepest expansion trajectory.
End User:
Procurement authority concentrates differently across direct manufacturing integration versus distribution-mediated contractor supply, reshaping pricing structures and technical service bundling.
- Manufacturers:Tier-1 automotive seating suppliers and appliance OEMs negotiate multi-year formulation supply contracts with embedded application equipment and line-efficiency guarantees. These accounts demand just-in-time delivery and on-site technical support across Midwest and Ontario manufacturing belts.
- Contractors:Commercial glazing and industrial flooring installers purchase through distribution with specification-driven product selection. CARB SCM-2007 compliance documentation and OSHA hazard communication training requirements elevate preferred supplier relationships over spot purchasing.
- Retailers:Home improvement channels move consumer-grade caulks and construction adhesives with brand-driven shelf placement.
- Distributors:Industrial supply houses aggregate SKU breadth for MRO and small-batch manufacturing accounts.
Direct manufacturer relationships capture the highest lifetime value; distributor channels provide geographic reach into fragmented contractor markets.
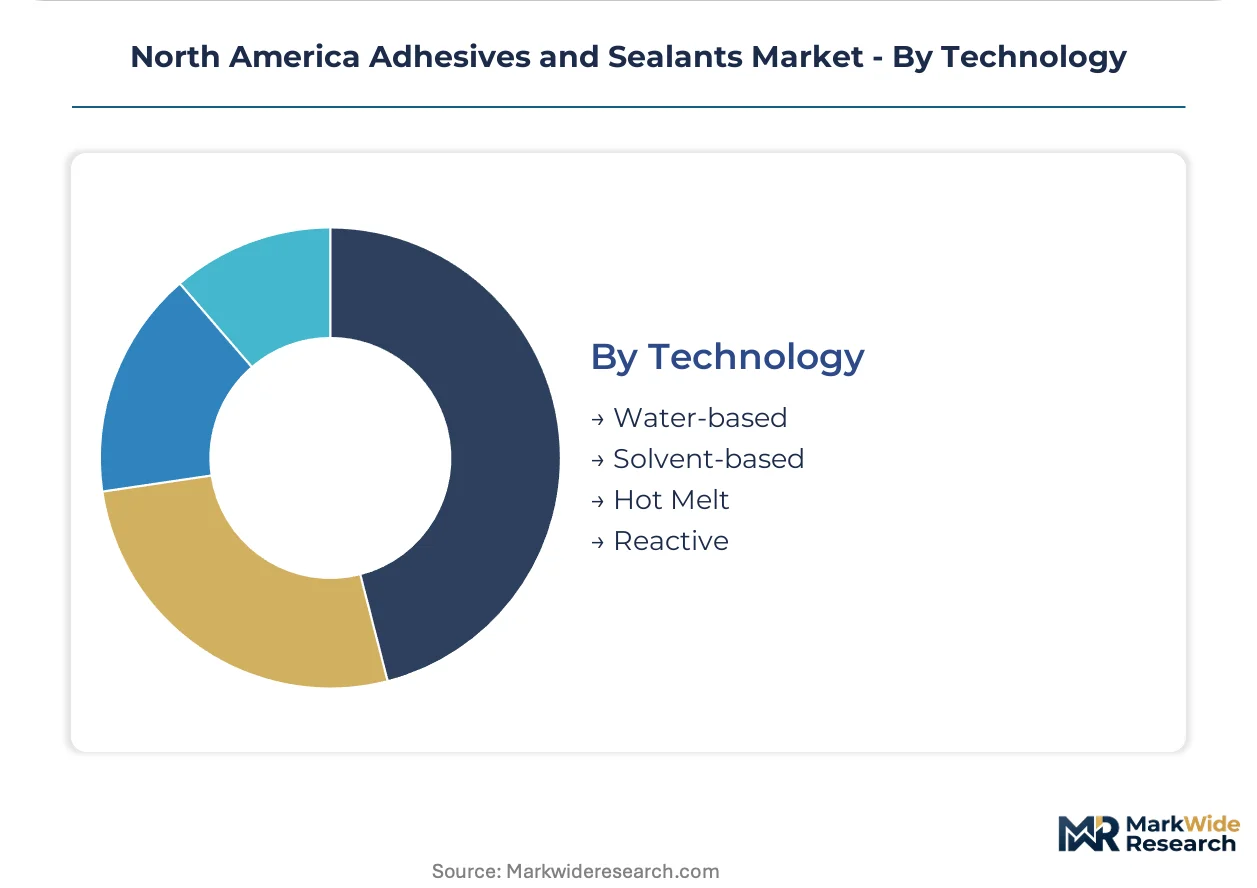
Technology:
Cure mechanism and carrier system selection determines capital equipment requirements, emission profiles, and processing throughput economics.
- Reactive:Moisture-cure and two-part systems polymerize through chemical crosslinking without solvent evaporation. These platforms are displacing solvent-borne assembly processes in automotive interior and EV battery applications where cure-on-demand processing eliminates drying ovens and reduces line footprint.
- Water-based:Acrylic and polyurethane dispersions serve packaging and wood assembly markets with low-VOC profiles compliant with EPA architectural coating regulations. Converters face capital-intensive retrofit complexity transitioning from solvent-borne application systems without production shutdowns.
- Hot Melt:EVA and metallocene polyolefin systems deliver instant green strength for high-speed packaging lines.
- Solvent-based:Remaining applications in specialty tape and membrane manufacturing face declining share under federal and state VOC phase-out schedules.
Water-based maintains dominant volume share; reactive platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in the US Midwest exhibit the highest price elasticity, squeezing margins on commodity water-based acrylics, while automotive OEMs in Ontario and northern Mexico absorb premium pricing for crash-rated structural bonding systems with minimal volume attrition.
United States
EPA VOC regulations and California CARB SCM-2007 limits are accelerating formulation shifts from solvent-borne to water-based and reactive chemistries. The US Gulf Coast petrochemical corridor from Houston to Baton Rouge hosts integrated silane and silicone precursor manufacturing. Michigan's automotive assembly belt is systematically replacing mechanical fasteners with structural polyurethane bonding across vehicle platforms.
Canada
Ontario's manufacturing belt concentrates automotive OEM demand and packaging converter activity, sustaining capacity utilization for regional adhesive formulators. Health Canada and Environment Canada coordinate chemical risk assessment protocols that align with EPA prioritization timelines. Toronto-Windsor corridor plants are retrofitting solvent-borne application systems to accommodate water-based chemistries without production shutdowns.
Mexico
US-Mexico nearshoring of automotive and appliance assembly to Nuevo León and Chihuahua is generating greenfield demand for localized adhesive blending capabilities. Mexican environmental regulations under SEMARNAT are tightening VOC limits in industrial coatings and adhesives. Querétaro and Guanajuato manufacturing clusters are attracting technical service investments from multinational suppliers seeking line-efficiency guarantees with tier-1 seating suppliers.
Texas
Texas hosts the densest concentration of silane and silicone precursor production along the Houston Ship Channel, creating geographic single-point vulnerability for sealant supply chains. TCEQ air quality regulations enforce VOC limits that exceed federal EPA thresholds in certain non-attainment zones. Dallas-Fort Worth metroplex distribution hubs are consolidating procurement for Southwest construction and industrial maintenance accounts.
North America Adhesives and Sealants Market Vendor Landscape
Integrated multinational chemical conglomerates and specialized adhesive formulators split the market along capital intensity and technical service capability lines. The vendor base concentrates around three strategic archetypes: Gulf Coast-integrated petrochemical producers with captive precursor supply, European-headquartered specialty chemical groups with reactive polyurethane platforms, and North American-focused formulators with embedded application equipment services. Competitive dynamics center on backward integration into silane and isocyanate feedstocks, and forward integration into line-efficiency guarantees and multi-year technical service contracts.
Among the integrated petrochemical tier, Dow anchors its position through manufacturing scale along the US Gulf Coast. Within the specialty formulation segment, H.B. Fuller Company exemplifies the service-integrated model, while Henkel Corporation occupies a position emphasizing R&D intensity in reactive platforms. These three entities represent distinct competitive vectors: feedstock security, technical service bundling, and formulation innovation.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Wacker Chemie AG |
| Henkel Corporation |
| RPM International Inc. |
| Arkema |
| Sika AG |
| Dow |
| Evonik Industries |
| 3M |
| Others |
Supply Flow & Price Mechanics
Gulf Coast silane precursor concentration creates geographic single-point vulnerability that simultaneously widens pricing tier spreads between captive-integrated suppliers and non-integrated formulators while compressing margin buffers across the supply chain. This feedstock dependency forces buyers into long-term offtake commitments or spot market exposure, with EPA VOC regulatory chokepoints further stratifying procurement economics between compliant and non-compliant inventory positions.
Pricing Analysis
Aftermarket service revenue tiers anchored by multi-year technical service contracts drive lifetime value capture beyond unit formulation sales. Three-tier pricing structure across premium crash-rated polyurethanes, standard water-based acrylics, and economy hot-melt platforms separates automotive OEM specifications from packaging converter spot purchases. Cost compression in commodity water-based grades is intensifying because Midwest packaging buyers exhibit extreme price elasticity. Tier-1 automotive accounts in Ontario and Michigan absorb premium structural bonding pricing with minimal volume attrition.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for specialty epoxy curing agents and certain acrylic monomer feedstocks. Manufacturing concentrates in the US Gulf Coast petrochemical corridor, Ontario's Toronto-Windsor industrial belt, and northern Mexico's Nuevo León assembly clusters. Raw material dependencies rest on benzene-derived isocyanates, propylene oxide, and silane precursors. Distribution runs through direct manufacturer relationships for Tier-1 automotive accounts and industrial supply houses for fragmented contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around reactive chemistry platform transitions, as EPA isocyanate prioritization and EV battery assembly requirements create specialized formulation niches inaccessible to commodity-scale producers.
For Market Incumbents: Pre-empt regulatory-driven formulation obsolescence by accelerating non-isocyanate polyurethane R&D pipelines before TSCA Section 6 enforcement timelines compress. Backward integration into Gulf Coast silane precursor production secures margin stability against feedstock volatility threatening non-integrated competitors. Channel control through embedded application equipment service contracts locks in Midwest packaging converter switching costs. For New Entrants and Emerging Players: Querétaro and Guanajuato automotive assembly clusters represent the most penetrable entry point for localized reactive hot-melt blending capabilities serving US-Mexico nearshored production. Technical service partnerships with Tier-1 seating suppliers bypass capital-intensive precursor manufacturing requirements. A specification-first go-to-market angle targeting California CARB SCM-2007 compliance documentation gaps exploits incumbent reformulation lag times. For Investors and Strategic Acquirers: EPA isocyanate prioritization under TSCA Section 6 reshapes the acquisition landscape toward formulators with advanced non-isocyanate polyurethane platforms and toxicology documentation infrastructure. Long-term viability favors targets with captive technical service networks and multi-year automotive OEM contracts rather than commodity water-based exposure. The signal to watch is accelerated OEM qualification timelines for alternative curing chemistries as contingency supply chain development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Gulf Coast captive supply secures margin stability against benzene volatility and tariff exposure. |
| Reactive Hot-Melt Capacity Expansion | EV battery assembly lines in Michigan and Ontario pull moisture-cure systems for thermal management. |
| Technical Service Network Embedding | On-site line-efficiency guarantees lock in multi-year contracts with Tier-1 automotive seating suppliers. |
| Non-Isocyanate Platform Development | TSCA Section 6 prioritization forces preemptive reformulation ahead of enforcement timelines. |
| Nearshored Blending Joint Venture | Nuevo León localized production captures US-Mexico automotive migration with reduced logistics exposure. |
Methodological Framework
The analysis maps polyurethane, silicone, epoxy, and acrylic formulation platforms, each validated through plant managers at Gulf Coast petrochemical facilities, procurement leads at Tier-1 automotive suppliers, distribution channel partners, and technical R&D directors. Primary interview data triangulates against customs and trade databases, American Chemistry Council sector reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up capacity utilization estimates and top-down end-use demand aggregation cross-validate volume and value outputs.
Assumptions held fixed include EPA VOC phase-out timelines and CARB SCM-2007 compliance thresholds, while benzene and propylene oxide feedstock pricing, automotive production volumes, and nearshoring velocity were varied across sensitivity scenarios. Segmentation dimensions modeled encompass chemistry platform, cure mechanism technology, end-use application, and regional production cluster. CAGRs derive from regression-based trend extrapolation against historical capacity expansion patterns and OEM specification adoption curves, with EV battery content-per-vehicle assumptions and infrastructure resilience mandate implementation as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, construction spending, and petrochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions subject to revision based on regulatory enforcement timing and alternative curing chemistry qualification rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market