
 Asia-Pacific Waterproofing Products Market | 2026-2036
Asia-Pacific Waterproofing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Waterproofing Products Market Insights
China's manufacturing corridor expansion is reconfiguring regional supply dynamics for modified bitumen and polymer-based systems. Beijing Oriental Yuhong Waterproof Technology leverages captive resin production to anchor cost positions across domestic infrastructure tenders. Sika AG competes through specification-grade polyurethane formulations that dominate elevated commercial podiums. Pidilite Industries controls distribution depth across India's contractor network, sustaining margin capture in tier-two cities.
Asia-Pacific waterproofing products encompass elastomeric and plastomeric membranes, cementitious crystalline admixtures, and fluid-applied polymer barriers engineered to achieve hydrostatic resistance exceeding 70 meters of water head. These systems protect structural concrete from chloride ingress and carbonation in monsoon-exposed climates. Liquid applied coatings lead value contribution due to complex geometry adaptability on irregular podium slabs and elevator pit configurations. TPO membranes represent the fastest-growing product category as cool-roof mandates proliferate across Australian and Southeast Asian commercial portfolios. The residential end-user segment remains volume-dominant though infrastructure commands premium pricing per installed square meter.
India's BIS certification requirements and China's GB standards for construction waterproofing enforce minimum elongation and tensile retention thresholds that filter subscale domestic producers. Australia's National Construction Code and Japan's JIS A 6021 standard similarly restrict market access to tested membrane systems. Stakeholders must monitor regulatory divergence between national building codes and harmonized ASEAN technical standards as cross-border project execution intensifies.
Market Dynamics
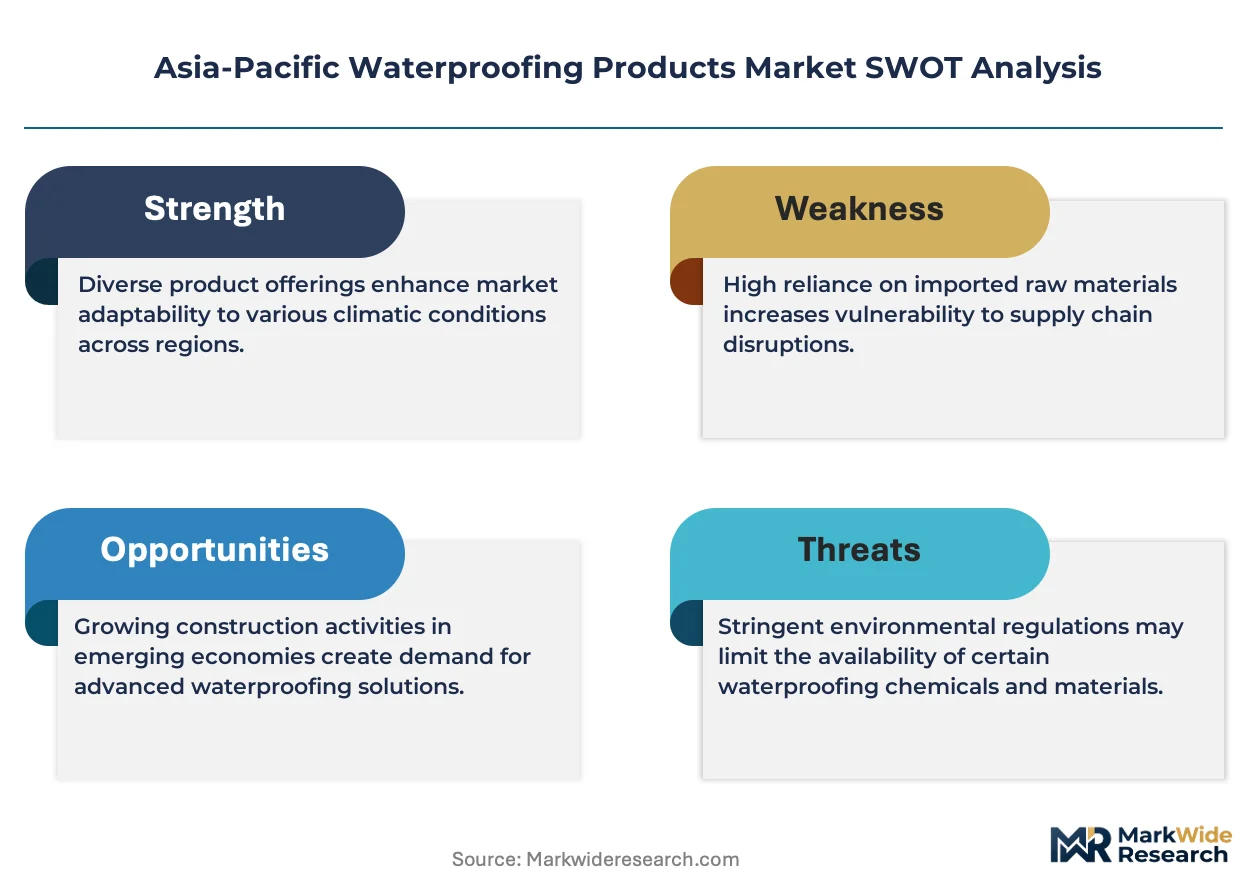
China's GB standards for construction waterproofing are compressing supplier margins while simultaneously filtering subscale domestic producers from infrastructure tenders. This regulatory compression is accelerating consolidation across membrane and coating supply chains.
Growth Catalysts
- India's Bureau of Indian Standards mandate:Stricter building envelope codes in tier-one and tier-two cities are pulling specification-grade crystalline admixtures into residential and commercial foundations.
- Australian cool-roof mandates:TPO membrane adoption is accelerating across commercial portfolios in Sydney and Melbourne as thermal performance requirements tighten.
- Urban infrastructure corridors:Southeast Asian metro rail and underground transit projects are specifying fluid-applied polyurethane for complex podium geometries.
Market Restraints
- Petrochemical input volatility:Modified bitumen and polyurethane resin costs fluctuate with naphtha and MDI pricing, compressing margin predictability for applicators.
- Supply concentration in East China:Captive resin production clusters around Shanghai and Jiangsu create geographic vulnerability to regional logistics disruptions.
- Technical limitation in cryogenic adhesion:Standard TPO membranes suffer reduced bond strength below 5°C, restricting winter application windows in northern Japan and Korea.
Strategic Opportunities
- Vietnam's underpenetrated tier-two construction:Cementitious crystalline systems remain below 15% penetration in Da Nang and Hai Phong residential markets.
- Digital specification platforms:Contractor procurement through B2B marketplaces is bypassing traditional distributor layers in India's western states.
- Japan's JIS A 6021 alignment with ASEAN standards:Harmonized testing protocols are reducing certification duplication costs for cross-border project execution.
Industry Challenges
- Applicator certification gaps:Fluid-applied polyurethane installation requires trained technicians, and shortage of certified crews is extending project timelines in Indonesia.
- Legacy substrate compatibility:Integrating new membrane systems with existing built-up roofing creates warranty complexity for retrofit contractors in Australia's aging commercial stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Waterproofing Products Market |
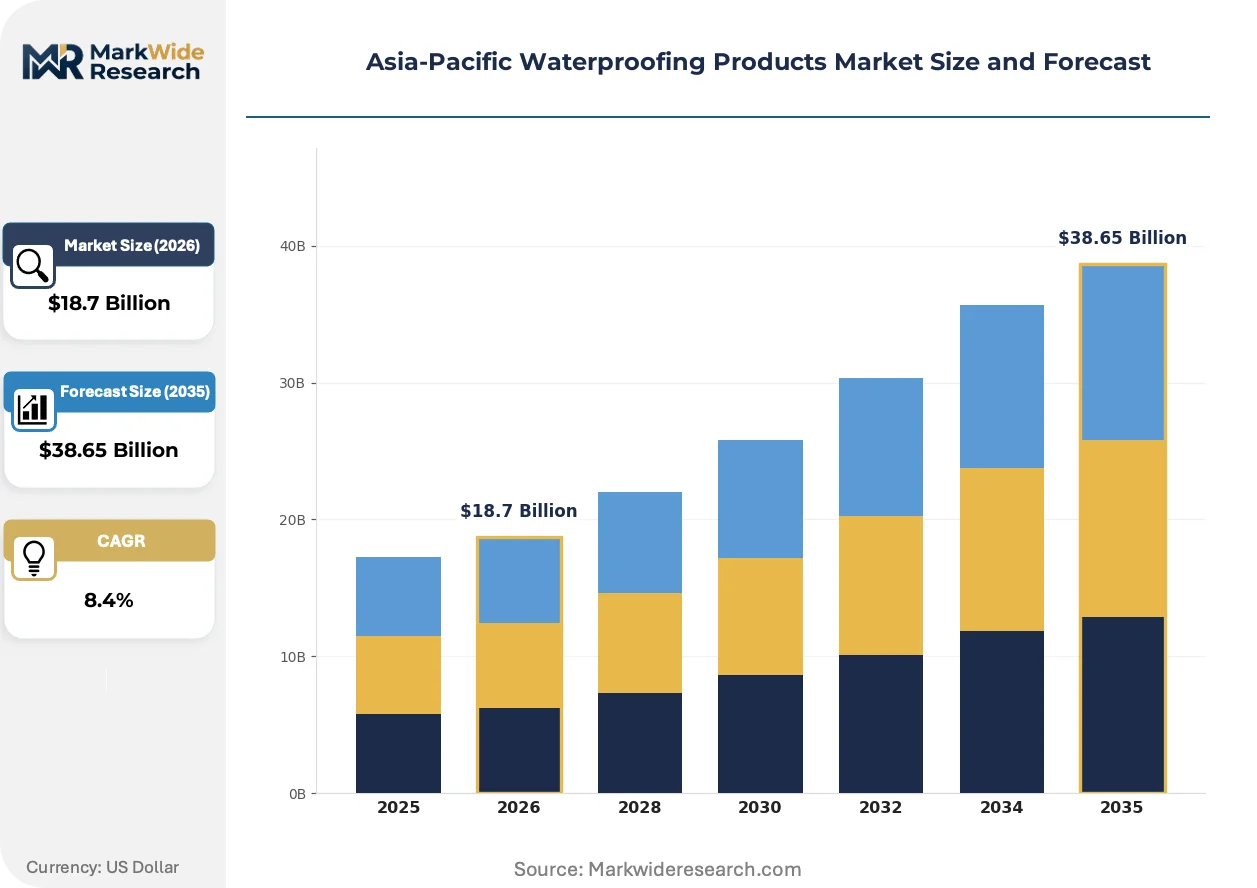
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous Membranes, Liquid Applied Coatings, Cementitious Waterproofing, TPO Membranes Application: Roofing, Basement, Elevator Pits, Water Tanks End User: Residential, Commercial, Industrial, Infrastructure Technology: Polyurethane, Acrylic, Silicone, EPDM |
| Companies Covered | Beijing Oriental Yuhong Waterproof Technology Co., Ltd., Sika AG, Saint-Gobain, Ardex Group, Hongyuan Waterproof Technology Group Co., Ltd., BASF SE, Pidilite Industries Limited, Keshun Waterproof Technology Co., Ltd., Mapei S.p.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Waterproofing Products Market Trends and Innovations
Specification behavior is pivoting toward performance-guaranteed systems rather than commodity membrane procurement. This shift is compressing the supplier base toward vertically integrated manufacturers with in-house testing capabilities.
Self-healing cementitious crystalline technology is migrating from below-grade infrastructure into elevated podium applications. Australian commercial developers are specifying these systems for green-roof assemblies. The technology is migrating from passive crystalline growth models toward active polymer-hybrid formulations that accelerate crack-sealing response times.
China's GB 50208 standard revision is mandating 70-year service life projections for underground waterproofing systems. This is forcing membrane suppliers to submit accelerated aging data beyond traditional 20-year warranties. High-speed rail tunnel projects in Sichuan and Yunnan provinces are now requiring dual-layer membrane configurations with independent leak detection membranes.
Asset-owner procurement teams are consolidating specification authority away from general contractors. Japanese commercial real estate investment trusts now retain independent waterproofing consultants for podium and basement reviews. This concentration is visible across Tokyo and Osaka Class-A office developments where owners bear long-term maintenance liability.
Asia-Pacific Waterproofing Products Market Segmentation
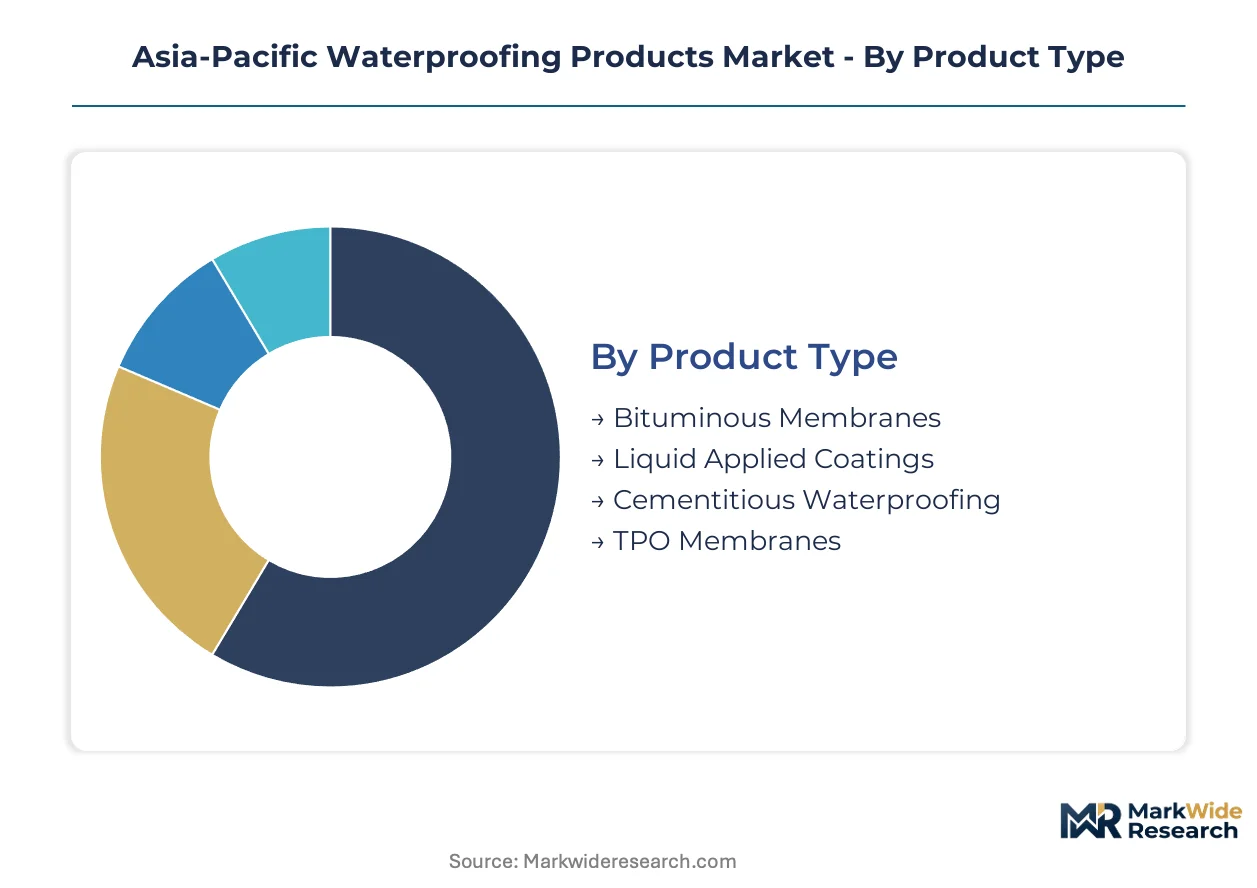
Waterproofing procurement in the Asia-Pacific region fragments across performance specifications, installation constraints, and asset-owner risk profiles. Each segmentation dimension reveals distinct margin structures and competitive entry barriers that suppliers must navigate.
Product Type:
Mature bituminous systems dominate volume, while emerging polymer technologies capture specification premiums in high-performance infrastructure.
- Liquid Applied Coatings:Fluid-applied polyurethane and acrylic formulations achieve seamless coverage on complex podium geometries. Demand concentrates in Southeast Asian metro rail projects where irregular substrate shapes render sheet membranes impractical. Specification-grade systems from Sika AG and Beijing Oriental Yuhong anchor premium pricing in Singapore and Bangkok underground transit corridors.
- TPO Membranes:Thermoplastic polyolefin sheets deliver cool-roof thermal performance with welded seam integrity. Australian commercial portfolios in Sydney and Melbourne specify white-reflective TPO as the National Construction Code tightens energy efficiency mandates. The segment encounters technical constraints below 5°C, restricting winter application windows in northern Japan and Korea.
- Bituminous Membranes:Modified bitumen sheets with SBS or APP polymer modification remain the default specification for residential foundations across India and China.
- Cementitious Waterproofing:Crystalline admixtures and brush-applied cementitious barriers protect below-grade concrete in monsoon-exposed climates.
Liquid applied coatings retain volume leadership; TPO membranes hold the steepest expansion curve.
Application:
Application segmentation reflects the hydrostatic pressure differential between above-grade and below-grade exposure conditions.
- Roofing:Above-grade waterproofing spans exposed membrane roofs, inverted assemblies, and green-roof substrates. Australian developers specify self-healing crystalline technology for green-roof podiums where root penetration and ponding water create compound failure risks. China's GB 50208 revision mandates 70-year service life projections for high-specification commercial roofing.
- Basement:Below-grade systems resist hydrostatic pressure exceeding 70 meters of water head in high-water-table environments. India's BIS certification requirements enforce minimum elongation thresholds for basement membranes in Mumbai and Chennai coastal developments.
- Elevator Pits:Confined-space waterproofing demands fluid-applied systems with complex geometry adaptability.
- Water Tanks:Potable water contact applications require NSF/ANSI 61 or equivalent certification for interior coating systems.
Basement applications command premium pricing per installed square meter; roofing specifications drive the broadest product mix.
End User:
End-user segmentation separates price-sensitive volume procurement from performance-guaranteed infrastructure tenders.
- Infrastructure:Government-backed metro rail, high-speed rail tunnels, and airport projects specify dual-layer membrane configurations with independent leak detection systems. China's Sichuan and Yunnan province rail tunnels now require accelerated aging data beyond traditional 20-year warranties. State-owned developers consolidate specification authority away from general contractors.
- Commercial:Class-A office and retail developments in Tokyo and Osaka increasingly retain independent waterproofing consultants as Japanese REITs absorb long-term maintenance liability.
- Residential:Volume-dominant segment with tier-one and tier-two city differentiation in India and Vietnam.
- Industrial:Manufacturing facilities and logistics warehouses prioritize rapid installation and chemical resistance.
Residential maintains volume dominance; infrastructure delivers the highest margin capture per project.
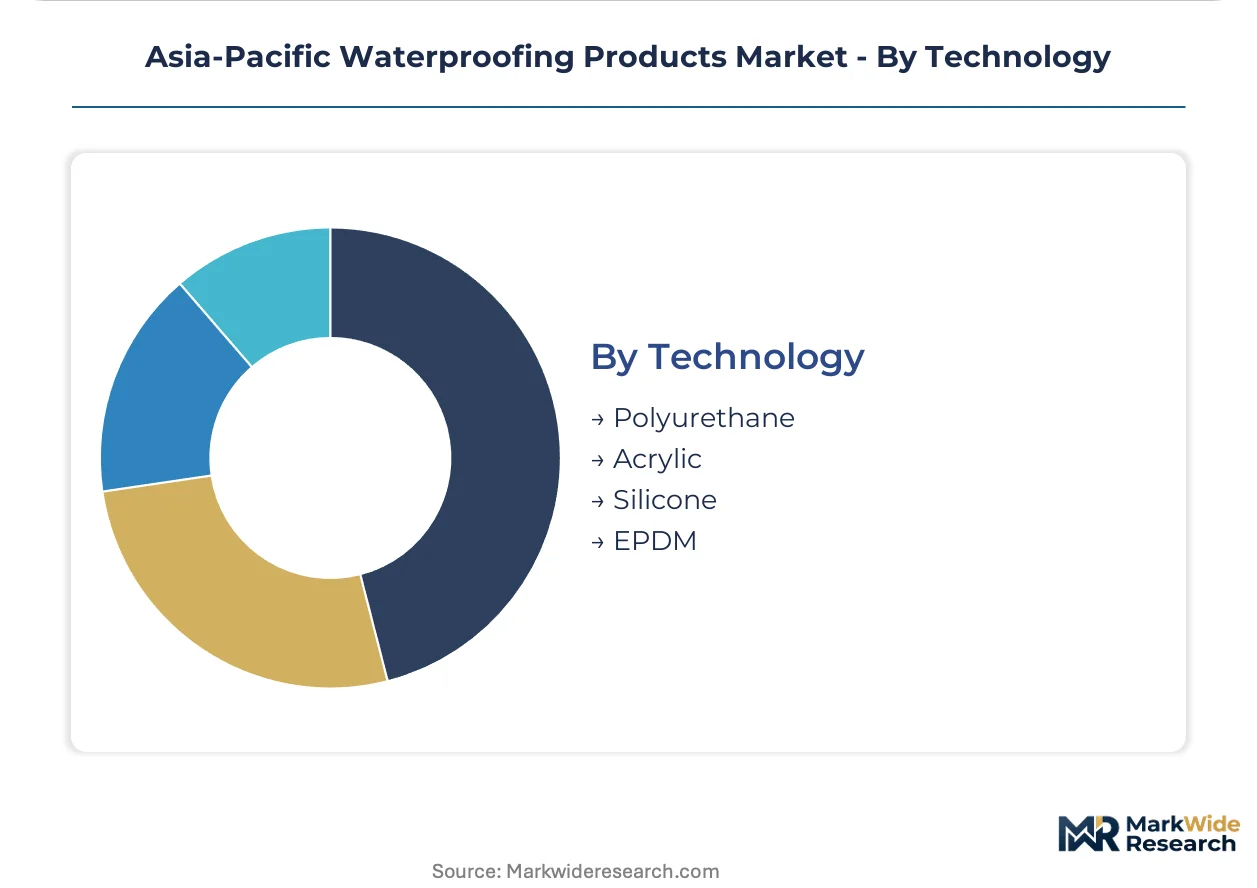
Technology:
Technology segmentation tracks the shift from commodity polymer systems toward specification-grade formulations with certified applicator networks.
- Polyurethane:Two-component aromatic and aliphatic polyurethane coatings deliver elastomeric performance with 300-800% elongation. Fluid-applied polyurethane dominates Southeast Asian podium specifications where complex geometries preclude sheet membrane installation. Applicator certification gaps in Indonesia extend project timelines and constrain supply capacity.
- Acrylic:Water-based acrylic emulsions serve cost-sensitive residential applications with breathable film formation for tropical humidity cycling.
- Silicone:High-solids silicone systems deliver UV stability for exposed roofing in Australian and Middle Eastern export markets.
- EPDM:Ethylene propylene diene monomer rubber membranes retain position in large-span commercial roofing with proven 30-year track records.
Polyurethane anchors premium infrastructure positioning; acrylic systems penetrate residential volume tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modified bitumen and polymer resin production clusters around Shanghai and Jiangsu province, creating geographic concentration that shapes regional logistics networks and tender participation across Southeast Asian infrastructure corridors.
China
High-speed rail tunnel projects in Sichuan and Yunnan provinces specify dual-layer membrane configurations with independent leak detection systems. GB standards for construction waterproofing enforce minimum elongation thresholds that filter subscale domestic producers from state-backed tenders. Beijing Oriental Yuhong leverages captive resin production to anchor cost positions across tier-one metropolitan infrastructure bids.
India
Tier-one and tier-two city construction pulls specification-grade crystalline admixtures into residential and commercial foundations. BIS certification requirements enforce stricter building envelope codes that restrict market access to tested membrane systems. Mumbai and Chennai coastal developments command premium basement waterproofing specifications due to high-water-table exposure.
Japan
Commercial real estate investment trusts retain independent waterproofing consultants for podium and basement reviews. JIS A 6021 standard alignment with ASEAN technical standards reduces certification duplication costs for cross-border project execution. Tokyo and Osaka Class-A office developments concentrate specification authority with asset owners bearing long-term maintenance liability.
Australia
TPO membrane adoption accelerates across Sydney and Melbourne commercial portfolios as the National Construction Code tightens energy efficiency mandates. Cool-roof thermal performance requirements specify white-reflective TPO with welded seam integrity. Self-healing cementitious crystalline technology migrates into green-roof assemblies for root penetration resistance.
Vietnam
Cementitious crystalline systems remain below penetration thresholds in Da Nang and Hai Phong residential markets. Urban infrastructure corridors including metro rail projects specify fluid-applied polyurethane for complex podium geometries. Digital specification platforms bypass traditional distributor layers in western provinces.
Asia-Pacific Waterproofing Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The supplier base compresses toward vertically integrated manufacturers with in-house testing capabilities as GB standards and BIS certification requirements raise technical barriers. Three archetypes dominate: captive resin producers with infrastructure tender access, specification-grade formulators serving commercial podiums, and distribution-heavy players penetrating tier-two contractor networks. Consolidation accelerates through backward integration into polymer feedstocks and strategic partnerships with certified applicator networks.
Among Asia-Pacific-based specialists, Beijing Oriental Yuhong Waterproof Technology Co., Ltd. exemplifies the captive production archetype, while Sika AG occupies a position on the premium formulation vector. Pidilite Industries Limited anchors the distribution-depth tier across India's contractor ecosystem. These three represent distinct competitive positions: resin-integrated cost leadership, specification-grade polyurethane systems, and tier-two city margin capture.
| Leading Market Players |
|---|
| Beijing Oriental Yuhong Waterproof Technology Co., Ltd. |
| Sika AG |
| Saint-Gobain |
| Ardex Group |
| Hongyuan Waterproof Technology Group Co., Ltd. |
| BASF SE |
| Pidilite Industries Limited |
| Keshun Waterproof Technology Co., Ltd. |
| Mapei S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Shanghai and Jiangsu province resin production clusters anchor regional cost positions across Asia-Pacific waterproofing tenders, concentrating pricing power with captive manufacturers while compressing margins for import-dependent formulators in Southeast Asian corridors.
Pricing Analysis
China's GB standards for construction waterproofing dictate the pricing tier structure across the region. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade polyurethane systems from modified bitumen sheets and commodity cementitious admixtures. Cost compression in standard-grade bituminous membranes is intensifying because petrochemical input volatility feeds through naphtha and MDI pricing. Residential contractors in India's tier-two cities exhibit highest price sensitivity, while infrastructure tender boards in China's tier-one metropolitan corridors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced polymer synthesis catalysts limit technology flows into domestic Chinese resin production, forcing regional formulators toward licensed additive packages. Supply concentrates in China, South Korea, and Japan for MDI prepolymers and SBS modifiers. Raw material dependencies rest on naphtha derivatives, titanium dioxide pigments, and specialty amine curatives. Single-source vulnerability concentrates around Shanghai port logistics chokepoints. Distribution runs through certified applicator networks in infrastructure segments and traditional distributor layers in residential construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-owner procurement consolidation across Japanese commercial REITs and Chinese state-backed developers is shifting buyer power toward performance-guaranteed specification authority, fragmenting traditional general contractor intermediation.
For Market Incumbents: Harden specification-grade positioning through in-house accelerated aging test capabilities that satisfy China's GB 50208 revision demands for 70-year service life projections. Deepen backward integration into captive resin production to defend margin positions against petrochemical input volatility threatening modified bitumen and polyurethane formulators. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated tier-two residential markets where cementitious crystalline systems remain below penetration thresholds in Da Nang and Hai Phong. Digital specification platforms offer direct contractor access in India's western states, bypassing entrenched distributor layers controlled by Pidilite Industries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with certified applicator networks and in-house testing capabilities over pure-play distribution assets. Long-term viability hinges on regulatory compliance depth as BIS and GB standards raise technical barriers. Acquisition targets should demonstrate dual-layer membrane configuration expertise for high-speed rail tunnel applications. The signal to watch is harmonization progress between Japan's JIS A 6021 and ASEAN technical standards as a cross-border project execution inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive MDI and SBS production insulates margin positions from naphtha volatility in Shanghai-Jiangsu corridor tenders. |
| Certified Applicator Network Expansion | Trained technician pools in Indonesia and Vietnam reduce project timeline extensions for fluid-applied polyurethane specifications. |
| In-House Accelerated Aging Test Capabilities | GB 50208 compliance for 70-year service life projections filters subscale competitors from Sichuan and Yunnan rail tunnel bids. |
| Digital Specification Platform Development | B2B marketplace procurement in India's western states bypasses traditional distributor margin layers. |
| Dual-Layer Membrane Configuration Expertise | Independent leak detection membrane integration captures premium infrastructure pricing in high-speed rail tunnel applications. |
Research Methodology
Operator-level perspectives from waterproofing contractors, membrane applicators, commercial real estate asset managers, and polymer procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, BIS certification registries, and GB standard revision documentation. Bottom-up project pipeline analysis triangulated against top-down construction spend forecasts across the Asia-Pacific region.
Scenario-bracketing around regulatory enforcement intensity and petrochemical input volatility framed the analytical approach across the analysis window. Segmentation dimensions modeled include product type, application exposure condition, end-user risk profile, and technology formulation grade. CAGRs derived from installation volume trajectories and specification-grade mix shifts. Industry-specific forecast inputs incorporated monsoon intensity patterns and cool-roof mandate adoption curves.
Sensitivities concentrate around GB standard enforcement consistency, BIS certification timeline extensions, and MDI pricing volatility. Forecasts reflect assumptions on infrastructure tender award velocities and residential construction permit issuance rates. Material shifts in ASEAN-Japan regulatory harmonization or captive resin production capacity additions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Timber Laminating Adhesives Market