
 North America Epoxy Adhesives Market | 2026-2036
North America Epoxy Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Epoxy Adhesives Market Analytics
Technical service subscriptions for formulation customization and on-site application support is recalibrating how adhesive suppliers capture value beyond resin volume. Henkel AG & Co. KGaA leverages its embedded laboratory network to sustain long-term contracts with tier-one automotive suppliers. Dow anchors its position through captive epichlorohydrin supply and direct technical service teams at major aerospace OEM sites. Huntsman International LLC differentiates via specialized high-temperature formulations for downhole oilfield applications.
Epoxy adhesives are thermosetting polymers formed by reacting epoxide resins with polyamine or anhydride hardeners, producing cross-linked structures with tensile shear strengths exceeding 20 MPa and operational stability from -55°C to 150°C depending on formulation. These properties make them indispensable for structural bonding where load transfer, chemical resistance, and thermal cycling endurance are required. Two-component systems dominate volume in construction and industrial assembly where pot life control and ambient cure flexibility matter most. Single-component heat-cure formulations command premium positioning in aerospace and electronics due to automated dispensing compatibility and void-free bond lines. The online distribution channel is expanding fastest among DIY enthusiasts and small contractors seeking technical datasheets and batch traceability without distributor markups.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, pushing manufacturers toward low-VOC epoxy formulations or solventless systems. OSHA hazard communication standards and state-level California Proposition 65 labeling requirements add compliance layers that favor established suppliers with dedicated regulatory affairs teams. The Federal Aviation Administration's material flammability standards (14 CFR 25.853) shape product qualification pathways for aerospace-grade adhesives. Stakeholders must monitor how evolving EPA Green Chemistry initiatives and potential revisions to TSCA Section 5 new chemical review processes could alter raw material access for specialty hardeners and reactive diluents.
Market Dynamics
Automotive lightweighting mandates in Michigan and Ontario are displacing mechanical fasteners with structural adhesive bonding, forcing formulation suppliers to recalibrate cure kinetics for mixed-material substrates while EPA VOC thresholds tighten compliance costs.
Growth Catalysts
- EPA 40 CFR Part 59 VOC limits:Low-solvent and solventless epoxy systems gain preference as manufacturers retrofit production lines to meet federal emissions ceilings without sacrificing bond strength.
- Wind blade manufacturing clusters:Texas and Iowa turbine assembly plants drive demand for thick-section laminating adhesives capable of sustaining fatigue loads across 80-meter-plus rotor spans.
- Two-component metering equipment:Precision dispensing systems enable on-site mixing with controlled pot life, expanding adhesive use in field construction where temperature and humidity fluctuate.
Market Restraints
- Epichlorohydrin supply concentration:US Gulf Coast petrochemical corridor disruptions propagate through bisphenol-A and epoxy resin pricing within 60-90 day windows.
- Heat-cure cycle requirements:Aerospace-grade single-component formulations demand 120-180°C oven exposure, limiting substrate compatibility and energy costs for tier-two suppliers.
- Polyurethane structural adhesives:Faster ambient cure and comparable shear strength in non-structural automotive panels threaten epoxy volume in Class A surface bonding.
Strategic Opportunities
- Electric vehicle battery pack assembly:Thermal runaway containment standards favor flame-retardant epoxy potting compounds for module-to-pack structural integration.
- Canada infrastructure stimulus:Federal and provincial bridge rehabilitation programs specify epoxy injection systems for concrete crack repair and carbon fiber reinforcement bonding.
- Digital substrate mapping:AI-driven surface preparation diagnostics converge with automated dispensing to reduce bond-line failure rates in high-throughput manufacturing.
Industry Challenges
- FAA 14 CFR 25.853 qualification timelines:Aerospace adhesive certification spans 18-36 months, compressing product development cycles against OEM platform deadlines.
- Reactive diluent handling protocols:OSHA hazard communication requirements for skin-sensitizing hardeners necessitate specialized ventilation and PPE investments at distributor mixing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Epoxy Adhesives Market |
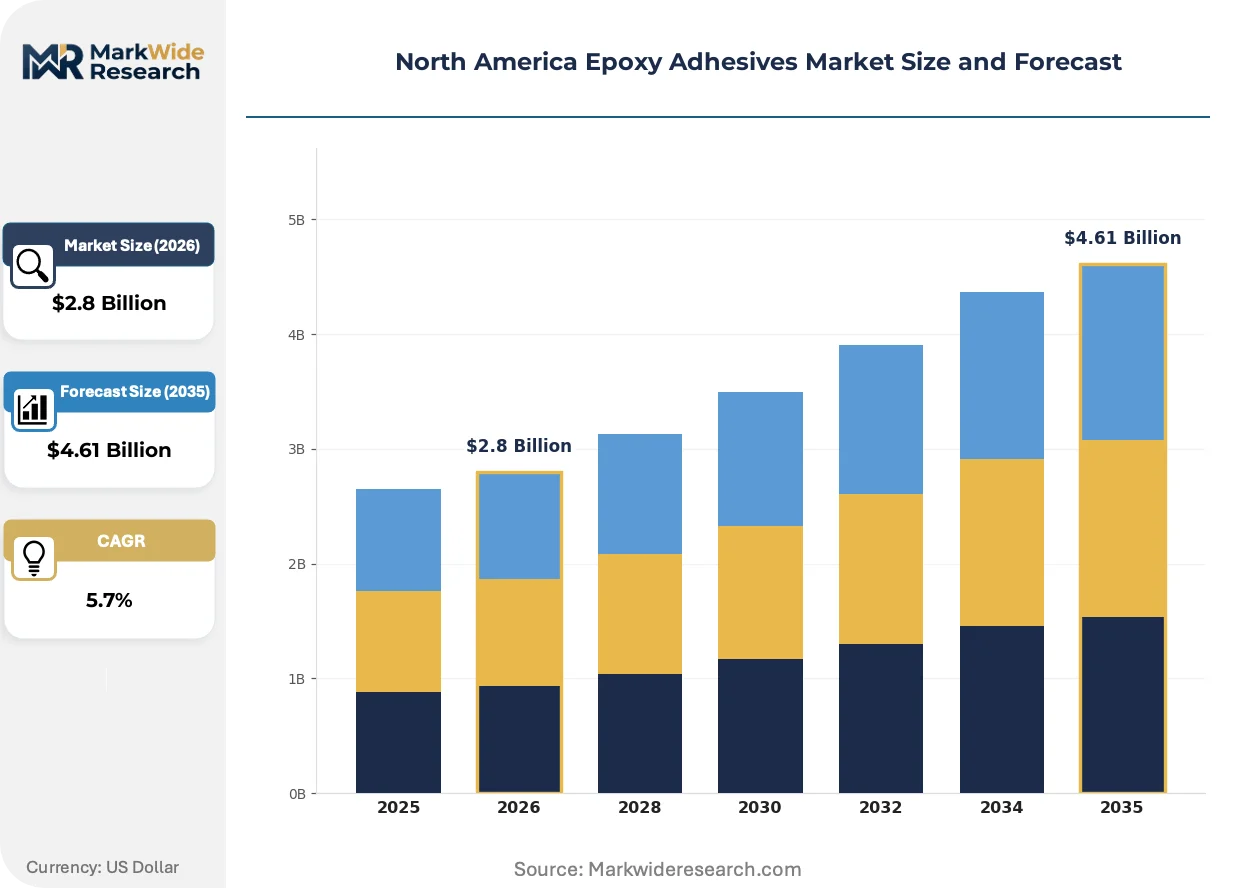
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Component, Two Component, High Temperature, Flexible Application: Aerospace, Automotive, Electronics, Construction End User: Manufacturers, Contractors, DIY Enthusiasts, Retailers Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Arkema Group, Dow, Huntsman International LLC, Evonik Industries, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Epoxy Adhesives Market Evolving Landscape
Bio-based hardener chemistry and automated dispensing integration are redefining formulation value capture, while regulatory pressure on volatile content accelerates solventless system development across transportation and construction verticals.
Hybrid bio-epoxy resins derived from lignin and plant-based phenolics are expanding into automotive interior trim and consumer electronics casings where aesthetic finish and moderate structural load converge. Tier-one suppliers in Detroit and Toronto are piloting these materials at 10-15% volume substitution rates. The technology is expanding into price-sensitive segments previously locked out of epoxy adoption due to petroleum-derived resin cost floors.
EPA Green Chemistry initiative criteria are tightening preferential purchasing standards for federal infrastructure projects, directing state transportation departments toward adhesives with third-party verified lifecycle assessments. Formulators must document feedstock provenance and energy intensity to maintain qualified supplier status. Construction-grade epoxy producers serving the Great Lakes manufacturing belt are restructuring technical documentation workflows to meet bid submission deadlines.
Direct technical service subscriptions are displacing traditional distributor markups as the primary value-capture mechanism for formulation customization. Small contractors and maintenance departments in Texas oilfield services now access on-site rheology adjustment and cure-profile optimization through annual service agreements rather than per-pound resin premiums. The Gulf Coast petrochemical corridor exhibits the fastest channel migration as buyers prioritize batch traceability and application failure liability transfer.
North America Epoxy Adhesives Market Segmentation
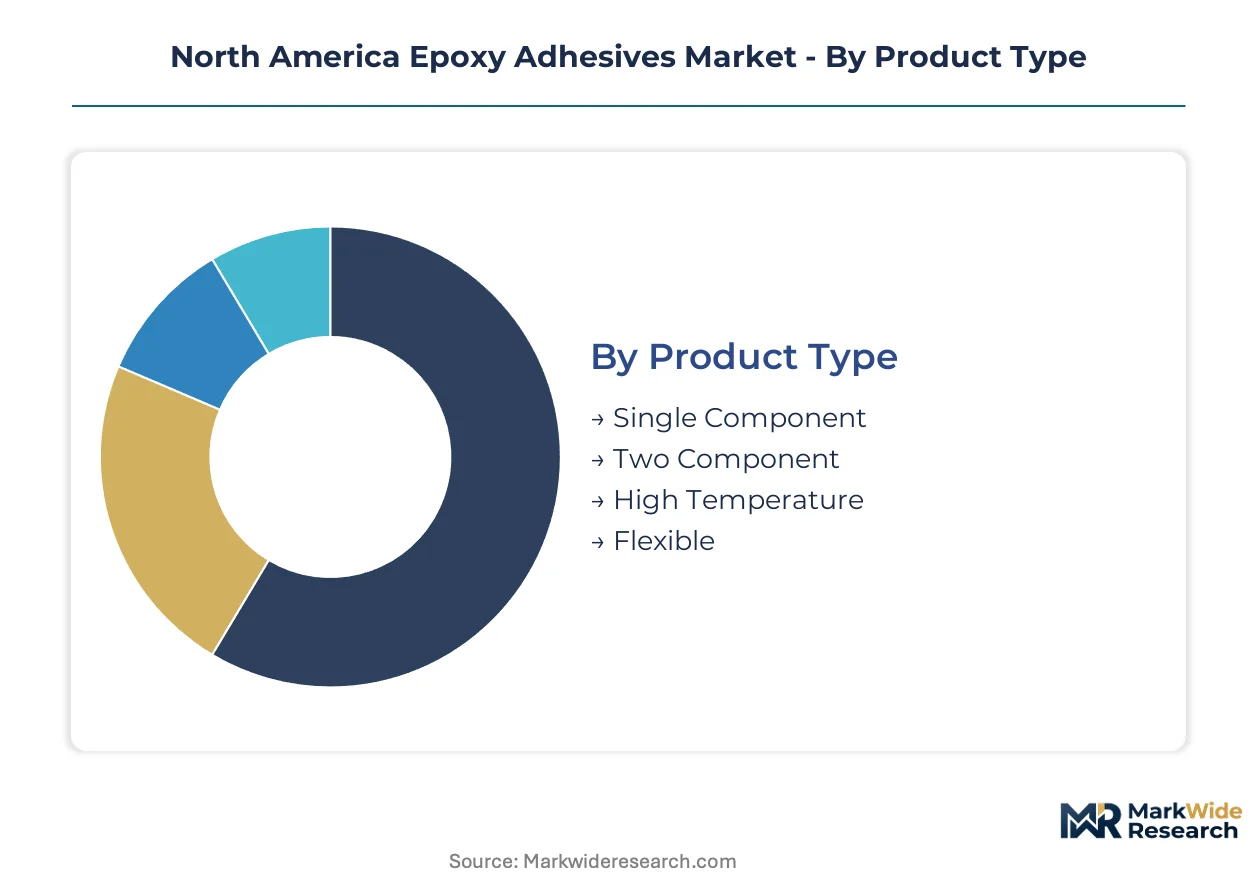
Epoxy adhesive procurement patterns diverge sharply across formulation chemistry, application environment, and buyer sophistication. Each segmentation axis carries distinct margin profiles and technical service requirements that reshape supplier go-to-market economics.
Product Type:
Upgrade cycles in automotive lightweighting and aerospace automation are displacing legacy formulations with precision-cure systems engineered for mixed-material substrates and robotic dispensing.
- Two Component:These systems combine resin and hardener at point of use through static mixing nozzles, delivering pot-life flexibility from 5 minutes to 4 hours depending on amine chemistry. Demand clusters in Great Lakes automotive assembly plants where aluminum-to-steel bonding requires ambient cure with controlled open time. Michigan and Ontario tier-one suppliers specify these systems for structural crash-resistant joints.
- Single Component:Pre-catalyzed formulations remain stable at room temperature yet cure rapidly at 120-180°C, enabling automated dispensing without mixing equipment. Aerospace OEMs in Seattle and Wichita specify heat-cure epoxies for primary structure bonding where void-free bond lines and FAA 14 CFR 25.853 flammability compliance are mandatory.
- High Temperature:Formulations with aromatic amine hardeners sustain 200°C+ continuous operation for downhole oilfield tools and exhaust system components.
- Flexible:Modified aliphatic amine systems absorb thermal cycling stress across -40°C to 120°C for electronics potting and wind blade root bonding.
Volume placements concentrate in Two Component; the faster expansion belongs to Single Component as aerospace automation accelerates.
Application:
Cost-tier stratification separates specification-grade aerospace and automotive applications from price-sensitive construction segments where bulk procurement dominates.
- Automotive:Structural bonding of aluminum-intensive body-in-white assemblies and carbon fiber hoods demands crash-durable epoxies with 25-35 MPa shear strength. EPA VOC thresholds under 40 CFR Part 59 are forcing solventless formulation conversions at Detroit and Ontario assembly plants.
- Construction:Concrete crack injection, rebar bonding, and carbon fiber reinforcement anchoring consume high-viscosity thixotropic systems. Federal bridge rehabilitation programs across the Great Lakes belt specify epoxy injection for spall repair and structural upgrading.
- Aerospace:Primary structure and interior panel bonding require extensive FAA qualification cycles spanning 18-36 months.
- Electronics:Thermal management and flame-retardant potting compounds for EV battery modules favor low-ionic-content formulations.
Construction captures the highest volume throughput; aerospace commands the steepest expansion trajectory as next-generation platforms multiply bonded joints.
End User:
Customer-type differentiation separates enterprise procurement with embedded technical service from transactional spot buying where documentation and liability transfer matter most.
- Manufacturers:Tier-one automotive and aerospace OEMs negotiate multi-year supply agreements bundling resin volume with on-site rheology adjustment and cure-profile optimization. These buyers demand batch traceability, failure analysis support, and regulatory documentation packages.
- Contractors:Bridge rehabilitation and industrial maintenance crews purchase through wholesale distributors with just-in-time delivery to project sites. Texas and Iowa wind farm contractors specify thick-section laminating adhesives with 4-hour pot life for field blade repair.
- DIY Enthusiasts:Small-volume buyers access technical datasheets and application videos through online channels, prioritizing convenience over price.
- Retailers:Big-box hardware chains stock consumer-grade 5-minute and 30-minute general-purpose epoxies for household repair.
Manufacturers anchor procurement volume; the contractor segment is climbing fastest as infrastructure stimulus accelerates field application demand.
Distribution Channel:
Supply concentration in the Gulf Coast petrochemical corridor shapes channel economics, with direct technical service subscriptions displacing traditional distributor markups among sophisticated buyers.
- Direct Sales:Formulation suppliers deploy technical service teams at major OEM sites for customized rheology matching and application troubleshooting. Henkel and Dow maintain embedded laboratories in Detroit and Seattle to sustain long-term automotive and aerospace contracts.
- Online:Digital platforms with batch traceability and instant technical documentation are expanding fastest among small contractors and maintenance departments seeking liability transfer without distributor overhead.
- Wholesale:Regional distributors with localized inventory serve construction contractors with unpredictable project timing.
- Retail:Hardware store chains capture consumer-grade volume with limited technical support.
Wholesale retains the largest placement base; online channels are gaining share fastest as digital substrate mapping and automated dispensing converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates epoxy adhesive production along the Gulf Coast petrochemical corridor, while consumption clusters in the Great Lakes automotive belt and Texas wind manufacturing hubs. Canada and Mexico complete the regional demand triangle with infrastructure and assembly-driven procurement patterns.
United States
Michigan and Ontario automotive lightweighting programs displace mechanical fasteners with structural adhesive bonding at Detroit-area assembly plants. EPA 40 CFR Part 59 VOC limits force solventless formulation conversions across Great Lakes manufacturing facilities. Texas and Iowa wind blade factories consume thick-section laminating adhesives for 80-meter-plus rotor assembly.
Canada
Federal and provincial bridge rehabilitation programs specify epoxy injection systems for concrete crack repair and carbon fiber reinforcement anchoring. Health Canada and PMRA chemical substance regulations align with EPA frameworks for cross-border formulation compliance. Ontario's manufacturing belt mirrors Michigan's adhesive demand patterns for automotive mixed-material bonding.
Mexico
Automotive assembly expansion in Nuevo León and Bajío Region drives two-component epoxy consumption for aluminum-intensive body-in-white production. Mexican environmental regulations under SEMARNAT tighten VOC thresholds for imported formulations. Querétaro and Guanajuato aerospace clusters qualify heat-cure adhesives for interior panel bonding under FAA-aligned certification.
North America Epoxy Adhesives Market Competitive Landscape
Top-tier vendors anchor the formulation supply base, while mid-scale specialists and regional distributors occupy secondary positions. The market exhibits tiered concentration around petrochemical-integrated resin producers and application-technology bundlers. Strategic archetypes include captive raw-material suppliers, embedded technical-service providers, and niche high-temperature formulators. Dominant competitive moves center on direct technical-service subscriptions and captive epichlorohydrin supply security.
Within the integrated chemical conglomerate tier, Dow and Huntsman International LLC represent upstream-backward positions with captive feedstock control. Henkel AG & Co. KGaA anchors the technical-service archetype through embedded laboratory networks at major OEM sites. These three exemplify how value capture shifts from resin volume toward formulation customization and on-site application support.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Arkema Group |
| Dow |
| Huntsman International LLC |
| Evonik Industries |
| RPM International Inc. |
| Others |
Value Network & Pricing Analysis
Tier-one automotive OEM procurement concentration in Michigan and Ontario anchors contract-based long-term offtake agreements, with annual resin volume commitments bundled with embedded technical service subscriptions rather than spot-market transactions.
Pricing Analysis
Margin tightening in aerospace-grade single-component formulations reflects 18-36 month FAA 14 CFR 25.853 qualification timelines that compress supplier pricing leverage against OEM platform deadlines. Three-tier pricing structure across qualification-grade, industrial-performance, and construction-economy levels separates certified aerospace adhesives from field-applied bridge repair systems. Price differentiation rests on certification level and volume scale, with bulk construction procurement exhibiting highest sensitivity while automotive structural bonding programs prioritize failure liability transfer over per-pound cost.
Supply Chain Analysis
Dual-sourcing mandates from Detroit and Seattle OEMs require qualified backup suppliers for epoxy resin and amine hardener streams, propagating qualification costs through tier-one procurement contracts. Raw material supply draws from US Gulf Coast petrochemical corridor for epichlorohydrin and bisphenol-A, with specialty aromatic amines sourcing from Germany and Japan. Single-source vulnerability concentrates in high-temperature hardener chemistry for downhole oilfield applications. Distribution runs through direct technical service teams at major OEM sites, supplemented by wholesale distributors serving construction contractors with unpredictable project timing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epichlorohydrin supply concentration along the US Gulf Coast petrochemical corridor props pricing power for backward-integrated resin producers, constraining margin expansion for formulation specialists lacking captive feedstock.
For Market Incumbents: Cement long-term supply security through captive epichlorohydrin production or exclusive offtake agreements with Gulf Coast petrochemical operators, while accelerating solventless formulation R&D to preempt EPA 40 CFR Part 59 compliance cost escalation. Polyurethane structural adhesive substitution in Class A automotive surface bonding threatens epoxy volume displacement without crash-durable formulation differentiation. For New Entrants and Emerging Players: Begin with digital substrate mapping and automated dispensing integration for small-to-mid contractors in Texas wind farm maintenance and Great Lakes bridge rehabilitation, where technical service subscriptions displace distributor markups as the primary value-capture mechanism. Online channels with batch traceability and instant documentation access represent the most penetrable go-to-market vector. For Investors and Strategic Acquirers: The window for entry favors mid-scale formulation specialists with embedded laboratory networks and existing automotive or aerospace qualification pathways, positioned for technical service subscription revenue expansion. Monitor EPA Green Chemistry initiative preferential purchasing standards as the inflection signal for feedstock provenance documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive feedstock supply secures margin position against Gulf Coast petrochemical corridor disruptions. |
| Solventless Formulation Conversion | EPA 40 CFR Part 59 compliance maintains qualified supplier status for Michigan and Ontario automotive programs. |
| Direct Technical Service Subscription Launch | Annual service agreements displace distributor markups while transferring application failure liability to suppliers. |
| FAA 14 CFR 25.853 Qualification Acceleration | Shortened certification timelines align adhesive development with Seattle and Wichita OEM platform deadlines. |
| Digital Substrate Mapping Partnership | AI-driven surface preparation diagnostics reduce bond-line failure rates in high-throughput manufacturing environments. |
Research Methodology
Multi-period observation of automotive lightweighting program announcements, wind blade manufacturing capacity additions, and EPA regulatory filing patterns anchored the trend analysis, supplemented by interviews with adhesive formulation R&D directors, tier-one automotive procurement managers, aerospace material qualification engineers, and construction contractor purchasing leads. Secondary validation drew from ACC chemical industry reports, SEC 10-K filings of petrochemical-integrated suppliers, FAA material flammability certification databases, and customs trade data for epoxy resin imports. Bottom-up segment volume estimates triangulated against top-down macroeconomic indicators across the North American manufacturing belt.
Segment-weighting approaches applied differential growth assumptions by formulation chemistry, application vertical, and end-user sophistication, with product-type splits modeled across two-component, single-component, high-temperature, and flexible systems. End-use industry segmentation incorporated automotive platform electrification timelines, federal bridge rehabilitation program allocations, and aerospace OEM production rate projections. CAGRs derived from regression analysis of historical volume patterns against industrial production indices and construction spending data, with cross-validation against adhesive consumption intensity metrics per vehicle class and wind turbine scale.
Underlying measurement precision varies by segment; automotive and aerospace applications carry tighter precision due to transparent OEM supply agreements, while construction contractor spot purchasing exhibits higher variance. Forecasts reflect assumptions regarding EPA VOC regulatory trajectory, epichlorohydrin supply stability, and automotive lightweighting program continuity. Deviation in FAA qualification timeline compression or Gulf Coast petrochemical corridor disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market