
 Spun Yarn Paper Cone Market | 2026-2036
Spun Yarn Paper Cone Market Size, Share, and Industry Trends Forecast 2026-2036
Spun Yarn Paper Cone Market Analytics
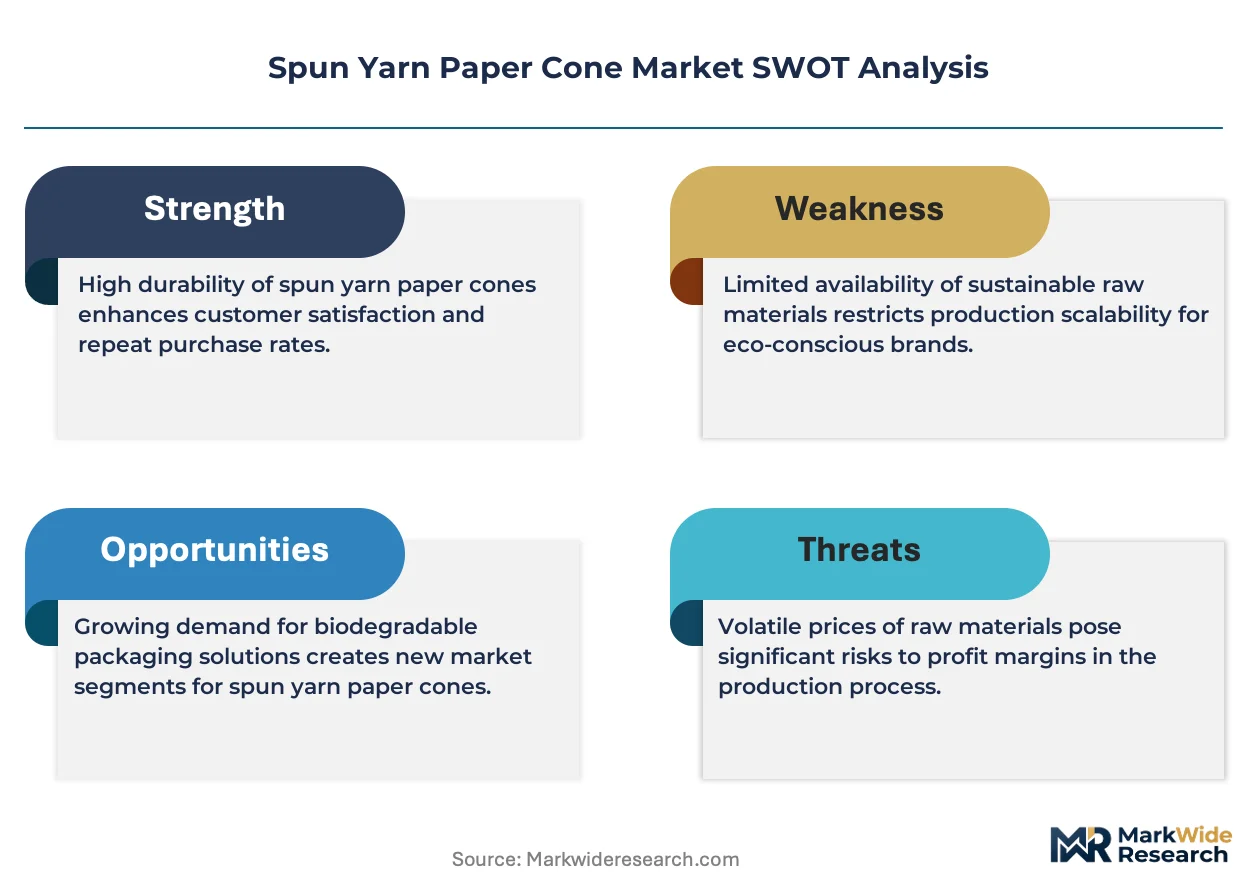
India's paper cone manufacturing belt is tilting toward higher-capacity output as domestic spinning mills expand yarn production. Pacific Cones leverages its regional distribution network to supply major South Asian textile hubs. Sonoco Products Company sustains technical leadership through precision-engineered cone geometries for high-speed winding. Conitex Sonoco anchors cross-border supply chains linking Latin American pulp sources to Asian cone finishing plants.
Spun yarn paper cones are cylindrical fiberboard carriers engineered to precise taper angles and wall thicknesses, typically manufactured from kraft pulp through spiral winding and adhesive bonding to withstand centrifugal forces during high-speed yarn winding. Standard Cone and Specialty Cone segments dominate current volume, with Recycled Cone gaining structural momentum as brands enforce circular procurement mandates. Composite Material formulations command premium positioning where technical textile applications require enhanced crush resistance.
India's BIS packaging standards and the EU REACH framework govern chemical content in cone adhesives and surface treatments, while China's GB standards for paper packaging shape export qualification requirements for Asian manufacturers. Regulatory divergence across these jurisdictions compels cone producers to maintain multiple certification pathways. Stakeholders must monitor evolving recycled content mandates and regional labeling requirements to align product portfolios with shifting compliance thresholds.
Market Dynamics
Spinning capacity migration to South Asia is compressing lead times and forcing cone manufacturers to co-locate finishing operations near textile clusters in Bangladesh and Vietnam.
Growth Catalysts
- EU REACH chemical compliance:Cone producers achieving adhesive certification under REACH protocols gain preferential access to European textile brands enforcing circular procurement mandates.
- Recycled fiber adoption:Textile mills in Tamil Nadu and Gujarat are specifying post-consumer kraft content in cone specifications, creating pull for certified recycled pulp supply chains.
- High-speed winding automation:Precision taper geometries engineered for centrifugal force tolerance enable running speeds above 25,000 RPM in modern ring spinning frames.
Market Restraints
- Kraft pulp price volatility:Latin American pulp supply concentration exposes cone margins to freight rate spikes and currency fluctuations in Brazilian Real-denominated contracts.
- India BIS certification timelines:Packaging standard compliance delays of 8-14 weeks create inventory bottlenecks for export-bound shipments.
- Plastic cone substitution:Polypropylene carriers retain cost advantage in coarse count yarn applications above Ne 20, limiting paper cone penetration in commodity spinning segments.
Strategic Opportunities
- Vietnam textile expansion:Cone demand from Ho Chi Minh City spinning parks exceeds domestic converter capacity, creating entry points for regional suppliers with cross-border logistics networks.
- Composite material convergence:Glass fiber-reinforced kraft laminates address technical textile requirements in industrial sewing thread and tire cord applications.
- India PLI scheme incentives:Production-linked benefits for textile machinery investment indirectly stimulate cone consumption as domestic spinning capacity expands.
Industry Challenges
- Spiral winding technician scarcity:Specialized adhesive calibration and tension control expertise is concentrating among aging workforces in Gujarat and Tamil Nadu manufacturing belts.
- Multi-jurisdiction certification complexity:Simultaneous compliance with India's BIS, China's GB standards, and EU REACH requires parallel testing protocols that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spun Yarn Paper Cone Market |
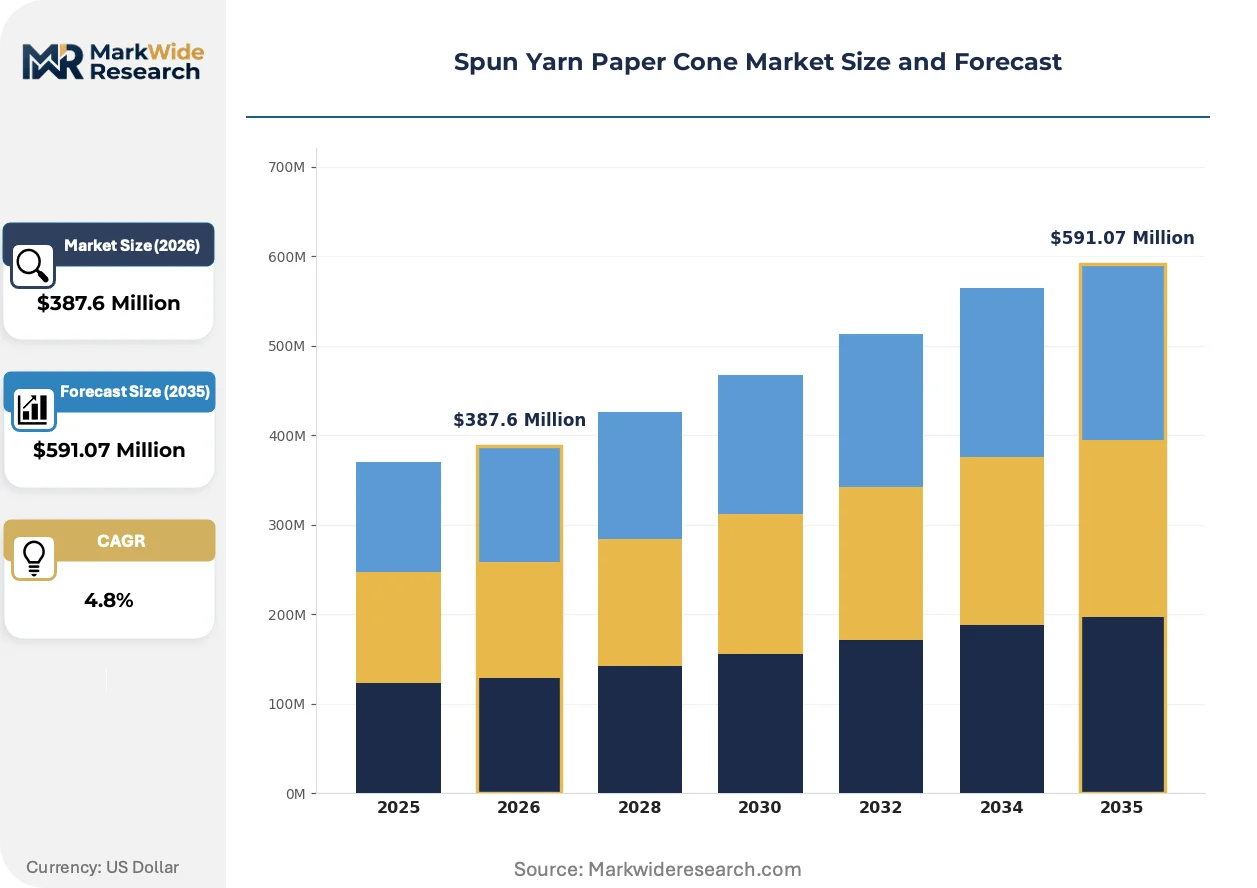
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cone, Specialty Cone, Custom Cone, Recycled Cone Application: Textiles, Apparel, Home Furnishings, Industrial Use Material: Pulp, Virgin Fiber, Recycled Fiber, Composite Material Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Pacific Cones, Sonoco Products Company, Conitex Sonoco, Shivshakti Paper Cone, SKS Paper Products, Shree Laxmi Corporation, Saroja Texcone, Sundaram Paper Products, Kaylor Rotomoulders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spun Yarn Paper Cone Market Evolving Landscape
Digital specification exchange between cone producers and spinning mills is compressing sample approval cycles, while surface treatment chemistry advances enable lighter-weight constructions without crush resistance trade-offs.
Water-based barrier coatings are collapsing the performance gap between traditional wax-treated cones and synthetic alternatives in humid mill environments. Bangladeshi textile groups are piloting these formulations for monsoon-season yarn storage. The technology is collapsing resistance to paper cone adoption in tropical climate spinning operations previously dependent on plastic carriers.
India's BIS packaging standards are tightening adhesive emission thresholds and mandating recycled content disclosure labeling for domestic market placement. Cone manufacturers serving both export and domestic channels must maintain dual specification streams. Tamil Nadu-based producers are responding by segregating production lines between BIS-certified domestic output and REACH-compliant export grades.
Consolidated procurement by multi-national textile groups is displacing fragmented mill-level cone purchasing across South Asian supply chains. Centralized sourcing teams at headquarters in Dhaka and Hanoi now negotiate annual frame contracts with specified technical parameters. This concentration is most visible in Vietnam, where Park City and Phong Phu spinning complexes have reduced their active cone supplier base from twelve vendors to four qualified partners.
Spun Yarn Paper Cone Market Segmentation
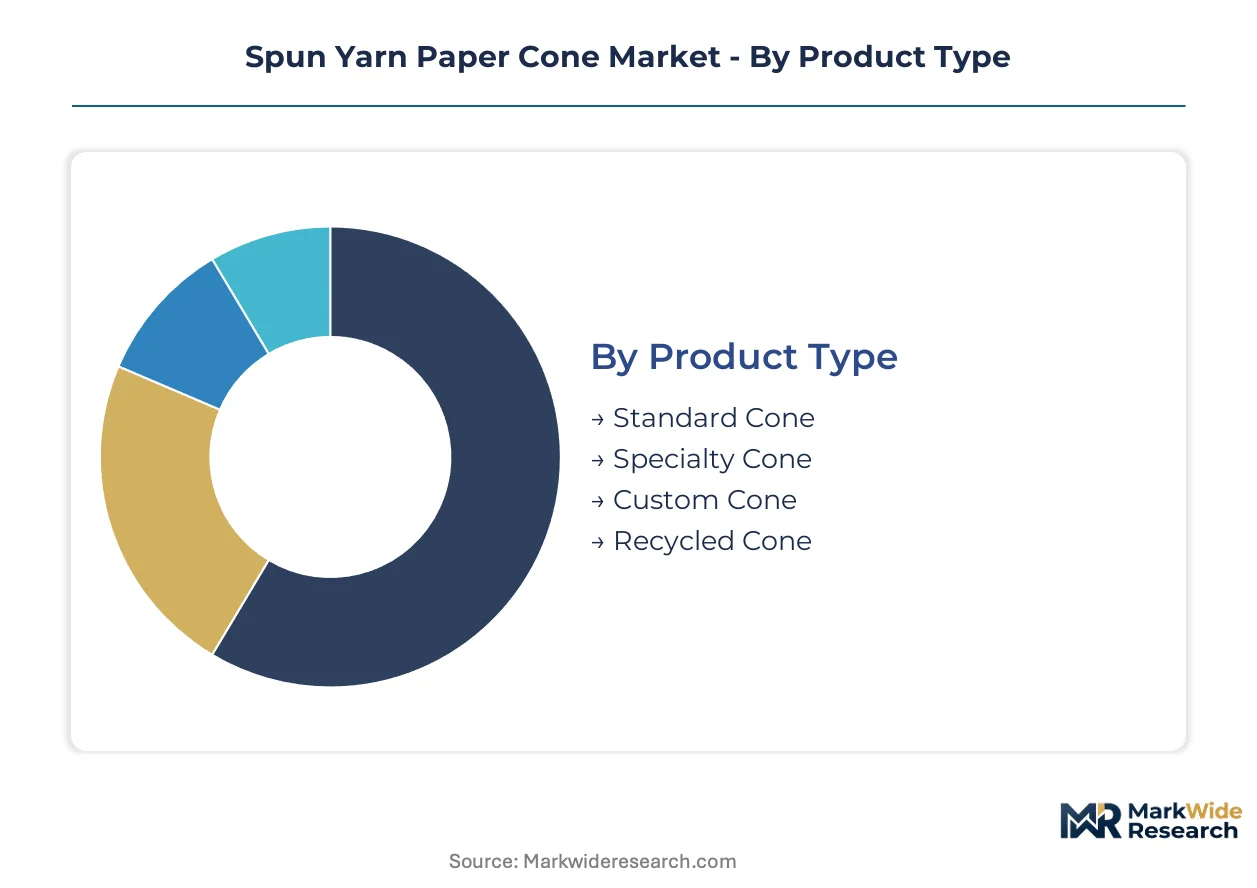
Segmentation in the spun yarn paper cone market reveals how procurement cycles and technical specifications diverge across end-use applications. Understanding these splits enables manufacturers to align production capacity with the velocity demands of textile mills versus the customization requirements of technical yarn producers.
Product Type:
Cycle times vary dramatically across cone categories, with commoditized formats turning inventory weekly while engineered variants require months of qualification.
- Standard Cone:Kraft pulp construction with fixed taper angles dominates high-volume ring spinning operations. Tamil Nadu textile mills consume these in continuous replenishment cycles driven by 25,000 RPM winding speeds. Standard Cone anchors the volume base while Recycled Cone gains share at the steepest rate.
- Specialty Cone:Precision-engineered wall thickness and crush-resistant geometries serve technical textile applications including tire cord and industrial sewing thread. Bangladeshi spinning complexes specify these for monsoon-season humidity tolerance where water-based barrier coatings replace wax treatments.
- Custom Cone:Bespoke taper angles and branded surface printing for premium yarn positioning.
- Recycled Cone:Post-consumer kraft content certified under circular procurement mandates from EU textile brands.
Standard Cone generates the production volume while Recycled Cone climbs fastest on sustainability-driven specification changes.
Application:
Cost tiers separate commodity yarn carriers from performance-critical industrial formats where failure carries downstream liability.
- Textiles:High-speed winding of ring-spun and open-end yarn in integrated spinning-weaving operations. Vietnam's Park City and Phong Phu complexes consolidate procurement here, reducing vendor counts from twelve to four qualified partners.
- Apparel:Fine count yarn cones for knitting and sewing thread with surface finish requirements for smooth unwinding.
- Home Furnishings:Coarser counts and heavier wall constructions for upholstery and decorative fabric yarn.
- Industrial Use:Glass fiber-reinforced kraft laminates withstand extreme centrifugal forces in tire cord and conveyor belt yarn. Gujarat manufacturers concentrate expertise here where crush resistance failures halt entire production lines.
Textiles commands the procurement volume while Industrial Use expands most quickly on technical material convergence.
Material:
Supply concentration in Latin American pulp sources creates margin exposure that shifts procurement toward recycled and composite alternatives.
- Pulp:Virgin kraft from Brazilian and Chilean mills remains the baseline feedstock for spiral-wound construction.
- Virgin Fiber:Bleached softwood kraft for premium surface appearance in branded yarn applications.
- Recycled Fiber:Post-consumer content specified by Tamil Nadu and Gujarat mills responding to BIS packaging standards and EU brand mandates. India's BIS certification timelines of 8-14 weeks create inventory bottlenecks for export-bound shipments using this feedstock.
- Composite Material:Glass fiber-reinforced laminates engineered for technical textile crush resistance. Ho Chi Minh City spinning parks exceed domestic converter capacity here, creating entry points for regional suppliers with cross-border logistics networks.
Pulp maintains the supply base while Composite Material shows the steepest expansion trajectory on technical performance requirements.
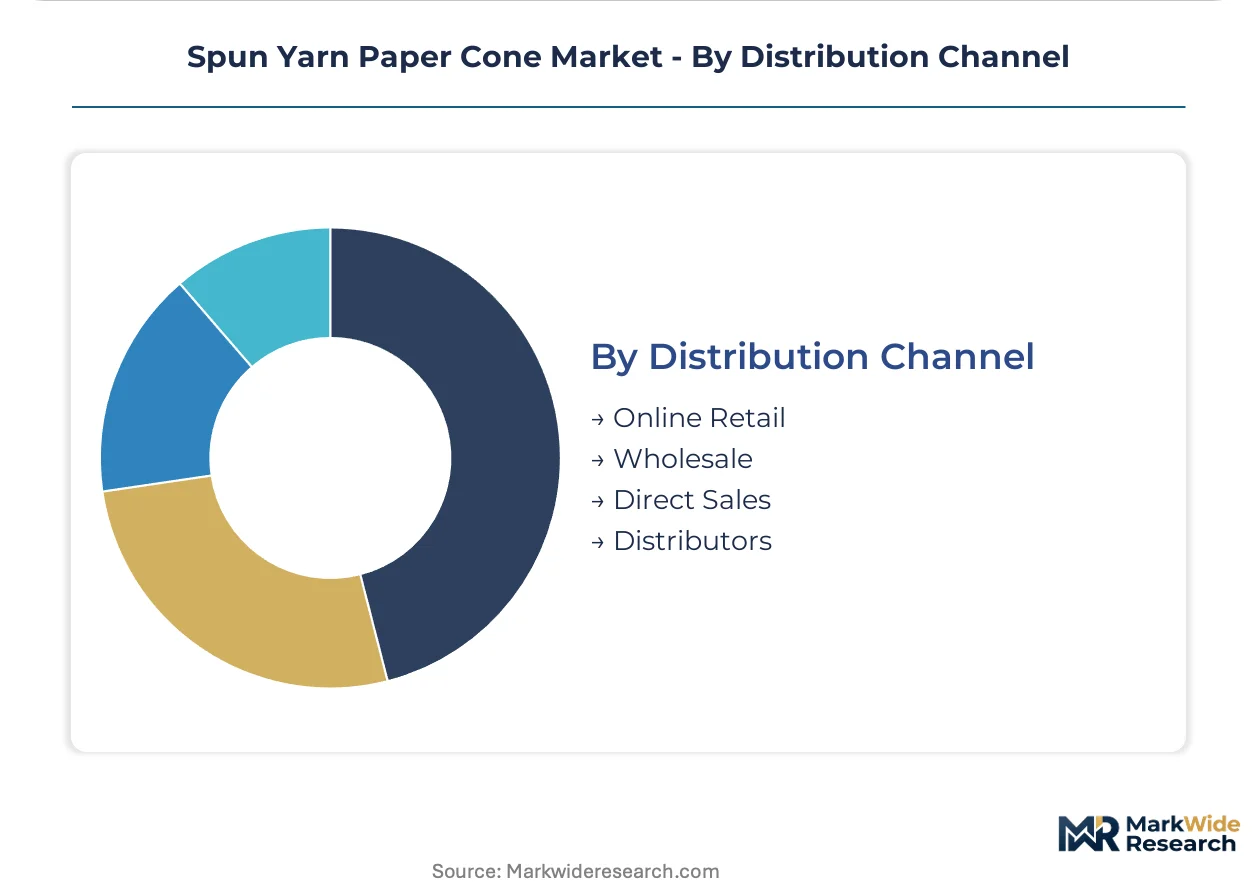
Distribution Channel:
Customer type fragmentation separates fragmented mill-level purchasing from centralized procurement teams that negotiate annual frame contracts.
- Online Retail:Digital specification exchange compresses sample approval cycles for small-batch technical yarn producers.
- Wholesale:Regional stockholding near Bangladesh and Vietnam textile clusters enables just-in-time replenishment.
- Direct Sales:Annual frame contracts with technical parameters negotiated by centralized sourcing teams in Dhaka and Hanoi headquarters. Pacific Cones leverages its regional distribution network to capture this concentrated demand.
- Distributors:Local inventory buffers for mills managing BIS certification delays and multi-jurisdiction compliance complexity.
Direct Sales captures the largest contract value while Online Retail grows fastest on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS packaging standards anchor the dominant geography, where Tamil Nadu and Gujarat textile belts concentrate cone demand from expanding domestic spinning capacity. Regional dynamics diverge sharply across South Asian manufacturing clusters, Latin American pulp supply zones, and Southeast Asian textile expansion corridors.
India
Tamil Nadu textile mills specify post-consumer kraft content in cone procurement, responding to BIS packaging standards mandating recycled content disclosure labeling. The national packaging regulator tightens adhesive emission thresholds for domestic market placement. Coimbatore and Tiruppur spinning clusters drive continuous replenishment cycles for standard cones rated above 25,000 RPM winding speeds.
Bangladesh
Textile groups pilot water-based barrier coatings for monsoon-season yarn storage, collapsing resistance to paper cone adoption in tropical humidity. The country's national textile regulator monitors chemical content in imported cone surface treatments. Dhaka-headquartered spinning complexes consolidate procurement from twelve vendors to four qualified partners under annual frame contracts.
Vietnam
Park City and Phong Phu spinning complexes generate cone demand exceeding domestic converter capacity, creating entry points for regional suppliers with cross-border logistics networks. The Ministry of Industry and Trade oversees packaging material import standards for textile machinery inputs. Ho Chi Minh City spinning parks anchor concentrated demand for composite material cones in technical yarn applications.
Brazil
Latin American pulp supply concentration exposes cone margins to freight rate spikes and currency fluctuations in Real-denominated contracts. The national environmental regulator enforces sustainable forestry certification for kraft pulp exports to Asian cone finishing plants. São Paulo-state pulp mills anchor virgin fiber supply chains feeding spiral-wound construction across South Asian manufacturing belts.
Germany
EU REACH chemical compliance protocols grant preferential access to European textile brands enforcing circular procurement mandates for cone adhesives. ECHA governs chemical content thresholds in surface treatments and adhesive bonding agents. Baden-Württemberg technical textile producers specify precision-engineered cone geometries for industrial sewing thread and tire cord applications requiring enhanced crush resistance.
Spun Yarn Paper Cone Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around regional specialists with spiral winding expertise and multinational converters with cross-border pulp-to-cone supply chains. Three archetypes dominate: South Asian integrated manufacturers co-located near textile clusters, Latin American pulp-anchored converters with finishing operations in Asia, and European precision-engineering specialists serving technical textile applications. Competitive moves concentrate on capacity co-location near Bangladeshi and Vietnamese textile parks, and certification stacking for simultaneous BIS, REACH, and GB standard compliance.
Among India-based fabricators, Shivshakti Paper Cone and SKS Paper Products occupy positions within the regional specialist tier, while Sonoco Products Company exemplifies the multinational converter archetype with technical leadership in precision-engineered geometries. Pacific Cones represents the logistics-integrated regional supplier model, leveraging distribution networks to capture concentrated demand from Dhaka and Hanoi headquarters procurement teams.
| Leading Market Players |
|---|
| Pacific Cones |
| Sonoco Products Company |
| Conitex Sonoco |
| Shivshakti Paper Cone |
| SKS Paper Products |
| Shree Laxmi Corporation |
| Saroja Texcone |
| Sundaram Paper Products |
| Kaylor Rotomoulders |
| Others |
Value Network & Pricing Analysis
Kraft pulp price volatility in Brazilian Real-denominated contracts determines both the spread between virgin and recycled cone tiers and the geographic configuration of finishing operations near South Asian textile clusters. Latin American pulp supply concentration exposes cone margins to freight rate spikes, compressing pricing power for converters without backward integration into pulp sourcing while accelerating regional co-location strategies.
Pricing Analysis
Price spreads between Tamil Nadu and Ho Chi Minh City suppliers reflect freight differentials and certification cost burdens rather than quality divergence alone. Three-tier pricing structure across REACH-compliant export grades, BIS-certified domestic output, and uncertified commodity cones anchors the market, with EU-bound shipments commanding premiums for adhesive emission documentation. Cost compression in standard cone tiers is intensifying because Vietnamese textile mills consolidate vendor bases under annual frame contracts. Small-scale Gujarat spinners exhibit highest price sensitivity, while German technical textile producers prioritize crush resistance specifications over unit cost.
Supply Chain Analysis
Spiral winding capacity concentrates among aging workforces in Gujarat and Tamil Nadu manufacturing belts, with Sonoco Products Company and Pacific Cones anchoring regional finishing networks. Virgin kraft pulp feeds from Brazilian São Paulo-state mills and Chilean forestry operations, while recycled fiber supply chains draw from post-consumer collection networks in South Asia. Single-source vulnerability in Latin American pulp exposes cone producers to currency-driven input cost spikes. Distribution runs through direct sales channels negotiated by centralized procurement teams in Dhaka and Hanoi headquarters, supplemented by wholesale stockholding near Bangladeshi textile parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polypropylene cone substitution in coarse count yarn above Ne 20 threatens paper cone incumbents with volume displacement unless technical performance differentiation hardens.
For Market Incumbents: Insulate core ring spinning accounts by embedding water-based barrier coating specifications into monsoon-season procurement contracts with Bangladeshi textile groups. Deepen upstream control over certified recycled pulp supply chains to offset Brazilian Real volatility and secure BIS compliance timelines. Prioritize composite material R&D investments for tire cord and industrial sewing thread applications where crush resistance failures halt production lines. For New Entrants and Emerging Players: Build out cross-border logistics networks targeting Ho Chi Minh City spinning parks where domestic converter capacity falls short of composite material cone demand. Capture white-space in digital specification exchange platforms that compress sample approval cycles for small-batch technical yarn producers. Lead with water-based barrier coating formulations to displace plastic cone adoption in tropical humidity applications previously dependent on synthetic carriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors logistics-integrated regional suppliers with multi-jurisdiction certification capabilities over pure-play spiral winding specialists. Acquisition targets should demonstrate parallel BIS, REACH, and GB standard compliance infrastructure alongside established relationships with centralized procurement teams in Dhaka and Hanoi. Quarterly review of vendor consolidation velocity at Vietnamese Park City and Phong Phu complexes is advised to detect inflection toward captive cone production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Supply | Secures BIS-certified feedstock streams for Tamil Nadu domestic market placement. |
| Multi-Jurisdiction Certification Stacking | Enables simultaneous REACH, BIS, and GB compliance for unified export-domestic production. |
| Co-location Near Vietnamese Textile Parks | Captures concentrated demand from Park City and Phong Phu spinning complexes exceeding domestic capacity. |
| Water-Based Barrier Coating Scale-Up | Collapses plastic cone cost advantage in Bangladeshi monsoon-season yarn storage applications. |
| Composite Material Technical Partnership | Addresses glass fiber-reinforced kraft laminate specifications for tire cord crush resistance requirements. |
Research Methodology
Initial hypotheses were tested against primary input from spiral winding technicians, textile mill procurement managers, pulp supply specialists, and BIS certification consultants and refined through secondary validation against customs trade records, BIS packaging standard filings, EU REACH registration databases, and SEC 10-K disclosures from multinational converters. Bottom-up demand modeling from individual spinning complex consumption patterns was triangulated against top-down pulp supply flow analysis across Brazilian and Chilean export corridors.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by cone type, application intensity, material grade tier, and regional regulatory cluster. CAGRs were derived from installed spinning capacity expansion trajectories in Bangladesh and Vietnam cross-referenced with cone consumption coefficients per thousand spindles. Forecast inputs incorporated BIS certification timeline bottlenecks and EU circular procurement mandate adoption curves without specifying implementation dates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by South Asian textile groups into captive cone production would shift outcomes beyond modeled ranges. Quarterly review of vendor consolidation announcements at Dhaka and Hanoi headquarters and BIS adhesive emission threshold revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market