
 South Korea Textile Market | 2026-2036
South Korea Textile Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Textile Market Insights
Digital textile printing as a subscription-enabled service layer is restructuring how South Korean mills monetize capacity. Hyosung TNC Corp leverages its spandex vertical to sustain domestic supply chain control. Kolon Materials, Inc. anchors the industrial fabrics segment through aramid fiber specialization. Hansae Yes24 competes on fast-fashion contract manufacturing scale for global apparel brands.
South Korea textiles encompass natural and engineered fibers woven, knitted, or non-woven into fabrics with specified tensile strength, denier counts, and finish treatments for end-use performance. The primary commercial purpose spans wearable goods, interior furnishings, and load-bearing industrial applications where material specifications determine functional outcomes. Synthetic fibers lead production volume due to petrochemical feedstock proximity in Ulsan and Yeosu cluster zones. Technical textiles represent the fastest-expanding application segment as automotive and construction buyers specify flame-retardant and high-tenacity material grades. Cotton and wool categories occupy mature positions with limited margin expansion potential relative to performance-oriented alternatives.
MFDS textile safety standards, KOTITI testing protocols, and Ministry of Environment chemical discharge regulations collectively shape product compliance costs and factory certification requirements for South Korean producers. The Korea Agency for Technology and Standards enforces fiber content labeling that directly influences export market access conditions. Stakeholders must monitor how carbon border adjustment mechanisms in destination markets will alter the cost structure of Korean textile exports.
Market Dynamics
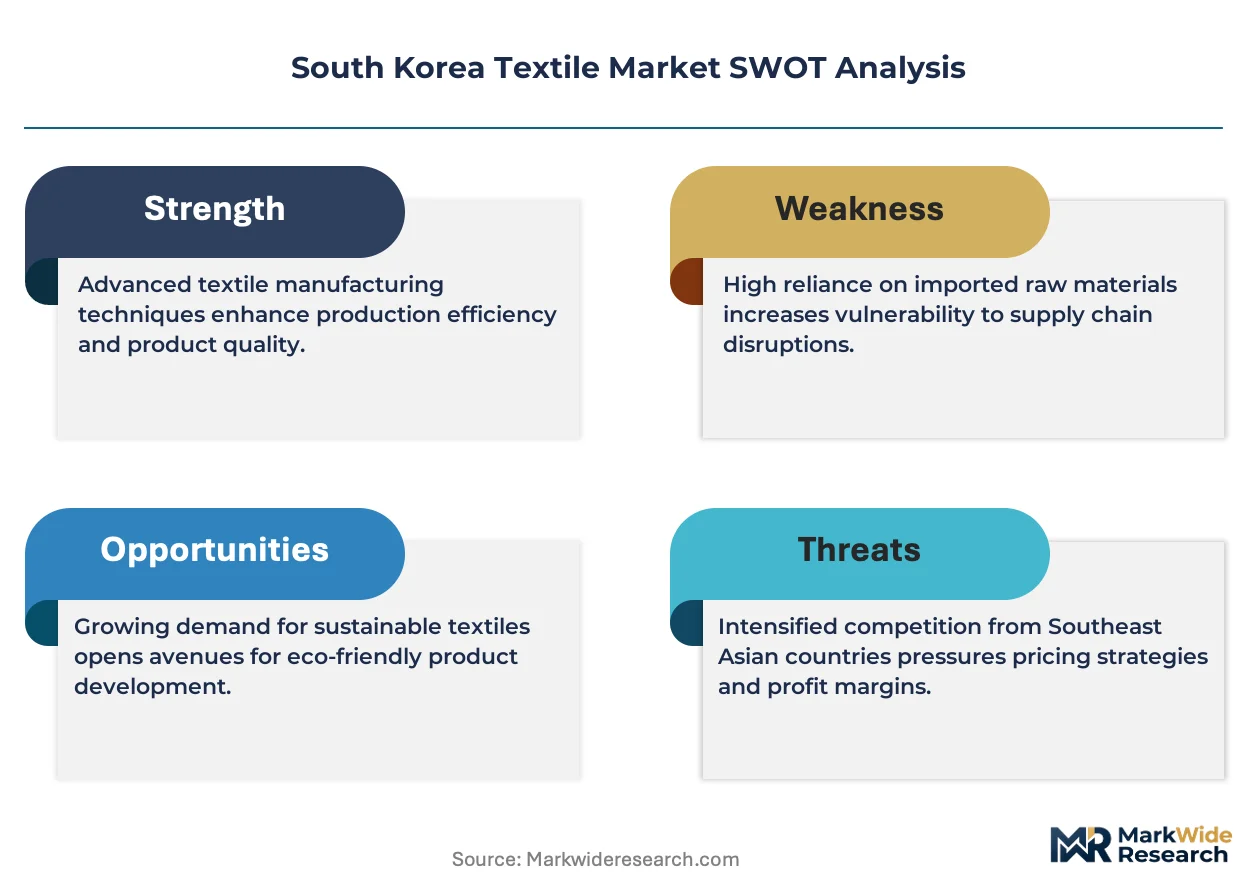
Smart manufacturing mandates from the Ministry of Trade, Industry and Energy are compressing legacy production timelines while forcing capital redeployment toward automated dyeing and finishing systems across the Gyeonggi-do corridor.
Growth Catalysts
- Automotive technical textile specification:Hyundai Mobis and Tier 1 suppliers are expanding flame-retardant fabric orders for electric vehicle battery enclosures and interior assemblies.
- MFDS safety standard harmonization:Aligned testing protocols with EU REACH and Japan's PMDA textile guidelines are reducing duplicate certification costs for export-oriented mills.
- Ulsan-Yeosu petrochemical feedstock proximity:Synthetic fiber producers capture 15-20% logistics cost advantages versus import-dependent competitors in Southeast Asia.
Market Restraints
- Para-aramid fiber import dependency:Domestic producers rely on DuPont and Teijin for high-tenacity fiber feedstock, exposing margins to yen-dollar volatility and shipping lane congestion.
- Ministry of Environment chemical discharge limits:Stricter COD and heavy metal effluent standards are forcing 30-40% of small dye houses into compliance-driven consolidation or closure.
- Polyester staple fiber substitution pressure:Recycled PET flake imports from Southeast Asia are undercutting virgin fiber pricing in commodity non-woven applications.
Strategic Opportunities
- Carbon fiber textile preforms for hydrogen storage:Kolon and Hyosung R&D pipelines target Type IV pressure vessel markets as Korea's hydrogen economy roadmap accelerates domestic offtake.
- Jeolla-do underutilized spinning capacity:Aging cotton mills in Gwangju and Jeonju offer retrofit-ready infrastructure for technical textile conversion at 40-60% of greenfield capex.
- Digital textile printing as-a-service:Subscription-based capacity access allows small apparel brands to bypass minimum order quantity constraints imposed by traditional rotary screen houses.
Industry Challenges
- Smart factory technician scarcity:PLC programming and IoT sensor calibration skills command 35-50% wage premiums over traditional textile engineering graduates, constraining automation rollout timelines.
- KOTITI multi-standard certification backlog:Testing queue delays of 8-12 weeks for Oeko-Tex and ISO 9001 renewals are freezing export shipment schedules for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Textile Market |
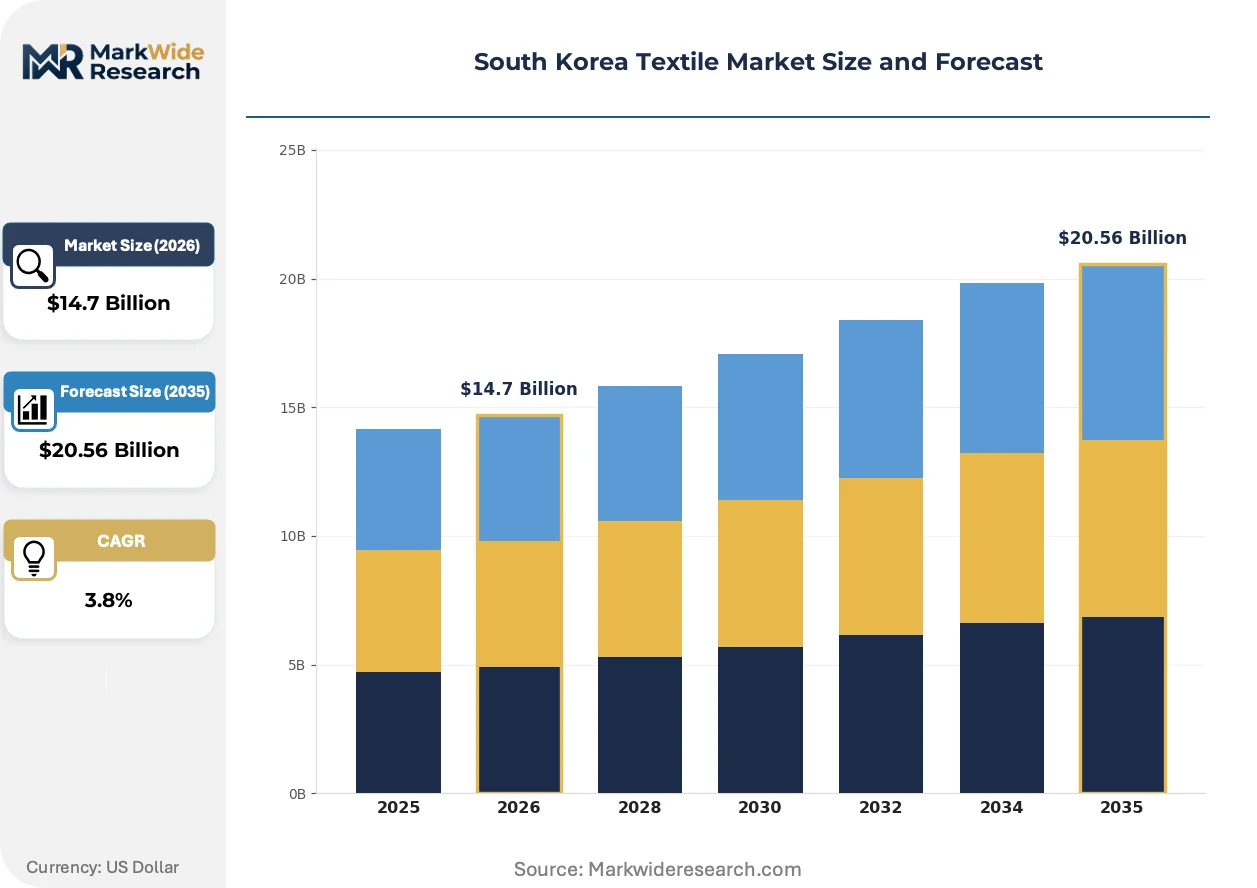
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $20.56 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Wool, Synthetic, Linen Application: Apparel, Home Textiles, Industrial Fabrics, Technical Textiles Distribution Channel: Online Retail, Wholesale, Specialty Stores, Department Stores End User: Fashion Brands, Manufacturers, Exporters, Retailers |
| Companies Covered | DSR Corp, Allerman co., Ltd., Hyosung TNC Corp, Shinwon, The Willbes & Co., Ltd., Kolon Materials, Inc., Texview Corporation, Hansae Yes24, Hojeon Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Textile Market Trends and Innovations
Production technology and compliance frameworks are rewriting competitive boundaries. Mills that synchronize dye chemistry advances with regulatory pre-certification are capturing disproportionate share in automotive and medical textile supply chains.
AI-driven color matching systems are integrating spectrophotometry data with dye recipe databases to cut lab dip approval cycles from five days to under four hours. Tier 1 automotive seating suppliers are mandating these systems for supplier qualification. The technology is integrating quality control and production scheduling into unified workflow platforms that compress total lead times by 20-30%.
MFDS textile safety standards are tightening heavy metal and formaldehyde thresholds for infant and skin-contact products, effective across all domestic production and import channels. Testing costs per SKU have risen 15-25% as laboratories expand GC-MS and atomic absorption spectroscopy capacity. Children's wear and bedding segments are absorbing these costs through supplier consolidation toward vertically integrated mills with captive testing facilities.
Apparel procurement is fragmenting toward micro-batch, near-shore sourcing as global brands compress design-to-retail cycles below eight weeks. Hansae Yes24 and similar contract manufacturers are restructuring floor layouts to handle 500-unit minimums versus traditional 10,000-unit runs. This behavioral shift concentrates in Seoul-based fast-fashion headquarters where real-time sales data triggers immediate replenishment orders to Gyeonggi-do cut-and-sew clusters.
South Korea Textile Market Segmentation
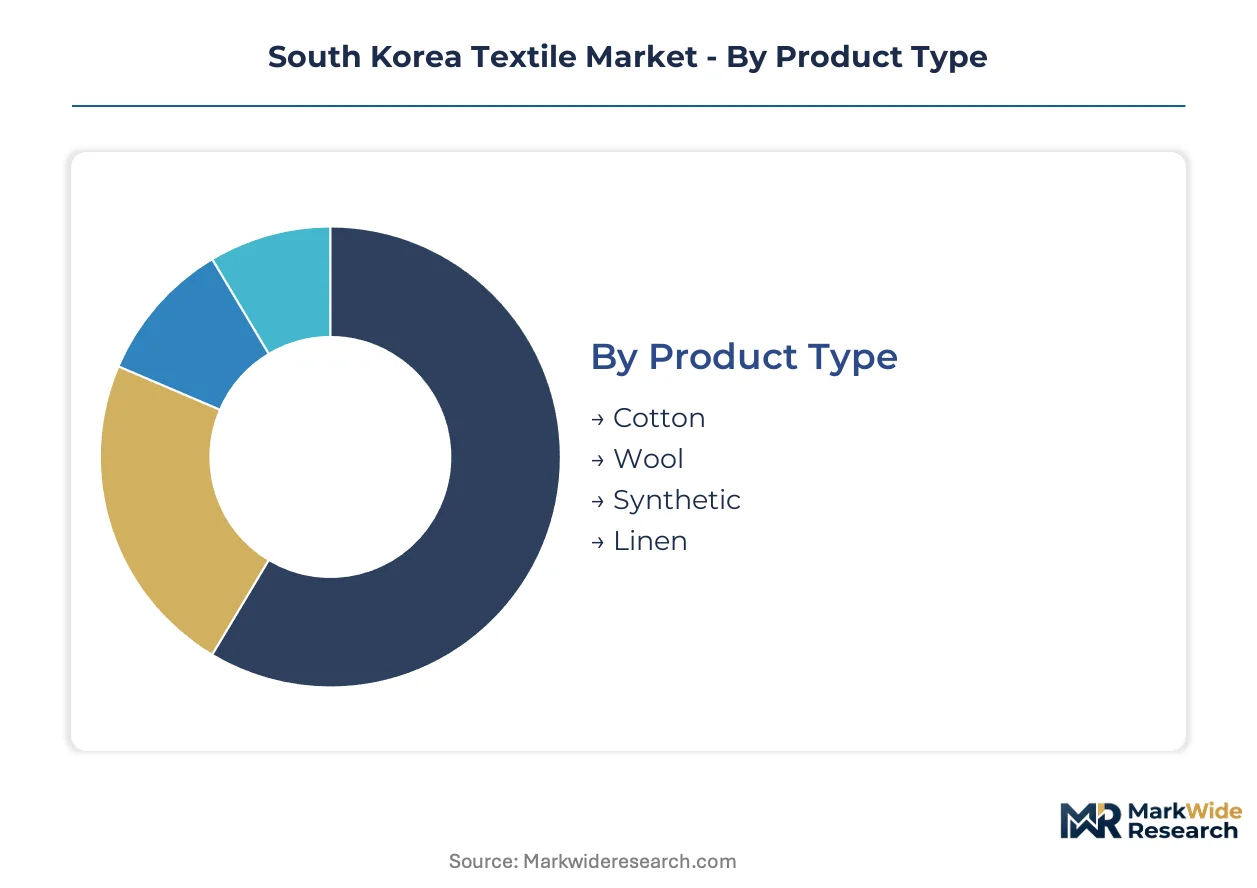
South Korean mills segment output to align fiber capabilities with distinct compliance and margin profiles. Each category reflects how production assets cluster around Gyeonggi-do technical centers versus Jeolla-do commodity spinning.
Product Type:
Supply concentration in the Ulsan-Yeosu petrochemical corridor locks in synthetic fiber dominance, while natural fiber processing migrates toward legacy cotton belt infrastructure.
- Cotton:Grown primarily through import dependency on US and Australian lint. Gwangju spinning houses process short-staple varieties for domestic apparel basics under BCI sustainability protocols.
- Wool:Specialty worsted weaving survives in Daegu heritage mills serving tailored menswear brands. Import volumes from New Zealand and Argentina constrain margin expansion due to currency hedging costs.
- Synthetic:Polyester and nylon filament production anchors the Ulsan-Yeosu cluster with direct petrochemical feedstock access. Technical textile specifications from Hyundai Mobis and battery enclosure manufacturers drive high-tenacity fiber R&D.
- Linen:Belgian and French flax imports supply small-batch summerwear producers in Seoul's Seongsu-dong design district. Limited domestic cultivation restricts scale.
Today's leader: Synthetic. Tomorrow's challenger: Cotton sustainability premiums.
Application:
Margin profiles diverge sharply between commodity apparel contracting and specialized industrial certifications.
- Apparel:Cut-and-sew contractors in Gyeonggi-do execute fast-fashion orders for global brands with eight-week design-to-retail cycles. Micro-batch capabilities at Hansae Yes24 and similar manufacturers compress minimum order quantities to 500 units.
- Home Textiles:Bedding and curtain fabrics face MFDS heavy metal testing requirements that favor vertically integrated mills with captive KOTITI laboratories. Children's products absorb 15-25% higher testing costs per SKU.
- Industrial Fabrics:Aramid and carbon fiber preforms from Kolon Materials target conveyor belting and composite reinforcement. Jeolla-do retrofit spinning capacity offers 40-60% cost advantages versus greenfield technical textile investment.
- Technical Textiles:Flame-retardant automotive fabrics for electric vehicle battery enclosures represent the steepest expansion trajectory. Hyundai Mobis Tier 1 specifications require AI-driven color matching systems that cut lab dip cycles from five days to four hours.
Certification-heavy segments command pricing power; commodity apparel runs on volume throughput.
Distribution Channel:
Channel selection determines working capital intensity and inventory risk allocation between mills and downstream partners.
- Online Retail:Seoul-based direct-to-consumer brands leverage digital textile printing subscription services to bypass rotary screen minimums. Real-time sales data triggers immediate replenishment orders to Gyeonggi-do cut-and-sew clusters.
- Wholesale:Dongdaemun Market intermediaries aggregate small brand orders for consolidated production runs. This channel concentrates payment risk with 60-90 day receivables typical.
- Specialty Stores:Premium fabric retailers in Gangnam and Garosu-gil curate imported European linens and Japanese selvedge denims. Limited SKU breadth supports 40-60% gross margins.
- Department Stores:Lotte and Hyundai department store textile halls emphasize domestic heritage brands with MFDS safety pre-certification. Floor space allocation favors suppliers with captive testing facilities.
Direct digital channels expand fastest; wholesale retains volume concentration.
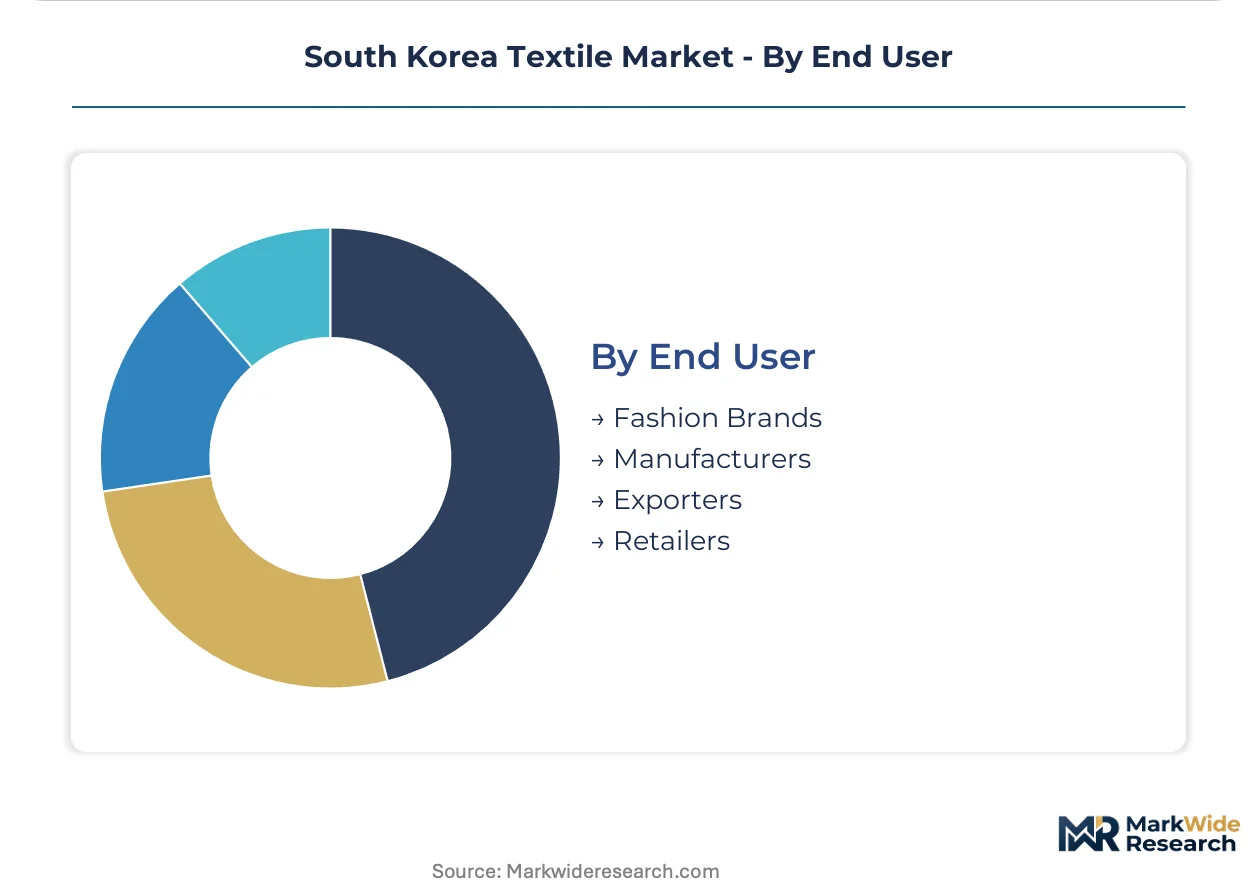
End User:
Buyer sophistication around technical specifications and compliance documentation separates premium contract opportunities from price-driven tenders.
- Fashion Brands:Global headquarters in Seoul's Gangnam district demand micro-batch agility and Oeko-Tex certification. Design-to-retail cycles below eight weeks favor Gyeonggi-do manufacturers with AI-integrated production scheduling.
- Manufacturers:Tier 1 automotive seating suppliers mandate spectrophotometry-linked dye recipe databases for supplier qualification. PLC programming capabilities command 35-50% wage premiums over traditional textile engineering skills.
- Exporters:EU and US destination markets drive REACH and CPSIA compliance investments. Carbon border adjustment mechanisms threaten polyester staple fiber competitiveness against Southeast Asian recycled PET imports.
- Retailers:Domestic mass-market chains consolidate procurement toward vertically integrated mills with captive KOTITI testing. Multi-standard certification backlogs of 8-12 weeks freeze shipment schedules for mid-tier producers.
Automotive manufacturers set the technical bar; exporters face the steepest compliance cost curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions where compliance cost gaps favor technical textile specialization. South Korea's regulatory alignment with EU REACH and Japan's PMDA standards creates export arbitrage opportunities that concentrate investment in specific sub-regional clusters.
Seoul Capital Area
Hyundai Mobis and Tier 1 automotive seating suppliers drive flame-retardant fabric demand for electric vehicle battery enclosures. MFDS safety standard harmonization with EU guidelines reduces duplicate certification burdens for export-oriented mills. Gyeonggi-do industrial corridor hosts AI-driven color matching systems that compress lab dip approval cycles from five days to under four hours.
Busan-Ulsan
Synthetic fiber producers capture logistics cost advantages through direct petrochemical feedstock access in the Ulsan-Yeosu cluster. Ministry of Environment chemical discharge regulations force consolidation among small dye houses unable to meet stricter COD and heavy metal effluent standards. Ulsan-based filament operations supply high-tenacity fiber specifications for conveyor belting and composite reinforcement applications.
Daegu-Gyeongbuk
Heritage worsted weaving mills serve tailored menswear brands with specialty wool processing capabilities. Import dependency on New Zealand and Argentine wool constrains margin expansion due to currency hedging costs. Daegu retains limited-scale cotton spinning for domestic apparel basics under BCI sustainability protocols.
Daejeon-Sejong
Korea Agency for Technology and Standards enforcement of fiber content labeling influences export market access conditions for regional producers. Smart manufacturing mandates from the Ministry of Trade, Industry and Energy accelerate automated dyeing system deployment. Sejong administrative city proximity facilitates regulatory coordination for technical textile certification pipelines.
Gwangju-Honam
Aging cotton mills in Gwangju and Jeonju offer retrofit-ready infrastructure for technical textile conversion at 40-60% of greenfield capital expenditure. Jeolla-do underutilized spinning capacity attracts investors targeting carbon fiber textile preforms for hydrogen storage applications. Regional wage differentials versus Seoul Capital Area support cost-competitive technical textile labor pools.
South Korea Textile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical textile producers commanding premium positioning against commodity apparel contractors. The vendor base organizes around three tiers: petrochemical-integrated synthetic fiber giants, automotive-certified industrial fabric specialists, and fast-fashion contract manufacturers competing on minimum order quantity flexibility. Strategic moves concentrate on backward integration into spandex and aramid feedstocks, plus geographic expansion through Jeolla-do capacity retrofits.
Among South Korea-based fabricators, Hyosung TNC Corp, Kolon Materials, Inc., and Hansae Yes24 occupy distinct archetype positions. Hyosung TNC Corp exemplifies the petrochemical-integrated synthetic fiber model with captive spandex vertical control. Kolon Materials, Inc. anchors the industrial fabrics segment through specialized fiber capabilities. Hansae Yes24 represents the contract manufacturing tier competing on micro-batch agility for global apparel brands with compressed design-to-retail cycles.
| Leading Market Players |
|---|
| DSR Corp |
| Allerman co., Ltd. |
| Hyosung TNC Corp |
| Shinwon |
| The Willbes & Co., Ltd. |
| Kolon Materials, Inc. |
| Texview Corporation |
| Hansae Yes24 |
| Hojeon Ltd |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap mills in the Gyeonggi-do corridor maintain pricing discipline through captive dye-house operations and long-term automotive supply contracts. Their ownership structure limits external financing pressure, allowing selective order acceptance that sustains margin floors despite polyester staple fiber import competition.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for commodity apparel contracting, forcing Korean mills toward premium-mid-economy pricing differentiation. Oeko-Tex certification tier and automotive qualification status separate pricing bands, with flame-retardant technical textiles commanding substantial premiums over basic cut-and-sew work. Cost compression in standard-grade non-wovens is intensifying because recycled PET flake imports undercut virgin fiber production. Exporters to EU markets show least price sensitivity due to carbon border adjustment pass-through mechanisms, while domestic wholesale channels face acute margin pressure.
Supply Chain Analysis
KOTITI multi-standard certification gates supplier qualification for Hyundai Mobis and Tier 1 automotive seating manufacturers, creating structural bottlenecks. Geographic supply concentration centers on South Korea, China, and Vietnam for finished textiles, with para-aramid fiber feedstock drawing from DuPont and Teijin in the United States and Japan. Single-source vulnerability in high-tenacity fiber imports exposes margins to yen-dollar volatility and shipping lane congestion. Distribution runs through Gyeonggi-do cut-and-sew clusters for domestic fulfillment and Busan port consolidation for export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as automotive technical textile specifications displace commodity apparel contracting. Tier 1 battery enclosure fabric orders reward mills with MFDS pre-certification and AI-driven color matching infrastructure.
For Market Incumbents: Cement automotive supply chain positioning through captive KOTITI testing facilities and spectrophotometry-linked dye recipe databases. Kolon Materials and Hyosung TNC demonstrate how backward integration into aramid and spandex feedstocks insulates margins from import dependency. Defensive consolidation of Jeolla-do retrofit spinning capacity at 40-60% greenfield cost extends technical textile production without capital intensity. For New Entrants and Emerging Players: Small-batch apparel brands with sub-500-unit minimums represent the most penetrable buyer archetype underserved by rotary screen houses. Digital textile printing subscription services bypass traditional capacity constraints and capture real-time replenishment demand from Seoul-based fast-fashion headquarters. Target carbon fiber textile preform production for hydrogen storage pressure vessels as Korea's hydrogen economy roadmap accelerates domestic offtake. For Investors and Strategic Acquirers: Valuations sit cheapest among aging cotton mills in Gwangju and Jeonju with retrofit-ready infrastructure for technical textile conversion. Long-term viability favors assets with automotive qualification pipelines and regulatory pre-certification capabilities. Watch for MFDS testing queue normalization below four weeks as inflection signal for mid-tier export capacity utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spandex Feedstock | Hyosung TNC's captive supply chain control insulates margin from petrochemical volatility. |
| Automotive Qualification Investment | AI-driven color matching systems cut lab dip cycles from five days to four hours for Tier 1 suppliers. |
| Jeolla-do Capacity Retrofit | Aging Gwangju spinning mills convert to technical textile production at 40-60% of greenfield capital expenditure. |
| Digital Printing Subscription Launch | Micro-batch capacity access captures 500-unit minimum orders from Seoul fast-fashion headquarters. |
| KOTITI Pre-Certification Pipeline | Captive testing facilities eliminate 8-12 week certification backlogs freezing export shipments. |
Research Methodology
Bottom-up automotive and apparel demand modeling reconciled against top-down synthetic fiber production tracking forms the analytical core of this study. Primary interviews with textile plant managers, Tier 1 supplier procurement leads, KOTITI certification officers, and MFDS regulatory affairs specialists combined with secondary validation from Korea Agency for Technology and Standards fiber content labeling records, Ministry of Environment effluent compliance disclosures, and customs trade data. Triangulation across these sources calibrated market sizing and growth trajectory assumptions.
Input-output matrices map filament production capacity through downstream cut-and-sew clusters across the analysis window. Segmentation dimensions include fiber type, application category, distribution channel, and end-user sophistication tier. CAGRs derive from production volume trends correlated with automotive platform launches and fast-fashion procurement cycle compression. Hydrogen economy roadmap milestones and carbon border adjustment implementation timelines inform scenario-weighted projections.
Inputs from KOTITI certification databases and Ministry of Trade, Industry and Energy smart manufacturing mandate disclosures were available through the study window; gaps in real-time small dye-house closure rates introduce uncertainty bands around consolidation velocity assumptions. Forecasts reflect documented assumptions regarding technical textile specification adoption curves and recycled PET import substitution elasticity. A model refresh is warranted upon material change in EU carbon border adjustment mechanism scope or MFDS heavy metal threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Parachute Fabric Market