
 Ring Spinning Frame Market | 2026-2036
Ring Spinning Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Ring Spinning Frame Market Insights
Compact spinning specifications is rotating demand toward higher-yarn-quality configurations across major textile corridors. Rieter leverages its integrated spindle technology platform to sustain premium positioning in European and Asian mills. Lakshmi Machine Works anchors its competitive stance through manufacturing scale and cost-engineered conventional ring frames serving South Asian yarn producers. Saurer differentiates via automation intensity, embedding autoconer linkages that reduce labor dependence in large-scale operations.
A ring spinning frame is a textile machine that twists drawn roving into yarn using a rotating spindle and traveler ring system, typically operating at speeds up to 25,000 rpm for fine-count cotton and synthetic blends. The equipment serves as the final formation stage in short-staple yarn production, delivering ring-spun yarn with superior strength and evenness for downstream weaving and knitting. Compact spinning technology within the technology dimension commands margin concentration as mills retrofit existing conventional ring frames to reduce hairiness and improve downstream processing efficiency. Apparel manufacturing within the application dimension absorbs the dominant volume share, though technical textiles represents the fastest-expanding addressable pool as industrial filtration and composite reinforcement specifications tighten.
India's BIS machinery safety standards and the EU's Ecodesign Directive together elevate compliance thresholds for new frame installations, effectively filtering out obsolete mechanical platforms from regulated markets. The EU F-Gas Regulation and REACH chemical frameworks further constrain lubricant and cooling system choices, pushing OEMs toward sealed bearing designs and synthetic oil alternatives. Stakeholders must monitor how dual carbon commitments in China and the EU's CBAM extension reshape the cost calculus of imported yarn versus domestic ring-spun production.
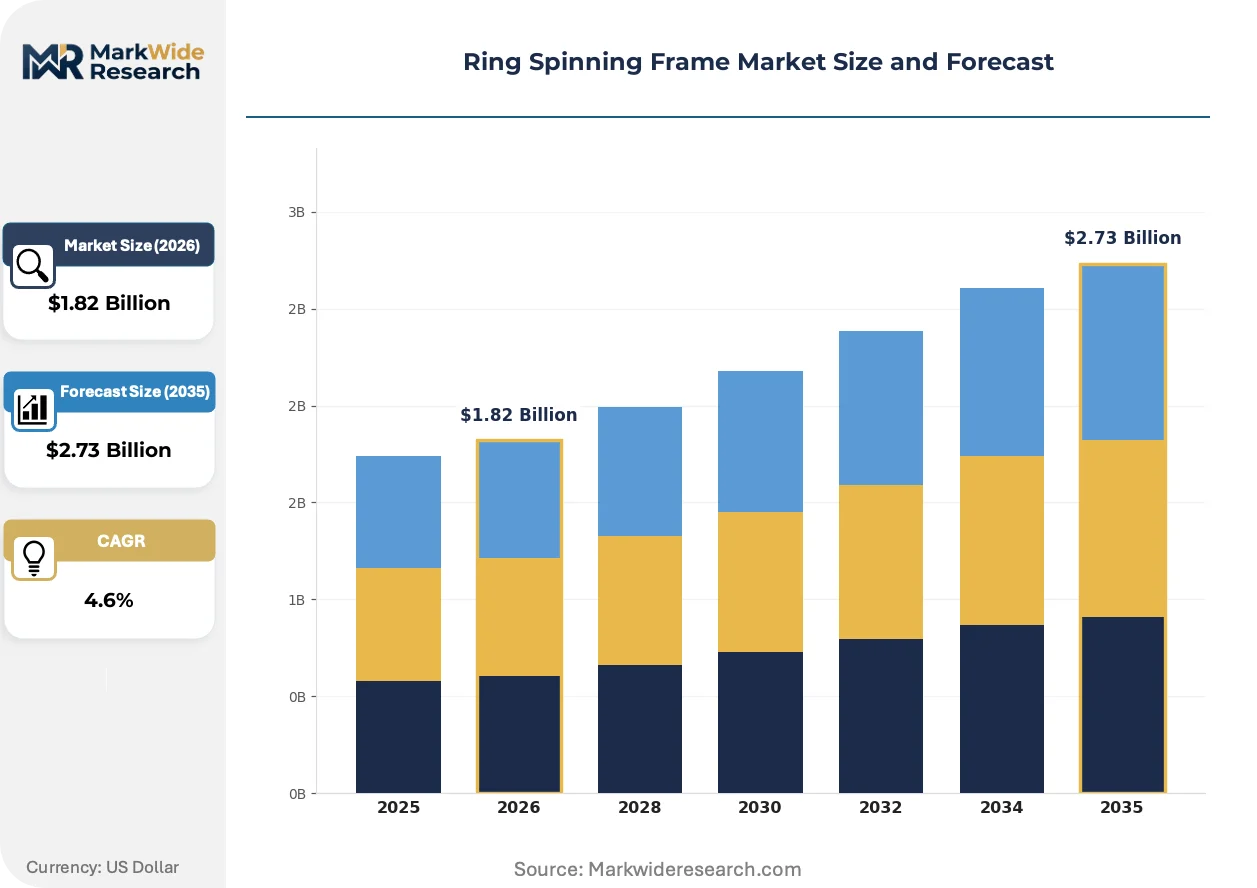
Market Dynamics
Compact spinning retrofits are compressing replacement cycles across established textile corridors as mills prioritize yarn quality premiums over extended equipment lifecycles. The shift from mechanical to mechatronic spindle platforms concentrates procurement decisions among OEMs with integrated automation portfolios.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates for textile machinery in Germany and Turkey accelerate compact spinning upgrades that reduce power consumption per kilogram of yarn output.
- India PLI scheme for textiles:Domestic apparel manufacturers expand captive yarn-making capacity under production-linked incentives, pulling ring frame demand toward higher-speed configurations.
- Technical textile filtration specifications:Industrial air and liquid filtration standards tighten across automotive and chemical processing end-uses, requiring low-hairiness ring-spun yarn for membrane substrates.
Market Restraints
- Aluminum alloy price volatility:Spindle housing and ring rail raw material costs fluctuate with London Metal Exchange pricing, compressing OEM margins on fixed-price contracts.
- Spindle component supply concentration:Precision bearing and traveler manufacturing clusters in Switzerland and Japan create single-source dependencies for high-speed frame configurations.
- Skilled maintenance technician scarcity:Mechatronic platform diagnostics require electro-mechanical hybrid competencies that vocational training pipelines in South Asia have not scaled to match installation rates.
Strategic Opportunities
- Vietnam textile corridor expansion:Apparel export manufacturing zones in Binh Duong and Dong Nai provinces lack sufficient domestic yarn supply, creating import substitution demand for ring-spun capacity.
- Autoconer linkage retrofit kits:Automation convergence between ring frames and winding systems enables labor reduction in large-scale Indian and Bangladeshi mills without full line replacement.
- EU CBAM extension to textiles:Carbon border adjustments on imported yarn elevate cost parity for domestic European ring-spun production against Asian imports.
Industry Challenges
- Legacy mechanical frame obsolescence:Conventional ring frame platforms lack sensor integration points for Industry 4.0 monitoring, forcing parallel infrastructure investment during upgrades.
- BIS machinery certification timelines:Indian safety standard testing backlogs delay commercial commissioning of imported high-speed configurations by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ring Spinning Frame Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Ring Frame, Conventional Ring Frame, Autoconer, Rotor Spinning Technology: Air Spinning, Compact Spinning, Open-End Spinning, Friction Spinning Application: Apparel Manufacturing, Home Textiles, Industrial Textiles, Technical Textiles End User: Textile Manufacturers, Yarn Producers, Fabric Processors, Garment Makers |
| Companies Covered | Rieter, Saurer, Lakshmi Machine Works, Toyota Industries, Trützschler, Savio Macchine Tessili, Muratec, Marzoli Machines Textile, Zinser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ring Spinning Frame Market Trends and Innovations
Digital spindle monitoring platforms are rewriting maintenance economics across textile manufacturing floors. Real-time vibration and temperature analytics now enable predictive interventions that compress unplanned downtime intervals.
Magnetic levitation spindle bearings is supplanting conventional ball-bearing assemblies in premium frame configurations. Technical textile producers in Germany and Switzerland adopt these systems to sustain speeds above 22,000 rpm for fine-count synthetic yarn. The technology is supplanting mechanical bearing maintenance schedules with contactless operation that extends service intervals by factor of three.
REACH chemical frameworks constrain lubricant formulation choices for European frame installations. ECHA substance restrictions on mineral oil additives push OEMs toward synthetic polyalphaolefin alternatives with narrower temperature operating windows. Filtration and automotive yarn segments face reformulation costs that disadvantage smaller mills lacking chemical compliance expertise.
Mill procurement committees now unbundle after-sales service from equipment purchase contracts. Large South Asian textile groups negotiate standalone maintenance agreements with third-party technical service providers rather than captive OEM service arms. This pattern concentrates most visibly in Tamil Nadu and Gujarat clusters where multi-brand frame installations create scale advantages for independent service networks.
Ring Spinning Frame Market Segmentation
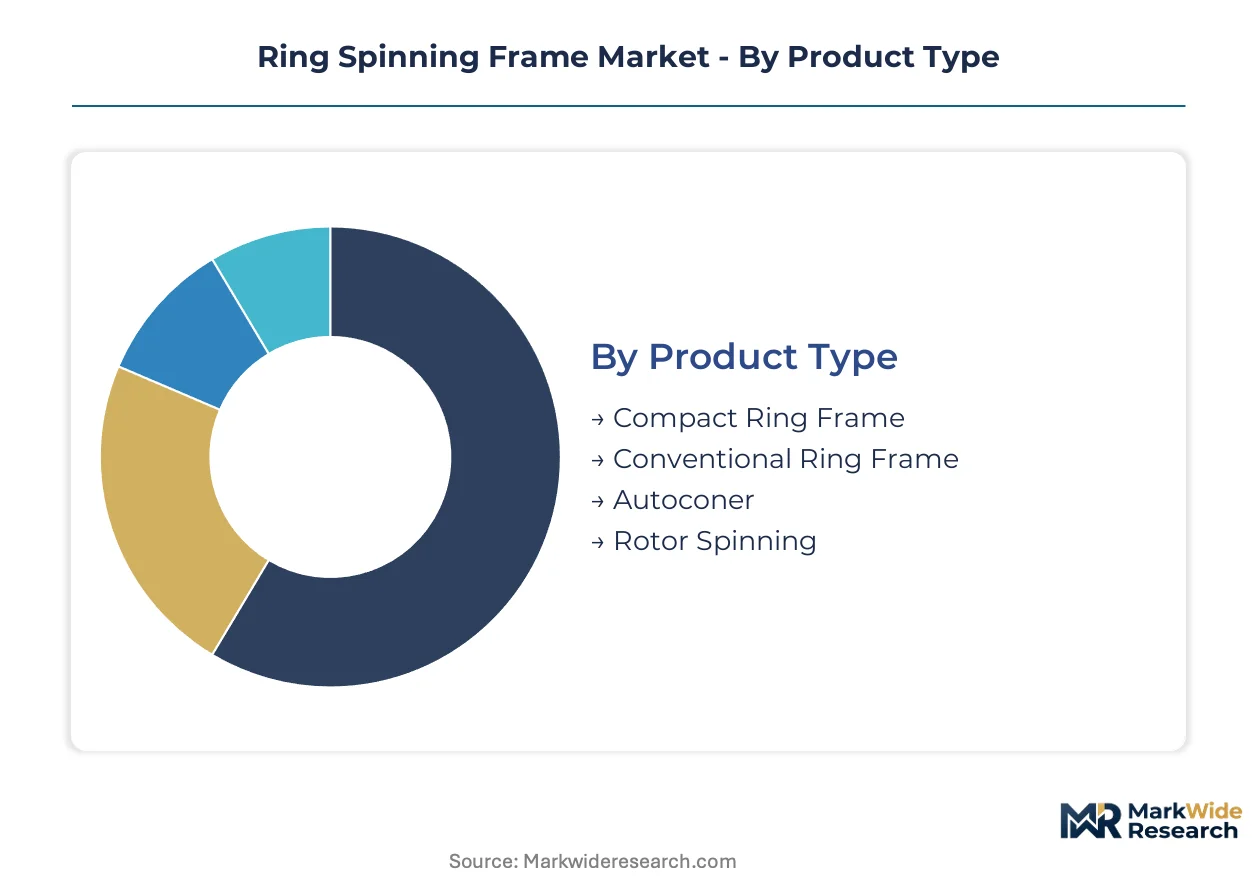
Ring spinning frame procurement decisions split across multiple technical and commercial dimensions. Each segmentation axis reveals distinct margin structures, upgrade cycles, and channel access patterns that shape vendor positioning.
Product Type:
Equipment flows through OEM-direct, dealer-distributor, and mill consortium procurement channels depending on configuration complexity and regional service infrastructure.
- Compact Ring Frame:Integrates pneumatic fiber condensing zones that reduce yarn hairiness by 40-60% versus conventional configurations. Demand concentrates in Germany and Turkey where EU Ecodesign energy-efficiency mandates drive retrofit programs.
- Conventional Ring Frame:Mechanical spindle platforms without fiber condensing, serving cost-sensitive yarn producers in South Asia. India absorbs dominant volume under PLI scheme capacity expansions, though procurement favors lower-speed configurations.
- Autoconer:Automated winding linkages that eliminate manual doffing operations. Bangladeshi and Vietnamese mills adopt these for labor cost reduction.
- Rotor Spinning:Open-end technology bypassing ring-traveler systems for coarse-count industrial yarn. Technical textile filtration segments specify these for membrane substrate production.
Conventional ring frames dominate installed base across South Asia. Compact configurations are where expansion concentrates as quality premiums justify capital intensity.
Technology:
Technology selection correlates with end-use margin tiers — premium apparel and technical textiles demand advanced spinning modes while commodity yarn tolerates legacy platforms.
- Compact Spinning:Pneumatic fiber condensing produces low-hairiness yarn for downstream high-speed weaving. Technical textile producers in Switzerland and Germany specify these for automotive filtration specifications.
- Air Spinning:Vortex spinning technology eliminating traveler-ring friction for synthetic fiber processing. Japanese synthetic yarn specialists deploy these for fine-count polyester.
- Open-End Spinning:Rotor-based systems for coarse-count industrial yarn. Home textile manufacturers in Pakistan favor these for terry towel production.
- Friction Spinning:Core-sheath yarn formation for industrial belting and hose reinforcement. Limited adoption outside specialized technical textile niches.
Open-end platforms anchor volume production in South Asia. Compact spinning is climbing the fastest as quality specifications tighten across EU and East Asian supply chains.
Application:
Application mix determines spindle speed requirements, with technical and industrial segments demanding sustained operation above 20,000 rpm.
- Apparel Manufacturing:Fine-count cotton and cotton-blend yarn for woven shirting and knitwear. Indian domestic brands expand captive spinning capacity under textile PLI incentives.
- Technical Textiles:Low-hairiness yarn for filtration membranes, composite reinforcements, and medical textiles. REACH chemical frameworks and EU F-Gas Regulation constrain lubricant choices for these installations.
- Home Textiles:Medium-count yarn for bedding, curtains, and upholstery. Turkish exporters upgrade to compact spinning for EU market access.
- Industrial Textiles:Heavy-count yarn for conveyor belts, ropes, and tire cord. Pakistan and Bangladesh concentrate production for regional construction and automotive supply.
Apparel manufacturing commands the dominant equipment base. Technical textiles represent the steepest expansion trajectory as filtration and composite specifications proliferate.
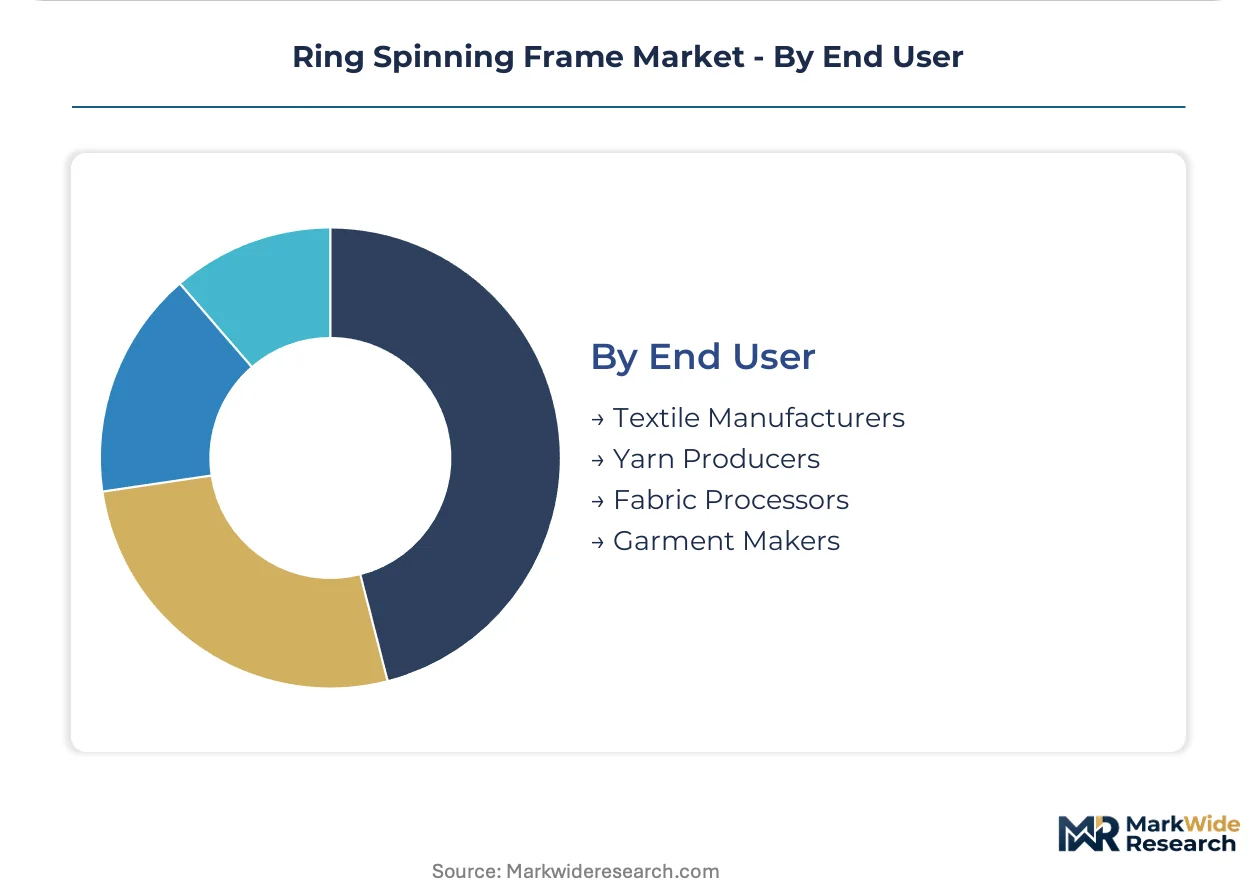
End User:
End-user category shapes maintenance contract structures, with integrated textile groups favoring multi-year service agreements over per-incident support.
- Textile Manufacturers:Vertically integrated mills spanning fiber-to-fabric operations. Tamil Nadu and Gujarat clusters in India negotiate consolidated procurement for multiple plant locations.
- Yarn Producers:Dedicated spinning operations supplying external weaving and knitting facilities. Vietnam's Binh Duong province attracts these as import substitution for garment export zones.
- Fabric Processors:Weaving and knitting houses with captive spinning for quality control. These users prioritize autoconer linkages for lot traceability.
- Garment Makers:Apparel exporters integrating backward into yarn production. Bangladesh's readymade garment sector drives this pattern for lead time compression.
Textile manufacturers hold the largest installed base. Yarn producers are gaining share fastest as geographic specialization fragments the value chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across textile corridors. German and Swiss buyers absorb premium pricing for energy-efficient compact configurations, while South Asian procurement committees prioritize capital efficiency over incremental quality gains.
India
Domestic apparel manufacturers expand captive spinning capacity under the PLI scheme for textiles. BIS machinery safety standards create compliance bottlenecks that delay commissioning of imported high-speed frames by four to six months. Tamil Nadu and Gujarat clusters negotiate consolidated procurement for multiple plant locations, concentrating order flow toward established OEM relationships.
Germany
Technical textile producers upgrade to compact spinning configurations to meet EU Ecodesign criteria for energy efficiency. REACH chemical frameworks and the EU F-Gas Regulation constrain lubricant choices, pushing mills toward sealed bearing designs. The Baden-Württemberg industrial belt anchors retrofit demand as filtration and automotive yarn specifications tighten.
Turkey
Export-oriented yarn producers face EU CBAM extension pressures that elevate cost parity for domestic ring-spun production against Asian imports. Turkish mills leverage geographic proximity to European technical textile end-users to capture quality-premium segments. The Bursa and İzmir manufacturing corridors concentrate compact spinning adoption for home textile export markets.
Vietnam
Apparel export manufacturing zones in Binh Duong and Dong Nai provinces lack sufficient domestic yarn supply, creating import substitution demand for ring-spun capacity. Garment makers integrate backward into spinning to compress lead times for EU and US export orders. Foreign direct investment from South Korean and Taiwanese textile groups accelerates frame procurement.
China
Dual carbon commitments reshape the cost calculus of imported yarn versus domestic ring-spun production in coastal manufacturing zones. MIIT energy-efficiency mandates for textile machinery accelerate retirement of obsolete mechanical platforms. The Jiangsu and Zhejiang textile belts concentrate demand for mechatronic spindle platforms with integrated automation.
Ring Spinning Frame Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ring spinning frame market. European and Japanese OEMs anchor the premium tier through integrated automation portfolios and magnetic levitation bearing systems, while Indian and Chinese fabricators dominate volume production through manufacturing scale and cost-engineered conventional configurations. The market structure stratifies across three strategic archetypes: integrated technology platforms, scale-driven regional specialists, and automation convergence enablers. Competitive dynamics center on autoconer linkage retrofit kits and compact spinning upgrade programs rather than greenfield frame sales.
Within the integrated technology tier, Rieter and Saurer exemplify archetypes that bundle spindle platforms with digital monitoring systems. Lakshmi Machine Works occupies a position representing scale-driven regional fabrication, anchoring cost-engineered conventional ring frames for South Asian yarn producers. These three companies illustrate how vendor positioning splits between premium automation convergence and capital-efficient mechanical platforms.
| Leading Market Players |
|---|
| Rieter |
| Saurer |
| Lakshmi Machine Works |
| Toyota Industries |
| Trützschler |
| Savio Macchine Tessili |
| Muratec |
| Marzoli Machines Textile |
| Zinser |
| Others |
Pricing and Supply Chain Analysis
Spindle manufacturing scale economies in Switzerland and Japan anchor supply concentration and establish price floors for high-speed frame configurations. OEMs with captive bearing production command premium positioning, while fabricators dependent on imported precision components absorb margin volatility from London Metal Exchange aluminum pricing.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across European textile corridors. Three-tier pricing structure across premium mechatronic platforms, standard compact configurations, and economy mechanical frames separates OEMs by automation intensity and energy efficiency certification. Price differentiation stems from magnetic levitation bearing integration and after-sales service bundling. Cost compression in conventional frame tiers is intensifying because Indian PLI scheme procurement committees prioritize capital efficiency over incremental quality gains. Bangladeshi garment-integrated spinners exhibit highest price sensitivity; German technical textile producers show lowest.
Supply Chain Analysis
Strategic stockpiling of precision bearings and traveler rings dominates inventory strategy among European frame OEMs facing Swiss and Japanese supply concentration. Manufacturing draws from Switzerland for spindle bearings, Japan for high-speed travelers, and China for aluminum alloy structural components. Raw material dependencies center on London Metal Exchange aluminum pricing, synthetic polyalphaolefin lubricants constrained by REACH frameworks, and rare-earth magnetic materials for levitation systems. Single-source vulnerability in precision bearing supply creates structural risk for premium frame configurations. Distribution runs through OEM-direct channels for complex mechatronic platforms and dealer-distributor networks for conventional mechanical frames.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ring spinning frame market is entering a cyclical recovery phase as EU Ecodesign retrofit programs and India's PLI scheme capacity expansions synchronize replacement demand across major textile corridors.
For Market Incumbents: Fortify aftermarket service revenue through standalone maintenance agreements with Tamil Nadu and Gujarat textile groups operating multi-brand frame installations. Deepen captive bearing manufacturing to offset aluminum price volatility and Swiss supply concentration. Prioritize autoconer linkage retrofit kits as defensive positioning against emerging automation convergence specialists threatening full-line replacement cycles.
For New Entrants and Emerging Players: Anchor in Vietnam's Binh Duong and Dong Nai provinces where apparel export zones lack sufficient domestic yarn supply and established OEM service networks remain underdeveloped. Target yarn producer segment procurement committees seeking import substitution capacity with lower total cost of ownership than European premium platforms. Deploy third-party technical service provider partnerships as primary go-to-market angle to bypass OEM-direct channel barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with integrated digital spindle monitoring platforms and multi-year service contracts. Long-term viability favors vendors with automation convergence capabilities spanning ring frames through winding systems. Acquisition target archetype: regional fabricators with manufacturing scale and cost-engineered conventional platforms but lacking mechatronic spindle technology. Watch for EU CBAM extension implementation as inflection indicator shifting cost parity toward domestic European ring-spun production.
| Strategic Initiative | Industry Significance |
|---|---|
| Compact Spinning Retrofit Program | EU Ecodesign compliance accelerates energy-efficient upgrade cycles across German technical textile corridors. |
| Autoconer Linkage Integration | Labor cost reduction in Bangladeshi and Vietnamese mills compresses doffing operations without full line replacement. |
| Magnetic Levitation Bearing Adoption | Swiss and German producers sustain speeds above 22,000 rpm for fine-count synthetic filtration yarn specifications. |
| Standalone Service Agreement Unbundling | Tamil Nadu textile groups negotiate third-party maintenance for multi-brand installations, fragmenting OEM service revenue. |
| Sealed Bearing Design Transition | REACH chemical constraints on mineral oil additives push synthetic lubricant alternatives with narrower temperature windows. |
Research Methodology
Cross-validation between primary interviews with textile mill procurement directors, maintenance engineers, and OEM product managers and secondary validation anchors the qualitative findings. Primary fieldwork engaged plant engineers at spinning facilities in Tamil Nadu and Gujarat clusters, aftermarket service heads at independent technical networks, and machinery safety certification officers at BIS testing laboratories. Secondary sources encompassed EU Ecodesign Directive implementation reports, BIS machinery safety standard filings, London Metal Exchange aluminum price series, and textile machinery trade association capacity surveys. Bottom-up spindle installation counts triangulate against top-down OEM revenue segmentation across the analysis window.
Sensitivity analysis on aluminum alloy price volatility and PLI scheme incentive continuity frames the forecast confidence intervals. The analytical framework models ring spinning frame demand across product type, technology mode, application segment, and end-user category throughout the forecast period. CAGRs derive from segment-level replacement cycle compression rates and greenfield capacity addition patterns. Industry-specific inputs include EU CBAM extension timing assumptions and BIS certification backlog duration estimates.
Decision-makers should treat outputs as directional under sustained EU Ecodesign enforcement and India PLI scheme continuity; material deviation would warrant model refresh. Forecasts reflect assumptions regarding skilled maintenance technician training pipeline scaling and REACH chemical framework lubricant formulation stability. Specific risk factors include aluminum price spike persistence beyond London Metal Exchange historical bands and BIS machinery safety testing capacity constraints extending commissioning delays. Revision becomes warranted when EU CBAM textile extension implementation crosses threshold certainty levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Felt Bobs Market