
 Denim Fabric Market | 2026-2036
Denim Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Denim Fabric Market Analysis
The EU Green Deal is broadening compliance requirements for textile producers across European supply chains. Candiani Denim leverages its Italian vertical mill to deliver reduced-water denim to premium brands. Arvind Limited anchors its position through integrated spinning, dyeing, and finishing operations in India. Isko competes by controlling one of the largest global production capacities for performance stretch denim.
Denim fabric is a durable cotton twill textile, typically woven with a colored warp and white weft, engineered in weights from five to thirty-two ounces per square yard for structural integrity and abrasion resistance. It serves primarily as the foundational material for jeans, jackets, and workwear, with expanding use in upholstery and accessories. Stretch denim dominates value contribution as elastane blends command premium positioning in fitted apparel, while raw denim sustains enthusiast segments with higher margin potential. Midweight constructions lead volume across casual apparel, and enzyme-washed finishes are displacing stone wash in environmentally constrained production regions.
REACH restricts hazardous chemical inputs in European denim finishing, while India's BIS certification mandates quality benchmarks for domestic textile sales. The EU AI Act will soon impose traceability requirements on automated textile sorting and recycling systems, reshaping compliance investment for exporters. Stakeholders must evaluate which regulatory layer—chemical, quality, or digital—will impose the steepest compliance cost before committing capacity expansion.
Market Dynamics
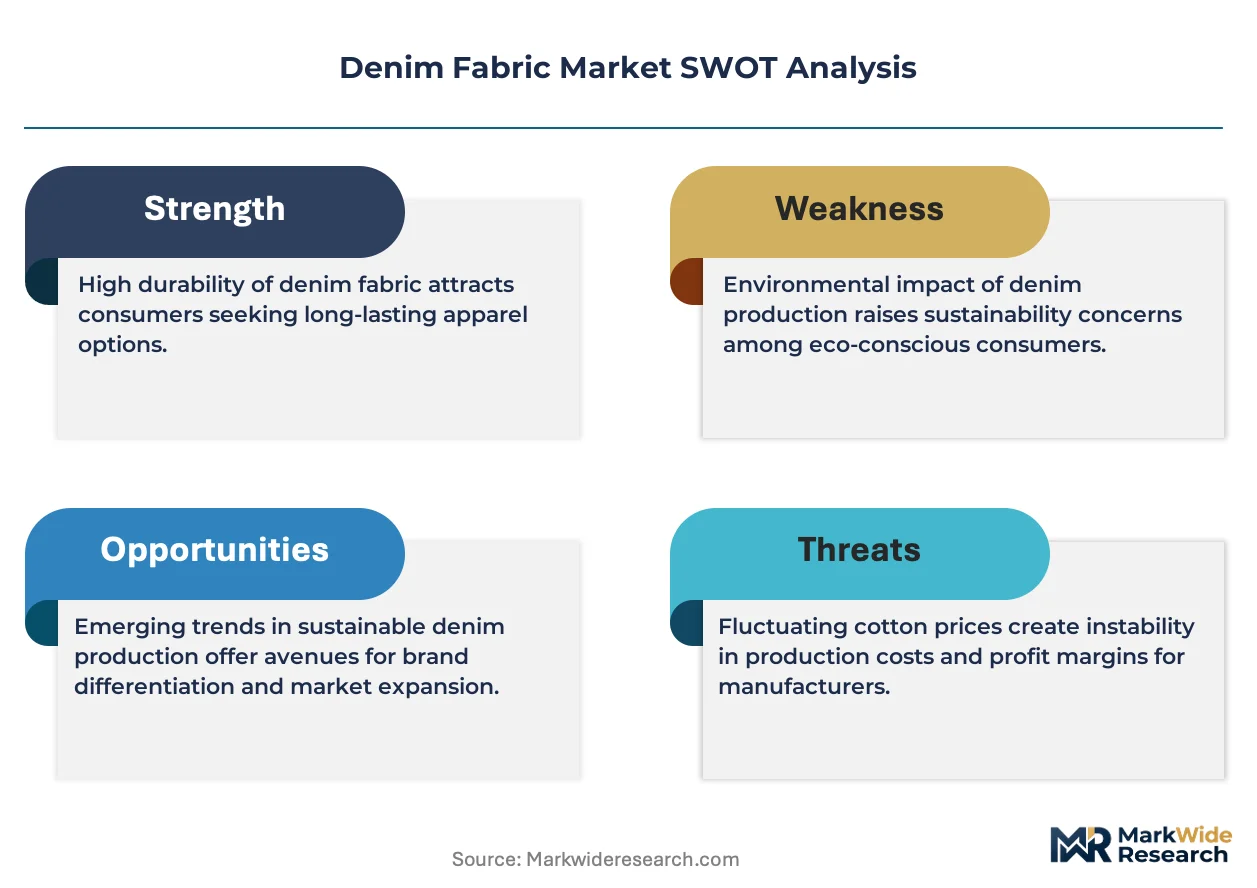
The EU Green Deal is compressing compliance timelines for European denim producers, forcing accelerated capital deployment into water recycling and low-impact dyeing infrastructure ahead of 2030 regulatory milestones.
Growth Catalysts
- REACH chemical restrictions:Hazardous substance limits under ECHA oversight are pulling premium brands toward certified clean-dye suppliers, tightening supplier qualification standards across European sourcing offices.
- India's PLI scheme for textiles:Production-linked incentives are expanding integrated mill capacity in Gujarat and Tamil Nadu, capturing export orders from brands diversifying beyond Chinese supply.
- Stretch denim formulations:Elastane-cotton blends are commanding premium positioning in fitted apparel segments, with performance specifications driving technical differentiation and repeat purchase loyalty.
Market Restraints
- Cotton price volatility:Input cost swings from weather-driven supply shocks in Texas and Maharashtra are compressing margin predictability for non-integrated weavers lacking captive spinning.
- Chinese supply concentration:Xinjiang-origin cotton restrictions under US UFLPA and EU due diligence laws are fragmenting raw material sourcing, raising traceability audit costs for multinational brands.
- Water intensity ceilings:Physical scarcity in Pakistan's Punjab region and India's Haryana belt is capping expansion potential for conventional indigo rope-dyeing operations.
Strategic Opportunities
- Vietnam's rising garment exports:Underpenetrated denim fabric supply relative to cut-make-trim capacity creates white space for regional mill investment serving EU-FTA advantaged apparel shipments.
- EU AI Act traceability mandates:Automated textile sorting and recycling system requirements are opening compliance-technology partnerships between European sorters and Asian mill groups.
- Enzyme wash substitution:Biotechnological finishing processes are replacing pumice stone methods, enabling water-stressed producers in Bangladesh and Turkey to maintain export qualification.
Industry Challenges
- Retrofitting legacy dye ranges:Capital intensity for closed-loop water systems and foam-dyeing equipment is straining mid-tier mills without access to green financing facilities.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of GOTS, OEKO-TEX, and ZDHC compliance is extending product development timelines and raising laboratory testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denim Fabric Market |
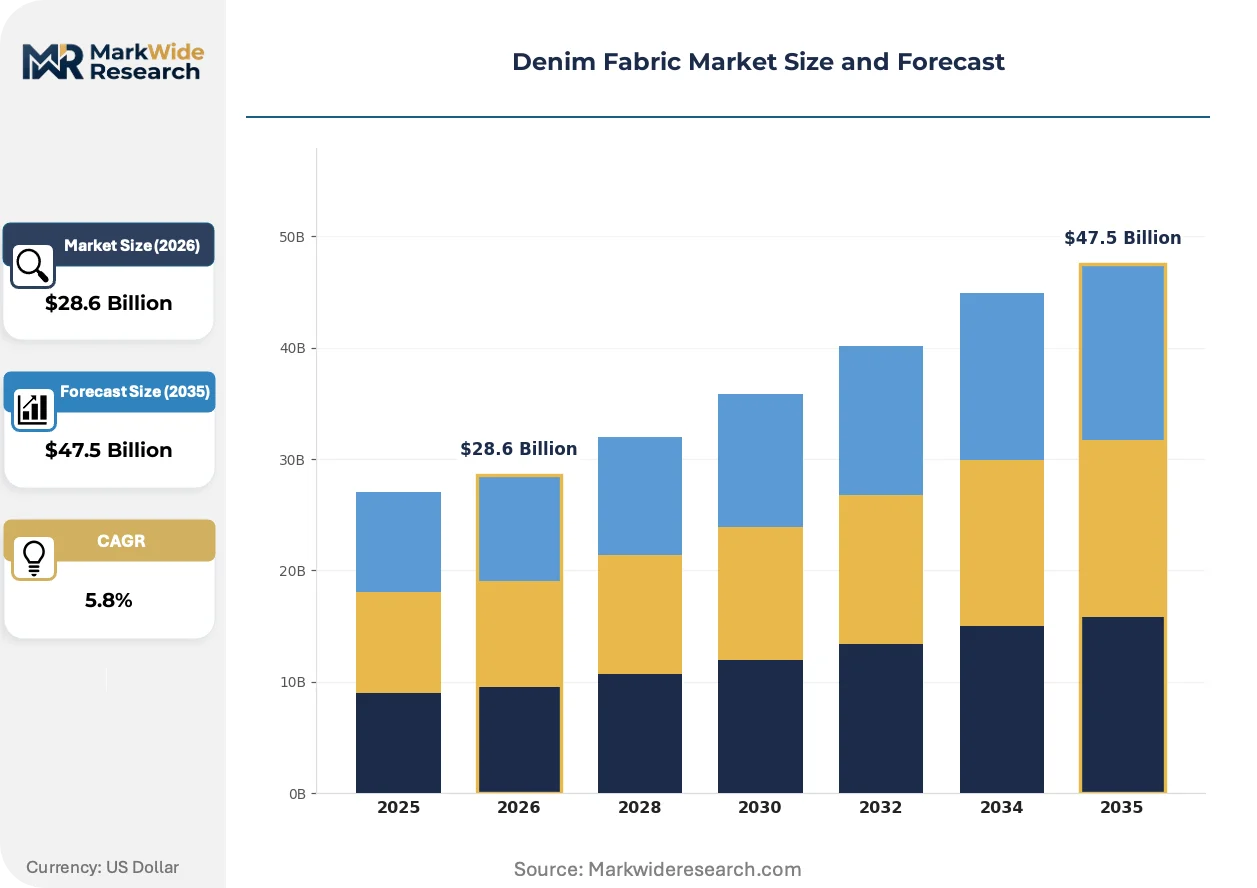
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Raw Denim, Selvedge Denim, Stretch Denim, Colored Denim End Use: Apparel, Home Textiles, Accessories, Upholstery Weight: Lightweight, Midweight, Heavyweight, Ultra-Heavyweight Finish Type: Stone Wash, Acid Wash, Rinse Wash, Enzyme Wash |
| Companies Covered | Kaihara Corporation, Candiani Denim, Arvind Limited, Nandan Denim Ltd., Orta Anadolu, Isko, Canatiba, Aarvee Denims & Exports Ltd., Vicunha Têxtil S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denim Fabric Market Emerging Trajectories
Laser finishing, bio-synthetic dyes, and blockchain traceability are converging to redefine production economics and buyer verification protocols across premium denim supply chains.
Laser scribing technology is integrating into finishing workflows to replicate vintage abrasion patterns without water-intensive stone washing or potassium permanganate spraying. Premium workwear and heritage brands in Japan and Italy are adopting these systems at replacement cycle pace, compressing the competitive advantage of traditional wet-processing specialists.
REACH authorization requirements for chromium-based mordants are tightening chemical substitution timelines for European finishers. The restriction is accelerating bio-based indigo fermentation pilot programs, with Italian and Portuguese dye houses investing in partnership structures with agricultural biotechnology developers to secure compliant feedstock.
Direct-to-brand contracting is displacing traditional trader-mediated procurement for large-volume European and North American apparel groups. Mill groups with in-house design studios and rapid sampling capability are capturing preferred supplier status, with this pattern most visible in Germany's premium denim brand cluster and California's direct-to-consumer labels.
Denim Fabric Market Segmentation
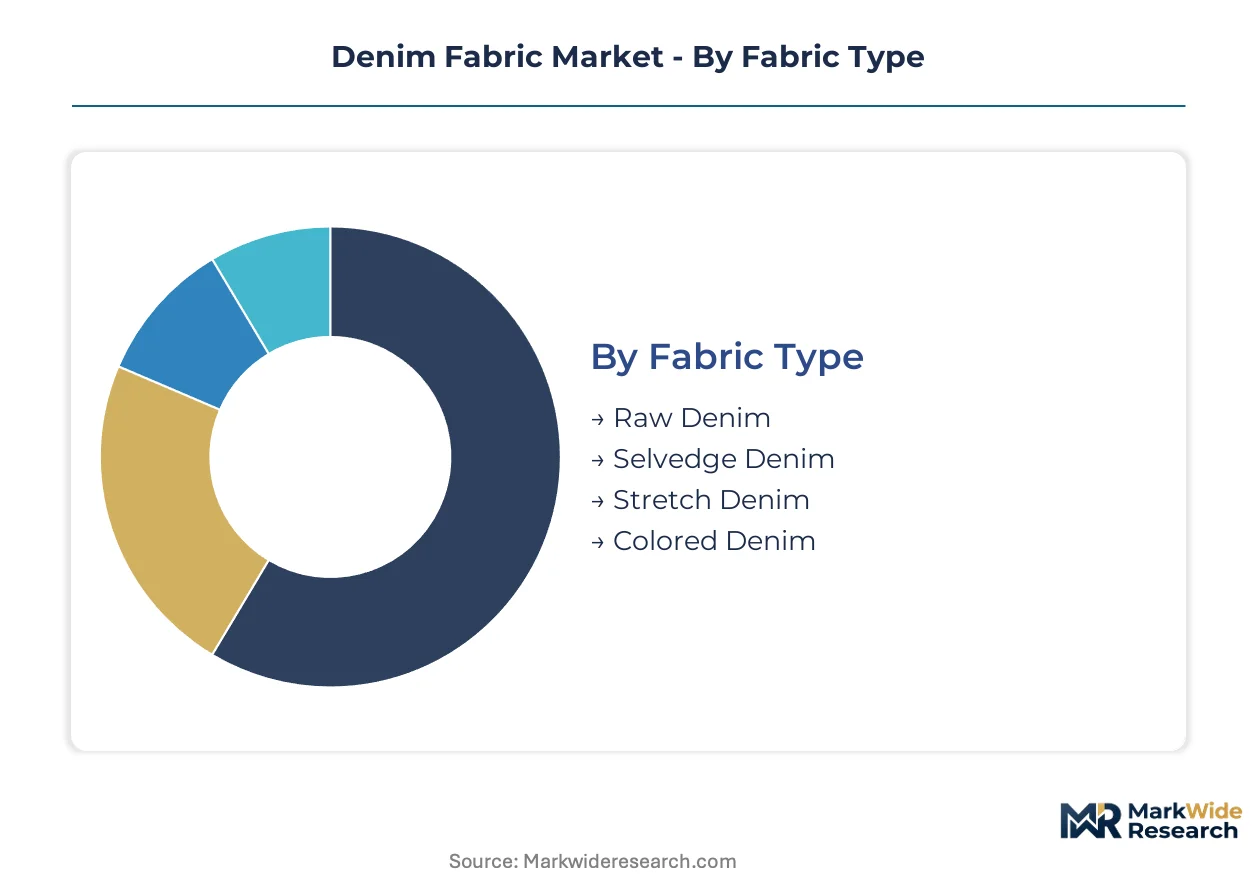
Denim fabric segmentation reveals divergent margin profiles across construction types and finishing methods. Producers allocate capital based on whether segments serve volume-driven mass retail or specification-heavy premium channels.
Fabric Type:
Volume concentrates in commoditized constructions, while premium positioning accrues to technically differentiated blends.
- Stretch Denim:Cotton-elastane blends ranging from 1% to 4% elastane content deliver recovery and shape retention for fitted jeans and activewear applications. Demand concentrates in Germany's premium denim brand cluster and California direct-to-consumer labels, where performance specifications command repeat purchase loyalty and technical differentiation premiums.
- Raw Denim:Unwashed, rigid constructions in 12-16 ounce weights develop personalized fade patterns through extended wear. Enthusiast segments in Japan and Italy sustain higher margin potential through limited-run drops and heritage positioning, though volumes remain constrained by narrow end-use specialization.
- Selvedge Denim:Shuttle-loomed narrow fabrics with self-finished edges signal craft authenticity in premium workwear.
- Colored Denim:Sulphur-dyed or pigment-coated alternatives to indigo serve fashion-cycle volatility in seasonal collections.
Today's leader: Stretch Denim. Tomorrow's challenger: Raw Denim.
End Use:
Apparel dominance shapes capacity planning, while non-apparel applications diversify revenue exposure.
- Apparel:Jeans, jackets, shirts, and skirts constitute the foundational demand pool, with cut-make-trim operations in Vietnam and Bangladesh pulling fabric from Indian and Turkish mills. REACH chemical restrictions and EU Green Deal compliance timelines are tightening supplier qualification standards for European-facing production.
- Accessories:Bags, belts, and small leather goods alternatives utilize lighter-weight constructions with specialized finishing. Demand from Japanese heritage brands and Italian luxury houses supports dedicated production lines with shorter runs and higher per-meter yields.
- Home Textiles:Decorative pillows, throws, and curtains employ softer hand constructions with reduced abrasion resistance requirements.
- Upholstery:Heavyweight, stain-resistant treatments serve contract furniture and automotive seating applications.
Apparel captures current volume concentration. Accessories gain share fastest as brand licensing extends denim iconography.
Weight:
Construction density determines equipment calibration and end-use suitability across climate and durability requirements.
- Midweight:10-12 ounce constructions balance durability with wearability across four-season casual apparel. This specification dominates cut-make-trim procurement from Vietnam's rising garment export sector, where EU-FTA advantaged shipments require versatile fabric inputs.
- Heavyweight:14-16 ounce fabrics deliver abrasion resistance for workwear and motorcycle protective gear. Demand from Germany's industrial heritage brands and Japan's Osaka-based specialist mills sustains premium positioning despite slower velocity.
- Lightweight:5-8 ounce constructions serve warm-climate apparel and draping applications.
- Ultra-Heavyweight:18-32 ounce specialty fabrics target enthusiast collectors and protective equipment.
Midweight commands current procurement volumes. Heavyweight posts steepest expansion trajectory as workwear aesthetics penetrate fashion cycles.
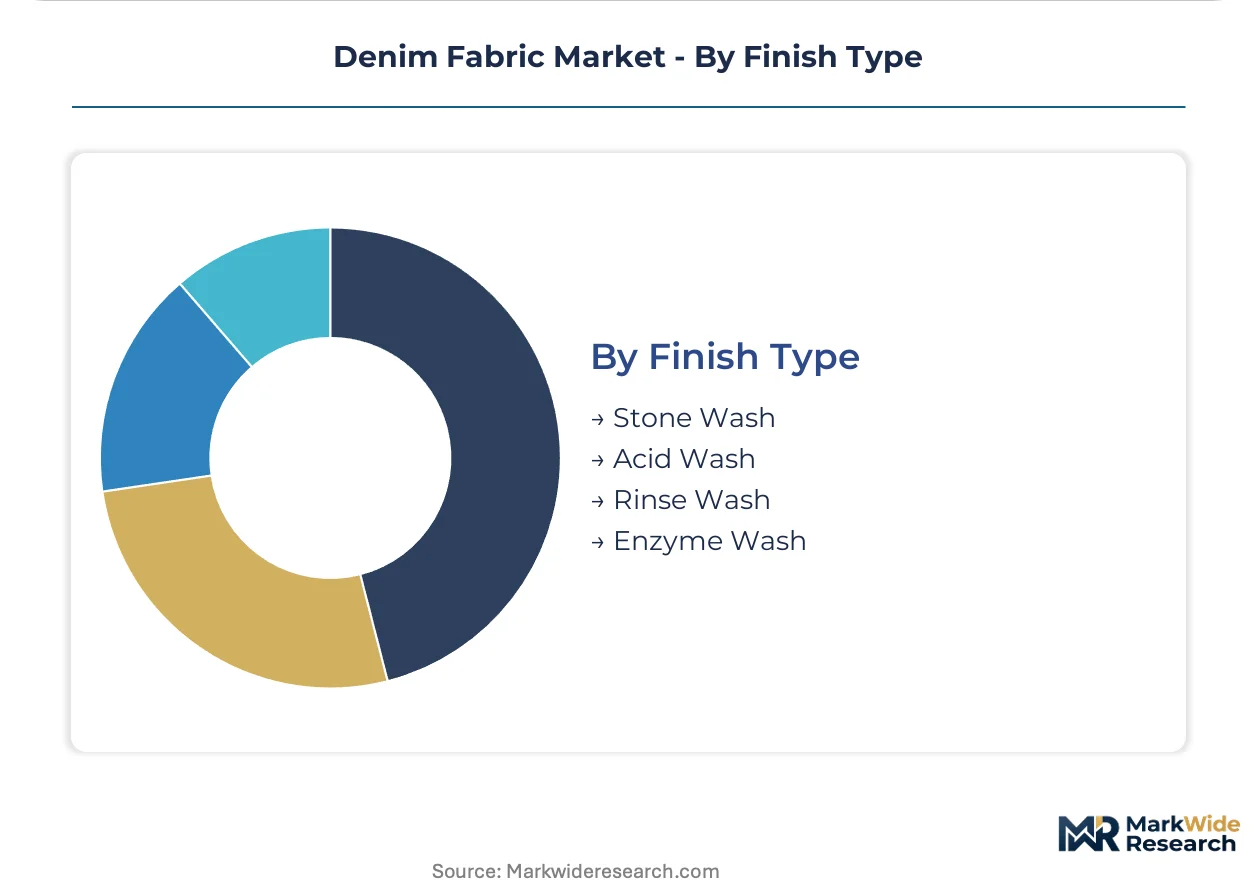
Finish Type:
Environmental compliance is reconfiguring process economics and equipment investment priorities.
- Enzyme Wash:Cellulase-based biological finishing replaces pumice stone abrasion with controlled fiber surface modification. Water-stressed producers in Turkey and Bangladesh are adopting these systems to maintain export qualification under tightening ECHA oversight and brand sustainability mandates.
- Stone Wash:Traditional pumice abrasion creates distinctive vintage effects but generates sludge waste and water intensity. Regulatory pressure in Pakistan's Punjab region and India's Haryana belt is capping expansion potential for conventional operations.
- Acid Wash:Chlorine-based or permanganate spraying achieves high-contrast mottling effects.
- Rinse Wash:Minimal processing softens hand feel while preserving dark indigo tones for commercial mainstream applications.
Enzyme Wash leads substitution momentum. Rinse Wash defends volume position through cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian textile engineers and Indian chemical technicians anchor the industry's technical workforce concentrations. German sustainability consultants and Turkish dyeing specialists complete the core talent pools shaping regional competitive positioning.
India
Gujarat's integrated denim mills scale capacity to serve European premium brands diversifying beyond Chinese supply. The PLI scheme for textiles accelerates capital deployment into spinning-dyeing-finishing operations. Ahmedabad and Surat clusters capture rising export orders as BIS certification mandates quality benchmarks for domestic sales.
Italy
Heritage workwear brands and luxury fashion houses drive demand for reduced-water selvedge constructions. REACH chemical restrictions under ECHA oversight pull sourcing toward certified clean-dye suppliers. Biella and Veneto mill districts leverage vertical integration to deliver compliant feedstock for EU Green Deal timelines.
Turkey
Water-stressed producers in Bursa and Denizli adopt enzyme-wash systems to maintain export qualification under tightening environmental oversight. Cut-make-trim operations in Istanbul pull midweight fabric for EU-FTA advantaged shipments. ECHA-aligned chemical substitution programs accelerate bio-based indigo fermentation partnerships.
United States
Direct-to-consumer labels in Los Angeles and New York source stretch denim with performance specifications commanding technical differentiation premiums. UFLPA restrictions on Xinjiang-origin cotton fragment raw material sourcing and raise traceability audit costs. Cone Denim's North Carolina operations anchor domestic heritage production for enthusiast segments.
Japan
Osaka-based specialist mills sustain premium positioning for rigid raw denim through limited-run drops and craft authenticity signaling. Enthusiast collectors in Tokyo and Okayama drive demand for ultra-heavyweight shuttle-loomed constructions. METI industrial standards support equipment modernization for laser finishing integration.
Denim Fabric Market Vendor Landscape
Capital-heavy integrated mill operators compete with asset-light design studios and trading intermediaries for brand relationships. The vendor base stratifies across three tiers: vertically integrated producers controlling captive spinning and dyeing, specialist finishers with rapid sampling capability, and regional converters serving price-sensitive mass retail. Strategic differentiation hinges on sustainability certification stacking and direct-to-brand contracting velocity. Capacity expansion in India and Turkey accelerates as M&A activity concentrates European heritage assets.
Among Italian vertical mill operators, Candiani Denim exemplifies the clean-dye supplier archetype serving REACH-compliant European sourcing offices. Isko occupies a position representing scale-driven performance stretch denim capacity. Arvind Limited anchors the integrated Indian mill group archetype with captive operations spanning Gujarat and Tamil Nadu.
| Leading Market Players |
|---|
| Kaihara Corporation |
| Candiani Denim |
| Arvind Limited |
| Nandan Denim Ltd. |
| Orta Anadolu |
| Isko |
| Canatiba |
| Aarvee Denims & Exports Ltd. |
| Vicunha Têxtil S.A. |
| Others |
Supply Flow & Price Mechanics
Premium apparel brand procurement offices in Germany and California concentrate purchasing power for stretch denim specifications, anchoring a three-tier pricing structure across premium, standard, and economy levels that rewards certified clean-dye suppliers with preferred supplier status.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the denim fabric market by certification grade and volume scale. Price differentiation hinges on GOTS and ZDHC compliance status alongside elastane content for performance specifications. Pricing pressure stems from cotton price volatility in Texas and Maharashtra, compressing margin predictability for non-integrated weavers. Mass retail buyers exhibit highest price sensitivity, while heritage brands in Japan and Italy accept substantial premiums for selvedge authenticity.
Supply Chain Analysis
Skilled textile engineering talent in Biella and Ahmedabad underpins competitive positioning for Italian and Indian mill groups. Supply concentrates in India, Turkey, and Italy, with raw cotton dependencies drawing from US, Brazilian, and Australian origins. Single-source vulnerability around Xinjiang-origin cotton restrictions fragments raw material sourcing under US UFLPA and EU due diligence laws. Distribution runs through direct-to-brand contracting channels displacing traditional trader-mediated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The denim fabric market functions as a stable compounder, with EU Green Deal compliance timelines forcing sustained capital deployment into water recycling infrastructure that locks in supplier relationships across multi-year horizons.
For Market Incumbents: Anchor defensive positioning through backward integration into captive spinning operations in Gujarat and Tamil Nadu, mitigating cotton price volatility exposure. Accelerate certification stacking for GOTS, OEKO-TEX, and ZDHC compliance to tighten supplier qualification standards before 2030 regulatory milestones strain mid-tier competitors.
For New Entrants and Emerging Players: Capture white space in Vietnam's underpenetrated denim fabric supply serving EU-FTA advantaged garment exports. Target enzyme-wash substitution partnerships with water-stressed producers in Bangladesh and Turkey as the most penetrable entry angle, leveraging biotechnological finishing capabilities for rapid sampling velocity.
For Investors and Strategic Acquirers: European premium apparel groups are the most active acquirer in this space, consolidating heritage mill assets to secure compliant feedstock. Long-term viability centers on integrated operators with in-house design studios and rapid sampling capability. Watch laser finishing adoption rates in Japanese and Italian heritage brands as the inflection indicator for wet-processing displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Spinning | Mitigates input cost swings from weather-driven cotton supply shocks in Texas. |
| Enzyme-Wash System Deployment | Enables Turkish and Bangladeshi producers to maintain export qualification under ECHA oversight. |
| Direct-to-Brand Contracting Expansion | Captures preferred supplier status with German premium denim brand clusters. |
| Bio-Based Indigo Fermentation Partnership | Secures REACH-compliant feedstock through agricultural biotechnology developer alliances. |
| Laser Finishing Technology Integration | Replicates vintage abrasion patterns without water-intensive stone washing processes. |
Methodological Framework
Bottom-up apparel demand modeling reconciled against top-down mill capacity tracking forms the analytical core of this study. Primary interviews with denim mill technical directors, brand sustainability officers, European sourcing office procurement leads, and chemical supplier R&D heads combined with secondary validation from customs trade data, BIS certification registries, SEC textile sector filings, and EU ECHA authorization databases. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Historical trendline analysis of fabric type, end-use application, weight specification, and finish technology dimensions shaped the projection framework across the analysis window. CAGR derivation rested on capacity utilization rates, regulatory compliance investment cycles, and substitution elasticity between conventional and low-impact dyeing processes. Segmentation modeling incorporated stretch denim elastane blend penetration, raw denim enthusiast segment sizing, and enzyme-wash adoption curves.
Underlying measurement precision varies by segment; stretch denim and midweight constructions carry tighter precision than selvedge and ultra-heavyweight specialty fabrics. Forecasts reflect assumptions around EU Green Deal implementation pacing and PLI scheme disbursement continuity. Material deviation in cotton price volatility or Xinjiang cotton restriction enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market