
 Silica Yarn Market | 2026-2036
Silica Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Silica Yarn Market Insights
ISO 2076 textile nomenclature and aerospace material qualification cycles is redrawing competitive boundaries for silica yarn suppliers. Sanul Co leverages in-house fiber drawing capabilities to anchor its position in high-temperature applications. Arrow Technical Textiles competes through specialized twisted and bulked form factors serving European electrical insulation buyers. Valmiera Glass sustains geographic dominance across Baltic and Nordic construction reinforcement markets with consistent filament quality.
Silica yarn consists of continuous or staple fibers drawn from high-purity silicon dioxide, typically exceeding 99% SiO₂ content, engineered to withstand continuous operating temperatures above 1,000°C without significant thermal degradation. Its primary industrial purpose centers on thermal insulation, fire containment, and structural reinforcement in environments where conventional organic fibers would combust or lose mechanical integrity. Heat-resistant yarn and composite yarn categories command premium positioning due to aerospace and automotive qualification requirements, while high-strength yarn occupies mature volume pools in construction reinforcement. Specialty yarn variants targeting protective gear applications represent the fastest-expanding margin segment as industrial safety regulations tighten across multiple jurisdictions.
REACH substance restrictions in Europe and EPA workplace exposure limits in the United States directly shape fiber purity standards and manufacturing process emissions controls for silica yarn producers. China's GB standards and SAMR quality certification frameworks govern market access for domestic and imported thermal insulation textiles. Japan's METI energy efficiency directives and JIS industrial standards influence product specifications for electrical insulation applications across Asia-Pacific supply chains. Stakeholders must monitor evolving material qualification timelines and regulatory harmonization gaps between major economies to anticipate certification bottlenecks and secure supply agreements.
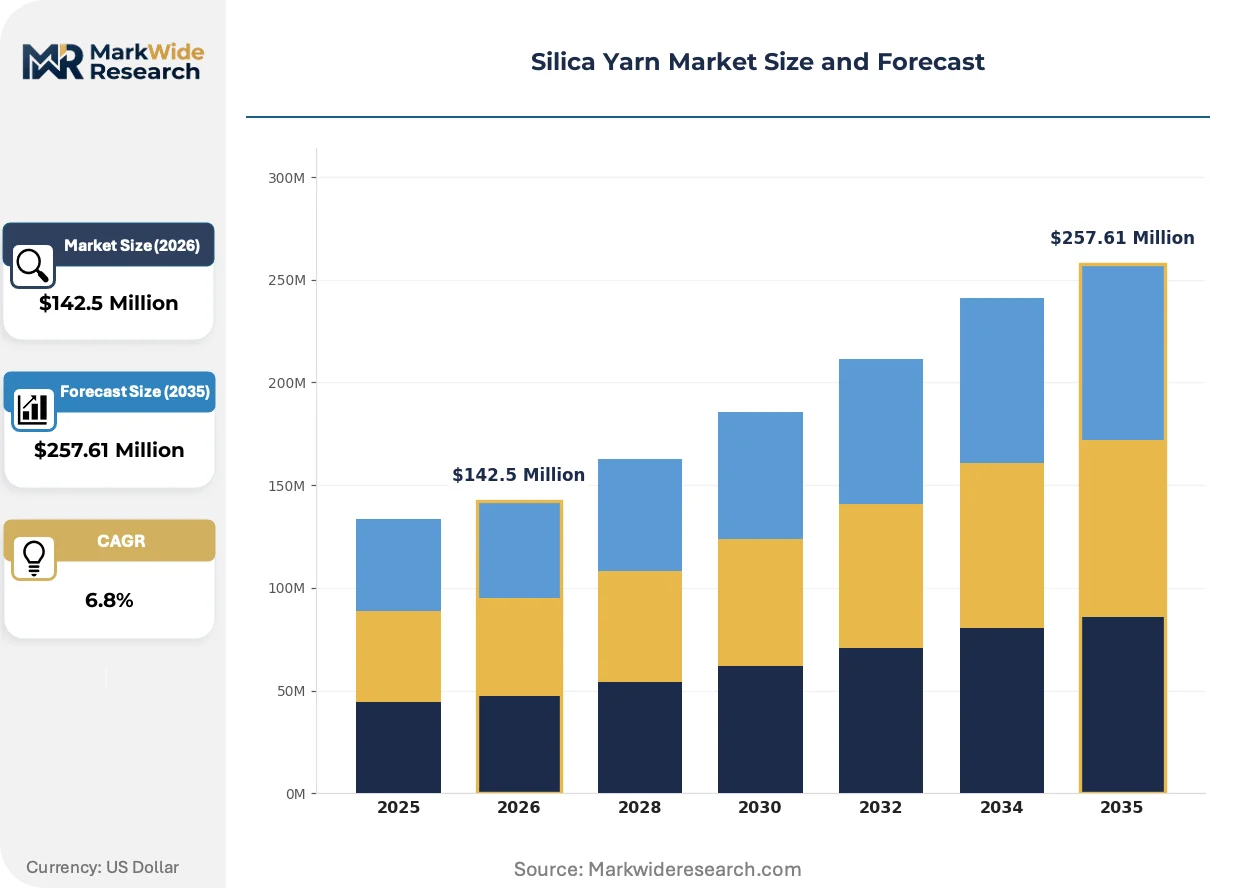
Market Dynamics
Aerospace thermal protection qualification cycles are compressing supplier timelines while REACH substance restrictions and EPA emissions standards simultaneously tighten purity thresholds, forcing fiber producers to recalibrate capital deployment and certification sequencing.
Growth Catalysts
- REACH compliance mandates:European ECHA substance restrictions on hazardous fiber classifications are accelerating replacement demand for high-purity SiO₂ alternatives in industrial insulation applications.
- Aerospace thermal protection systems:Reentry vehicle and engine nacelle manufacturers in the United States are expanding specifications for continuous-filament silica fabrics rated above 1,100°C.
- China's eastern manufacturing provinces:SAMR quality certification frameworks for GB-standard thermal textiles are consolidating procurement toward qualified domestic and import suppliers.
Market Restraints
- High-purity quartz feedstock volatility:Semiconductor-grade silicon dioxide sourcing constraints in Brazil and Madagascar are transmitting cost pressure through drawn-fiber value chains.
- Single-source drawing equipment dependency:Specialized furnace and bushing technology concentrates among German and Japanese capital equipment suppliers, creating supply bottleneck risk.
- Alumina-silica ceramic fiber substitution:Lower-cost refractory ceramic fibers rated to 1,260°C are capturing volume in non-aerospace construction insulation specifications.
Strategic Opportunities
- India's industrial safety expansion:BIS certification requirements for protective textiles in steel and foundry operations are opening qualified-supplier windows before domestic capacity matures.
- Electric vehicle battery enclosure fire containment:NHTSA thermal runaway propagation standards are creating specification demand for silica-based compression pads and module separators.
- Digital thread integration:Convergence of ISO 2076 textile nomenclature with blockchain material provenance tracking is enabling premium pricing for qualification-documented fiber lots.
Industry Challenges
- Specialized fiber-drawing technician scarcity:Master glass technologists capable of maintaining 99%+ SiO₂ purity across continuous filament production are concentrated among retiring workforce cohorts in Germany and Japan.
- Aerospace material qualification timeline compression:FAA and EASA concurrent certification requirements for new thermal protection fabrics are extending development-to-revenue cycles beyond typical capital planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica Yarn Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Strength Yarn, Heat-Resistant Yarn, Composite Yarn, Specialty Yarn Form: Filament, Twisted, Textured, Bulked End User: Aerospace, Electrical Insulation, Automotive, Construction Application: Fireproof Fabrics, Reinforcement, Insulation, Protective Gear |
| Companies Covered | Sanul Co, Arrow Technical Textiles, Valmiera Glass, Nanjing Tianyuan, Shanxi Huatek, Domin-Tex Insulation Corp, Bohemiatex, EAS Fiberglass, TextileTechnologies Europe Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica Yarn Market Trends and Innovations
Process automation in fiber drawing and real-time purity monitoring are compressing production variance and enabling lot-level traceability that aerospace buyers now mandate.
Sol-gel derived high-purity silica precursor synthesis is bifurcating supplier tiers. Aerospace prime contractors and tier-one thermal protection integrators are qualifying sol-gel feedstock for next-generation reentry systems. This technology is bifurcating the market between qualified sol-gel suppliers capturing premium positioning and conventional melt-drawn fiber producers defending construction and industrial volume segments.
EPA workplace exposure limits for respirable crystalline silica are tightening permissible concentration thresholds in United States manufacturing facilities. Fiber producers are retrofitting enclosed drawing environments and automated handling systems to maintain compliance. High-strength yarn segments serving construction reinforcement face disproportionate compliance cost pressure relative to aerospace-qualified continuous filament categories.
Specification-driven procurement consolidation is concentrating buying power among aerospace primes and major industrial textile converters. Long-term supply agreements with embedded volume commitments and technical service provisions are displacing spot-market transactions. This pattern is most visible in Germany's industrial textile corridor, where major automotive and aerospace buyers have consolidated supplier panels to three qualified silica yarn sources.
Silica Yarn Market Segmentation
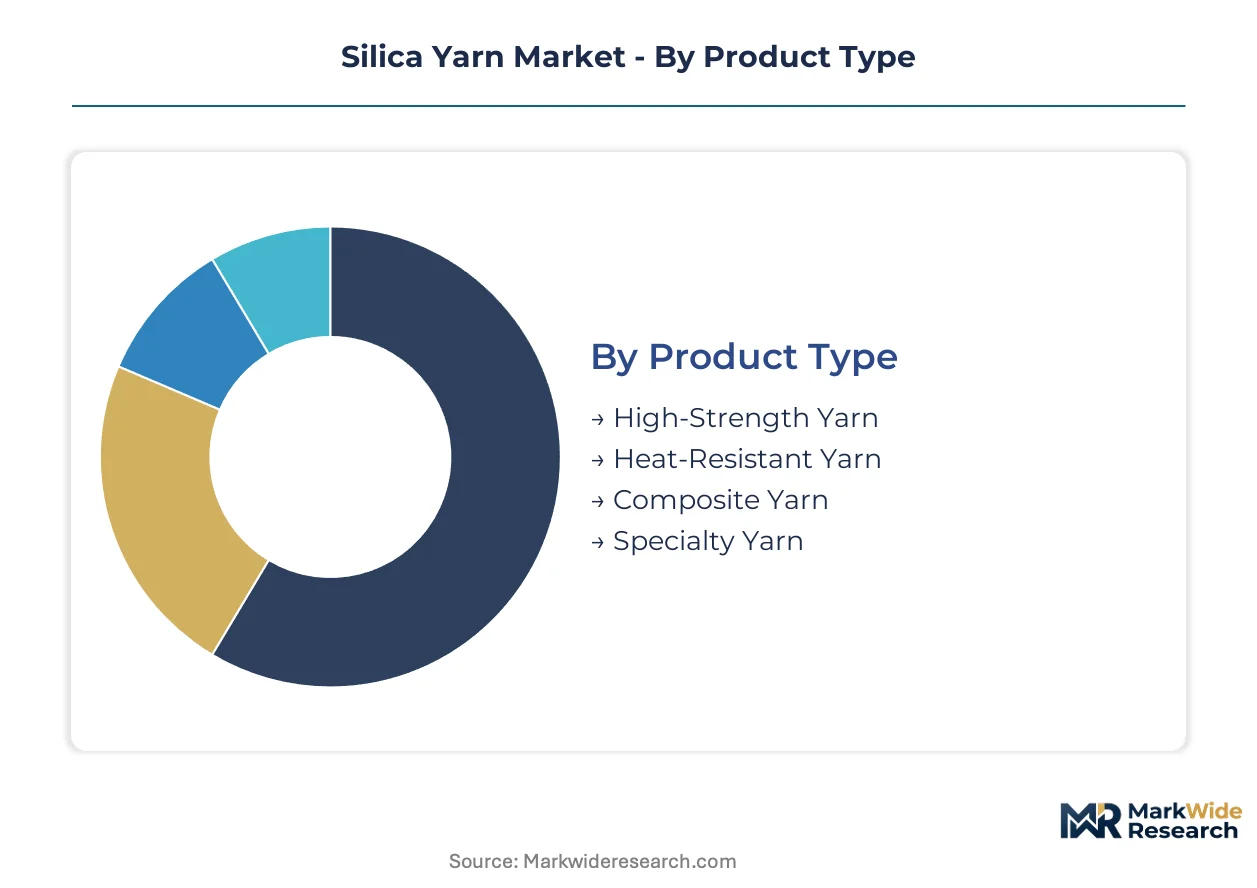
Silica yarn segmentation reveals how thermal performance specifications and qualification requirements concentrate margin pools across distinct product tiers. Aerospace-grade continuous filament commands premium positioning, while construction reinforcement operates on volume economics shaped by feedstock purity and drawing efficiency.
Product Type:
Heat-resistant and composite yarn categories capture the deepest margin pools due to aerospace and automotive qualification barriers.
- Heat-Resistant Yarn:Continuous-filament constructions rated above 1,100°C continuous service dominate reentry vehicle thermal protection specifications from US aerospace primes. FAA and EASA concurrent certification requirements compress supplier panels to three qualified sources.
- Composite Yarn:Hybrid constructions combining silica with ceramic or metallic filaments serve electrical insulation applications under Japan's METI energy efficiency directives. Demand concentrates in Germany's industrial textile corridor where automotive buyers consolidate procurement.
- High-Strength Yarn:Construction reinforcement specifications in China's eastern manufacturing provinces drive volume procurement under GB-standard thermal textile frameworks.
- Specialty Yarn:Protective gear variants targeting industrial safety regulations across multiple jurisdictions represent the fastest-expanding margin segment.
Heat-resistant yarn holds installed capacity. Specialty yarn is rotating up the share rankings.
Form:
Filament forms dominate aerospace procurement while twisted and bulked variants serve cost-sensitive industrial insulation.
- Filament:Continuous-drawn monofilaments exceeding 99% SiO₂ purity anchor thermal protection systems for engine nacelle manufacturers. REACH substance restrictions on hazardous fiber classifications accelerate replacement demand from European ECHA mandates.
- Twisted:Multi-ply constructions serve electrical insulation buyers in Germany's industrial textile corridor with specialized form factors that Arrow Technical Textiles leverages for competitive positioning.
- Textured:Surface-modified filaments enhance resin adhesion in composite manufacturing for automotive battery enclosure applications.
- Bulked:Expanded cross-section constructions improve thermal insulation efficiency in construction reinforcement specifications.
Filament maintains process control advantages. Bulked forms are climbing the fastest as insulation efficiency gains priority.
End User:
Aerospace qualification cycles and automotive thermal runaway standards create dual premium demand anchors.
- Aerospace:Reentry vehicle and engine nacelle manufacturers in the United States specify continuous-filament silica fabrics rated above 1,100°C. NHTSA thermal runaway propagation standards for electric vehicle battery enclosures create adjacent specification demand.
- Automotive:Battery module separator and compression pad applications under tightening thermal containment regulations drive qualification activity.
- Electrical Insulation:Japan's JIS industrial standards and METI directives influence product specifications across Asia-Pacific supply chains.
- Construction:China's SAMR quality certification frameworks consolidate procurement toward qualified domestic and import suppliers for GB-standard thermal textiles.
Aerospace commands specification leadership. Automotive is gaining share fastest on electrification safety mandates.
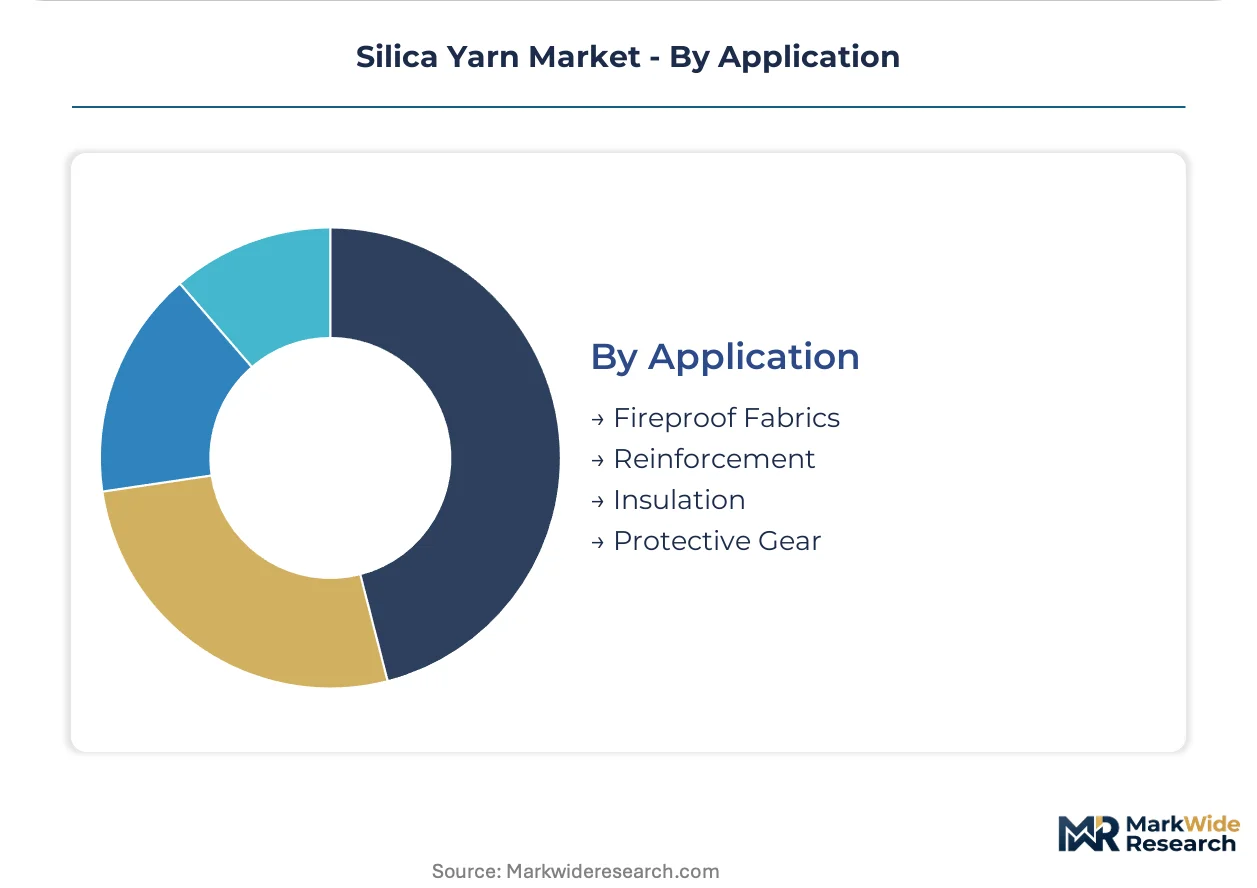
Application:
Fireproof fabrics and protective gear concentrate value capture through regulatory-driven replacement cycles.
- Fireproof Fabrics:Thermal protection systems for reentry vehicles and engine nacelles require continuous-filament constructions with lot-level traceability that aerospace buyers now mandate. EPA workplace exposure limits for respirable crystalline silica tighten manufacturing compliance costs.
- Protective Gear:Industrial safety regulations across multiple jurisdictions drive fastest-expanding demand as BIS certification requirements in India open qualified-supplier windows before domestic capacity matures.
- Reinforcement:Construction applications face alumina-silica ceramic fiber substitution pressure in non-aerospace insulation specifications.
- Insulation:Industrial thermal containment applications operate on mature volume economics with limited differentiation.
Fireproof fabrics hold qualification barriers. Protective gear is rotating up the share rankings on safety regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions and EPA emissions standards are tightening material qualification requirements across major manufacturing economies. Aerospace procurement expansion and industrial safety regulation tightening are redrawing regional demand patterns for high-purity thermal insulation textiles.
United States
FAA and EASA concurrent certification requirements for thermal protection fabrics are compressing supplier timelines for reentry vehicle and engine nacelle manufacturers. EPA workplace exposure limits for respirable crystalline silica mandate enclosed drawing environments and automated handling retrofits. Aerospace prime contractors in California and Texas are consolidating supplier panels to three qualified silica yarn sources under long-term supply agreements.
Germany
Industrial textile buyers in Baden-Württemberg and Bavaria are consolidating procurement toward qualified domestic and import suppliers under ECHA REACH compliance mandates. The country's national industrial safety regulator enforces hazardous fiber classification restrictions that accelerate replacement demand for high-purity SiO₂ alternatives. Germany's industrial textile corridor anchors European electrical insulation demand with specialized twisted and bulked form factors serving automotive and aerospace specifications.
China
SAMR quality certification frameworks for GB-standard thermal textiles are consolidating procurement in Jiangsu and Zhejiang provinces toward qualified domestic and import suppliers. The Ministry of Ecology and Environment enforces dual carbon goals that tighten manufacturing process emissions controls for fiber producers. Eastern manufacturing provinces drive volume demand for construction reinforcement specifications under evolving national quality certification frameworks.
Japan
METI energy efficiency directives and JIS industrial standards influence product specifications for electrical insulation applications across Asia-Pacific supply chains. The Ministry of Economy, Trade and Industry mandates performance benchmarks that shape regional procurement patterns for hybrid composite yarn constructions. Industrial clusters in Aichi and Osaka prefectures concentrate demand for ceramic-metallic filament combinations serving high-temperature electrical containment applications.
India
BIS certification requirements for protective textiles in steel and foundry operations are opening qualified-supplier windows before domestic capacity matures. The Bureau of Indian Standards enforces industrial safety regulations that drive fastest-expanding demand for specialty yarn variants targeting protective gear applications. Maharashtra and Gujarat industrial corridors concentrate procurement activity as qualified import suppliers establish technical service provisions ahead of domestic manufacturing scale-up.
Silica Yarn Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth, creating a tiered structure where scale-driven players defend volume positions against qualified niche operators. The vendor base segments across three strategic archetypes: integrated fiber producers with captive drawing capabilities, specialized textile converters serving regional qualification requirements, and diversified refractory material houses leveraging cross-product customer relationships. Dominant competitive moves include backward integration into high-purity quartz feedstock sourcing and technology licensing partnerships for sol-gel precursor synthesis.
Within the integrated producer tier, Sanul Co exemplifies the archetype of in-house fiber drawing capabilities anchoring high-temperature application positions. Arrow Technical Textiles and Valmiera Glass occupy positions as specialized textile converters, with the former representing European electrical insulation specialization and the latter exemplifying geographic concentration across Baltic and Nordic construction reinforcement markets. These three named entities illustrate how qualification-documented fiber lots command premium positioning against conventional melt-drawn competitors defending construction and industrial volume segments.
| Leading Market Players |
|---|
| Sanul Co |
| Arrow Technical Textiles |
| Valmiera Glass |
| Nanjing Tianyuan |
| Shanxi Huatek |
| Domin-Tex Insulation Corp |
| Bohemiatex |
| EAS Fiberglass |
| TextileTechnologies Europe Ltd |
| Others |
Pricing and Supply Chain Analysis
Twenty-four to thirty-six month aerospace material qualification cycles compress supplier panels and amplify pricing power for qualified fiber lots, while REACH compliance investments in European drawing facilities transmit cost premiums through the value chain.
Pricing Analysis
Certification level creates the primary spread between aerospace-qualified continuous filament and industrial-grade staple fiber, with FAA-EASA concurrent qualification commanding substantial premiums over GB-standard construction reinforcement. Price differentiation separates lot-traceable sol-gel feedstock from conventional melt-drawn alternatives, while volume scale in China's eastern provinces drives economy-tier positioning. Cost compression in high-strength yarn segments intensifies due to alumina-silica ceramic fiber substitution pressure. Construction reinforcement buyers exhibit highest price sensitivity; aerospace thermal protection integrators demonstrate least sensitivity given single-source qualification risk.
Supply Chain Analysis
Germany and Japan anchor specialized fiber-drawing furnace and bushing technology, while China concentrates mid-range filament capacity and Brazil and Madagascar supply semiconductor-grade quartz feedstock. Raw material dependencies rest on high-purity silicon dioxide, platinum-rhodium bushing alloys, and specialized refractory ceramics. Single-source equipment vulnerability from German and Japanese capital suppliers creates structural bottleneck risk. Distribution runs through long-term supply agreements with embedded volume commitments rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master glass technologists capable of maintaining 99%+ SiO₂ purity across continuous filament production are retiring faster than training pipelines replenish, compressing qualified supplier timelines and amplifying acquisition premiums for technical workforces.
For Market Incumbents: Shield aerospace qualification positions through captive sol-gel precursor synthesis investments before next-generation reentry system specifications finalize. Consolidate backward integration into high-purity quartz feedstock sourcing to mitigate Brazilian and Madagascar supply volatility. Certification depth remains the priority defensive lever against emerging sol-gel specialists. For New Entrants and Emerging Players: BIS certification fast-tracks for Indian protective textile applications open qualified-supplier windows before domestic capacity matures. Electric vehicle battery enclosure specifications under NHTSA thermal runaway standards present the most penetrable white-space target. Partner with established textile converters for technical service provisions rather than building full drawing capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a qualification-moat play because aerospace and automotive thermal protection specifications embed multi-year incumbent advantages. Target mid-cap fiber producers with in-house drawing capabilities and partial certification progress. Watch for FAA-EASA concurrent certification completion as the inflection signal for revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Feedstock | Captive supply of Brazilian and Madagascar semiconductor-grade silicon dioxide mitigates cost volatility. |
| Sol-Gel Precursor Synthesis Investment | Next-generation reentry vehicle specifications from US aerospace primes favor qualified sol-gel suppliers. |
| Long-term Supply Agreement with Volume Commitments | Germany's automotive and aerospace buyers consolidate procurement toward three qualified silica yarn sources. |
| Process Automation in Fiber Drawing | Real-time purity monitoring enables lot-level traceability that thermal protection integrators now mandate. |
| Joint Venture for Indian Protective Textile Certification | BIS requirements in Maharashtra and Gujarat industrial corridors open qualified-supplier windows ahead of domestic scale-up. |
Research Methodology
Operator-level perspectives from fiber drawing technicians, aerospace procurement managers, thermal protection system engineers, and industrial textile converters anchored the qualitative base. Primary interviews combined with secondary validation from ECHA REACH substance databases, FAA certification filings, SAMR GB-standard documentation, and customs trade records for high-purity quartz feedstock. Bottom-up capacity assessments across German, Japanese, and Chinese drawing facilities triangulated against top-down demand modeling from aerospace prime contractor specifications.
Sensitivity analysis tested forecast outputs against varying assumptions for aerospace qualification timeline compression, alumina-silica substitution rates in construction insulation, and sol-gel feedstock adoption curves across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry qualification requirements, form factor specifications, and regional regulatory cluster alignment. CAGRs derived from installed capacity growth rates, replacement demand cycles, and specification-driven procurement consolidation patterns. Industry-specific inputs encompassed semiconductor-grade quartz supply constraints and master technician workforce demographics.
Decision-makers should treat outputs as directional under sustained aerospace thermal protection procurement expansion and REACH-EPA regulatory harmonization; material deviation in sol-gel adoption rates or ceramic fiber substitution thresholds would warrant model refresh. Forecasts reflect assumptions about certification timeline stability and feedstock supply continuity. Recalibration cycles align with material shifts in FAA-EASA concurrent certification requirements and Indian BIS enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Wool Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Sailcloth Market