
 Poly Cotton Fabric Market | 2026-2036
Poly Cotton Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Cotton Fabric Market Analytics
Software-defined inventory management and digital color-matching subscriptions is restructuring how mills monetize poly cotton output beyond the physical roll. Milliken & Company leverages its chemical research heritage to dominate performance-treated poly cotton for institutional uniforms. Parkdale Mills, Inc. sustains massive ring-spun capacity across the southeastern United States, anchoring North American apparel supply chains. Grasim Industries Limited controls upstream viscose-polyester integration, extending cost advantages into blended fabric lines.
Poly cotton fabric combines natural cotton fibers with synthetic polyester in ratios typically ranging from 65/35 to 50/50, engineered through ring spinning or open-end rotor systems to deliver wrinkle resistance, dimensional stability, and moisture management for apparel, bedding, and protective applications. Woven constructions occupy the dominant share of industrial and uniform demand due to structural durability and predictable shrinkage profiles, while knitted formats are capturing share in athleisure and medical textiles where stretch recovery matters. The home textiles segment concentrates margin pools in hospitality and healthcare institutional contracts, where flame-retardant and antimicrobial finishes command specification premiums.
India's BIS mandates fiber content labeling and dimensional stability testing under compulsory registration schemes, while the EPA governs chemical finishing emissions from U.S. textile mills under Clean Air Act permits. REACH restrictions on formaldehyde-based resins in Europe are redirecting formulation R&D toward citric acid crosslinking and silicone-based softening systems. Stakeholders must monitor how digital product passport requirements under emerging EU textile regulations reshape traceability investments and supplier qualification timelines.
Market Dynamics
Digital product passport mandates under emerging EU textile regulations are forcing mills to restructure traceability investments and supplier qualification timelines before physical certification becomes compulsory.
Growth Catalysts
- REACH restrictions on formaldehyde-based resins:European chemical regulations are redirecting formulation R&D toward citric acid crosslinking and silicone-based softening systems, creating first-mover advantages for compliant mills.
- Hospital network procurement expansion:Healthcare workwear standardization across institutional buyers is concentrating poly cotton volume in flame-retardant and antimicrobial specification tiers.
- Bangladesh garment export concentration:Medium-weight blended sheeting demand from Dhaka-based export houses is anchoring regional spinning capacity utilization rates.
Market Restraints
- Raw material cost volatility:Cotton futures fluctuation against polyester staple fiber pricing compresses blended yarn margins unpredictably.
- Upstream supply concentration:Viscose-polyester integration advantages controlled by select South Asian chemical-textile conglomerates limit independent mill bargaining power.
- Technical performance ceiling:Breathability-wrinkle resistance trade-offs in 65/35 constructions prevent penetration of high-performance athletic applications dominated by pure synthetics.
Strategic Opportunities
- Software-defined inventory monetization:Digital color-matching subscriptions and predictive dye lot management are unifying mill revenue streams beyond physical roll sales.
- Antimicrobial finish specification premiums:Healthcare and hospitality institutional contracts are creating margin pools for performance-treated poly cotton that commodity suppliers cannot access.
- India BIS fiber content disclosure mandates:Compulsory registration schemes for dimensional stability testing are advantaging certified domestic producers against informal competitors.
Industry Challenges
- Legacy ERP integration with traceability platforms:Mill-level software migration to comply with digital product passport requirements demands capital deployment and technical staffing that mid-tier producers struggle to resource.
- Colorfastness certification timeline compression:Accelerated buyer qualification cycles for institutional contracts are shortening acceptable testing windows without reducing protocol rigor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Cotton Fabric Market |
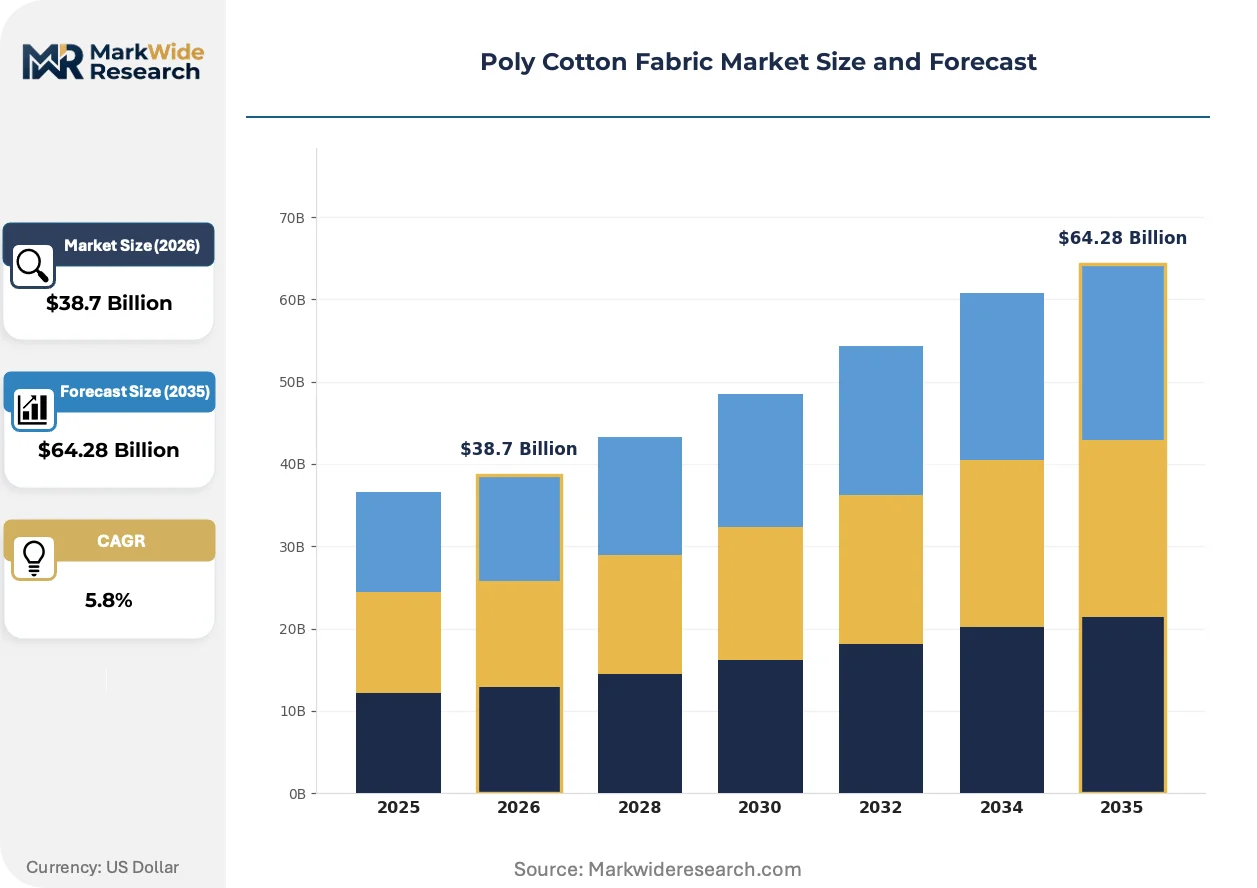
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Woven, Knitted, Non-woven, Blended End Use: Apparel, Home Textiles, Industrial, Automotive Weight: Lightweight, Medium, Heavyweight, Ultra-light Distribution Channel: Online Retail, Specialty Stores, Wholesale, Distributors |
| Companies Covered | Milliken & Company, Parkdale Mills, Inc., Toray Industries, Inc., Reliance Industries Limited, Klopman International, Grasim Industries Limited, Arvind Limited, Welspun India Ltd., Vardhman Textiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Cotton Fabric Market Evolving Landscape
Three intersecting forces are restructuring how poly cotton moves from fiber to finished good: chemical formulation evolution, regulatory disclosure mandates, and procurement digitization.
Citric acid crosslinking chemistry is unifying wrinkle resistance and formaldehyde-free positioning in a single finish package. Hospitality procurement teams at major hotel chains are specifying these systems for uniform and bedding contracts previously held by resin-treated alternatives. This convergence is compressing the competitive window for mills still dependent on legacy formaldehyde-based curing.
EU textile regulations advancing digital product passport requirements are mandating fiber origin disclosure and chemical finishing documentation across the value chain. Mills serving European buyers must now maintain blockchain-traceable batch records from cotton gin to dyehouse. Home textile suppliers with hospitality contracts in Germany and France are investing earliest, recognizing that passport compliance will become a qualification gate rather than a differentiator.
Subscription-based color-matching platforms are displacing traditional physical lab dip approval cycles between brands and mills. Athleisure and medical textile buyers are adopting cloud-based spectral matching to compress development timelines from weeks to days. This shift is most visible among Bangladesh-based garment exporters serving North American retail brands, where first-sample approval speed determines contract allocation.
Poly Cotton Fabric Market Segmentation
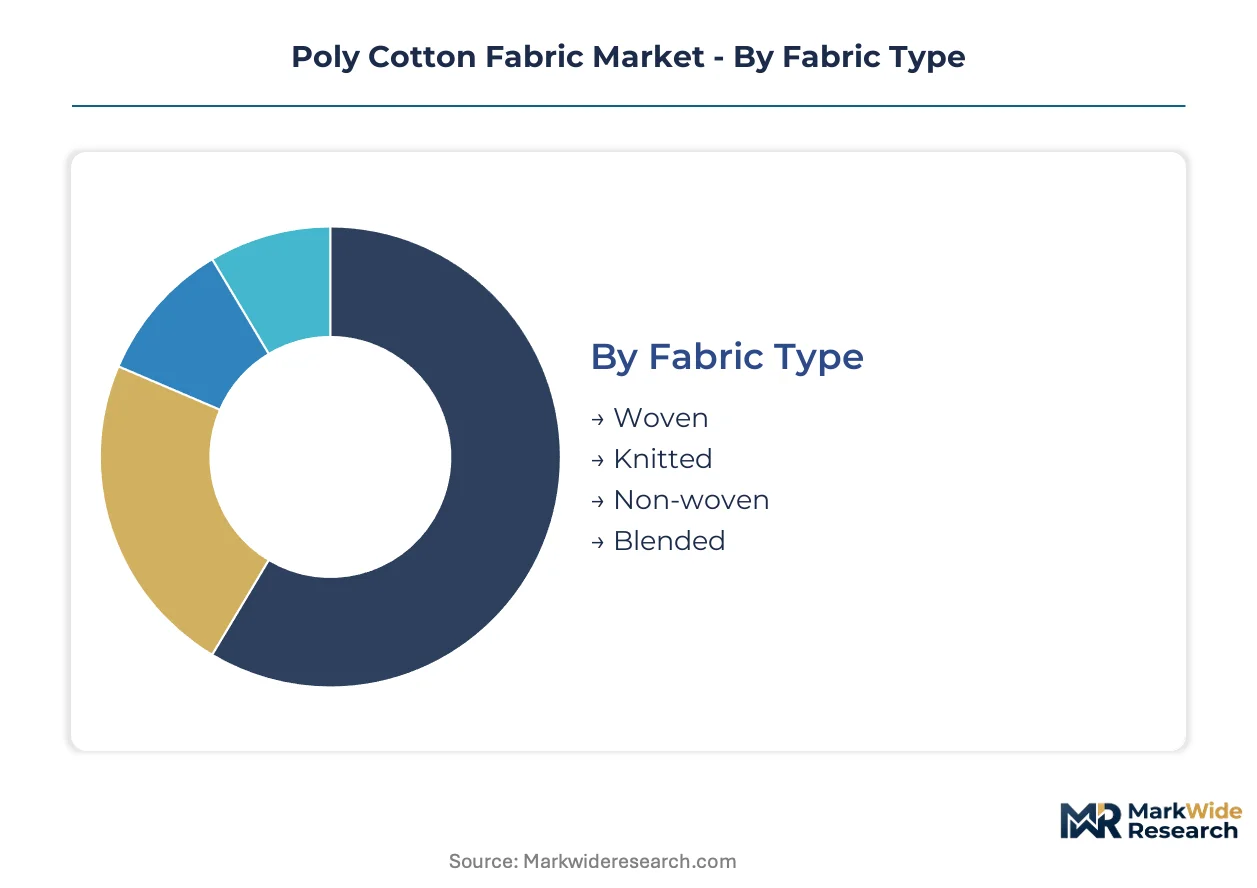
Poly cotton fabric segmentation reveals how technical specifications and channel economics create distinct margin pools. Upgrade cycles in institutional procurement and shifting retail formats are redistributing volume across categories.
Fabric Type:
Replacement cycles vary sharply by construction method, with woven formats demanding longer capital commitments from buyers while knitted alternatives enable faster seasonal turnover.
- Woven:Ring-spun and open-end rotor constructions deliver structural durability and predictable shrinkage profiles. Hospital networks in Germany and France specify woven poly cotton for flame-retardant institutional uniforms, locking in multi-year procurement contracts with certified mills.
- Knitted:Jersey and interlock constructions provide stretch recovery essential for athleisure and medical textiles. Dhaka-based garment exporters serving North American retail brands concentrate knitting capacity for rapid sample-to-production cycles.
- Non-woven:Spunbond and needlepunch formats serve disposable protective applications with limited reusability requirements.
- Blended:Viscose-polyester and specialty fiber combinations extend performance characteristics for technical end-uses.
Volume placements concentrate in Woven; the faster expansion belongs to Knitted.
End Use:
Customer type determines specification rigor, with institutional buyers imposing certification burdens that commodity suppliers cannot satisfy.
- Apparel:Corporate uniforms and workwear represent the core volume driver, with 65/35 constructions dominating wrinkle-resistant shirt programs. REACH-compliant finishing mandates from European retail chains are redirecting formulation sourcing toward citric acid crosslinking suppliers.
- Home Textiles:Bedding and sheeting contracts concentrate in hospitality procurement teams at major hotel chains. Flame-retardant and antimicrobial specification tiers command premiums that commodity mills forfeit.
- Industrial:Protective applications require durability testing under OSHA guidelines for U.S. manufacturing facilities.
- Automotive:Seat covering and interior panel applications demand heat resistance certification under OEM qualification protocols.
Institutional contract value pools in Home Textiles outpace Apparel volume; Automotive specifications are climbing the fastest as electric vehicle production expands interior customization programs.
Weight:
Cost tier stratification aligns with end-use durability requirements, with heavier constructions supporting longer replacement intervals.
- Medium:150-200 gsm constructions anchor Bangladesh's garment export sector for blended sheeting, balancing drape and durability for uniform and casual apparel programs. Dhaka-based export houses concentrate spinning capacity utilization around this specification band.
- Heavyweight:200+ gsm fabrics serve industrial protective applications and premium hospitality bedding where longevity justifies unit cost premiums.
- Lightweight:100-150 gsm formats enable seasonal fashion turnover with reduced material input costs.
- Ultra-light:Sub-100 gsm constructions target disposable medical textiles and limited-use protective covers.
Medium weight captures the dominant procurement volume; Heavyweight specifications are expanding most quickly as institutional buyers extend replacement cycles.
Distribution Channel:
Supply concentration in spinning clusters shapes channel economics, with proximity to mill capacity determining fulfillment speed and minimum order thresholds.
- Wholesale:Volume transactions from southeastern U.S. ring-spun capacity anchor North American apparel supply chains, with Parkdale Mills sustaining massive production scale for direct mill-to-cut-factory relationships.
- Distributors:Regional inventory positioning enables just-in-time fulfillment for mid-tier garment manufacturers without captive spinning supply.
- Specialty Stores:Curated selections for premium uniform and workwear segments serve smaller buyers lacking direct mill access.
- Online Retail:Digital color-matching platforms and subscription-based spectral services compress development timelines for athleisure and medical textile buyers.
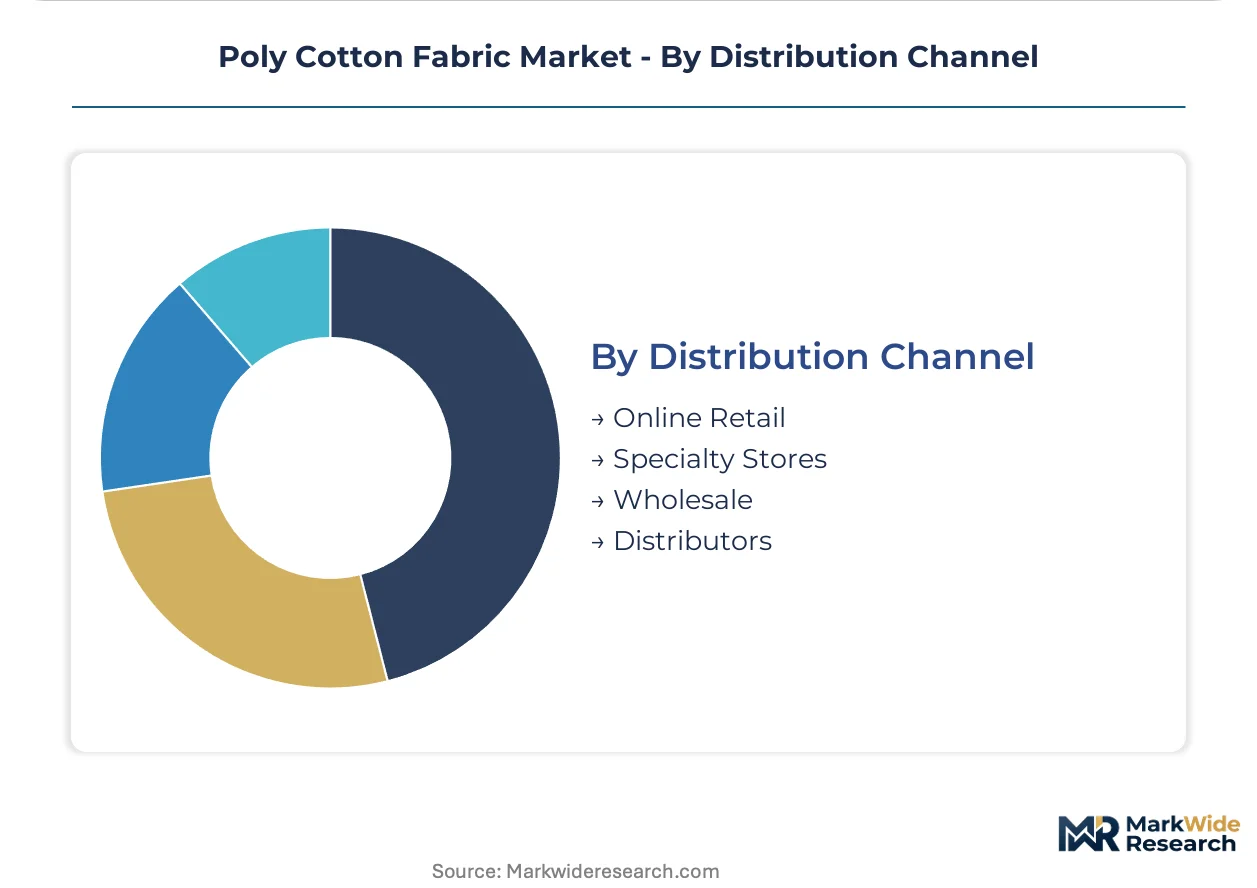
Wholesale volume dominates established supply relationships; Online Retail is gaining share fastest as cloud-based procurement tools displace physical lab dip approvals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dhaka's garment export corridor concentrates medium-weight poly cotton sheeting demand, anchoring spinning capacity utilization across South Asia while European institutional buyers drive specification premiums for flame-retardant and antimicrobial finishes.
United States
Hospital network procurement standardization and corporate uniform programs sustain poly cotton volume in institutional channels. EPA Clean Air Act permits govern chemical finishing emissions from southeastern textile mills. Parkdale Mills anchors ring-spun capacity across the Carolinas and Georgia, sustaining direct mill-to-cut-factory supply relationships for North American apparel chains.
Germany
Hospitality procurement teams at major hotel chains specify citric acid crosslinked fabrics for uniform and bedding contracts. REACH restrictions on formaldehyde-based resins redirect formulation sourcing toward silicone-based softening systems. The North Rhine-Westphalia industrial corridor hosts technical textile finishers investing earliest in digital product passport compliance infrastructure.
India
Domestic apparel consumption and export-oriented garment manufacturing expand poly cotton absorption across price-sensitive segments. BIS mandates fiber content labeling and dimensional stability testing under compulsory registration schemes. The Tiruppur knitwear cluster and Surat weaving belt concentrate spinning and finishing capacity for blended sheeting exports to Bangladesh and European buyers.
Bangladesh
Dhaka-based export houses serving North American retail brands concentrate demand for medium-weight blended sheeting in 150-200 gsm specifications. The country's garment export sector operates under EU GSP trade preferences that incentivize compliance with REACH-aligned chemical standards. Chittagong port logistics and Narayanganj spinning mills form a tight production corridor minimizing fiber-to-fabric lead times.
China
Yarn and fabric export competitiveness persists despite shifting labor costs, with Zhejiang and Jiangsu provinces maintaining integrated polyester-cotton spinning complexes. MIIT industrial standards govern textile quality certification for domestic and export markets. The Shaoxing textile market functions as a global pricing reference point for blended yarn quotations and spot fabric transactions.
Poly Cotton Fabric Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor base where integrated chemical-textile conglomerates hold upstream cost advantages. The market structure concentrates around three strategic archetypes: performance finish specialists commanding institutional specification premiums, massive ring-spun operators anchoring volume supply chains, and upstream fiber integrators extending cost advantages into blended fabric lines. Competitive moves center on digital color-matching platform deployment and predictive inventory monetization rather than physical capacity expansion alone.
Among North American ring-spun specialists, Parkdale Mills exemplifies scale-driven supply chain anchoring, while Milliken & Company occupies the performance-treated institutional uniform tier. Grasim Industries Limited represents upstream viscose-polyester integration extending into downstream blended fabric lines. These three entities illustrate how geographic clustering and vertical control create defendable positions against commodity competitors lacking captive fiber supply or chemical research heritage.
| Leading Market Players |
|---|
| Milliken & Company |
| Parkdale Mills, Inc. |
| Toray Industries, Inc. |
| Reliance Industries Limited |
| Klopman International |
| Grasim Industries Limited |
| Arvind Limited |
| Welspun India Ltd. |
| Vardhman Textiles |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between REACH-compliant performance finishes and commodity resin-treated alternatives manifests in both pricing power concentration and supplier qualification timelines. Mills with blockchain-traceable batch records command specification premiums from European hospitality procurement teams, while informal competitors face margin compression from accelerated buyer qualification cycles.
Pricing Analysis
Margin tightening in institutional contract tiers reflects REACH-mandated formulation shifts away from formaldehyde-based resins. Three-tier pricing structure across premium, standard, and economy levels separates citric acid crosslinked performance fabrics from legacy resin-treated alternatives and undifferentiated commodity sheeting. Cost-down pressure on medium-weight blended sheeting accelerates because Dhaka-based export houses prioritize first-sample approval speed over unit price negotiation. Hospital network procurement teams exhibit lowest price sensitivity due to multi-year specification lock-ins, while seasonal fashion buyers drive hardest bargain on lightweight constructions.
Supply Chain Analysis
Digital product passport compliance is gating supplier qualification for European institutional contracts, forcing mills to maintain traceable records from cotton gin to dyehouse. Geographic supply concentration centers on India, Bangladesh, and China, with Tiruppur knitwear clusters, Dhaka garment export corridors, and Zhejiang spinning complexes anchoring regional capacity. Raw material dependencies rest on polyester staple fiber pricing, cotton futures volatility, and viscose pulp supply controlled by South Asian chemical-textile conglomerates. Single-source vulnerability in upstream viscose-polyester integration limits independent mill bargaining power. Distribution runs through wholesale mill-to-cut-factory relationships anchored by southeastern U.S. ring-spun capacity and direct procurement from Dhaka-based export houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards consolidation plays as REACH compliance costs and digital passport infrastructure investments force sub-scale mills into acquisition targets or exit.
For Market Incumbents: Anchor institutional specification tiers by accelerating citric acid crosslinking R&D and deploying predictive dye lot management platforms. Defend against software-defined inventory monetization disruptors by integrating subscription-based color-matching services into existing mill-to-cut-factory relationships. Prioritize BIS certification maintenance in India to exploit compulsory registration schemes disadvantaging informal competitors. For New Entrants and Emerging Players: Enter via antimicrobial finish specification gaps in North American healthcare workwear procurement, where hospital network standardization creates volume concentration without entrenched supplier relationships. Target medium-weight blended sheeting for Bangladesh garment exporters seeking alternative spinning sources to Narayanganj capacity constraints. Lead with cloud-based spectral matching capabilities to compress development timelines against legacy physical lab dip cycles. For Investors and Strategic Acquirers: Re-rating potential sits with performance finish specialists given EU textile regulation enforcement timelines accelerating digital product passport compliance requirements. Long-term viability favors mills with captive chemical research heritage and blockchain-traceable supply chain infrastructure. Watch for inflection in institutional contract qualification rejection rates as informal competitors fail REACH-aligned chemical standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Viscose-Polyester Fiber Supply | Grasim Industries extends cost advantages into blended fabric lines through captive pulp-to-yarn control. |
| Digital Color-Matching Platform Deployment | Parkdale Mills compresses development timelines for North American retail brands via cloud-based spectral approval. |
| REACH-Compliant Finish Formulation Investment | Milliken & Company captures specification premiums from European hospitality procurement teams mandating formaldehyde-free alternatives. |
| Blockchain Traceability Infrastructure Buildout | Home textile suppliers serving Germany and France secure qualification gates before digital passport mandates become compulsory. |
| Antimicrobial Treatment Certification Program | Performance-treated poly cotton suppliers access margin pools in healthcare institutional contracts inaccessible to commodity mills. |
Research Methodology
Trade databases, BIS registration filings, and ECHA REACH substance restrictions formed the secondary backbone for this analysis. Primary interviews with spinning mill operations directors, hospitality procurement managers at major hotel chains, Dhaka-based garment export house merchandisers, and chemical finishing R&D leads validated demand assumptions and pricing dynamics. Bottom-up volume estimates from individual mill capacity utilization rates triangulated against top-down absorption projections from end-use sector procurement trends.
Historical trendline analysis of fiber price ratios, institutional contract award patterns, and regulatory enforcement timelines informed the projection framework. Segmentation modeling incorporated fabric construction type, end-use application, weight specification band, and distribution channel complexity across the projection horizon. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity expansion schedules, with specific inputs from cotton futures volatility patterns and polyester staple fiber pricing corridors.
Revisions become necessary when EU digital product passport implementation timelines accelerate or when Bangladesh GSP trade preference terms shift materially. Forecasts reflect assumptions about REACH enforcement consistency and hospital network procurement standardization continuity. A model refresh is warranted upon material change in India BIS dimensional stability testing mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market